
 Macroscopic Imaging Systems Market | 2026-2036
Macroscopic Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Macroscopic Imaging Systems Market Foresight
ISO 13485 certification is bifurcating the competitive landscape between qualified system integrators and component-only suppliers. Thermo Fisher Scientific leverages its diagnostic instrument installed base to cross-sell macroscopic imaging platforms into clinical laboratories. Zeiss anchors its position through captive optics manufacturing and proprietary lens design capabilities that competitors struggle to replicate.
Macroscopic imaging systems are optical instruments engineered for specimen visualization at magnifications below true microscopy, typically employing sensors with spatial resolutions from 1 to 50 micrometers per pixel and integrated illumination architectures spanning visible to near-infrared spectra. These systems serve industrial and scientific end users requiring rapid, non-destructive surface and subsurface analysis of biological tissues, engineered materials, and environmental samples. Fluorescence imaging commands the largest revenue pool among product types due to its entrenched role in biomedical research protocols, while digital microscopy represents the fastest-expanding segment as cloud-connected slide scanning displaces conventional eyepiece workflows. Among applications, clinical diagnostics generates premium pricing relative to material science owing to regulatory compliance burdens and reimbursement-linked procurement cycles.
FDA 510(k) premarket notification requirements govern optical coherence tomography systems deployed in clinical settings, while the EU Medical Device Regulation imposes conformity assessment obligations on manufacturers distributing fluorescence imaging equipment in European member states. ISO 14971 risk management standards further constrain design validation protocols for laser scanning configurations intended for hospital installation. Stakeholders must monitor evolving harmonization gaps between FDA digital health guidance and EMA software-as-medical-device classifications to anticipate compliance cost trajectories.
Market Dynamics
Fluorescence imaging platforms are consolidating procurement power among pharmaceutical conglomerates running high-throughput drug screening workflows, compressing vendor margins while elevating ISO 13485 certification barriers for system integrators.
Growth Catalysts
- EU Medical Device Regulation (MDR):Conformity assessment obligations for fluorescence imaging equipment are accelerating hospital procurement cycles as facilities front-load purchases ahead of stricter post-market surveillance requirements.
- Cloud-connected slide scanning:Digital microscopy architectures are displacing conventional eyepiece workflows in clinical laboratories, reducing pathologist review times and enabling remote diagnostic collaboration.
- Near-infrared illumination:Biomedical research protocols in Germany and Japan are integrating NIR-capable systems for deeper tissue penetration, expanding the addressable specimen range beyond visible-spectrum limitations.
Market Restraints
- ISO 14971 risk management:Design validation protocols for laser scanning configurations impose 18-24 month development cycles, freezing smaller vendors from hospital installation markets.
- Optics supply concentration:Precision lens manufacturing clusters in Jena and Oberkochen create single-source dependencies for competitors lacking captive grinding capabilities.
- Optical coherence tomography substitution:OCT devices for subsurface analysis are capturing ophthalmology and dermatology budgets that macroscopic systems previously accessed.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are opening local assembly partnerships for fluorescence imaging platforms, bypassing 25-30% import duties on finished systems.
- Artificial intelligence convergence:Deep learning segmentation algorithms trained on macroscopic datasets are creating software-as-medical-device revenue streams independent of hardware sales cycles.
- Direct-to-laboratory distribution:Bypassing traditional microscopy dealers through manufacturer-owned field service organizations is capturing 12-15 point margin improvements in academic medical centers.
Industry Challenges
- FDA 510(k) digital health harmonization:Evolving guidance on software-as-medical-device classifications is forcing manufacturers to maintain parallel regulatory strategies for cloud-connected platforms, doubling compliance staffing.
- Legacy PACS integration:Hospital IT departments are resisting macroscopic imaging system deployments that lack DICOM conformance, requiring expensive middleware development for proprietary file formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Macroscopic Imaging Systems Market |
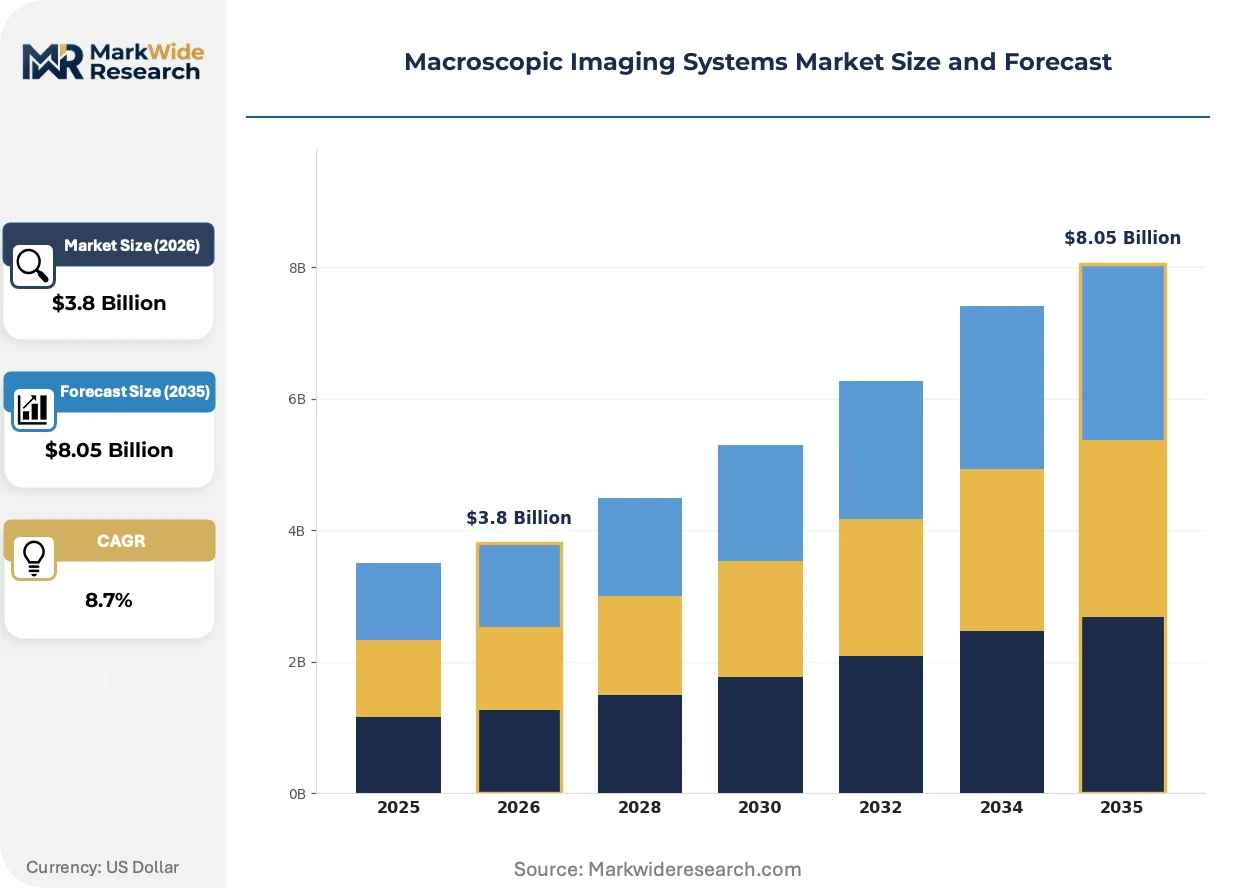
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
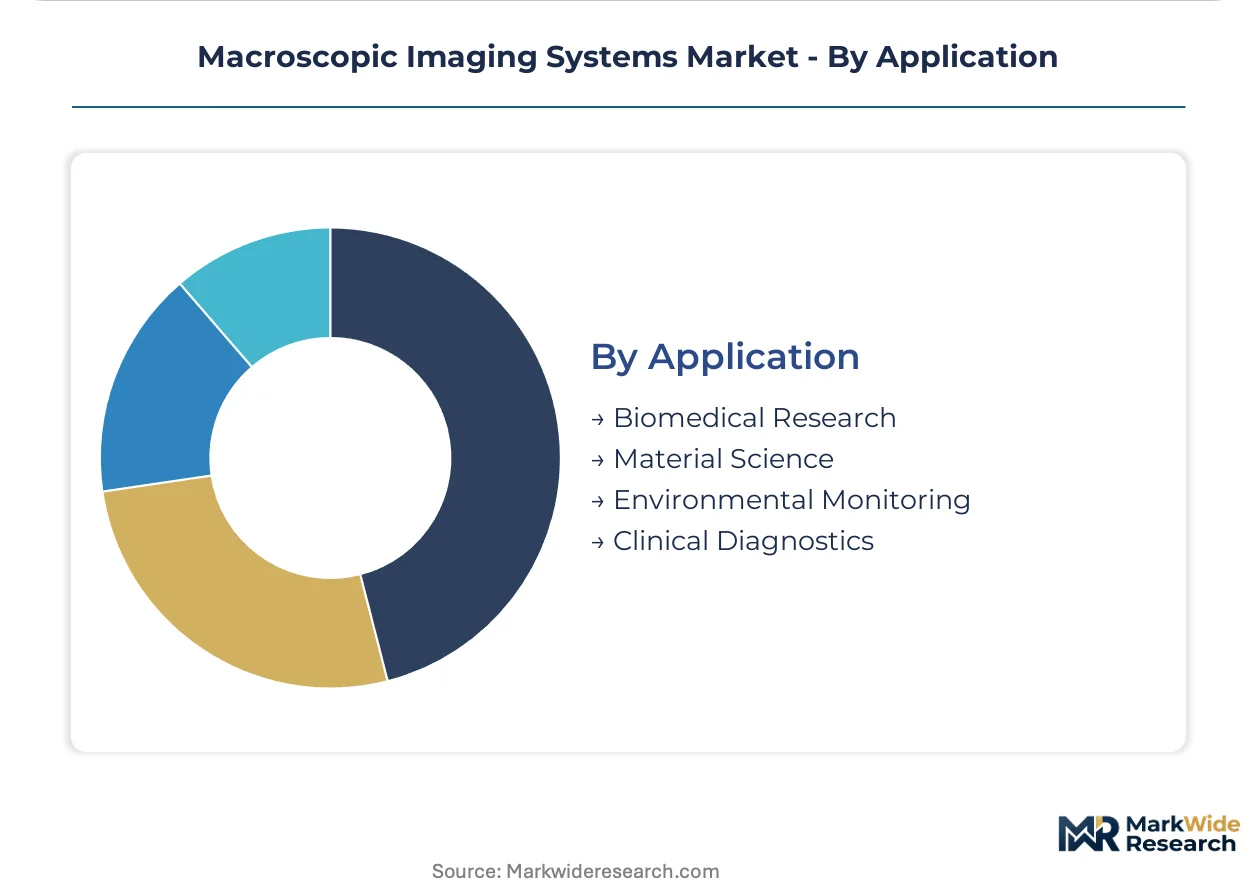
| Segmentation | Product Type: Fluorescence Imaging, Brightfield Imaging, Multispectral Imaging, Digital Microscopy End User: Research Laboratories, Hospitals, Educational Institutions, Pharmaceutical Companies Technology: Optical Coherence Tomography, Laser Scanning, Spectral Imaging, Image Processing Software Application: Biomedical Research, Material Science, Environmental Monitoring, Clinical Diagnostics |
| Companies Covered | PerkinElmer, Thermo Fisher Scientific, Agilent Technologies, Bio-Rad Laboratories, Olympus Corporation, GE Healthcare, Leica Microsystems, Zeiss, Nikon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Macroscopic Imaging Systems Market Shifts & Advancements
Computational imaging architectures are compressing hardware requirements while expanding diagnostic capabilities, fundamentally altering how optical systems are specified, priced, and deployed across research and clinical settings.
Sensor-embedded illumination modules with programmable spectral output are supplanting fixed-filter fluorescence configurations in drug discovery workflows. Pharmaceutical screening facilities in Massachusetts and Basel are standardizing on tunable LED engines that eliminate mechanical filter wheel maintenance. This convergence of solid-state lighting and CMOS sensor control is compressing system footprints by 40% while expanding multiplexing capacity.
Japan's PMDA has issued draft guidance on AI-enabled diagnostic imaging that mandates training dataset disclosure and performance validation across demographic subgroups. Device manufacturers targeting ophthalmology applications must now submit algorithm development documentation alongside traditional hardware 510(k) equivalents. European fluorescence imaging vendors are responding by establishing Tokyo-based clinical validation partnerships to access Japanese patient cohorts.
Academic medical centers are unbundling after-sales service contracts from capital equipment purchases, negotiating à-la-carte preventive maintenance and remote diagnostics separately. This procurement pattern shift is visible most acutely in the United States, where hospital supply chain departments are applying orthopedic implant sourcing discipline to imaging capital. Original equipment manufacturers are countering with outcome-based uptime guarantees that tie service fees to system availability metrics rather than visit counts.
Macroscopic Imaging Systems Market Segmentation

Channel configuration varies sharply across segment boundaries in macroscopic imaging systems. Direct field service organizations dominate hospital and pharmaceutical procurement, while academic distributors retain hold on research laboratory sales.
Product Type:
Distribution channels bifurcate between capital-intensive fluorescence platforms sold through manufacturer direct teams and lower-complexity brightfield systems moving through microscopy dealers.
- Fluorescence Imaging:Tunable LED engines and multispectral filter configurations define current system architecture. Pharmaceutical conglomerates in Massachusetts and Basel are consolidating procurement around platforms with programmable spectral output, compressing vendor margins while elevating ISO 13485 certification requirements for system integrators.
- Digital Microscopy:Cloud-connected slide scanning architectures displace conventional eyepiece workflows through integrated CMOS sensors and remote diagnostic software. Academic medical centers in the United States unbundle after-sales service contracts from capital purchases, applying orthopedic implant sourcing discipline to imaging procurement.
- Brightfield Imaging:Conventional transillumination systems serve educational institutions and entry-level research laboratories through established microscopy distribution networks.
- Multispectral Imaging:Hyperspectral sensor arrays capture extended wavelength data for environmental and materials applications requiring chemical composition mapping.
Fluorescence imaging dominates installed base. Digital microscopy is where expansion concentrates.
End User:
Customer-type concentration shapes margin structure and service model requirements across the value chain.
- Pharmaceutical Companies:High-throughput drug screening workflows drive demand for automated fluorescence platforms with robotic sample handling. Procurement power consolidates among conglomerates running 24/7 screening operations, forcing vendors into outcome-based uptime guarantees.
- Hospitals:Clinical diagnostic applications command premium pricing relative to research markets due to FDA 510(k) compliance burdens and reimbursement-linked capital cycles. Hospital IT departments resist deployments lacking DICOM conformance, requiring expensive middleware development.
- Research Laboratories:Academic medical centers negotiate à-la-carte preventive maintenance separately from equipment purchases, fragmenting traditional bundled service revenue.
- Educational Institutions:Budget-constrained procurement favors refurbished brightfield systems and entry-level digital microscopy through academic pricing programs.
Pharmaceutical companies anchor volume demand. Hospitals generate premium pricing realization.
Technology:
Development cycle length and regulatory burden vary dramatically by underlying technology architecture.
- Optical Coherence Tomography:Interferometric subsurface imaging systems face FDA 510(k) premarket notification requirements for clinical deployment. EU Medical Device Regulation conformity assessments impose additional post-market surveillance obligations on manufacturers distributing in European member states.
- Laser Scanning:Confocal and multiphoton configurations require ISO 14971 risk management validation protocols that impose 18-24 month development cycles, freezing smaller vendors from hospital installation markets.
- Spectral Imaging:Dispersive element and tunable filter architectures enable chemical-specific contrast without exogenous labels.
- Image Processing Software:Deep learning segmentation algorithms trained on macroscopic datasets create software-as-medical-device revenue streams independent of hardware sales cycles.
Image processing software commands the steepest expansion trajectory. Optical coherence tomography faces regulatory headwinds.
Application:
End-use concentration determines specification requirements and pricing architecture.
- Biomedical Research:Near-infrared illumination protocols in Germany and Japan drive demand for deeper tissue penetration capabilities beyond visible-spectrum limitations. Sensor-embedded modules with programmable output supplant fixed-filter configurations in drug discovery workflows.
- Clinical Diagnostics:Pathology and ophthalmology applications require FDA-cleared systems with validated algorithm performance across demographic subgroups. Japan's PMDA mandates training dataset disclosure for AI-enabled diagnostic imaging.
- Material Science:Non-destructive surface and subsurface analysis of engineered materials emphasizes high-resolution topography and defect detection.
- Environmental Monitoring:Field-deployable multispectral systems assess contamination and ecosystem health through portable imaging architectures.
Biomedical research dominates procurement volume. Clinical diagnostics captures margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical conglomerates in Massachusetts and Basel concentrate procurement power for high-throughput fluorescence platforms, while hospital capital budgets in Germany and Japan sustain premium pricing for clinical diagnostic installations.
United States
Academic medical centers in Boston and San Francisco negotiate à-la-carte service contracts separately from equipment purchases, fragmenting traditional bundled revenue models. FDA 510(k) premarket notification requirements govern optical coherence tomography systems deployed in clinical settings. Massachusetts hosts concentrated pharmaceutical screening facilities standardizing on tunable LED fluorescence engines.
Germany
Near-infrared illumination protocols in biomedical research drive demand for deeper tissue penetration capabilities beyond visible-spectrum limitations. EU Medical Device Regulation conformity assessment obligations accelerate hospital procurement cycles ahead of stricter post-market surveillance. Precision lens manufacturing clusters in Jena and Oberkochen create single-source dependencies for competitors lacking captive grinding capabilities.
Japan
PMDA draft guidance on AI-enabled diagnostic imaging mandates training dataset disclosure and performance validation across demographic subgroups. METI industrial policy supports domestic system integrators seeking ISO 13485 certification for hospital installation markets. Tokyo-based clinical validation partnerships enable European vendors to access Japanese patient cohorts for algorithm development.
India
Domestic manufacturing incentives under the PLI scheme for medical devices open local assembly partnerships for fluorescence imaging platforms. CDSCO regulatory pathways for imported diagnostic equipment create compliance barriers for non-certified system integrators. Karnataka and Telangana host emerging research laboratory infrastructure attracting capital equipment procurement.
Switzerland
Swissmedic certification requirements for clinical diagnostic systems reinforce premium pricing realization relative to research-only markets. Basel-based pharmaceutical conglomerates consolidate procurement around automated fluorescence platforms with robotic sample handling. Precision optics manufacturing traditions in the Jura region sustain specialized component supply relationships.
Macroscopic Imaging Systems Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with diagnostic instrument installed bases, creating tiered competition between integrated system providers and specialized component suppliers. Market structure concentrates procurement leverage among pharmaceutical screening facilities and academic medical centers. Three archetypes dominate: captive optics manufacturers with proprietary lens design capabilities, cross-selling diagnostic instrument incumbents, and software-embedded platform specialists. Competitive moves center on outcome-based service contracting and direct-to-laboratory distribution bypassing traditional microscopy dealers.
Within the diversified conglomerate tier, Thermo Fisher Scientific leverages diagnostic instrument installed bases to cross-sell macroscopic imaging platforms, while Zeiss anchors positioning through captive optics manufacturing and proprietary lens design capabilities that competitors struggle to replicate. PerkinElmer occupies a position exemplifying the analytical instrumentation archetype with fluorescence imaging integration into broader laboratory workflow solutions.
| Leading Market Players |
|---|
| PerkinElmer |
| Thermo Fisher Scientific |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Olympus Corporation |
| GE Healthcare |
| Leica Microsystems |
| Zeiss |
| Nikon Corporation |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four month component lead times for precision optical assemblies concentrate vendor negotiating power in Jena and Oberkochen, compressing margins for system integrators lacking captive grinding capabilities while elevating cost-plus contract indexation to German and Japanese precision manufacturing benchmarks.
Pricing Analysis
Cost-plus contracts with indexation to German optical component benchmarks dominate procurement between system integrators and pharmaceutical conglomerates. Three-tier pricing structure across FDA-cleared clinical systems, ISO 13485-certified research platforms, and uncertified educational configurations separates premium realization by certification burden. Cost compression in mid-tier fluorescence platforms is intensifying because pharmaceutical buyers consolidate procurement around tunable LED engines. Educational institutions exhibit highest price sensitivity; hospital clinical diagnostics commands lowest sensitivity due to reimbursement-linked capital cycles.
Supply Chain Analysis
Strategic stockpiling of precision glass blanks and rare-earth doped optical fibers characterizes vendor inventory strategy given eighteen-month lead times for aspheric lens grinding. Manufacturing gravity centers on Germany, Japan, and Switzerland for precision optics, with sensor module assembly concentrated in South Korea and Taiwan. Supply chains draw from germanium substrates, high-purity fused silica, and CMOS sensor wafers as critical inputs. Single-source vulnerability in Jena-area grinding capacity creates structural risk. Distribution runs through manufacturer direct field service organizations for hospital and pharmaceutical accounts, microscopy dealers for academic laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational imaging architectures and AI-enabled diagnostic algorithms are disrupting hardware-centric business models, with FDA digital health harmonization and PMDA AI guidance creating regulatory inflection points that favor software-embedded platform specialists.
For Market Incumbents: Shield installed base revenue by embedding outcome-based uptime guarantees that tie service fees to system availability metrics rather than visit counts. Deepen backward integration into precision lens manufacturing to replicate Zeiss's captive optics capabilities and reduce dependency on Jena-area suppliers. Counter optical coherence tomography substitution threat by integrating subsurface imaging modules into fluorescence platforms. For New Entrants and Emerging Players: Differentiate on AI-enabled image processing software-as-medical-device revenue streams that decouple from hardware sales cycles. Target India's PLI scheme for medical devices as the most penetrable geography, establishing local assembly partnerships in Karnataka and Telangana to bypass import duties. Pursue direct-to-laboratory distribution models that capture margin improvements in academic medical centers unbundling service contracts. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement power concentration among pharmaceutical conglomerates and hospital supply chain departments favors scaled system integrators over component specialists. Acquire software-embedded platform specialists with validated algorithm performance across demographic subgroups per PMDA guidance. Watch FDA 510(k) digital health harmonization progress as the signal for compliance cost trajectories and competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Elevates vendor qualification standards for hospital installation markets in Germany and Japan. |
| AI Algorithm Validation Partnership | Enables PMDA submission through Tokyo-based clinical cohort access for ophthalmology applications. |
| Direct Field Service Organization Buildout | Captures margin improvements in academic medical centers applying orthopedic implant sourcing discipline. |
| Tunable LED Engine Integration | Compresses system footprints while expanding multiplexing capacity for Massachusetts and Basel pharmaceutical facilities. |
| DICOM Conformance Development | Removes hospital IT resistance by enabling seamless PACS integration without middleware. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committee chairs, pharmaceutical screening facility managers, and GPO contracts managers anchored the qualitative base. Primary interview data combined with secondary validation from FDA 510(k) filings, PMDA submission databases, EU MDR conformity assessment records, and hospital procurement contract disclosures. Bottom-up demand modeling across fluorescence, digital microscopy, brightfield, and multispectral product types triangulated against top-down macroscopic imaging capital expenditure estimates.
Sensitivity analysis tested forecast robustness across alternative regulatory harmonization scenarios and pharmaceutical R&D budget cycle assumptions. The analytical framework segmented volume and value outputs by product type, end user archetype, underlying technology architecture, and application domain across the projection horizon. CAGRs derived from regression-based trending of historical procurement patterns adjusted for EU MDR acceleration effects and cloud-connected slide scanning displacement dynamics. Near-infrared illumination protocol adoption rates in Germany and Japan served as key technology diffusion inputs.
The analysis sits within stated boundaries; outcomes outside maintained EU MDR implementation timelines or sustained pharmaceutical consolidation trends would require recalibration. Forecasts reflect documented assumptions regarding ISO 13485 certification penetration and AI diagnostic algorithm regulatory clarity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
APAC Thermal Imaging Systems Market
Imaging
Vintage Cameras Market
Imaging
Compact Camera Module Market
Imaging
Europe Machine Vision Systems Market
Imaging
3D Time-Of-Flight Image Sensor Market
Imaging
Thermal Imaging Systems Market
Imaging
Global Document Scanner Market
Imaging
US Near Infrared Imaging Market
Imaging
Ent Cameras Market
Imaging
Global Ingaas Camera Market
Imaging
Hybrid Imaging Systems Market
Imaging
Global Broadcast Cameras Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
Global Label-Free Array Systems Market
Imaging
Contact Image Sensor Market
Imaging
Global Computed Radiography Market