
 Anomaloscope Market | 2026-2036
Anomaloscope Market Size, Share, and Industry Trends Forecast 2026-2036
Anomaloscope Market Outlook
Clinical-grade diagnostic precision is redrawing competitive boundaries in the anomaloscope landscape. Zeiss Group leverages its optical engineering heritage to sustain premium positioning in hospital vision laboratories. Heine Optotechnik GmbH & Co. KG anchors its presence through specialized handheld instrument design for occupational health screening. Hoya Corporation differentiates via integrated lens-technology synergies that extend its reach across Asian clinical networks.
An anomaloscope is a specialized optical instrument that quantifies color vision deficiency by requiring the subject to match mixed light wavelengths against a reference standard, typically using Rayleigh or Moreland equations with nanometer-scale precision in its LED or filtered light sources. The device serves ophthalmologists, occupational health programs, and research institutions requiring objective, reproducible color discrimination metrics. Digital anomaloscope systems now lead product-type expansion as software-driven calibration and customizable settings displace legacy manual units. Automated anomaloscope configurations capture the fastest growth trajectory within the technology dimension, propelled by workflow efficiency demands in high-volume clinical laboratories.
FDA 510(k) pathways and CE marking under the EU MDR govern anomaloscope commercialization, with both frameworks intensifying electromagnetic compatibility and clinical performance documentation requirements. ISO 10993 biocompatibility standards and IEC 60601-1 electrical safety protocols further constrain design choices for manufacturers targeting regulated markets. Stakeholders must monitor evolving software-validation expectations as regulatory bodies scrutinize algorithm-driven color-matching interpretations.
Market Dynamics
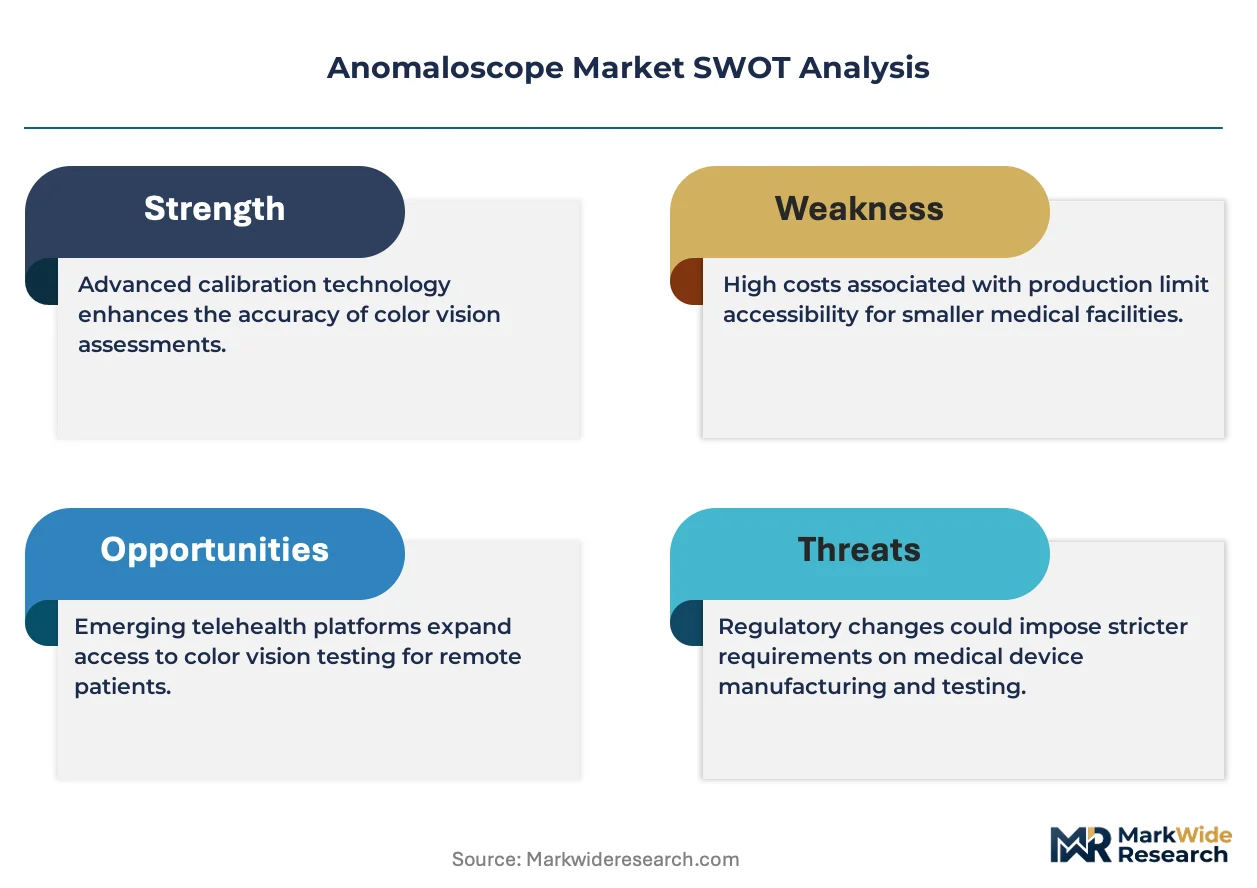
Digital calibration protocols are compressing replacement cycles for legacy anomaloscope hardware as hospital vision laboratories prioritize software-validated precision over mechanical longevity. This shift intensifies R&D allocation toward algorithm-driven color-matching engines and away from optical component refinement.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated review timelines for automated diagnostic devices are incentivizing hospital procurement committees to upgrade from manual to digital anomaloscope systems.
- Occupational health mandates:Aviation and maritime regulatory bodies in Japan and Germany now require documented color vision screening protocols, expanding institutional purchasing.
- LED nanometer precision:Solid-state light sources with tighter wavelength control are reducing inter-device variability, enabling multi-site clinical studies.
Market Restraints
- Specialized optical glass supply:German and Japanese suppliers dominate precision-filter substrate production, creating single-source vulnerability for mid-tier manufacturers.
- EU MDR clinical evidence requirements:Expanded post-market surveillance obligations are extending time-to-revenue for new anomaloscope entrants by 18-24 months.
- Tablet-based color screening apps:Consumer-grade alternatives, though clinically non-equivalent, are eroding price elasticity in occupational health segments.
Strategic Opportunities
- Pediatric vision screening networks:School-based early detection programs in India and Brazil remain hardware-underserved, favoring portable digital units.
- Tele-ophthalmology integration:Remote diagnostic platforms are creating demand for anomaloscopes with cloud-native calibration logging and encrypted data transmission.
- Japan METI medical device export incentives:Subsidized certification support is lowering market entry costs for manufacturers targeting Southeast Asian clinical networks.
Industry Challenges
- IEC 60601-1 third edition compliance:Revised electromagnetic immunity testing protocols are forcing hardware redesigns for existing product lines.
- Software validation documentation:Algorithm-driven color-matching interpretations now require extensive clinical performance datasets, straining smaller engineering teams.
- Legacy system interoperability:Hospital information system integration demands are complicating deployment timelines for automated anomaloscope configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anomaloscope Market |
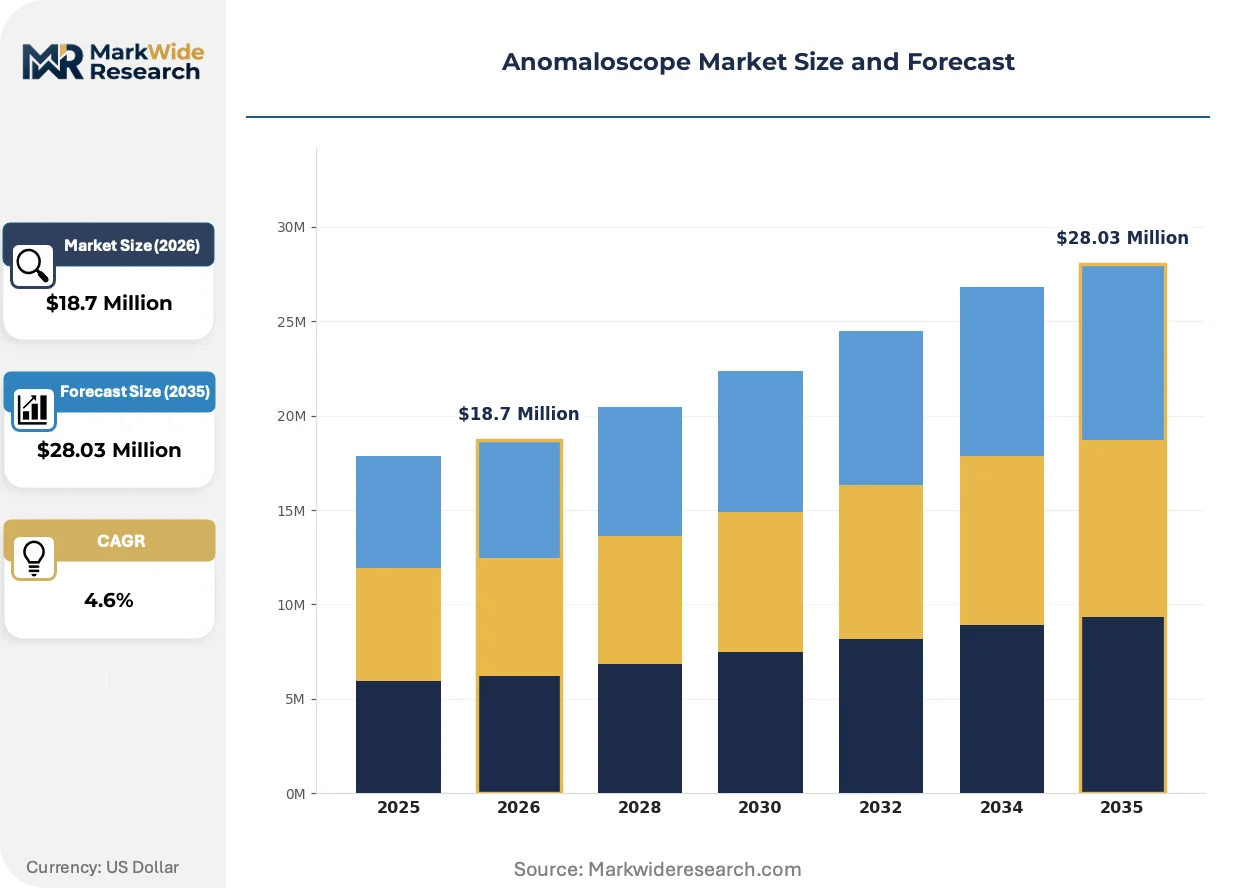
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $28.03 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Anomaloscope, Portable Anomaloscope, Digital Anomaloscope, Automated Anomaloscope Application: Color Vision Testing, Clinical Diagnostics, Research Studies, Occupational Health End User: Hospitals, Clinical Laboratories, Research Institutions, Vision Testing Centers Technology: LED Technology, Optical Filters, Software-Driven, Customizable Settings |
| Companies Covered | Heine Optotechnik GmbH & Co. KG, Hoya Corporation, Zeiss Group, Stereo Optical Company, Inc., Topcon Corporation, Essilor International, Nikon Corporation, Neitz Instruments Co., Ltd., Oculus Optikgeräte GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anomaloscope Market Strategic Shifts
Spectral engineering advances and regulatory digitization are converging to redefine how color vision assessment devices are manufactured, certified, and deployed across clinical environments.
LED-array anomaloscopes with programmable wavelength output are supplanting tungsten-filter legacy systems in hospital vision laboratories. German and Japanese diagnostic centers are completing fleet replacements within 24-month procurement windows. This technology transition is compressing the addressable market for replacement bulb and filter component suppliers.
EU MDR Annex XVI expansion is reclassifying certain color vision screening devices as Class IIa medical products requiring notified body oversight. Manufacturers must now submit clinical evaluation reports demonstrating diagnostic accuracy equivalence to predicate devices. High-volume occupational health screening programs in Germany are delaying purchase decisions pending certification clarity.
Subscription-based calibration and software maintenance contracts are displacing upfront capital expenditure models among mid-sized ophthalmology practices. Device vendors now bundle remote diagnostic support with hardware leases, capturing recurring revenue streams. This shift is most pronounced in United States hospital outpatient departments managing constrained capital budgets.
Anomaloscope Market Segmentation
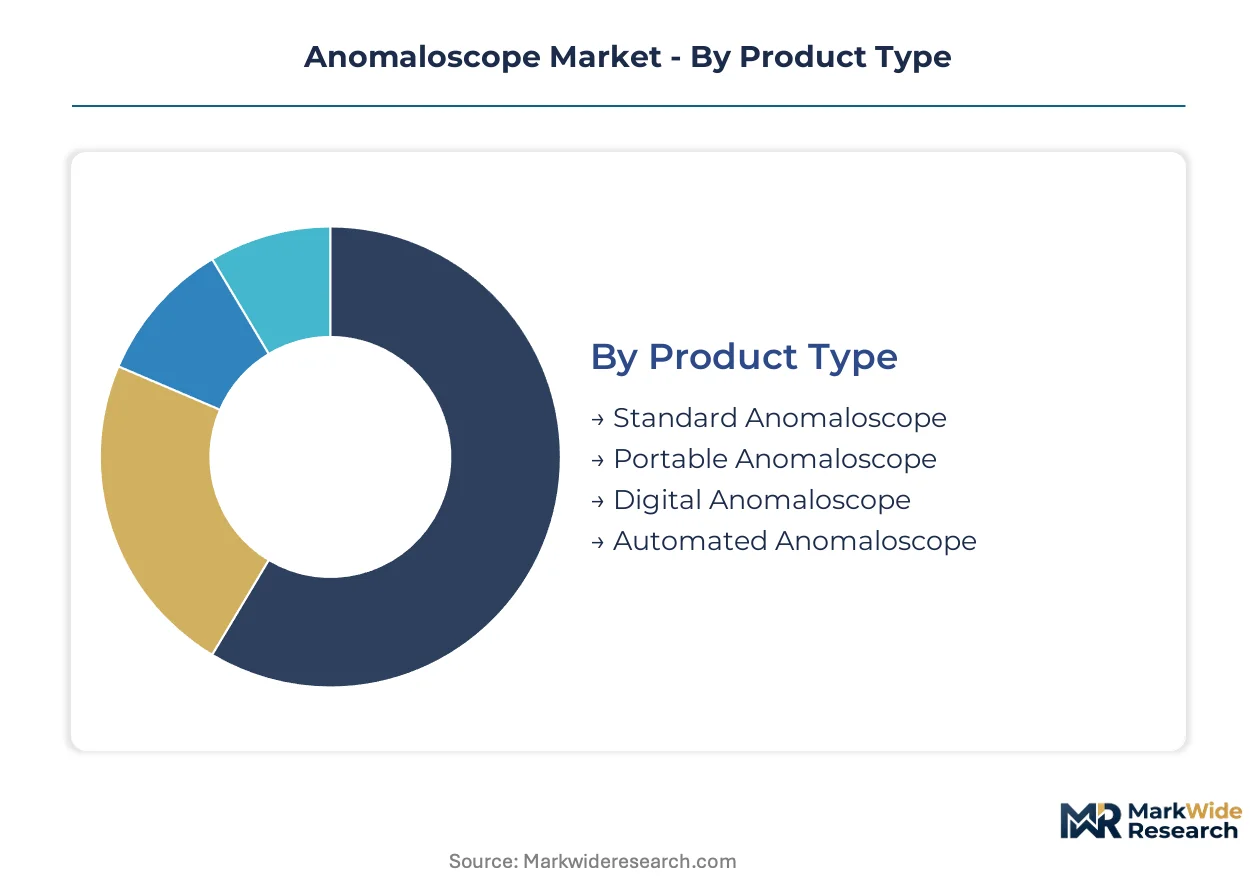
Channel economics in the anomaloscope market vary sharply by product configuration and end-user procurement authority. Hospital vision laboratories, occupational health programs, and research institutions each impose distinct technical specifications and purchasing workflows that reshape competitive positioning across segment boundaries.
Product Type:
Distribution channels segment cleanly by mobility requirements and calibration complexity, with hospital-based procurement favoring fixed-installation precision while occupational health buyers prioritize field-deployable units.
- Digital Anomaloscope:Software-validated wavelength control replaces mechanical adjustment with touchscreen interfaces and automated scoring algorithms. Demand concentrates in German and Japanese diagnostic ophthalmology clinics completing fleet modernization programs, driven by EU MDR documentation requirements for traceable calibration records.
- Automated Anomaloscope:Fully self-administered testing protocols with integrated patient response logging and direct electronic health record transmission. United States hospital outpatient departments are expanding fastest here, pressured by staffing constraints and throughput targets in high-volume vision screening programs.
- Standard Anomaloscope:Bench-mounted manual matching instruments with tungsten light sources and rotating filter wheels.
- Portable Anomaloscope:Battery-powered handheld units for occupational health field screening and school-based vision programs.
Standard anomaloscopes dominate installed base. Automated configurations are where expansion concentrates.
Application:
Cost tier stratification separates reimbursed clinical procedures from self-funded occupational compliance and grant-supported research, with pricing power varying accordingly.
- Clinical Diagnostics:Reimbursable color vision assessment within ophthalmology practices and hospital departments, requiring FDA 510(k) or CE marking for diagnostic claims. Japanese aviation medical examiners and German maritime health officers now mandate documented anomaloscope testing, expanding institutional purchasing.
- Occupational Health:Regulatory-mandated screening for safety-critical roles in transportation, utilities, and defense sectors. India's expanding manufacturing base and Brazil's port authority modernization are driving portable unit demand where local calibration infrastructure remains limited.
- Color Vision Testing:General population screening and educational assessment applications.
- Research Studies:Academic and pharmaceutical protocols requiring standardized, exportable color discrimination metrics.
Clinical diagnostics commands premium pricing. Occupational health is climbing the fastest.
End User:
Customer type determines service bundling requirements, with integrated delivery networks demanding enterprise software compatibility that smaller independent laboratories cannot justify.
- Hospitals:Multi-department vision laboratories with capital equipment committees, information system integration mandates, and preventive maintenance contracts. United States health systems are consolidating vendor relationships, favoring suppliers offering remote calibration support and cybersecurity-compliant data architectures.
- Vision Testing Centers:Specialized outpatient facilities serving occupational health contracts and driver licensing authorities. German and Japanese networks are standardizing on digital platforms to satisfy regulatory audit requirements.
- Clinical Laboratories:Hospital-affiliated or independent testing facilities processing high specimen volumes.
- Research Institutions:Universities and pharmaceutical developers requiring customizable protocols and publication-grade precision documentation.
Hospitals anchor procurement volume. Vision testing centers are gaining share fastest.
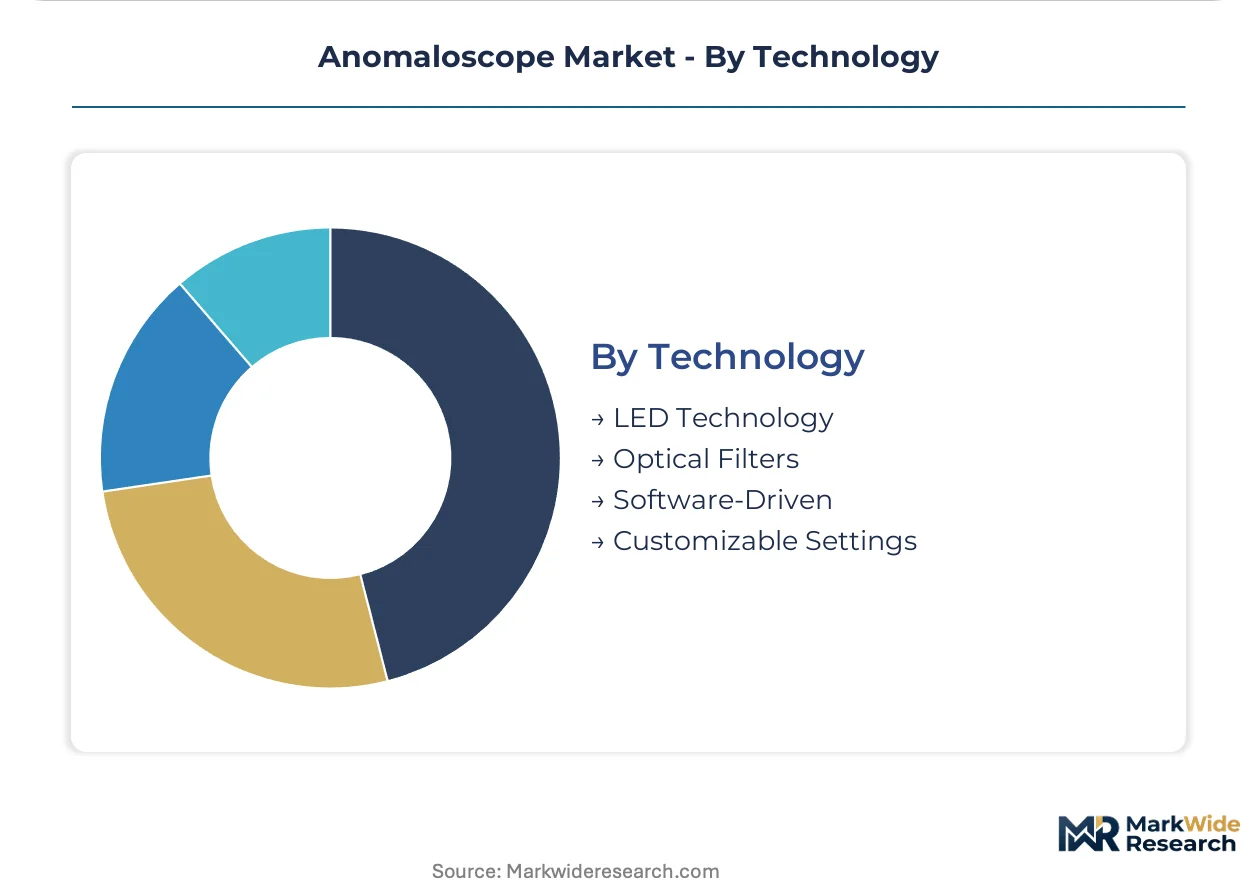
Technology:
Supply concentration in precision optical components and semiconductor light sources is reshaping vendor sourcing strategies and geographic manufacturing footprints.
- LED Technology:Solid-state emitters with nanometer-scale wavelength stability and programmable intensity profiles. German and Japanese LED substrate suppliers control critical feedstock, creating sourcing vulnerability for mid-tier device assemblers seeking IEC 60601-1 compliance.
- Software-Driven:Algorithmic color-matching interpretation with cloud-native calibration logging and encrypted transmission protocols. Tele-ophthalmology platforms in the United States are specifying these capabilities for remote diagnostic deployment.
- Optical Filters:Precision-coated glass substrates for wavelength selection in legacy and hybrid instrument designs.
- Customizable Settings:User-configurable test protocols adapting to pediatric, geriatric, or research-specific requirements.
Optical filters retain legacy installed base. Software-driven architectures are where R&D allocation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in precision optical instruments favor established manufacturing clusters in Germany and Japan, while import dependency shapes procurement strategies in emerging clinical markets across India and Brazil.
United States
Hospital outpatient departments and aviation medical examiners drive institutional procurement of automated anomaloscope systems. FDA 510(k) pathway streamlining accelerates digital device approvals, reducing time-to-deployment for hospital vision laboratories. The Greater Boston research corridor and Texas Medical Center anchor demand from academic ophthalmology programs and military health systems.
Germany
Maritime health officer mandates and occupational screening protocols expand institutional purchasing across port cities and industrial zones. EU MDR Annex XVI reclassification tightens clinical evidence requirements for color vision devices, delaying some procurement decisions. The Rhine-Ruhr metropolitan region concentrates diagnostic ophthalmology clinic networks completing fleet modernization programs.
Japan
Aviation regulatory bodies and METI medical device export incentives stimulate domestic production and regional market development. PMDA alignment with international standards facilitates Southeast Asian market access for Japanese manufacturers. The Kanto region around Tokyo hosts dense clusters of precision optical engineering facilities serving both domestic and export markets.
India
School-based pediatric vision screening programs and expanding manufacturing base occupational health requirements create hardware demand. CDSCO medical device regulations are harmonizing with international standards, though local calibration infrastructure remains limited. Maharashtra and Gujarat industrial corridors drive portable unit procurement for field-deployable screening applications.
Brazil
Port authority modernization and driver licensing authority standardization expand institutional purchasing for documented color vision assessment. ANVISA regulatory frameworks are evolving toward international convergence, creating certification pathway uncertainty. São Paulo state concentrates both clinical diagnostic demand and occupational health screening contract awards.
Anomaloscope Market Competitive Environment
Concentration sits with diversified optical engineering conglomerates possessing captive precision manufacturing capabilities. The vendor base stratifies across three tiers: heritage optics houses with hospital laboratory relationships, specialized handheld instrument designers serving occupational health segments, and diversified ophthalmic equipment portfolios addressing high-volume screening programs. Scale-driven consolidation and technology licensing partnerships represent the dominant competitive vectors reshaping market access.
Within the heritage optics tier, Zeiss Group and Hoya Corporation exemplify positioning built on vertical control over precision optical component supply. Heine Optotechnik GmbH & Co. KG occupies a specialist position in handheld diagnostic instrument design. These three anchors illustrate how geographic clustering in German and Japanese precision manufacturing regions reinforces competitive moats through proximity to LED substrate and optical filter suppliers.
| Leading Market Players |
|---|
| Heine Optotechnik GmbH & Co. KG |
| Hoya Corporation |
| Zeiss Group |
| Stereo Optical Company, Inc. |
| Topcon Corporation |
| Essilor International |
| Nikon Corporation |
| Neitz Instruments Co., Ltd. |
| Oculus Optikgeräte GmbH |
| Others |
Value Chain & Pricing Dynamics
LED substrate substitution for tungsten-filter assemblies is compressing component costs while redrawing procurement geography toward German and Japanese precision semiconductor suppliers, simultaneously elevating pricing power for captive manufacturers and squeezing margins for device assemblers dependent on spot-market sourcing.
Pricing Analysis
Hospital vision laboratories anchor a three-tier pricing structure across premium, standard, and economy levels, with FDA 510(k) certification tier and software-validated calibration precision serving as primary differentiation drivers. Price erosion runs through the standard manual instrument tier as tablet-based screening alternatives erode occupational health budgets. Occupational health programs exhibit highest price sensitivity due to compliance-mandated volume purchasing, while research institutions demonstrate lowest sensitivity given grant-funded procurement protocols.
Supply Chain Analysis
Inventory lead times for precision optical glass substrates now extend 18-24 months following EU MDR Annex XVI reclassification documentation requirements. German and Japanese suppliers dominate LED emitter and optical filter feedstock, with device assembly drawing from Taiwanese semiconductor packaging and Chinese electronic component sourcing. Single-source vulnerability concentrates in precision-filter substrate production. Distribution runs through authorized medical device distributors with notified body certification and direct hospital procurement committee relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across pediatric vision screening networks and tele-ophthalmology platforms, as regulatory digitization and remote diagnostic validation create addressable niches underserved by incumbent hospital-laboratory specialists.
For Market Incumbents: Compound defensive positioning through backward integration into LED substrate supply and accelerated FDA 510(k) pathway pre-submission for automated configurations. Threat from tablet-based screening alternatives demands software companion development for cloud-native calibration logging. Certification investment in EU MDR Annex XVI clinical evidence packages represents the critical lever for European market retention. For New Entrants and Emerging Players: Japan METI medical device export incentive fast-tracks lower Southeast Asian market entry costs for manufacturers targeting calibration-underserved Indian and Brazilian screening networks. Most penetrable white space sits in portable digital units for school-based pediatric programs. Go-to-market angle should emphasize battery-powered field deployability with minimal local calibration infrastructure requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ophthalmic equipment portfolios seeking platform consolidation into automated diagnostic workflows. Five-to-ten-year viability hinges on software-driven recurring revenue capture through subscription calibration contracts. Acquisition target archetype: mid-tier device assemblers with hospital system relationships but lacking captive optical component supply. Signal to watch is FDA 510(k) review timeline compression for algorithm-driven color-matching submissions.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR Annex XVI compliance unlocks German maritime health officer procurement mandates. |
| Hospital System Partnership | Integrated delivery network consolidation favors vendors with cybersecurity-compliant data architectures. |
| Software Companion Development | Cloud-native calibration logging satisfies tele-ophthalmology platform specifications in United States deployments. |
| Backward Integration into LED Supply | Captive wavelength emitter control reduces IEC 60601-1 third edition compliance redesign costs. |
| Pediatric Screening Network Expansion | Portable digital unit demand concentrates in Maharashtra and Gujarat industrial corridors for field applications. |
Study Parameters
The analysis maps digital anomaloscope, automated anomaloscope, standard anomaloscope, and portable anomaloscope sub-sectors, each validated through ophthalmology clinic directors, hospital purchasing committee members, biomedical engineers, and occupational health program administrators. Primary interview findings triangulate against FDA 510(k) filing databases, EU MDR notified body certification records, Japanese PMDA medical device registrations, and Indian CDSCO import licensing data. Bottom-up unit shipment estimates reconcile with top-down addressable market sizing across the projection horizon.
Consistency checks validate volume and value outputs against hospital capital expenditure surveys, ophthalmology equipment procurement databases, and aviation medical examiner screening protocol documentation. Segmentation dimensions encompass product configuration, application type, end-user category, and technology architecture, with CAGRs derived from installed base replacement cycle analysis and fleet modernization program timelines. Forecast inputs incorporate LED substrate cost trajectory assumptions and regulatory review timeline elasticity.
Underlying assumptions cover EU MDR Annex XVI implementation pace, FDA automated device review streamlining continuity, and Japanese METI export incentive program duration, with deviation risk concentrated in software validation documentation burden escalation. Forecasts reflect these documented conditions. Revision becomes warranted when tablet-based screening alternative clinical equivalence claims achieve regulatory recognition thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Glass Scintillator Market
Optics
Fiber Optic Development Tools Market
Optics
Electro Optics Market
Optics
Global Enhanced Vision System Market
Optics
Beam Expanders Market
Optics
Fiber-Optic Couplers Market
Optics
Smartphone Lenses Market
Optics
3D Optical Microscope Market
Optics
Residential 1080P Laser Television Projector Market
Optics
Optical Telephoto Lens Market
Optics
Laser Transmitter Market
Optics
Solid State Lasers Market
Optics
Optical Fiber Raw Material Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Sports Optics Market
Optics
MEMS Mirrors Market