
 Digital Holographic Microscopy Market | 2026-2036
Digital Holographic Microscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Holographic Microscopy Market Insights
Buyer concentration among pharmaceutical and biotechnology companies is consolidating as contract research organizations centralize imaging procurement under multi-year service agreements. Zeiss Group leverages its established confocal microscopy installed base to cross-sell holographic upgrades into existing accounts. Phase Holographic Imaging specializes in quantitative phase imaging workflows that anchor its position in cell biology laboratories. NanoLive SA competes through label-free tomography platforms that reduce phototoxicity in long-term live-cell studies.
Digital holographic microscopy captures interference patterns between reference and object light beams to reconstruct three-dimensional sample morphology without staining or fixation, typically achieving axial resolution below one micrometer using laser illumination at visible or near-infrared wavelengths. The technique enables real-time observation of transparent biological specimens and dynamic material processes across pharmaceutical quality control and semiconductor inspection workflows. Microscopes command the largest share of product type revenue, though imaging software is expanding fastest as laboratories prioritize AI-assisted phase reconstruction and automated particle tracking. Cell biology dominates application demand, while material science segments attract premium pricing for customized environmental chambers and high-temperature sample holders.
FDA device classification rules shape commercialization pathways for holographic diagnostic instruments in the United States, while the EU MDR and CE marking requirements govern market access for European healthcare deployments. ISO 10993 biocompatibility testing standards and IEC 61010-1 electrical safety certifications create compliance thresholds that filter smaller instrument assemblers from clinical segments. Stakeholders must monitor evolving reimbursement codes for digital pathology and label-free cytometry to anticipate which end-user budgets will absorb next-generation holographic platforms.
Market Dynamics
Label-free imaging requirements from pharmaceutical quality control laboratories are compressing replacement cycles for legacy fluorescence microscopes, forcing instrument vendors to bundle AI reconstruction software with hardware contracts to defend account relationships.
Growth Catalysts
- NIH funding concentration:United States research centers are channeling grants toward live-cell analysis platforms that eliminate phototoxicity risks in long-term studies. This funding stream accelerates procurement decisions at academic medical centers.
- EU MDR pathway clarity:CE marking requirements for holographic diagnostic devices have stabilized, reducing regulatory uncertainty for European healthcare deployments and enabling predictable commercialization timelines.
- Semiconductor wafer inspection:Taiwan and South Korea fabrication facilities are adopting high-speed holographic metrology for sub-micron defect detection in advanced packaging processes.
Market Restraints
- Laser source cost volatility:Solid-state laser diodes and helium-neon tubes face price instability from rare earth supply concentration in Chinese processing facilities, squeezing instrument margins.
- Computational infrastructure requirements:GPU clusters for real-time phase reconstruction demand capital outlays that filter smaller laboratories from purchasing decisions.
- Confocal microscopy substitution:Established fluorescence techniques with mature reagent ecosystems retain preference among pathologists despite holography's label-free advantages.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO quality control mandates for export-oriented generic drug producers are creating first-time demand for automated cell viability monitoring.
- AI-phase reconstruction convergence:Deep learning algorithms trained on synthetic holograms are unifying hardware-software value capture away from standalone instrument sales.
- Cloud-enabled remote pathology:Telemedicine infrastructure in Brazilian diagnostic networks opens channel innovation for holographic slide-sharing platforms.
Industry Challenges
- Computational microscopy skill scarcity:Biologists trained in conventional optical techniques require reskilling in interferometry physics and Python-based image processing pipelines.
- IEC 61010-1 certification timelines:Electrical safety testing for laser-classified instruments extends product launch schedules by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Holographic Microscopy Market |
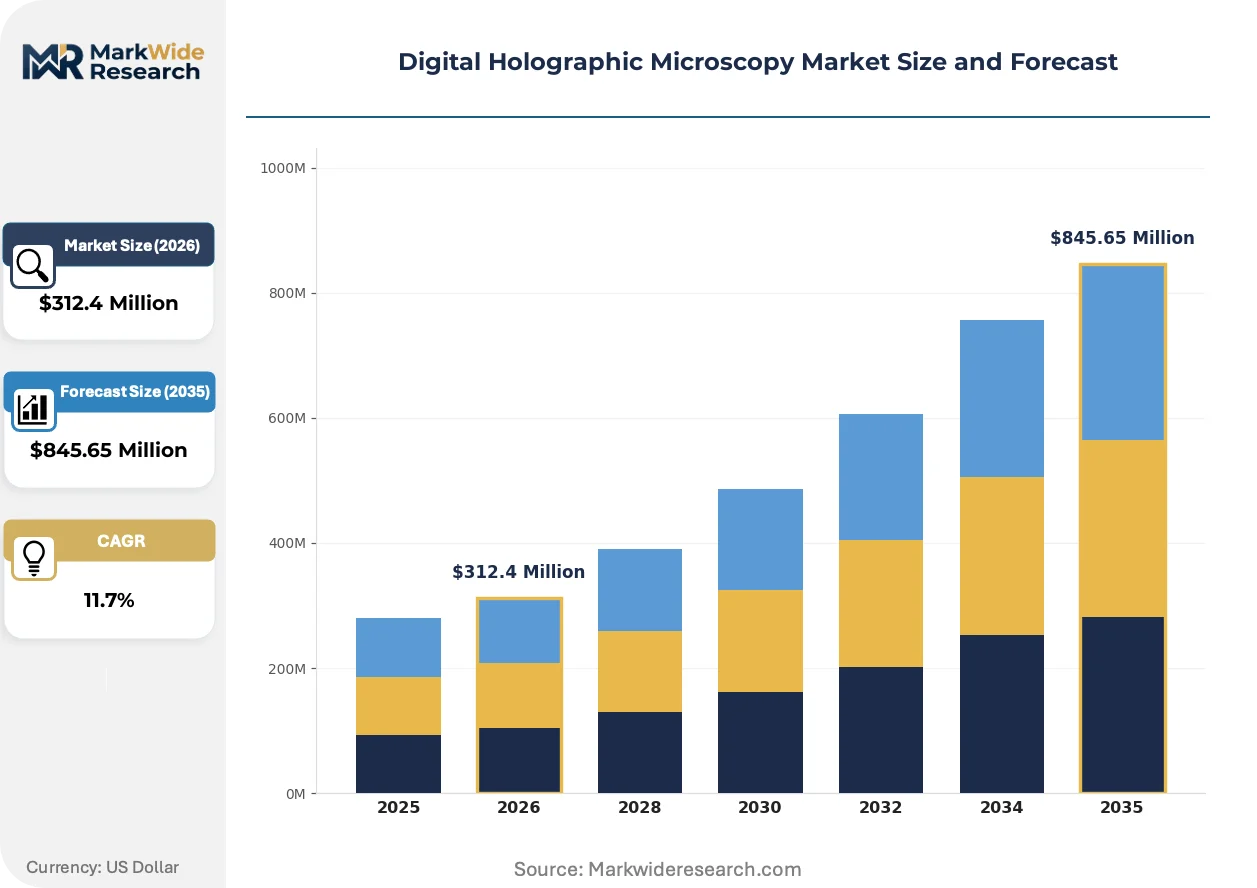
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microscopes, Accessories, Imaging Software, Analysis Tools End User: Research Institutions, Healthcare Facilities, Biotechnology Companies, Educational Institutes Application: Cell Biology, Material Science, Pathology, Microorganism Studies Installation: Laboratory, On-site, Clinical, Educational Environment |
| Companies Covered | NanoLive SA, Zeiss Group, Lyncee Tec, Geola Digital UAB, Olympus Corporation, Phase Holographic Imaging, Leica Microsystems, RealView Imaging, Ovizio Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Holographic Microscopy Market Trends and Innovations
Quantum dot illumination sources and federated learning architectures are compressing the boundary between hardware performance and software-defined microscopy capabilities.
Deep learning-based phase unwrapping algorithms are unifying previously separate reconstruction steps into single inference pipelines. Pharmaceutical quality control laboratories in Germany and Switzerland are deploying these systems for real-time batch release decisions. This compression is enabling instrument vendors to capture recurring software revenue alongside capital equipment sales.
EU MDR classification rules for holographic diagnostic devices are tightening clinical evidence requirements for CE marking. Manufacturers must now submit prospective validation studies rather than retrospective analytical performance data. Cell biology applications face the steepest compliance burden, while material science segments benefit from existing ISO 17025 laboratory accreditation pathways.
Contract research organizations are consolidating imaging procurement under multi-year service agreements that bundle instrument placement, maintenance, and consumables. This displaces traditional capital purchase models at biotechnology companies in Massachusetts and California. The shift is most visible among mid-sized CROs seeking to standardize cross-site data comparability for multi-center drug safety studies.
Digital Holographic Microscopy Market Segmentation
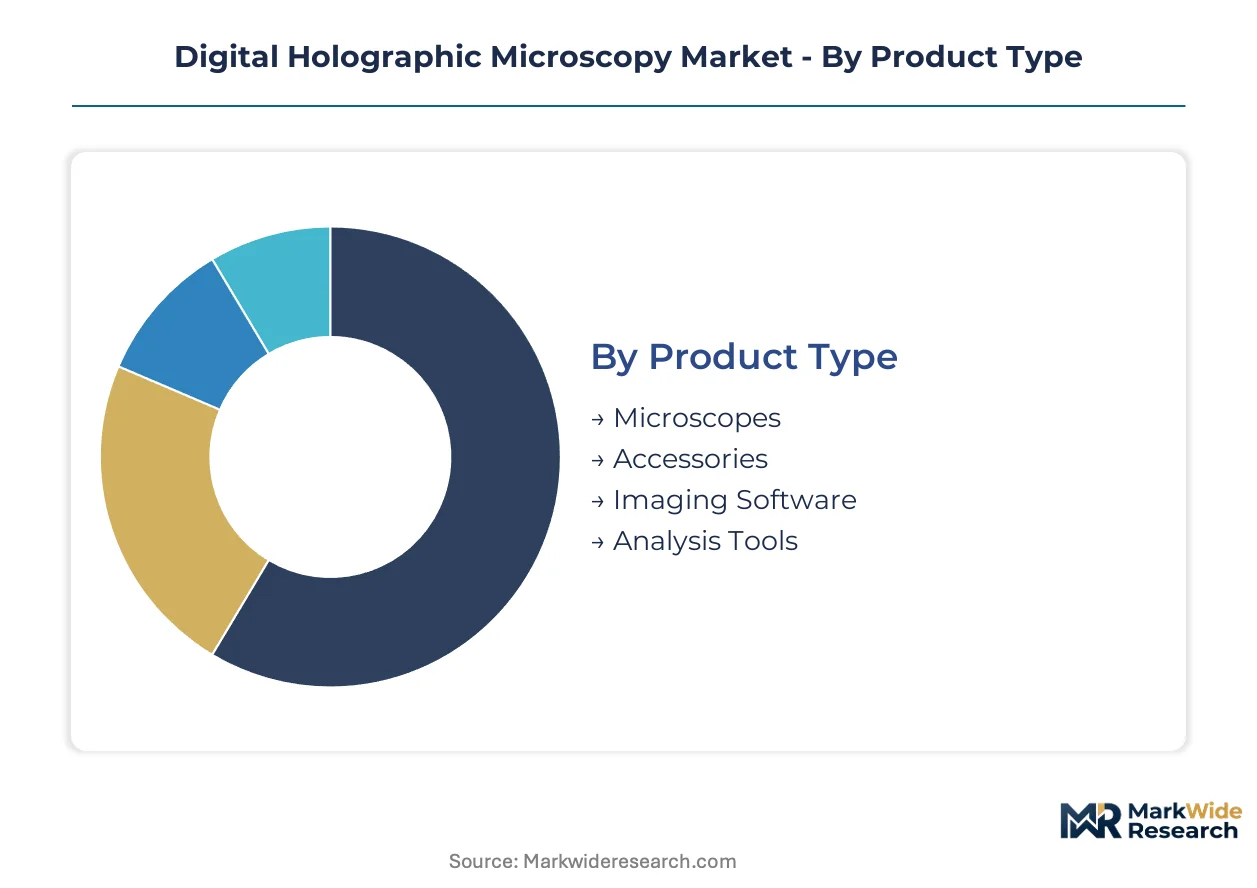
Segmentation in digital holographic microscopy reveals divergent purchasing logic across hardware, software, and service layers. Pharmaceutical laboratories prioritize label-free workflows while semiconductor fabs demand sub-micron metrology precision. Understanding these splits enables vendors to align R&D investment with margin concentration points.
Product Type:
Hardware platforms command premium pricing through optical precision, while software layers capture recurring revenue through AI-assisted reconstruction subscriptions.
- Microscopes:Laser-interference optical benches with CMOS sensors achieve axial resolution below one micrometer. Demand concentrates in United States NIH-funded centers replacing legacy fluorescence systems due to phototoxicity elimination requirements.
- Imaging Software:Deep learning algorithms compress phase unwrapping and reconstruction into single inference pipelines. German pharmaceutical quality control laboratories deploy these for real-time batch release decisions, driving fastest expansion in recurring revenue models.
- Accessories:Environmental chambers and high-temperature sample holders extend platform utility for material science applications.
- Analysis Tools:Python-based particle tracking modules enable automated quantification of cell viability metrics.
Mature deployment sits with Microscopes. Newer deployment is concentrated in Imaging Software.
End User:
Capital intensity separates institutional buyers from commercial operators, with procurement centralization reshaping vendor relationship economics.
- Biotechnology Companies:Contract research organizations in Massachusetts and California consolidate multi-year service agreements bundling instrument placement, maintenance, and consumables. This displaces traditional capital purchase models as mid-sized CROs standardize cross-site data comparability.
- Research Institutions:Academic medical centers leverage NIH grants for live-cell analysis platforms. United States funding concentration accelerates replacement cycles for legacy optical microscopes at centers prioritizing long-term study viability.
- Healthcare Facilities:EU MDR classification rules tighten clinical evidence requirements for holographic diagnostic deployments.
- Educational Institutes:Training laboratories require simplified interfaces for biologists reskilling in interferometry physics.
Procurement consolidation is reshaping Biotechnology Companies. Grant dependency characterizes Research Institutions.
Application:
Biological transparency drives volume, while material customization enables margin extraction through specialized environmental configurations.
- Cell Biology:Quantitative phase imaging enables real-time observation of transparent specimens without staining or fixation. Demand anchors in pharmaceutical laboratories expanding label-free imaging procurement for live-cell analysis workflows.
- Material Science:Customized environmental chambers and high-temperature sample holders attract premium pricing. Taiwan and South Korea semiconductor fabrication facilities adopt high-speed holographic metrology for sub-micron defect detection in advanced packaging.
- Pathology:FDA clearance pathways for holographic diagnostic devices shorten time-to-market for instrument developers targeting clinical segments.
- Microorganism Studies:Long-term viability monitoring supports antibiotic resistance research and quality control protocols.
Volume concentration sits with Cell Biology. Margin expansion concentrates in Material Science.
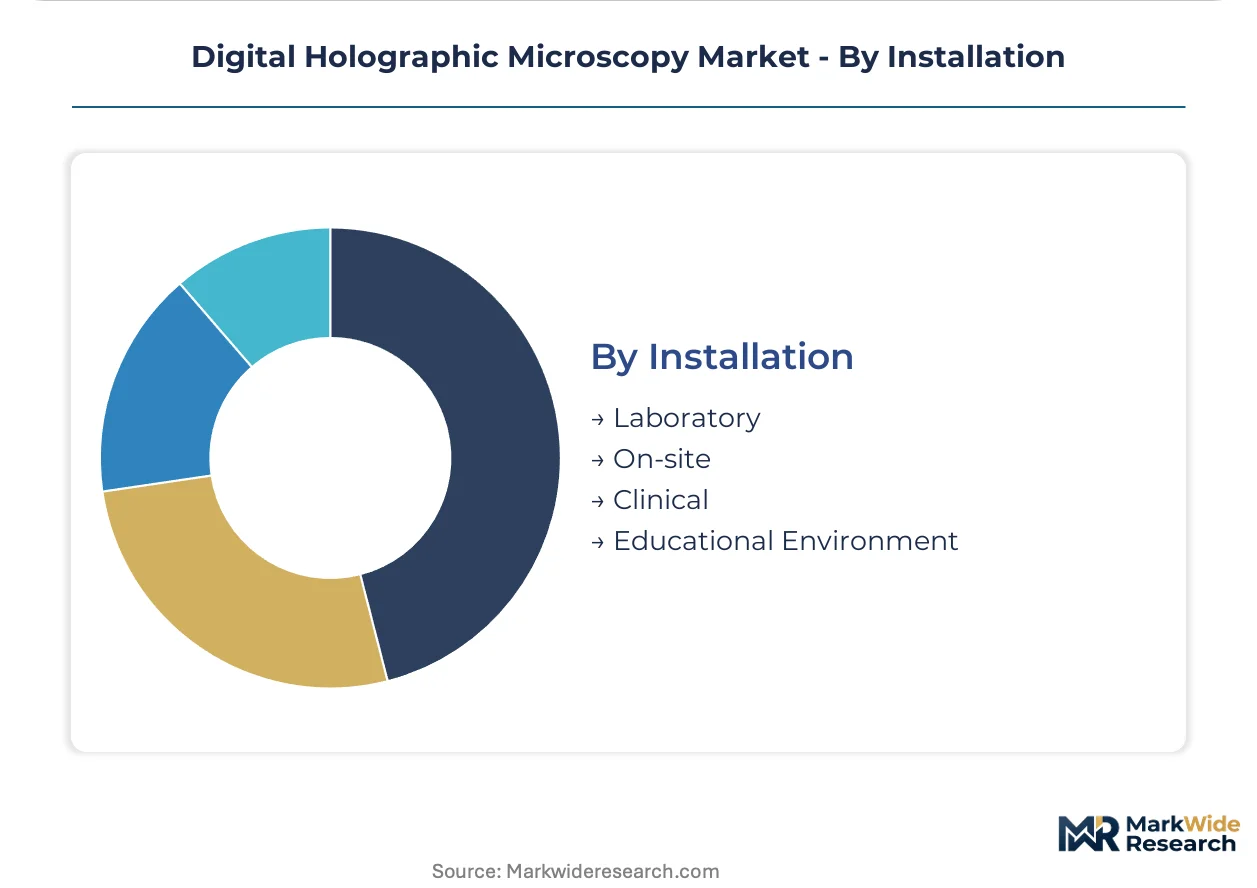
Installation:
Controlled environment requirements separate laboratory precision from field adaptability, with regulatory jurisdiction determining deployment feasibility.
- Laboratory:Climate-controlled optical tables with vibration isolation enable sub-micron stability. German pharmaceutical quality control laboratories represent anchor demand for automated cell viability monitoring systems.
- Clinical:IEC 61010-1 electrical safety certification and ISO 10993 biocompatibility testing create compliance thresholds. FDA device classification rules in the United States and EU MDR requirements govern market access for healthcare deployments.
- On-site:Portable configurations serve semiconductor wafer inspection in fabrication facilities requiring rapid defect detection.
- Educational Environment:Simplified alignment procedures accommodate users without interferometry physics training.
Regulatory complexity sits with Clinical. Standardized deployment concentrates in Laboratory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NIH-funded research centers in the United States concentrate procurement authority for live-cell analysis platforms, while pharmaceutical quality control mandates in Germany and CDSCO export requirements in India reshape regional demand patterns for label-free imaging systems.
United States
Academic medical centers in Massachusetts and California leverage NIH grants to accelerate replacement cycles for legacy fluorescence microscopes. FDA device classification rules for holographic diagnostic instruments compress time-to-market pathways for instrument developers. Boston-Cambridge biotechnology clusters anchor demand for automated cell viability monitoring in contract research workflows.
Germany
Pharmaceutical laboratories in Bavaria and North Rhine-Westphalia expand procurement of label-free imaging systems for real-time batch release decisions. EU MDR classification rules stabilize CE marking requirements for holographic diagnostic deployments. Heidelberg and Munich research institutes concentrate quantitative phase imaging adoption for transparent biological specimen analysis.
Switzerland
Swiss pharmaceutical quality control facilities prioritize phototoxicity elimination in long-term live-cell studies. Swissmedic regulatory pathways govern clinical evidence requirements for diagnostic holography platforms. Basel and Zurich metropolitan clusters integrate holographic metrology into semiconductor inspection workflows for precision manufacturing.
India
CDSCO quality control mandates for export-oriented generic drug producers create first-time demand for automated cell viability systems. The country's national pharmaceutical regulator tightens documentation requirements for holographic diagnostic submissions. Maharashtra and Gujarat pharmaceutical manufacturing corridors anchor procurement centralization under multi-year service agreements.
South Korea
Semiconductor fabrication facilities in Gyeonggi Province adopt high-speed holographic metrology for sub-micron defect detection in advanced packaging processes. MFDS medical device regulations shape commercialization timelines for clinical holography platforms. Seoul Capital Area research institutes channel government funding toward AI-assisted phase reconstruction development.
Digital Holographic Microscopy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue label-free tomography specialization and AI-phase reconstruction convergence. Market structure consolidates around optical instrumentation conglomerates with installed base leverage and niche specialists with workflow-specific anchoring. Three archetypes dominate: diversified microscopy incumbents cross-selling holographic upgrades, quantitative phase imaging pure-plays, and semiconductor metrology diversifiers. Competitive moves center on multi-year service agreement bundling and AI software subscription layering atop hardware contracts.
Within the diversified instrumentation tier, Zeiss Group and Olympus Corporation represent established optical microscopy incumbents with installed base leverage for holographic cross-selling. Phase Holographic Imaging exemplifies the quantitative phase imaging pure-play archetype with workflow-specific positioning in cell biology laboratories. NanoLive SA occupies a position within the label-free tomography specialization vector, anchoring competitive presence through phototoxicity reduction positioning in long-term live-cell studies.
| Leading Market Players |
|---|
| NanoLive SA |
| Zeiss Group |
| Lyncee Tec |
| Geola Digital UAB |
| Olympus Corporation |
| Phase Holographic Imaging |
| Leica Microsystems |
| RealView Imaging |
| Ovizio Imaging |
| Others |
Pricing and Supply Chain Analysis
Rare earth oxide price indices for neodymium and dysprosium feed directly into solid-state laser diode manufacturing costs, cascading through three distinct pricing tiers as instrument vendors absorb volatility or pass through to pharmaceutical laboratories, academic medical centers, and semiconductor fabrication facilities with varying contract structures.
Pricing Analysis
Volume concentration in entry-level educational microscopes compresses margins, while premium cell biology platforms with AI-assisted phase reconstruction capture recurring software subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic instruments from research-grade systems and teaching configurations. Pricing pressure stems from GPU cluster cost inflation filtering smaller laboratories from real-time reconstruction capabilities. Contract research organizations exhibit lowest price sensitivity due to multi-year service agreement bundling, while educational institutes face acute budget constraints.
Supply Chain Analysis
Optical engineering talent scarcity in Germany and Switzerland constrains precision interferometer assembly capacity despite strong demand from pharmaceutical quality control laboratories. Laser diode sourcing concentrates in China and Japan, with CMOS sensor fabrication anchored in Taiwan and South Korea. Helium-neon tube supply hinges on rare earth processing concentration creating single-source vulnerability. Distribution runs through authorized microscopy distributors with field service engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase where quantitative phase imaging displaces legacy fluorescence microscopy in live-cell analysis workflows, driven by phototoxicity elimination requirements from NIH-funded research centers.
For Market Incumbents: Extend software subscription revenue through AI-phase reconstruction bundling to defend against emerging label-free tomography specialists. Deepen installed base leverage by cross-selling holographic upgrades into existing confocal microscopy accounts. Prioritize IEC 61010-1 certification investment to compress launch timelines against regulatory uncertainty. For New Entrants and Emerging Players: Cloud-enabled remote pathology platforms offer the lowest channel friction for penetrating Brazilian diagnostic networks and Indian pharmaceutical manufacturing corridors. Target CDSCO-mandated quality control workflows in Maharashtra and Gujarat for first commercial traction. Pursue federated learning partnerships with academic medical centers to bypass capital-intensive GPU infrastructure requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor quantitative phase imaging pure-plays with workflow-specific anchoring in cell biology laboratories. Long-term viability centers on software-defined microscopy convergence unifying hardware-software value capture. Monitor NIH funding allocation shifts as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Phase Reconstruction Platform Launch | Deep learning algorithms unify reconstruction steps into single inference pipelines for German pharmaceutical laboratories. |
| Multi-Year Service Agreement Expansion | Bundled instrument placement displaces capital purchase models at Massachusetts and California contract research organizations. |
| EU MDR CE Marking Pathway Investment | Prospective validation studies enable predictable commercialization timelines for holographic diagnostic deployments. |
| Semiconductor Metrology Partnership | High-speed defect detection platforms penetrate Taiwan and South Korea advanced packaging fabrication facilities. |
| Cloud-Enabled Remote Pathology Development | Telemedicine infrastructure integration opens Brazilian diagnostic network channels for holographic slide-sharing platforms. |
Research Methodology
FDA 510(k) filings, NIH grant award databases, and EU MDR notified body documentation formed the secondary backbone, cross-referenced with primary interviews involving biomedical engineers, pharmaceutical quality control directors, hospital purchasing committee members, and microscopy distributor field service heads. Bottom-up instrument shipment data triangulated against top-down laboratory capital expenditure surveys.
Historical trendline analysis across laser interference microscopy adoption curves informed projection modeling across product type, application, end user, and installation segmentation dimensions. CAGRs derived from segment-level growth rate reconciliation with macroeconomic healthcare R&D spending indicators. Forecast inputs incorporated semiconductor fabrication capacity expansion plans and pharmaceutical outsourcing trends.
The model holds under stable NIH funding trajectories and EU MDR pathway continuity; deviation in rare earth supply disruptions or laser source cost volatility would shift instrument margin assumptions and replacement cycle timing. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Excimer Lasers for DUV Lithography Market
Optics
Optical Receivers Market
Optics
Photostimulation Lasers Market
Optics
Asia-Pacific Anti-Blue Ray Myopia Lenses Market
Optics
Fiber Optic Cable Market
Optics
Liquid Crystal on Silicon Market
Optics
Tunable Laser Market
Optics
Optical Imaging Market
Optics
Global Super Hi Vision Market
Optics
Asia Pacific Fiber Optics Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Quartz Glass Market
Optics
Middle East and Africa Tunable Laser Market
Optics
Global Enhanced Vision System Market
Optics
Fiber Optic Preform Market
Optics
Optical Sensing Market