
 Smart Photochromic Lenses Market | 2026-2036
Smart Photochromic Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Photochromic Lenses Market Insights
The premium ophthalmic lens tier is rebalancing around embedded sensor compatibility and real-time light adaptation, while commodity photochromic options face margin compression from private-label substitutes. EssilorLuxottica leverages its captive retail network to bundle smart tinting with progressive lens fittings. Hoya Corporation anchors its position through proprietary surfacing technology that reduces adaptation time. Transitions Optical differentiates via brand recognition and exclusive dye chemistry partnerships with independent optometrists.
Smart photochromic lenses incorporate silver halide or naphthopyran molecules that reversibly darken under ultraviolet exposure, typically achieving 70-85% visible light transmittance reduction within 30-60 seconds to protect retinal tissue from cumulative phototoxicity. Progressive lenses lead value generation due to complex freeform surfacing requirements and higher average selling prices across aging demographics. Nanotechnology-based coatings represent the fastest-expanding technology segment as manufacturers embed anti-reflective and hydrophobic layers directly into the photochromic matrix. Polycarbonate material dominates volume production because of impact resistance mandates in pediatric and safety eyewear applications.
FDA ophthalmic device regulations govern lens impact resistance and optical power accuracy in the United States, while the EU MDR and CE marking requirements enforce biocompatibility testing for materials contacting ocular tissue. ISO 8980 standards provide the international baseline for refractive power tolerances and abrasion resistance that manufacturers must satisfy for cross-border market access. Stakeholders should monitor how evolving blue-light filtration claims intersect with emerging digital wellness regulations across major economies.
Market Dynamics
The transition from silver halide to naphthopyran dye systems is compressing adaptation latency windows and forcing capital retooling across independent lens surfacing labs. This molecular platform shift reconfigures competitive advantage around proprietary formulation IP rather than manufacturing scale alone.
Growth Catalysts
- Prescription eyewear integration:Progressive lens fittings now bundle photochromic tinting as standard in managed vision benefit plans across the United States.
- REACH compliance thresholds:European ECHA restrictions on legacy photochromic precursors accelerate migration to safer naphthopyran chemistries.
- Pediatric safety mandates:Polycarbonate impact resistance requirements in school-age vision programs drive replacement demand for durable photochromic options.
Market Restraints
- Silver halide supply concentration:Specialty chemical precursors for legacy photochromic systems source predominantly from Chinese and Japanese specialty dye houses.
- Private-label substitution:Unbranded lens treatments at independent optometry chains compress margin on standard photochromic tiers.
- UV-B sensitivity limitations:Temperature-dependent darkening performance in extreme cold climates reduces functional reliability for Nordic outdoor workers.
Strategic Opportunities
- Embedded sensor convergence:Integration of ambient light sensors with electrochromic overlays enables real-time tint algorithms for digital device users.
- Direct-to-consumer channel expansion:Online vision testing platforms now route prescription verification to remote optometrists for photochromic lens fulfillment.
- EU MDR biocompatibility pathways:Streamlined CE marking for ocular surface contact materials accelerates novel matrix coating introductions.
Industry Challenges
- Freeform surfacing technician scarcity:Complex progressive lens topography programming requires specialized CAD/CAM operator training that outpaces vocational pipeline output.
- ISO 8980 certification timelines:Abrasion resistance and refractive power tolerance testing extends new product validation by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Photochromic Lenses Market |
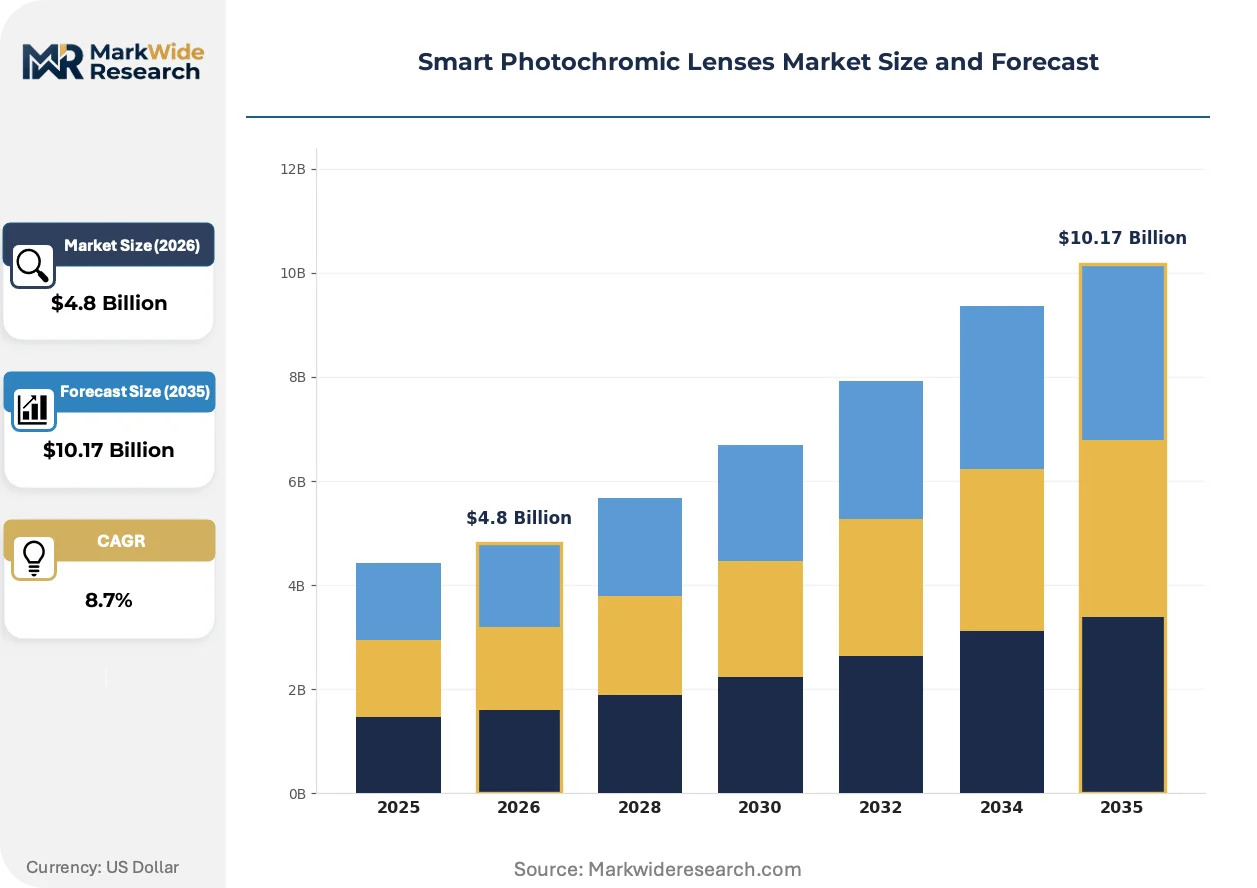
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Vision, Bifocal, Progressive, Polarized Material: Polycarbonate, Trivex, Glass, Hybrid End User: Retail Customers, Optical Stores, Online Platforms, Clinics Technology: Thermochromic, Photo-reactive, Nanotechnology, Smart Coatings |
| Companies Covered | EssilorLuxottica, Hoya Corporation, Transitions Optical, Carl Zeiss AG, Rodenstock GmbH, Corning Incorporated, Seiko Optical Products, Tokai Optical, Shamir Optical Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Photochromic Lenses Market Trends and Innovations
Real-time environmental responsiveness now defines premium tier positioning. Manufacturers embed computational layers into optical substrates while regulatory bodies tighten material safety verification protocols.
Nanotechnology-based coating architectures are decentralizing traditional supply relationships between lens fabricators and aftermarket treatment providers. Anti-reflective and hydrophobic functionalities now integrate directly into photochromic matrices during initial surfacing rather than post-coating application. Independent optical labs in Germany and South Korea adopt these integrated workflows to compress turnaround times for custom progressive orders.
EU MDR biocompatibility testing requirements for materials contacting ocular tissue now extend to photochromic dye leachate assessment. Manufacturers must demonstrate twelve-month stability data for naphthopyran molecules under thermal cycling protocols. EssilorLuxottica and Hoya Corporation have restructured European quality assurance departments to manage expanded documentation burdens.
Managed vision benefit administrators now mandate photochromic tinting as standard for outdoor worker categories in United States municipal and federal employee plans. This procurement consolidation shifts volume toward contracted lens fabricators with direct payer relationships. Independent optometrists respond by unbundling frame selection from lens specification consultations.
Smart Photochromic Lenses Market Segmentation
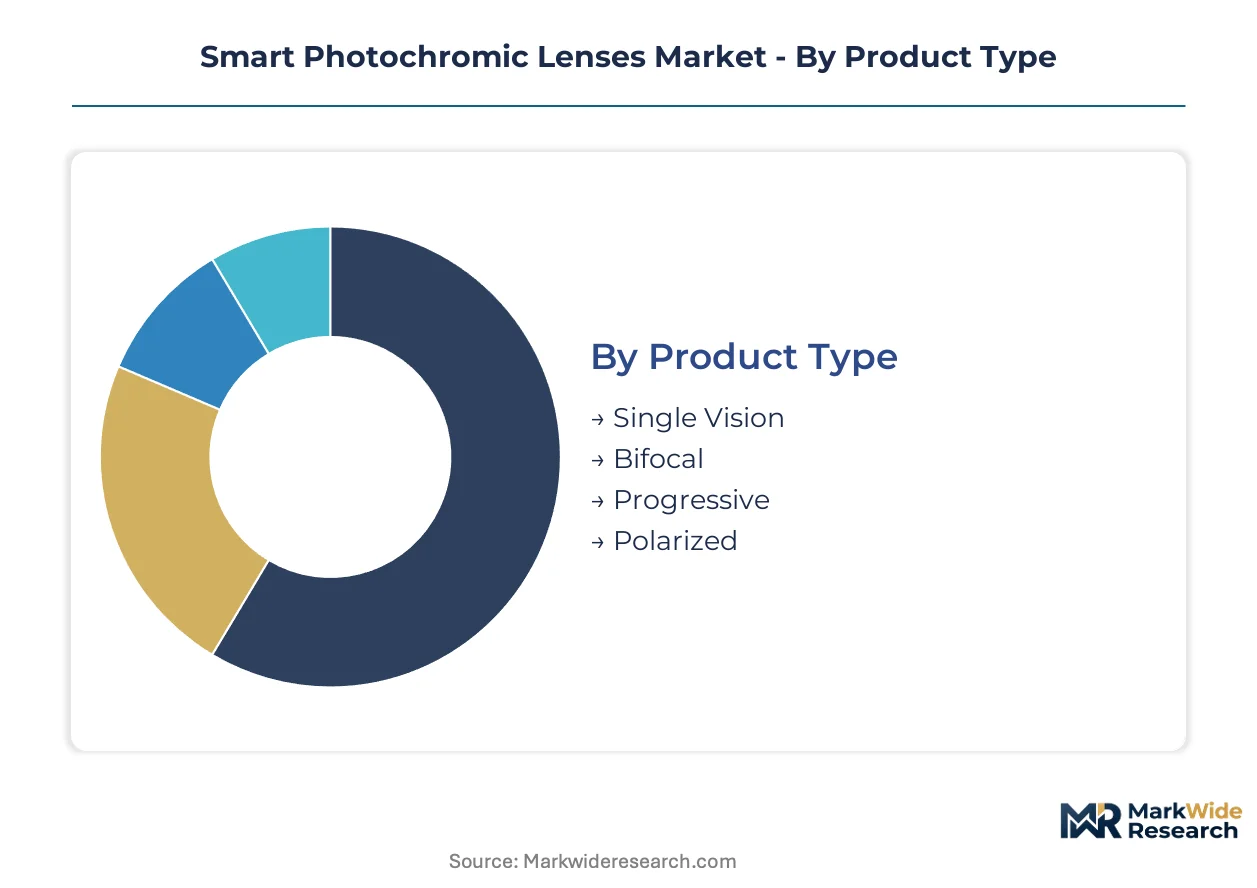
Smart photochromic lens purchasing decisions cascade through multiple technical dimensions simultaneously. Buyers weigh optical performance requirements against material durability, channel accessibility, and embedded technology tiers before finalizing specifications.
Product Type:
Vision correction complexity determines price band and fabrication lead time for lens orders.
- Progressive:Freeform surfacing integrates variable focal power across a continuous surface without visible segmentation lines. Aging demographics in Germany and Japan drive replacement demand for these high-value fittings in managed vision networks.
- Single Vision:Uniform diopter correction across the entire lens surface suits younger prescription holders and first-time photochromic adopters. Volume concentrates in United States school vision screening programs where polycarbonate impact resistance is mandatory.
- Bifocal:Distinct near-distance segments remain prevalent among cost-sensitive buyers in rural optometry practices.
- Polarized:Glare reduction overlays target fishing and maritime professionals in coastal Australian and Norwegian markets.
Volume sits with Single Vision; growth tilts toward Progressive.
Material:
Impact resistance mandates and weight preferences split procurement across safety-critical and lifestyle applications.
- Polycarbonate:Thermoplastic polymer delivers ANSI Z87.1 impact resistance at half the weight of mineral glass. Pediatric safety regulations in the United States and Australia enforce this material for school-age prescription fulfillment.
- Trivex:Urethane-based monomer combines shatter resistance with superior optical clarity and the lightest density in ophthalmic substrates. Premium positioning in South Korean and Swiss optical retail channels supports margin expansion.
- Glass:Mineral substrates persist in industrial safety eyewear where chemical resistance outweighs weight penalties.
- Hybrid:Composite laminates merge polycarbonate cores with hardcoat surfaces for niche military and aviation applications.
Polycarbonate dominates unit shipments; Trivex climbs the fastest on premium positioning.
End User:
Channel structure determines bundling economics and prescription verification workflows.
- Optical Stores:Brick-and-mortar fittings bundle comprehensive eye examinations with lens specification consultations. Independent practices in France and Italy retain customer relationships through personalized progressive lens fitting services.
- Online Platforms:Direct-to-consumer routing connects remote prescription verification with centralized surfacing labs. United States telehealth regulations now accommodate asynchronous refraction testing for photochromic lens fulfillment.
- Retail Customers:Big-box optical departments in suburban United States markets compete on price transparency and same-day service guarantees.
- Clinics:Hospital-affiliated ophthalmology departments manage post-surgical lens provisioning for cataract and refractive surgery patients.
Optical Stores anchor current volume; Online Platforms gain share fastest on convenience positioning.
Technology:
Molecular activation mechanisms differentiate adaptation speed, temperature stability, and manufacturing capital requirements.
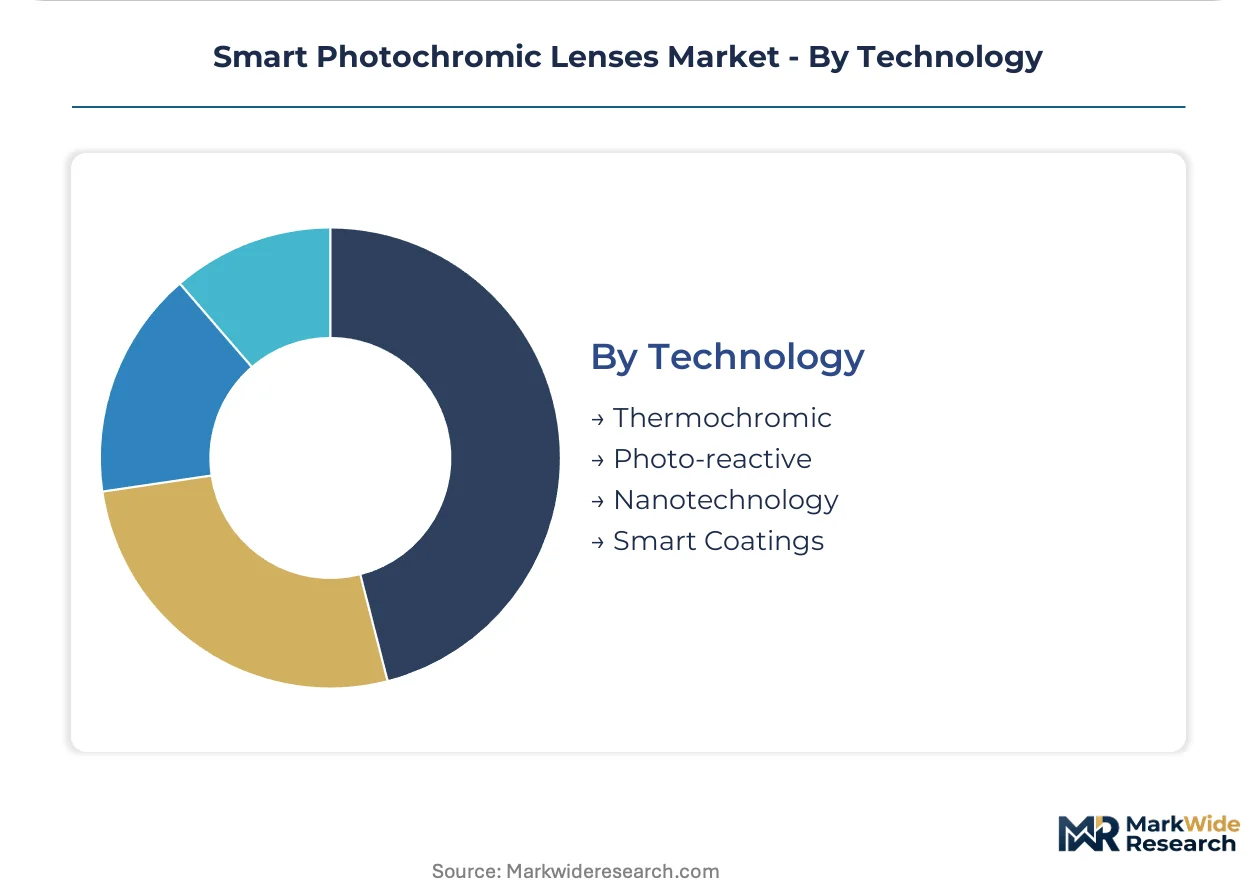
- Nanotechnology:Embedded nanoparticles enable anti-reflective and hydrophobic functionalities within the photochromic matrix itself. German and South Korean independent labs adopt these integrated workflows to compress custom progressive turnaround times.
- Photo-reactive:Naphthopyran dye systems achieve sub-60-second darkening response with reduced temperature sensitivity compared to legacy silver halide platforms. REACH compliance deadlines in Europe accelerate migration toward these safer chemistries.
- Thermochromic:Temperature-activated tinting serves specialized industrial applications where UV exposure is minimal.
- Smart Coatings:Electrochromic overlays with ambient light sensors enable algorithmic tint adjustment for prolonged digital device use.
Photo-reactive platforms command current volume; Nanotechnology shows steepest expansion trajectory on coating integration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EssilorLuxottica's manufacturing hub in Ligny-en-Barrois anchors European photochromic lens production, while managed vision benefit expansion in the United States and REACH compliance deadlines in Germany reshape procurement geography.
United States
Managed vision benefit administrators now mandate photochromic tinting for outdoor worker categories in municipal and federal employee plans. FDA ophthalmic device regulations govern lens impact resistance and optical power accuracy across all interstate commerce. Independent optometry practices in suburban Dallas and Phoenix compete through unbundled frame selection and same-day progressive lens service guarantees.
Germany
Aging demographics in Bavaria and Baden-Württemberg drive replacement demand for high-value progressive lens fittings in statutory health insurance networks. ECHA REACH restrictions on legacy photochromic precursors accelerate migration toward safer naphthopyran chemistries. Independent optical labs in Stuttgart and Munich adopt nanotechnology-integrated workflows to compress custom order turnaround times.
Japan
Progressive lens adoption among retirees in Tokyo and Osaka generates complex freeform surfacing demand for premium photochromic tiers. METI industrial standards and PMDA device oversight enforce biocompatibility testing for materials contacting ocular tissue. Hoya Corporation's Nagoya operations anchor proprietary surfacing technology that reduces adaptation latency for aging presbyopes.
South Korea
Premium Trivex positioning in Seoul and Busan optical retail channels supports margin expansion for lightweight impact-resistant photochromic options. MFDS ophthalmic device regulations mandate stability documentation for dye leachate under thermal cycling protocols. Independent labs in Daegu-Gyeongbuk integrate nanoparticle coatings directly into photochromic matrices during initial surfacing rather than post-coating application.
Australia
Pediatric safety regulations enforce polycarbonate impact resistance for school-age prescription fulfillment in New South Wales and Victoria. TGA therapeutic goods oversight extends to photochromic lens biocompatibility for post-surgical cataract patients. Polarized photochromic demand concentrates among fishing and maritime professionals in coastal Queensland and Western Australia.
Smart Photochromic Lenses Market Competitive Landscape
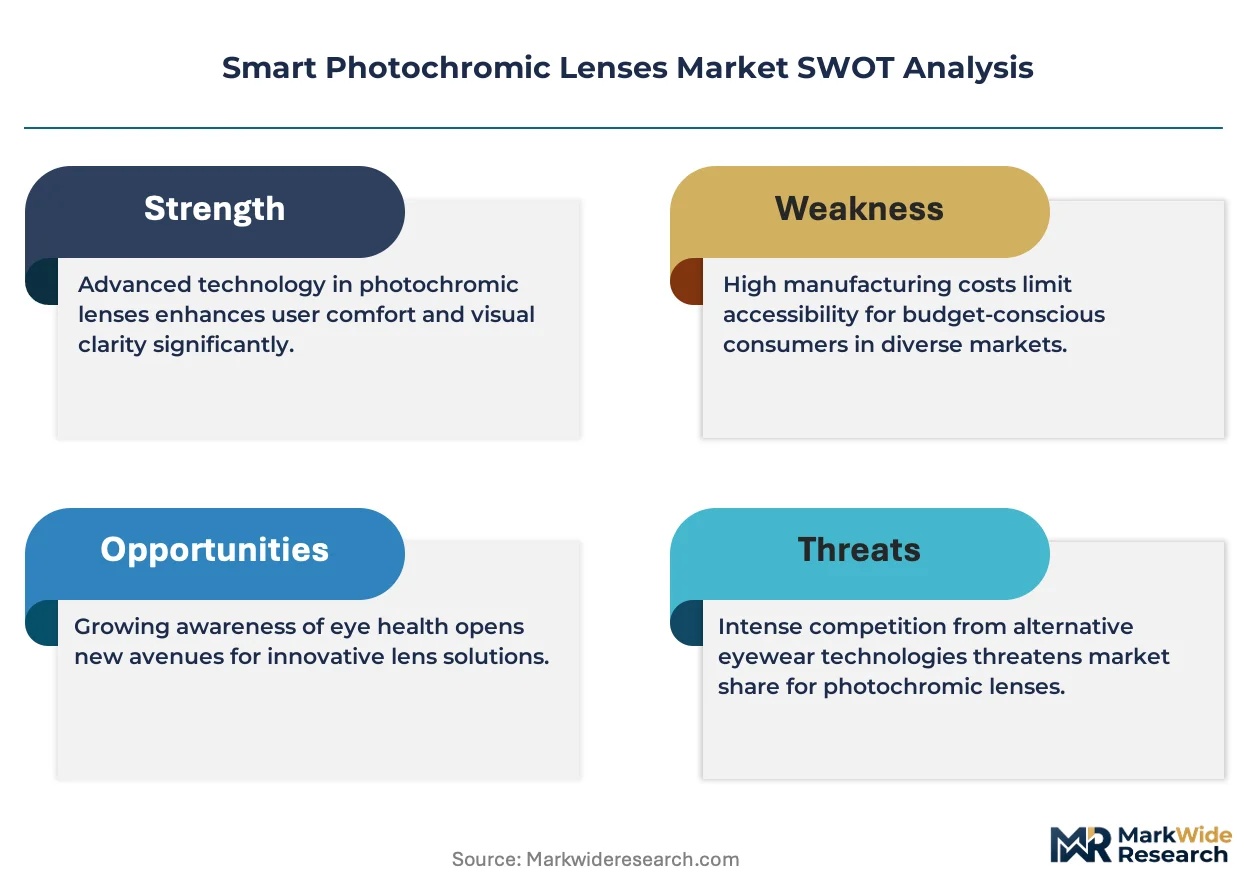
Premium-margin players sit above commodity-margin players across proprietary dye chemistry and captive retail network dimensions. The vendor base stratifies into three tiers: integrated ophthalmic conglomerates with lens-to-frame vertical control, specialized surfacing technology houses, and independent coating chemistry partners. Strategic moves concentrate on M&A for retail network expansion and technology licensing for naphthopyran formulation access.
Within the integrated conglomerate tier, EssilorLuxottica and Hoya Corporation exemplify archetypes of captive retail distribution and proprietary manufacturing depth. EssilorLuxottica leverages its Luxembourg-Italian structure to bundle smart tinting with progressive fittings across owned optical chains. Hoya Corporation anchors its Tokyo-based position through in-house surfacing technology that commands premium positioning in Asian managed vision networks. Transitions Optical occupies a distinct licensing-specialist position, representing the brand-recognition archetype through exclusive dye chemistry partnerships with independent optometrists rather than captive fabrication assets.
| Leading Market Players |
|---|
| EssilorLuxottica |
| Hoya Corporation |
| Transitions Optical |
| Carl Zeiss AG |
| Rodenstock GmbH |
| Corning Incorporated |
| Seiko Optical Products |
| Tokai Optical |
| Shamir Optical Industry |
| Others |
Pricing and Supply Chain Analysis
REACH compliance deadlines in Europe gate qualified supply and premium-tier pricing access, as ECHA restrictions on legacy silver halide precursors force lens fabricators toward naphthopyran chemistry investments that only scaled manufacturers can absorb. This regulatory moat compresses commodity margins for non-compliant independents while concentrating pricing power among certified producers serving managed vision networks.
Pricing Analysis
Adaptation speed performance anchors value-based pricing tiers across the ophthalmic lens market. Three-tier pricing structure across premium, standard, and economy levels separates sub-30-second naphthopyran systems from legacy silver halide platforms and unbranded private-label substitutes. Price differentiation hinges on ISO 8980 certification tier and freeform surfacing complexity for progressive geometries. Cost compression in the standard tier intensifies because independent optometry chains aggressively unbundle frame selection from lens consultations. School vision program administrators exhibit highest price sensitivity due to polycarbonate impact resistance mandates, while aging presbyopes in statutory insurance networks show lowest sensitivity for premium progressive fittings.
Supply Chain Analysis
Freeform surfacing technician scarcity in Germany, Japan, and the United States constrains output expansion at independent optical labs. Specialty naphthopyran dye precursors draw from Japanese and German specialty chemical houses, while polycarbonate substrate production rests on petrochemical feedstocks from South Korean and Saudi Arabian suppliers. Single-source vulnerability concentrates in legacy silver halide precursor sourcing from Chinese dye manufacturers facing ECHA export scrutiny. Distribution runs through EssilorLuxottica's captive retail network, Hoya's Asian managed vision partnerships, and Transitions Optical's independent optometrist licensing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR biocompatibility documentation requirements create a barrier-to-entry moat for players with structured quality assurance departments.
For Market Incumbents: Deploy proprietary surfacing technology licensing to independent labs seeking REACH-compliant naphthopyran access without capital retooling. Consolidate position through backward integration into specialty dye chemistry partnerships, countering the threat of private-label substitution eroding standard-tier margins. Channel control via managed vision benefit direct contracts protects volume against online platform disintermediation. For New Entrants and Emerging Players: Launch via direct-to-consumer asynchronous prescription verification platforms targeting United States telehealth regulations. Online routing for photochromic lens fulfillment represents the most penetrable channel, as independent optometrists resist bundling economics. White-space sits in pediatric polycarbonate safety eyewear for Australian school vision programs and embedded sensor convergence for digital device user segments. For Investors and Strategic Acquirers: ECHA precursor restriction announcements are the leading indicator that naphthopyran chemistry access will consolidate among integrated manufacturers. Long-term viability favors vertically positioned players with captive retail networks and in-house formulation IP rather than pure-play surfacing houses. Target acquisition archetype: independent optical labs in Germany or South Korea with nanotechnology-integrated coating workflows and established CE marking documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Naphthopyran Chemistry Licensing | REACH-compliant dye access transfers competitive advantage from manufacturing scale to formulation IP control. |
| Direct-to-Consumer Channel Expansion | Asynchronous telehealth prescription verification routes volume around traditional optometry bundling economics. |
| Embedded Sensor Convergence | Ambient light sensor integration with electrochromic overlays creates algorithmic tint tiers for prolonged digital device use. |
| EU MDR Quality Assurance Restructuring | Biocompatibility documentation capabilities separate compliant manufacturers from excluded commodity players. |
| Freeform Surfacing Technician Training | CAD/CAM operator pipeline investment addresses the vocational scarcity constraining progressive lens output. |
Research Methodology
FDA 510(k) ophthalmic device filings, ECHA REACH restriction notices, and ISO 8980 certification records formed the secondary backbone, supplemented by customs data on specialty dye precursor trade flows. Primary interviews with optical lab operations directors, managed vision benefit administrators, independent optometrists, and ophthalmic device regulatory consultants validated demand assumptions and pricing dynamics. Bottom-up triangulation across surfacing lab capacity estimates and top-down reconciliation against statutory insurance reimbursement schedules anchored volume projections.
Bottom-up modeling built from individual country-level prescription fulfillment rates, progressive lens adoption curves by age demographic, and naphthopyran chemistry migration timelines across the analysis window. Segmentation dimensions spanned vision correction complexity, material impact resistance tier, molecular activation mechanism, and channel structure. CAGRs derived from regression against aging population projections, REACH compliance deadline effects, and managed vision benefit expansion patterns in municipal employee categories.
Regulatory timeline delays, naphthopyran supply concentration disruptions, and telehealth prescription verification policy reversals are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on ECHA enforcement intensity and freeform surfacing technician training pipeline expansion. Material deviation in named triggers warrants pause and re-evaluation of volume and value trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
North America Optical Imaging Market
Optics
Middle East and Africa Optical Imaging Market
Optics
Liquid Crystal on Silicon Market
Optics
Asia-Pacific Optical Imaging Market
Optics
Germanium Lens Market
Optics
Excimer Laser Market
Optics
Fiber Optic Development Tools Market
Optics
Smart Glass Market
Optics
Anti Glare Film Market
Optics
Optical Sensing Market
Optics
Global Fiber Optic Components Market
Optics
Asia Pacific Fiber Optics Market
Optics
Residential 1080P Laser Television Projector Market
Optics
MEMS Mirrors Market
Optics
Beam Expanders Market
Optics
Photostimulation Lasers Market