
 Photostability Chamber Market | 2026-2036
Photostability Chamber Market Size, Share, and Industry Trends Forecast 2026-2036
Photostability Chamber Market Outlook
Direct distribution to pharmaceutical quality control laboratories is fragmenting as regional test equipment dealers and digital procurement platforms capture mid-size accounts. Atlas leverages its xenon arc technology leadership to sustain premium positioning among European drug manufacturers. BINDER anchors the German market through precision climate control engineering that dominates GxP-validated installations. Weiss Technik competes across Asia-Pacific with localized service networks that extend its reach beyond core European operations.
A photostability chamber is a controlled-environment testing apparatus that exposes pharmaceutical formulations, cosmetic products, and material samples to defined light spectra—typically ICH Q1B-compliant UV and visible radiation—while maintaining precise temperature and humidity parameters to evaluate degradation kinetics and shelf-life claims. LED-based chambers now capture the fastest expansion within product type segments as mercury-phase-out regulations and energy efficiency mandates reshape capital expenditure priorities. Pharmaceutical testing applications concentrate the largest revenue pool, though research and development end users generate disproportionate margin contribution through customized chamber configurations and protocol validation services.
FDA enforcement of ICH Q1B photostability data requirements for New Drug Applications directly shapes North American demand for validated chamber systems, while EMA's Q1B interpretation through the Committee for Medicinal Products for Human Use establishes parallel compliance architecture across European member states. Japan's PMDA aligns with ICH harmonization but imposes supplemental thermal cycling protocols that favor chambers with integrated climate control technology. Stakeholders must monitor divergence between regional pharmacopeial updates and ICH revision timelines when planning multi-site testing standardization and equipment procurement cycles.
Market Dynamics
LED photostability chamber technology is compressing equipment replacement cycles as mercury lamp phase-outs accelerate across pharmaceutical quality control laboratories. This hardware transition is reshaping vendor competitive positioning and procurement evaluation criteria.
Growth Catalysts
- ICH Q1B harmonization:FDA and EMA enforcement of photostability data requirements for drug submissions mandates validated chamber installations across formulation development and stability testing workflows.
- Biologics pipeline expansion:Monoclonal antibody and mRNA therapeutic developers require specialized light exposure protocols that drive demand for customized chamber configurations with precise spectral control.
- Mercury lamp bans:EU RoHS and REACH restrictions on mercury-containing equipment are forcing accelerated LED retrofits in German, French, and Swiss pharmaceutical manufacturing facilities.
Market Restraints
- Capital intensity barrier:GxP-validated photostability chambers with integrated climate control require substantial upfront investment that limits adoption among mid-size contract research organizations.
- Component supply concentration:Precision LED arrays and calibrated radiometers rely on specialized Japanese and German optical component suppliers, creating vulnerability to regional supply disruptions.
- Validation timeline friction:Installation qualification and operational qualification protocols for FDA-regulated environments extend procurement-to-deployment cycles by 6-12 months.
Strategic Opportunities
- Indian pharmaceutical expansion:CDSCO's alignment with ICH guidelines and domestic API manufacturing growth create demand for cost-optimized LED chamber systems in Hyderabad and Mumbai clusters.
- Cosmetics photostability testing:EU Cosmetics Regulation (EC) No 1223/2009 shelf-life claim requirements are extending chamber applications beyond pharmaceuticals into premium skincare formulation labs.
- Remote monitoring integration:IoT-enabled chamber telemetry is opening subscription-based service revenue streams for equipment vendors serving multi-site pharmaceutical networks.
Industry Challenges
- Metrology skill scarcity:Qualified technicians capable of radiometric calibration and spectral uniformity mapping are concentrated in established pharmaceutical regions, constraining deployment in emerging manufacturing hubs.
- Legacy protocol migration:Fluorescent-based historical data archives require cross-validation against LED spectral outputs, complicating regulatory filing continuity for generic drug sponsors.
- Multi-site standardization complexity:Corporate quality groups struggle to harmonize chamber operating procedures across facilities with divergent local regulatory interpretations of ICH Q1B.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photostability Chamber Market |
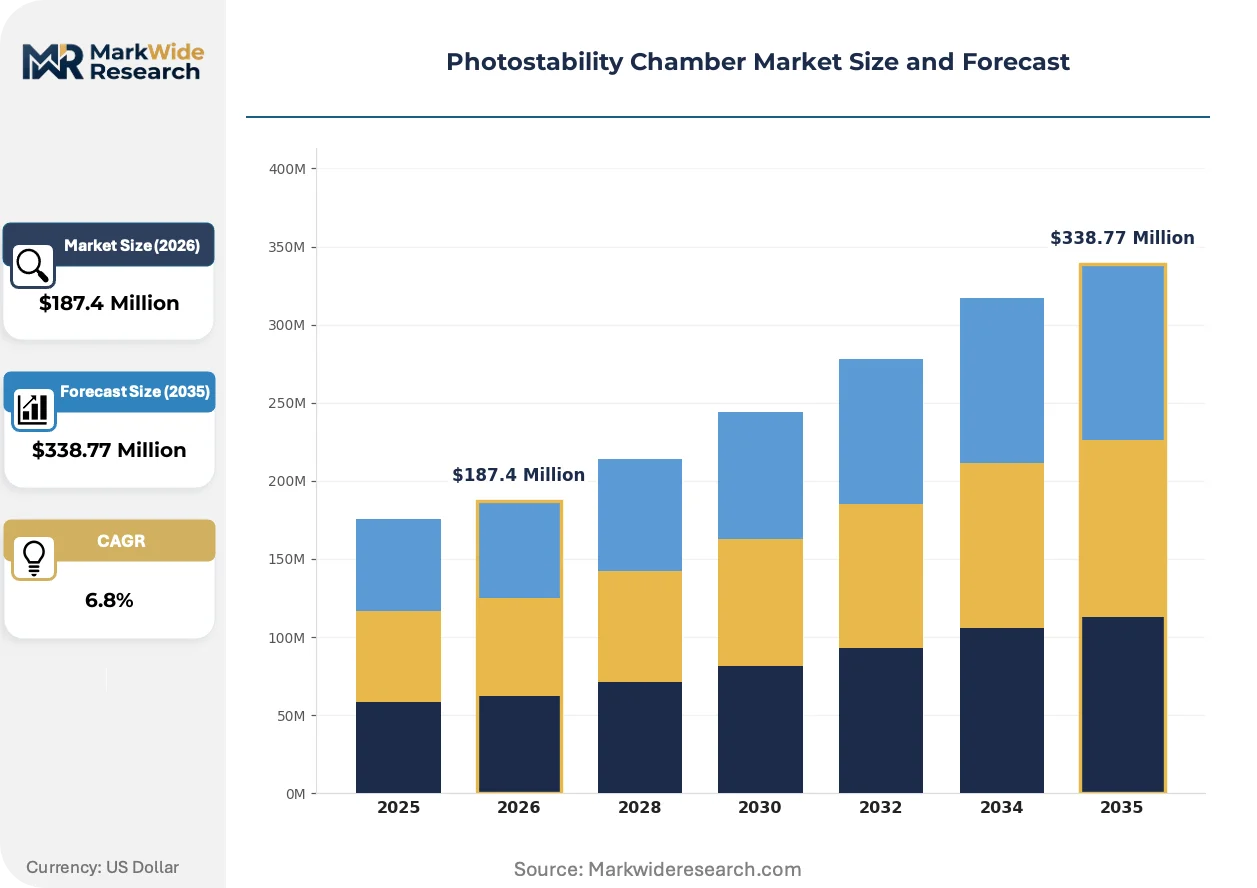
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Chambers, LED-Based Chambers, Environmental Chambers, Miniaturized Chambers Application: Pharmaceutical Testing, Cosmetic Stability Testing, Material Testing, Research & Development Technology: UV Light Source, Xenon Light Source, Fluorescent Light Source, Climate Control Technology End User: Pharmaceutical Companies, Cosmetics Manufacturers, Research Institutions, Quality Control Laboratories |
| Companies Covered | Atlas, AI SI LI (China) Test Equipment Co., Ltd, BINDER, Dycometal, POL-EKO, Weiss Technik, Bionics Scientific, XCH Biomedical, Q-Lab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photostability Chamber Market Strategic Shifts
Spectral engineering and connectivity architectures are redefining equipment value propositions as pharmaceutical laboratories prioritize data integrity and energy efficiency in capital planning cycles.
LED array technology is hybridizing with programmable spectral tuning capabilities that enable simultaneous UV-A, visible, and near-infrared exposure from a single source module. Large molecule formulation groups at biologics developers are adopting these systems to accelerate forced degradation studies. The technology is hybridizing traditional single-purpose chambers into multi-protocol platforms that compress laboratory footprint requirements and reduce capital duplication.
EMA's updated Q1B interpretation through the Committee for Medicinal Products for Human Use is tightening acceptance criteria for light source spectral distribution documentation. European generic drug manufacturers must now submit enhanced calibration certificates with marketing authorization applications. Solid oral dosage form sponsors in Germany and Italy are responding by specifying chambers with built-in spectroradiometer verification systems.
Equipment leasing and validation-as-a-service arrangements are displacing traditional capital purchase models among mid-size pharmaceutical companies. Regional test equipment dealers and digital procurement platforms are capturing accounts previously served by direct manufacturer relationships. This pattern is most visible in the United States, where contract development and manufacturing organizations prioritize operational expenditure flexibility over asset ownership.
Photostability Chamber Market Segmentation
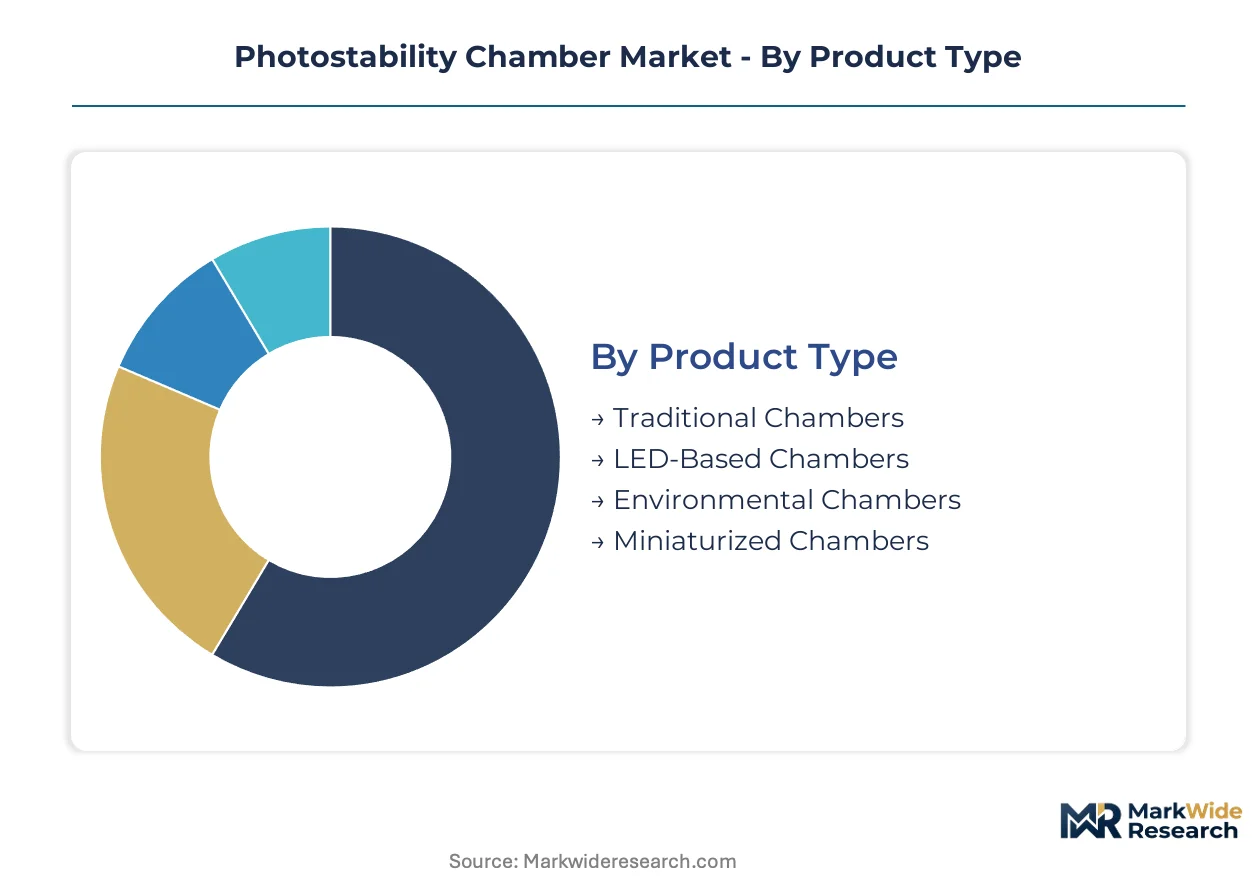
Photostability chamber procurement patterns diverge sharply across product architectures, application protocols, and end-user sophistication levels. Equipment vendors must align R&D roadmaps and service capabilities against these segment-specific technical requirements and compliance timelines.
Product Type:
Mature fluorescent-based systems now share laboratory floorspace with emerging LED architectures that promise spectral precision and regulatory alignment.
- Traditional Chambers:Fluorescent and xenon arc systems dominate legacy installations at established pharmaceutical manufacturers. European facilities in Germany and Switzerland face accelerated replacement mandates under EU RoHS mercury restrictions.
- LED-Based Chambers:Programmable spectral arrays deliver ICH Q1B-compliant UV-A and visible output with calibrated uniformity mapping. North American quality control laboratories prioritize these systems for biologics forced degradation studies where wavelength specificity drives kinetic accuracy.
- Environmental Chambers:Integrated temperature and humidity control modules address Japan PMDA supplemental thermal cycling requirements. These units command premium positioning at multi-protocol testing facilities.
- Miniaturized Chambers:Compact footprint designs serve early-stage formulation screening at contract research organizations with limited laboratory space.
Traditional chambers retain volume leadership; LED-based chambers hold the steepest expansion curve.
Application:
Cost tier stratification separates high-stakes regulatory submissions from exploratory research workflows.
- Pharmaceutical Testing:GxP-validated installations support FDA New Drug Application stability data packages. These deployments require installation qualification and operational qualification protocols that extend procurement cycles.
- Cosmetic Stability Testing:EU Cosmetics Regulation shelf-life claim verification drives adoption at premium skincare formulation laboratories in France and Italy. Protocols emphasize visible light exposure for photoallergen assessment.
- Material Testing:Polymer and coating degradation studies utilize standardized UV exposure for automotive and aerospace component qualification.
- Research & Development:Customized chamber configurations with protocol development services generate disproportionate margin contribution through spectral engineering consultation.
Pharmaceutical testing commands the largest revenue pool; cosmetic stability testing is expanding most quickly amid regulatory tightening.
Technology:
Supply concentration around precision optical components shapes vendor competitive boundaries.
- UV Light Source:Narrowband UV-A emitters at 320-400nm serve photostability protocol Option 1 specifications. Japanese optical component suppliers dominate calibrated radiometer sourcing.
- Xenon Light Source:Broadband solar simulation systems anchor weathering and accelerated aging applications at material science laboratories.
- Fluorescent Light Source:Legacy cool white and daylight fluorescent configurations face phase-out under mercury-containing equipment restrictions across European member states.
- Climate Control Technology:Integrated thermal and humidity modules enable simultaneous stress testing protocols required by Japan's PMDA and select FDA guidance documents.
Climate control technology anchors premium system configurations; UV light source architectures gain share fastest through LED substitution.
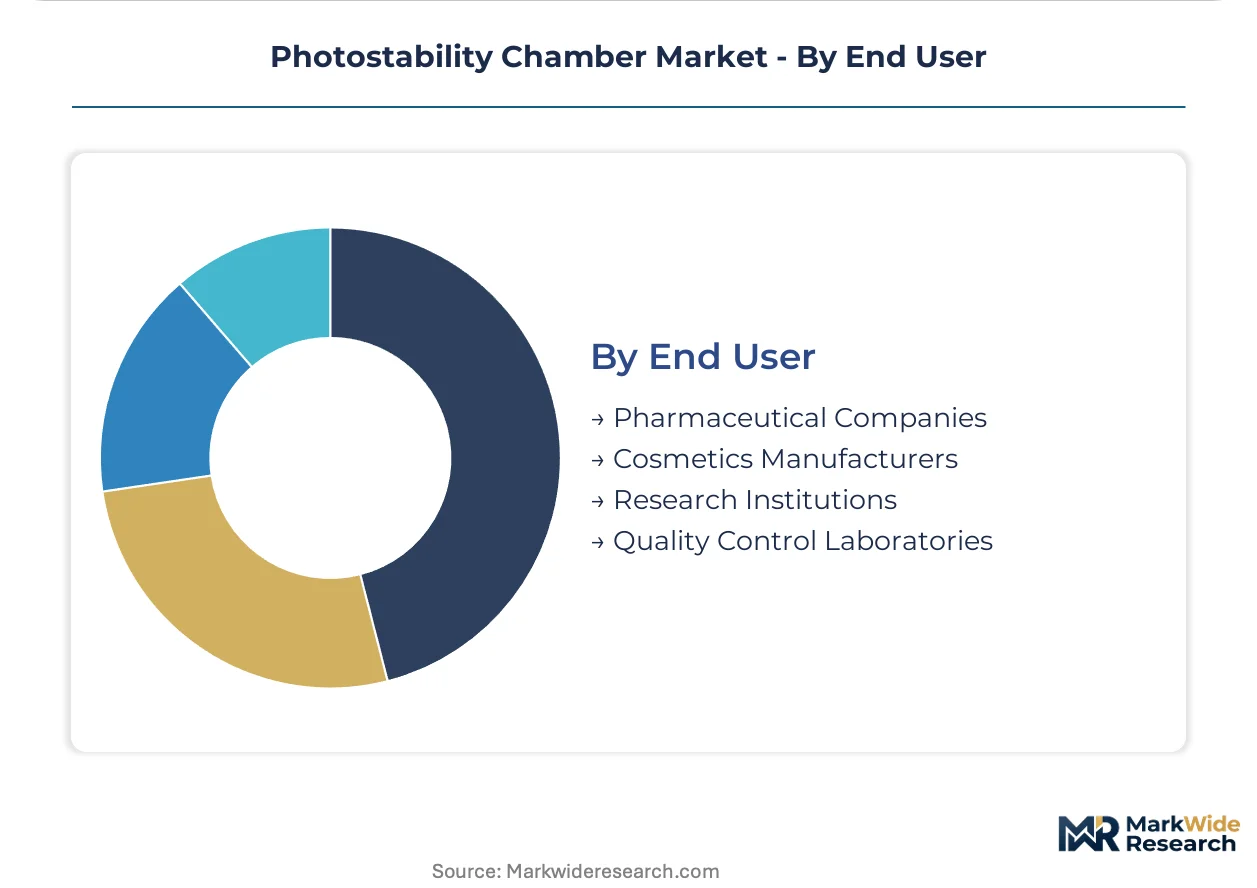
End User:
Customer type determines procurement channel preference and validation service intensity.
- Pharmaceutical Companies:Multi-site quality groups prioritize standardization across manufacturing and development facilities. These buyers specify chambers with built-in spectroradiometer verification for EMA submission requirements.
- Cosmetics Manufacturers:Premium brand owners invest in in-house stability infrastructure to protect proprietary formulation data. French and Italian luxury skincare houses lead this segment.
- Research Institutions:Academic and government laboratories favor flexible leasing arrangements and shared equipment access models.
- Quality Control Laboratories:Contract testing organizations demand rapid deployment timelines and remote monitoring capabilities to serve dispersed client portfolios.
Pharmaceutical companies dominate installed base; quality control laboratories are climbing the fastest as outsourcing trends accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical manufacturers command premium pricing for GxP-validated installations, while Indian contract research organizations negotiate aggressively on LED chamber procurement in Hyderabad and Mumbai clusters. This pricing-power asymmetry reflects divergent regulatory enforcement intensity and local manufacturing scale.
United States
FDA enforcement of ICH Q1B photostability data requirements for New Drug Applications drives chamber installations across formulation development workflows. The agency's Office of Pharmaceutical Quality maintains strict validation protocols for stability testing infrastructure. Quality control laboratories in New Jersey and Massachusetts concentrate procurement activity for biologics forced degradation studies.
Germany
EMA's Committee for Medicinal Products for Human Use tightened spectral distribution documentation requirements for generic drug marketing authorizations. EU RoHS mercury lamp bans accelerate LED retrofits across Baden-Württemberg and Bavaria pharmaceutical manufacturing corridors. BINDER anchors domestic demand through precision climate control engineering at GxP-validated installations.
Japan
PMDA alignment with ICH harmonization incorporates supplemental thermal cycling protocols favoring integrated climate control technology. METI energy efficiency mandates compress replacement cycles for fluorescent-based legacy systems. Pharmaceutical quality groups in Osaka and Tokyo prioritize chambers with built-in spectroradiometer verification for regional filing requirements.
India
CDSCO's progressive alignment with ICH guidelines and domestic API manufacturing expansion create demand for cost-optimized LED systems. The PLI scheme for pharmaceuticals incentivizes quality infrastructure investment across formulation development. Contract research organizations in Hyderabad and Mumbai clusters drive mid-tier procurement volume through digital procurement platforms.
Switzerland
Swissmedic maintains stringent interpretation of ICH Q1B validation standards for biologics and biosimilar submissions. The country's precision engineering heritage supports premium positioning for climate-integrated chamber configurations. Basel and Zurich pharmaceutical hubs concentrate demand for multi-protocol testing platforms serving global headquarters operations.
Photostability Chamber Market Competitive Environment
Precision-engineering specialists and scale-oriented fabricators split the market between premium validated installations and cost-optimized mid-tier systems. The vendor base concentrates around German climate-control heritage and Asian manufacturing scale. Three archetypes dominate: European precision-engineering houses with GxP validation expertise, Chinese scale manufacturers serving emerging market price sensitivity, and Japanese optical component suppliers anchoring LED array technology. Competitive moves center on spectral engineering partnerships and regional service network expansion to compress deployment timelines.
Among German precision-engineering houses, BINDER and Weiss Technik exemplify the climate-control heritage archetype, while Atlas represents xenon arc technology leadership in premium European positioning. Chinese fabricators including AI SI LI (China) Test Equipment Co., Ltd. occupy the scale-driven tier serving cost-optimized procurement in emerging pharmaceutical clusters. These named entities anchor industry-level commentary on archetype differentiation without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Atlas |
| AI SI LI (China) Test Equipment Co., Ltd |
| BINDER |
| Dycometal |
| POL-EKO |
| Weiss Technik |
| Bionics Scientific |
| XCH Biomedical |
| Q-Lab |
| Others |
Value Chain & Pricing Dynamics
Baden-Württemberg's precision engineering cluster concentrates LED array manufacturing capacity, granting German vendors pricing power over GxP-validated configurations while Chinese fabricators compress mid-tier quotations through scale economies in Jiangsu and Guangdong provinces.
Pricing Analysis
Configured-to-order pricing for GxP-validated chambers with integrated climate control commands substantial premiums over standard LED systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by validation documentation depth and spectral engineering complexity. Cost compression in mid-tier systems intensifies as digital procurement platforms aggregate contract research organization demand. Quality control laboratories exhibit highest price sensitivity; biologics developers prioritize spectral precision over procurement cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for precision radiometer sourcing. German and Japanese optical component suppliers anchor calibrated LED array production. Critical inputs include spectroradiometer modules, programmable driver electronics, and climate control compressors. Single-source vulnerability concentrates in Japanese calibrated sensor suppliers. Distribution runs through regional test equipment dealers and direct manufacturer relationships serving pharmaceutical quality groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward mid-size pharmaceutical companies as digital procurement platforms fragment traditional direct distribution channels and aggregate fragmented demand into volume-leverage positions.
For Market Incumbents: Pre-empt LED retrofit cycles by accelerating spectroradiometer-integrated product launches before EMA documentation requirements harden. Defend against Chinese scale manufacturers by embedding validation-as-a-service offerings that extend customer switching costs. Channel control through certified service networks remains the critical defensive lever. For New Entrants and Emerging Players: Build out cost-optimized LED chamber lines targeting Indian contract research organizations in Hyderabad and Mumbai clusters where price elasticity exceeds specification rigidity. Cosmetics stability testing applications offer the most penetrable segment given lighter validation requirements. Go-to-market execution should prioritize digital procurement platform partnerships over direct sales infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial equipment parents where photostability chamber units represent non-core revenue pools with stranded GxP validation expertise. Long-term viability hinges on spectral engineering capabilities rather than fabrication scale. Monitor LED array cost curves as the inflection signal for margin expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| LED Technology Migration | Mercury lamp phase-outs under EU RoHS accelerate replacement demand across German pharmaceutical facilities. |
| Validation-as-a-Service Launch | Subscription revenue models capture mid-tier accounts seeking operational expenditure flexibility over capital ownership. |
| Spectral Engineering Partnership | Collaborations with Japanese optical component suppliers secure calibrated radiometer supply for EMA-compliant systems. |
| Regional Service Network Expansion | Localized technical support compresses deployment timelines for quality control laboratories in emerging manufacturing hubs. |
| Remote Monitoring Integration | IoT-enabled telemetry opens recurring revenue streams serving multi-site pharmaceutical quality groups. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA guidance documents, EMA committee opinions, and ICH harmonization texts. Quality control laboratory directors, regulatory affairs specialists at pharmaceutical sponsors, and test equipment procurement managers provided operating data. Secondary sources included CDSCO circulars, METI efficiency standards, and SEC filings from diversified equipment manufacturers. Bottom-up equipment shipment analysis triangulates against top-down pharmaceutical R&D expenditure allocation.
Forecast inputs span product type migration curves, regulatory enforcement intensity by geography, and LED cost reduction trajectories. Segmentation dimensions cover light source architecture, application protocol, and end-user sophistication tier. Climate control integration rates and biologics pipeline composition inform therapeutic-specific demand projections. CAGRs derive from equipment replacement cycle compression and emerging market penetration elasticity.
Stress conditions across LED component pricing, ICH guideline revision timelines, and pharmaceutical capital expenditure cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization pace and mercury lamp phase-out enforcement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
One-Box Testers Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Test Benches Market
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Gloss Meters Market
Test and Measurement
United States Signal Generator Market
Test and Measurement
LCR Meter Market
Test and Measurement
Sound Meter Market
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
VXI Test Equipment Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
LAMEA Semiconductor Metrology and Inspection Market
Test and Measurement
Telecom Testing Equipment Market