
 3D IC and 2.5D IC Packaging Market | 2026-2036
3D IC and 2.5D IC Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
3D IC and 2.5D IC Packaging Market Intelligence
The European Union's RoHS directive, restricting hazardous substances in electronic equipment, is repositioning material selection and process development in advanced packaging. Taiwan Semiconductor Manufacturing Company, Ltd. (TSMC) leads in foundry-level integration of these packages for its clients. Amkor Technology specializes in outsourced assembly and test (OSAT) services for complex 2.5D designs. Intel Corporation leverages its in-house capabilities to produce high-performance computing processors with integrated packaging.
3D IC and 2.5D IC packaging involves stacking multiple semiconductor dies vertically or placing them side-by-side on an interposer within a single package. This architecture uses high-density interconnects, such as micro-bumps and Through-Silicon Vias (TSVs), to improve performance and reduce form factor. High Performance Computing and enterprise server applications currently drive the bulk of volume due to their stringent bandwidth requirements. The Through Silicon Via package type itself is a key segment, enabling the most advanced vertical stacking configurations.
Compliance with international standards is non-negotiable for market access. The EU's REACH regulation, US EPA rules on chemical safety, and China's GB standards collectively govern material composition in packaging. These frameworks dictate the use of lead-free solders and specific underfill materials during manufacturing. Navigating the complex interplay between thermal management requirements and evolving substance-of-concern lists is a primary strategic challenge for designers and foundries.
Market Dynamics
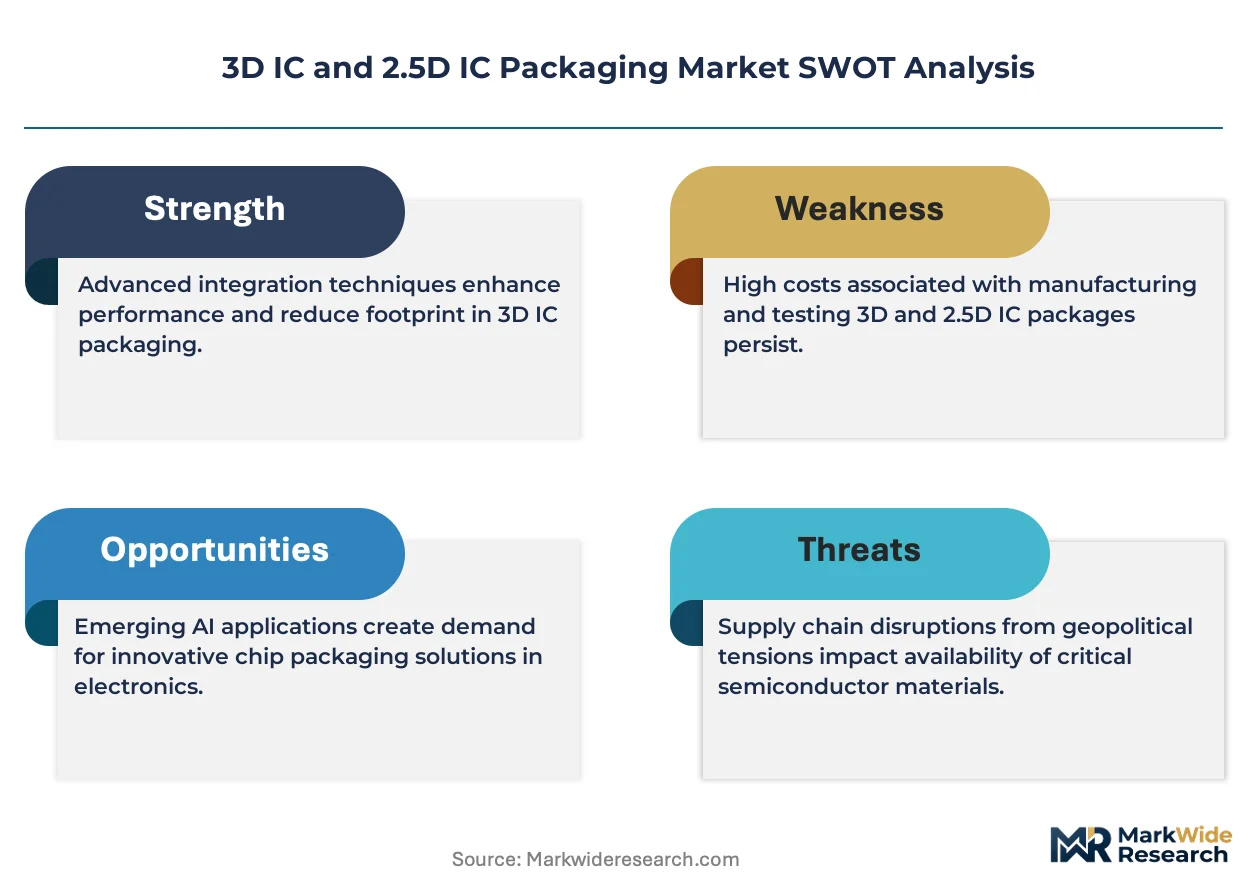
The market's primary structural force is the disaggregation of monolithic silicon into multi-die chiplet architectures. This shift maximizes performance for applications like AI but concentrates manufacturing complexity and risk within a small number of advanced foundries.
Growth Catalysts
- High-Bandwidth Memory Integration:The need to co-package HBM with logic for AI accelerators is a primary catalyst, as 2.5D packaging is the key enabling technology.
- Data Center Expansion:Insatiable bandwidth requirements in hyperscale data centers drive volume for processors and switches that rely on advanced packaging.
- Foundry Ecosystem Development:Expertise concentration in Taiwan and South Korea creates an ecosystem effect, reducing friction for fabless companies to adopt advanced designs.
Market Restraints
- High Capital Expenditure:The cost of lithography, bonding, and inspection equipment for TSV and hybrid bonding processes creates a significant barrier to entry and requires massive investment.
- Thermal Management Complexity:Stacking multiple active dies generates significant heat density, creating complex thermal challenges that can limit performance and reliability if not properly managed.
- Geopolitical Supply Risk:Over-concentration of leading-edge packaging capacity in Taiwan exposes the semiconductor supply chain to significant disruption from regional political instability.
Strategic Opportunities
- Automotive Compute Platforms:The move toward centralized domain controllers and autonomous driving systems in vehicles presents a significant opportunity for ruggedized, high-performance 2.5D packages.
- Hybrid Bonding Commercialization:The maturation of direct copper-to-copper hybrid bonding offers a path to higher interconnect density and improved power efficiency, opening new application frontiers.
- Government Industrial Policy:National initiatives like the US CHIPS Act and the European Chips Act provide incentives to onshore advanced packaging, creating new geographic hubs.
Industry Challenges
- Specialized Talent Scarcity:A global shortage of engineers skilled in co-design, thermal analysis, and signal integrity for multi-chiplet systems constrains the industry's design capacity.
- Interface Standardization Delays:The lack of a universal standard for connecting chiplets from different vendors, such as UCIe, complicates system integration and slows ecosystem development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D IC and 2.5D IC Packaging Market |
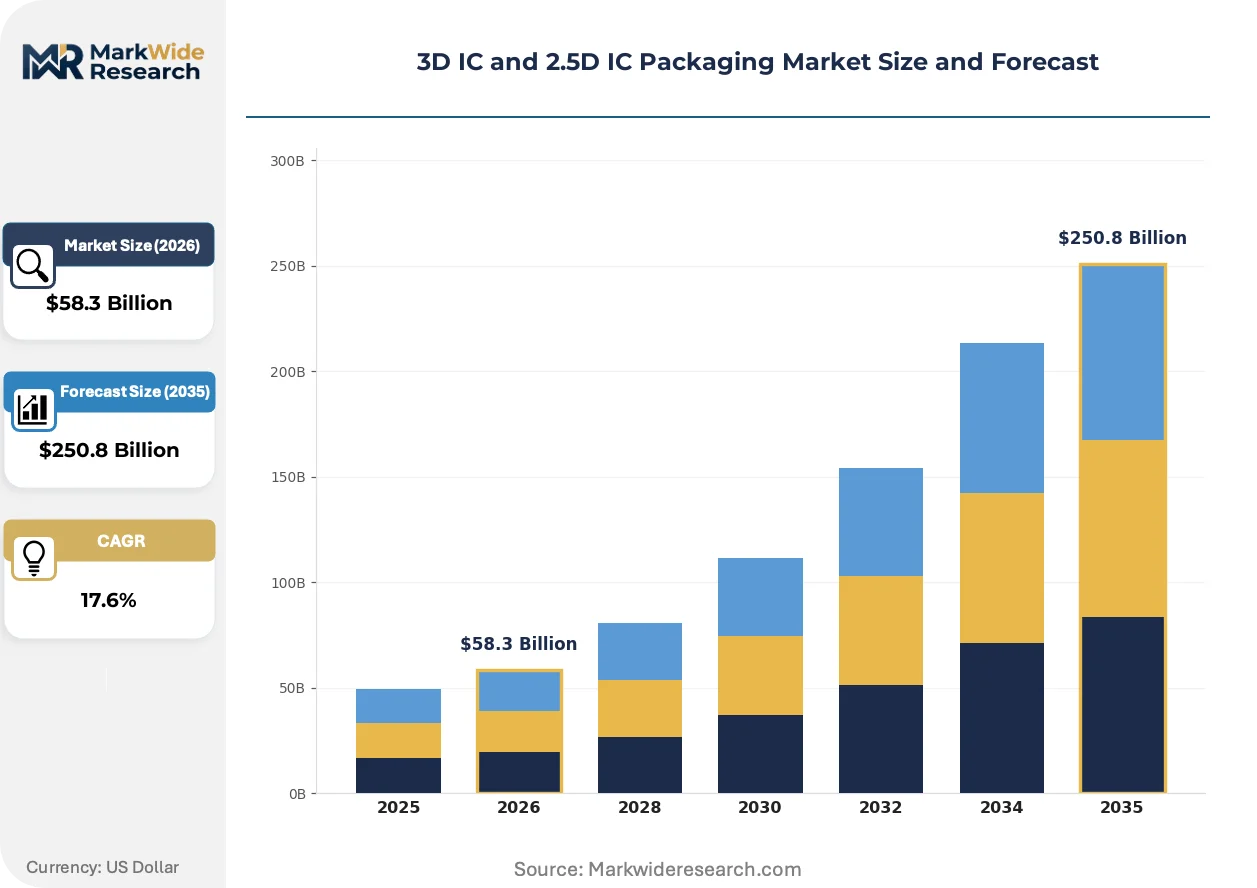
| Market Size in 2026 | $58.3 Billion |
| Market Size in 2035 | $250.8 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Package Type: Through Silicon Via, Interposer, Chip on Wafer on Substrate, Fan-Out, System in Package, Embedded Die Technology: Silicon Interposer, Organic Substrate, Glass Interposer, TSV, Wafer Level Packaging, Micro-Bump Application: High Performance Computing, Networking Equipment, Consumer Electronics, Aerospace & Defense, Telecommunications, Enterprise Servers End User: Semiconductor Foundries, IC Designers, Assembly & Test Services, OEMs, Semiconductor Equipment Providers, Electronic Manufacturing Services |
| Companies Covered | ASE Technology Holding Co., Ltd., Broadcom, Taiwan Semiconductor Manufacturing Company, Ltd. (TSMC), JCET Group Co., Ltd., Texas Instruments Inc., Samsung Electronics, Amkor Technology, Powertech Technology Inc., Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D IC and 2.5D IC Packaging Market Strategic Shifts & Innovations
Disaggregation of monolithic system-on-chips (SoCs) into heterogeneous, chiplet-based designs is the defining architectural shift. This trend places the packaging technology at the center of system performance, cost, and power considerations, fundamentally changing the semiconductor value chain.
Hybrid bonding technology provides direct copper-to-copper connections between dies, eliminating solder micro-bumps. High-performance computing and AI accelerator designers are driving its adoption for next-generation products. This bumpless interconnect method is overtaking traditional micro-bumping techniques for the most demanding applications.
European Union regulations like the Corporate Sustainability Reporting Directive (CSRD) mandate extensive disclosure of environmental impacts. This is forcing foundries and OSATs to implement detailed tracking for energy, water, and chemical usage. Semiconductor fabrication facilities in Asia supplying the EU market are most affected by these new compliance demands.
A fundamental shift towards chiplet-based design is altering silicon procurement. System architects are increasingly licensing or purchasing pre-validated dies from a diverse ecosystem of vendors instead of relying on single-source monolithic SoCs. This model is most prominent in the data center and HPC sectors.
3D IC and 2.5D IC Packaging Market Segmentation
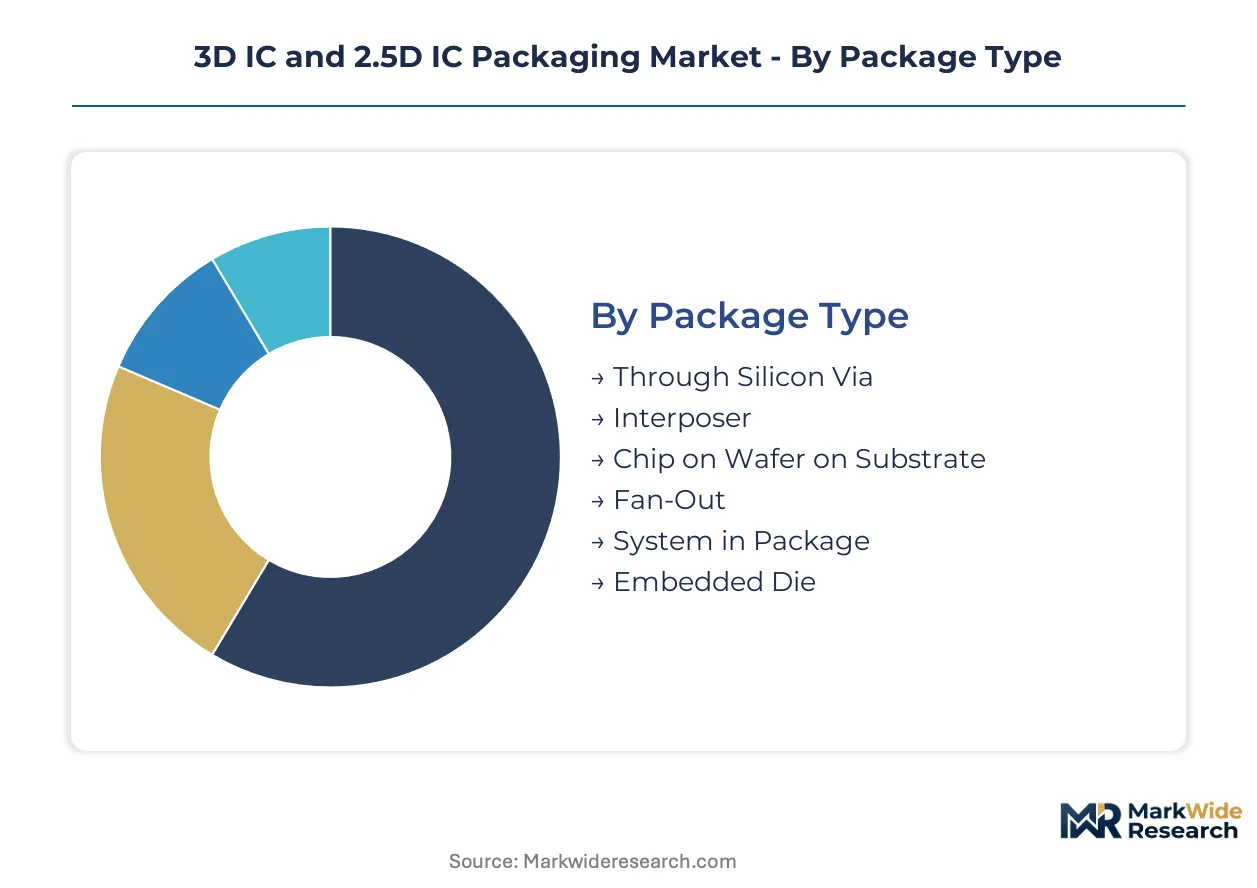
The segmentation of the 3D IC and 2.5D IC packaging market reveals critical variations in architectural approaches and target applications. Understanding these distinctions is essential for stakeholders to align product development with specific industry requirements and technological advancements.
Package Type:
Selecting the appropriate package type depends on the required performance, power efficiency, and form factor constraints for the target application.
- Through Silicon Via:This package type employs vertical electrical connections passing through the silicon die itself, enabling high-density 3D stacking of multiple active components. High-bandwidth memory (HBM) integration for AI accelerators heavily relies on TSV technology.
- Interposer:An interposer acts as an electrical interface between multiple dies and the package substrate, facilitating high-density interconnects in 2.5D configurations. Data center processors frequently utilize interposers to connect logic and memory components side-by-side.
- Chip on Wafer on Substrate:This advanced packaging method involves mounting unpackaged dies directly onto a silicon wafer, which is then attached to a substrate. It offers improved electrical performance for specialized computing needs.
- Fan-Out:Fan-out packaging extends the redistribution layer beyond the die area, allowing for more I/O connections and smaller package footprints. Mobile and consumer electronics applications increasingly adopt fan-out solutions.
- System in Package:SiP integrates multiple active and passive components from different process technologies into a single package. This approach reduces board space and simplifies system design for compact devices.
- Embedded Die:Embedded die technology integrates active semiconductor dies directly into the package substrate, enhancing miniaturization and electrical performance. Automotive and IoT devices benefit from embedded die solutions.
Volume sits with Through Silicon Via; growth tilts toward Interposer.
Technology:
The choice of underlying technology often reflects a balance between manufacturing cost, integration complexity, and desired electrical performance.
- TSV:Through-Silicon Via technology creates vertical electrical connections directly through the silicon dies, minimizing signal path lengths and enabling true 3D integration. This technology is foundational for advanced memory stacking in high-performance computing.
- Micro-Bump:Micro-bumps are tiny solder or copper interconnects used to electrically connect stacked dies or a die to an interposer, providing high I/O density. Hybrid bonding methods are now displacing traditional micro-bumps for the most demanding applications.
- Silicon Interposer:Silicon interposers provide a high-density wiring layer between chips and the package substrate, offering superior electrical performance and thermal conductivity. These are critical for 2.5D integration of logic and HBM.
- Organic Substrate:Organic substrates are cost-effective alternatives to silicon interposers, offering flexibility and good electrical performance for less demanding applications. Consumer electronics and networking equipment often employ organic substrates.
- Glass Interposer:Glass interposers offer superior electrical properties, including lower signal loss and better thermal stability, compared to organic substrates. This technology is gaining traction for high-frequency communication modules.
- Wafer Level Packaging:Wafer level packaging processes encapsulate and test individual dies while still on the wafer, offering smaller form factors and reduced manufacturing costs. This method is prevalent in mobile and wearable devices.
Wafer Level Packaging exhibits the steepest expansion trajectory, while Micro-Bump technology also gains share quickly.
Application:
Demand for advanced packaging varies significantly across different application domains, driven by specific bandwidth and latency requirements.
- High Performance Computing:This segment includes supercomputers, scientific research systems, and specialized accelerators that require extreme processing power and bandwidth. AI and machine learning workloads are primary drivers for advanced packaging in HPC.
- Enterprise Servers:Data centers and cloud infrastructure rely on enterprise servers for processing and storage, demanding high-density, low-latency, and power-efficient packaging solutions. These servers often integrate multi-die processors with HBM.
- Networking Equipment:Routers, switches, and other network infrastructure components utilize advanced packaging to handle massive data throughput and minimize latency. 2.5D and 3D packages enhance the performance of these communication systems.
- Consumer Electronics:Smartphones, wearables, and other portable devices require compact, power-efficient, and high-performance packaging to enable advanced features within small form factors. Fan-out and SiP solutions are common in this sector.
- Aerospace & Defense:Ruggedized, high-reliability advanced packages are essential for mission-critical systems in aerospace and defense applications. These systems often operate in harsh environments and demand robust interconnects.
- Telecommunications:5G infrastructure, base stations, and optical transceivers leverage advanced packaging for high-frequency signal processing and efficient power delivery. This sector demands low-loss and high-density interconnects.
High Performance Computing holds the largest market share, with Enterprise Servers also driving substantial demand.
End User:
The ecosystem of end-users reflects the specialized capabilities required at various stages of the advanced packaging value chain.
- Semiconductor Foundries:Foundries like TSMC provide the manufacturing infrastructure for fabricating wafers and integrating advanced packaging processes, including TSV and interposer fabrication. They offer comprehensive front-end and back-end integration services.
- Assembly & Test Services:Outsourced Semiconductor Assembly and Test (OSAT) providers specialize in the assembly, packaging, and testing of semiconductor devices. Amkor Technology is a prominent OSAT player in complex 2.5D designs.
- IC Designers:Integrated Circuit designers develop the blueprints for semiconductor chips and increasingly collaborate with foundries and OSATs on co-design for advanced packages. Their role involves optimizing chiplet architectures.
- OEMs:Original Equipment Manufacturers integrate packaged semiconductor devices into their final products, ranging from consumer electronics to automotive systems. They drive demand for specific package types and performance characteristics.
- Semiconductor Equipment Providers:These companies supply the specialized tools and machinery required for advanced packaging processes, including lithography, bonding, and inspection equipment. Their innovations enable new packaging capabilities.
- Electronic Manufacturing Services:EMS providers offer manufacturing and testing services for electronic components and assemblies. They integrate packaged chips onto circuit boards for various industries.
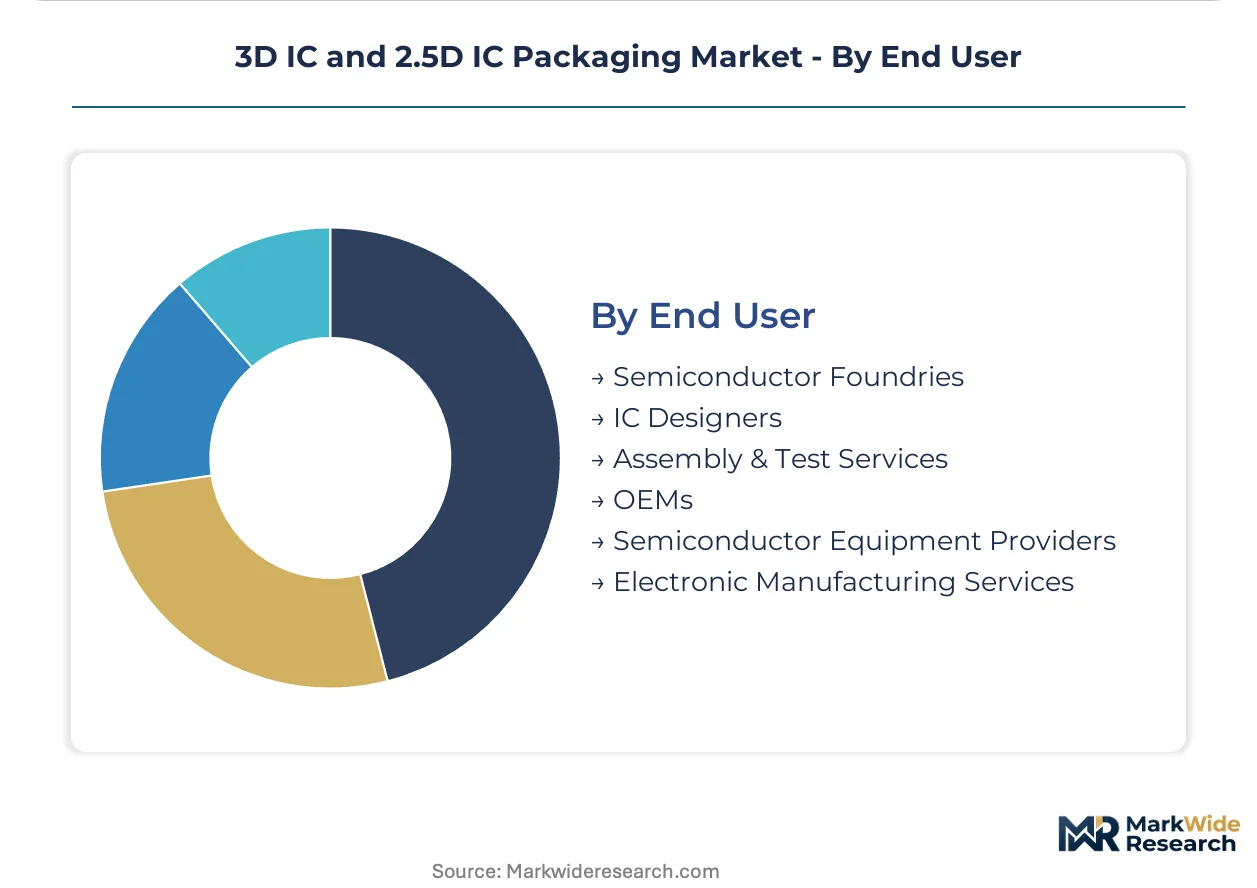
Demand concentration remains high among Semiconductor Foundries, with Assembly & Test Services also securing significant market engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global 3D IC and 2.5D IC packaging market exhibits a pronounced divide between regions driving technological innovation and those serving as manufacturing hubs. Advanced packaging production concentrates heavily in Asia, particularly in Taiwan and South Korea, while demand for high-performance applications spans worldwide markets.
Taiwan
High-performance computing and AI accelerators drive significant demand for advanced packaging in Taiwan. TSMC leads foundry-level integration, supported by government incentives. Hsinchu Science Park remains a crucial hub for semiconductor research, development, and manufacturing.
South Korea
Memory and logic integration for data centers and mobile devices fuels demand in South Korea. The Ministry of Trade, Industry and Energy supports R&D for next-generation packaging. Samsung Electronics and Powertech anchor a robust ecosystem of advanced packaging facilities in Gyeonggi Province.
United States
High-performance computing and defense applications create substantial demand for advanced packaging in the United States. The US CHIPS Act provides incentives for domestic semiconductor manufacturing and packaging. Silicon Valley and Arizona are seeing renewed investment in advanced packaging facilities and talent development.
China
Domestic demand for AI processors and telecommunications equipment stimulates the advanced packaging market in China. China's GB standards influence material selection and manufacturing, with national industrial policy encouraging self-sufficiency. Shanghai and Suzhou host numerous OSATs and design centers focusing on advanced packaging solutions.
Germany
Automotive compute platforms and industrial electronics underpin demand for robust advanced packaging in Germany. The European Chips Act strengthens the region's semiconductor value chain, including advanced packaging. Dresden, "Silicon Saxony," serves as a key microelectronics cluster for both manufacturing and R&D activities.
3D IC and 2.5D IC Packaging Market Key Industry Players
The competitive structure tilts toward integrated device manufacturers, specialized outsourced assembly and test providers, and dedicated foundries. The market exhibits a tiered landscape, with a few dominant players controlling significant advanced packaging capacity and intellectual property. These firms leverage strategic partnerships for technology co-development, engage in continuous capacity expansion to meet evolving demand, and strategically acquire smaller innovators.
Taiwan Semiconductor Manufacturing Company, Ltd. (TSMC) represents a foundry-centric archetype, providing leading-edge packaging integration for its fabless clients globally. Amkor Technology occupies a position as a specialized outsourced assembly and test (OSAT) provider, focusing on complex 2.5D designs for a broad customer base across various industries. Intel Corporation exemplifies an integrated device manufacturer, leveraging extensive in-house capabilities to produce high-performance computing processors with advanced packaging for its own product lines.
| Leading Market Players |
|---|
| ASE Technology Holding Co., Ltd. |
| Broadcom |
| Taiwan Semiconductor Manufacturing Company, Ltd. (TSMC) |
| JCET Group Co., Ltd. |
| Texas Instruments Inc. |
| Samsung Electronics |
| Amkor Technology |
| Powertech Technology Inc. |
| Intel Corporation |
| Others |
Cost & Logistics Intelligence
Silicon wafer spot prices, influenced by global demand and supply, cascade through the advanced packaging supply chain, impacting the final pricing tiers for 3D IC and 2.5D IC solutions. The concentration of advanced manufacturing capabilities in specific regions also exerts considerable influence on cost structures and market access.
Pricing Analysis
Value-based pricing, anchored to performance metrics like interconnect density and power efficiency, governs advanced packaging solutions. Price differentiation stems from the customization level required for chiplet integration and specific certification levels for automotive applications. Pricing pressure stems from the high capital expenditure required for advanced lithography and bonding equipment. High-performance computing and defense segments exhibit the least price sensitivity, while consumer electronics OEMs remain highly sensitive.
Supply Chain Analysis
Logistics and freight costs significantly influence the overall supply chain efficiency for 3D IC and 2.5D IC packaging, particularly for inter-regional shipments. Geographic supply concentration centers heavily in Taiwan, South Korea, and China for advanced packaging services. The supply chain draws from critical raw materials such as silicon wafers, specialty chemicals like underfill materials, and micro-bumps. Geopolitical instability in key manufacturing hubs presents a significant supply chain risk. Distribution runs through direct foundry-to-fabless company engagements and outsourced semiconductor assembly and test (OSAT) providers to original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European Union's RoHS directive creates a significant cost-of-compliance narrative, establishing a barrier-to-entry moat for compliant advanced packaging players.
For Market Incumbents: Cement market leadership through strategic investments in hybrid bonding research and development, particularly for copper-to-copper interconnects. Focus on expanding advanced packaging capacity in regions like the United States, leveraging incentives from initiatives such as the US CHIPS Act. Mitigate geopolitical supply risk by diversifying manufacturing footprints. Prioritize talent development programs to address the specialized engineering scarcity.
For New Entrants and Emerging Players: A significant price-point gap exists between premium advanced packaging solutions and economy-tier legacy options, creating market entry opportunities. Target specialized applications like automotive compute platforms or industrial IoT devices requiring robust packaging but potentially lower volume. Focus on developing cost-effective fan-out packaging solutions for consumer electronics. A go-to-market angle could involve offering comprehensive material compliance and thermal management expertise.
For Investors and Strategic Acquirers: The window for entry favors specialized OSATs with unique material science intellectual property and proven manufacturing capabilities. Long-term viability remains strong due to the fundamental shift towards chiplet architectures and sustained demand from high-performance computing. Monitor the adoption rate and standardization of chiplet interfaces like UCIe as a key inflection indicator for ecosystem maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in New Regions | Reduces geopolitical supply risk and diversifies manufacturing footprint for advanced packages. |
| R&D in Hybrid Bonding | Enables higher interconnect density and improved power efficiency for next-generation AI accelerators. |
| Ecosystem Partnerships | Facilitates co-design and integration of chiplets from diverse vendors, accelerating market adoption. |
| Material Compliance Investment | Ensures adherence to global regulations like EU RoHS, securing market access and reducing operational risk. |
| Talent Development Programs | Addresses the critical shortage of skilled engineers in multi-chiplet system design and thermal analysis. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a robust foundation for market sizing. Primary research involved in-depth interviews with foundry executives, OSAT engineers, IC designers, and OEM procurement leads to gather qualitative insights. This comprehensive approach employed both bottom-up estimation and top-down validation to ensure data accuracy and market representativeness.
Market granularity was modeled at the application, package type, technology, and end-user levels, alongside regional manufacturing capacity. Compound annual growth rates were derived through a regression analysis of historical trends and projected technological advancements across the analysis window. Key industry-specific forecast inputs included high-bandwidth memory demand projections and data center capital expenditure forecasts.
Inputs from SEC filings and industry reports were available through the study window; gaps in emerging technology adoption rates introduce uncertainty bands for long-term projections. Forecasts reflect assumptions regarding geopolitical stability and continued investment in semiconductor R&D. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market
Semiconductor Packaging
Global MEMS Packaging Market
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
2.5D IC Packaging Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
Chip Carrier Socket Market
Semiconductor Packaging
3D TSV Packages Market
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Epoxy Potting Market