
 Epoxy Potting Market | 2026-2036
Epoxy Potting Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Potting Market Intelligence
European specialty chemical producers are pivoting production towards high-purity, UV-curable epoxies to meet stringent electronics manufacturing standards. Henkel AG & Co. KGaA leverages its extensive portfolio to serve diverse end-markets from automotive to consumer goods. Huntsman Corporation specializes in advanced materials for demanding aerospace and industrial environments. Dow focuses on large-scale production for core industrial applications, supporting broad infrastructure and manufacturing needs.
Epoxy potting involves encapsulating electronic components or assemblies in a solid, non-conductive epoxy resin compound for protection. This process provides resistance to shock, vibration, moisture, and corrosive agents, with formulations often including fillers to enhance thermal conductivity. While standard epoxy formulations in liquid resin form dominate volume, thermal conductive epoxy types command higher margins in electronics encapsulation. Applications in renewable energy modules, particularly for solar panel junction boxes, represent a significant growth vector for the market.
Market access is governed by substance regulations like the European Union's REACH and RoHS directives, which restrict hazardous materials in electronics. In the United States, materials used in aerospace or medical devices must often comply with specific performance standards set by bodies like the FAA or FDA. Formulators must therefore balance performance requirements with an increasingly complex and fragmented global chemical compliance landscape.
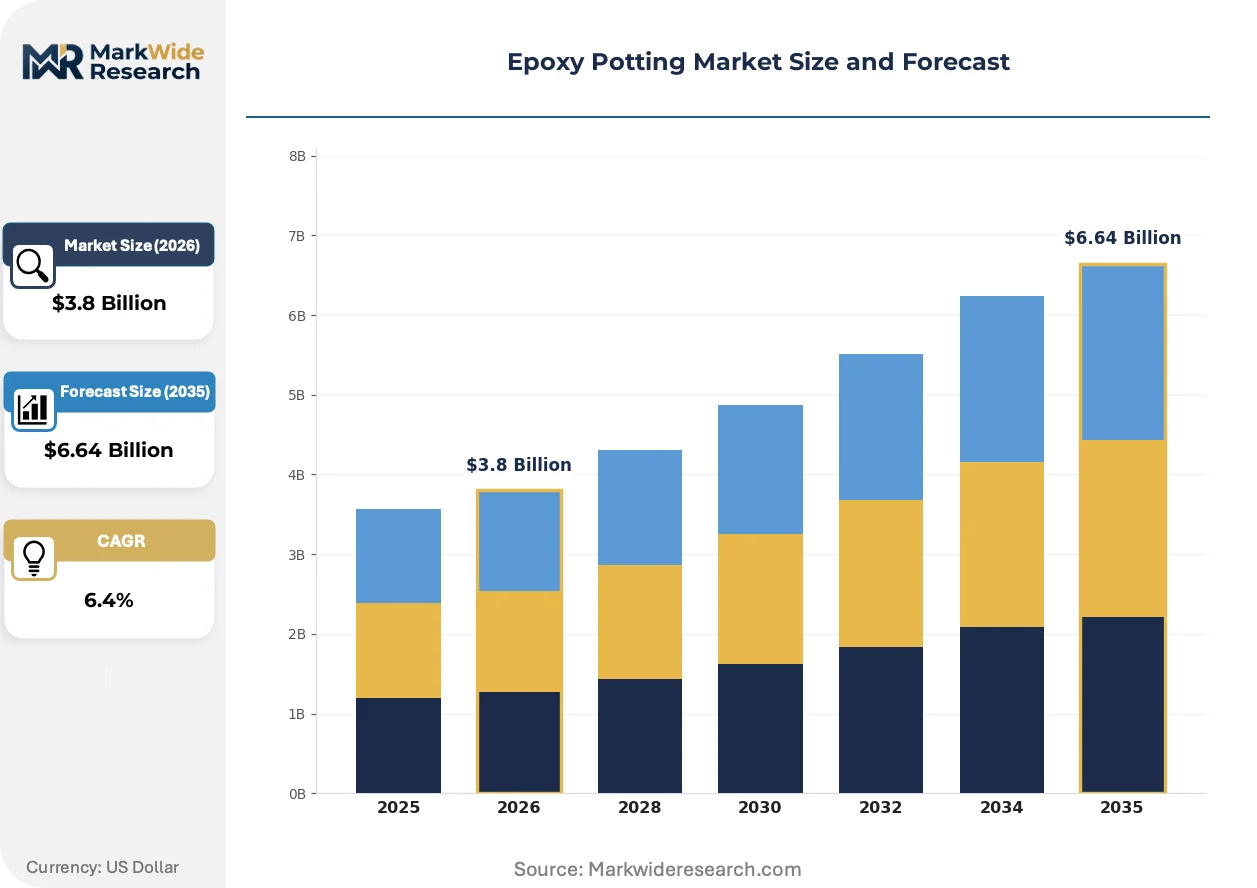
Market Dynamics
The ongoing miniaturization of electronic components is the central force shaping the epoxy potting market. This trend creates acute demand for advanced thermal management and protective encapsulation, with material requirements concentrating in semiconductor and display manufacturing centers like South Korea.
Growth Catalysts
- Electric Vehicle Production:The automotive shift to EVs drives demand for potting compounds in battery packs and chargers for thermal and vibration control.
- Renewable Energy Targets:Government mandates for solar power in the EU and China drive demand for epoxies to protect outdoor electronic components.
- Aerospace Standards:Strict FAA specifications for avionics require high-performance potting materials for protection against stress.
Market Restraints
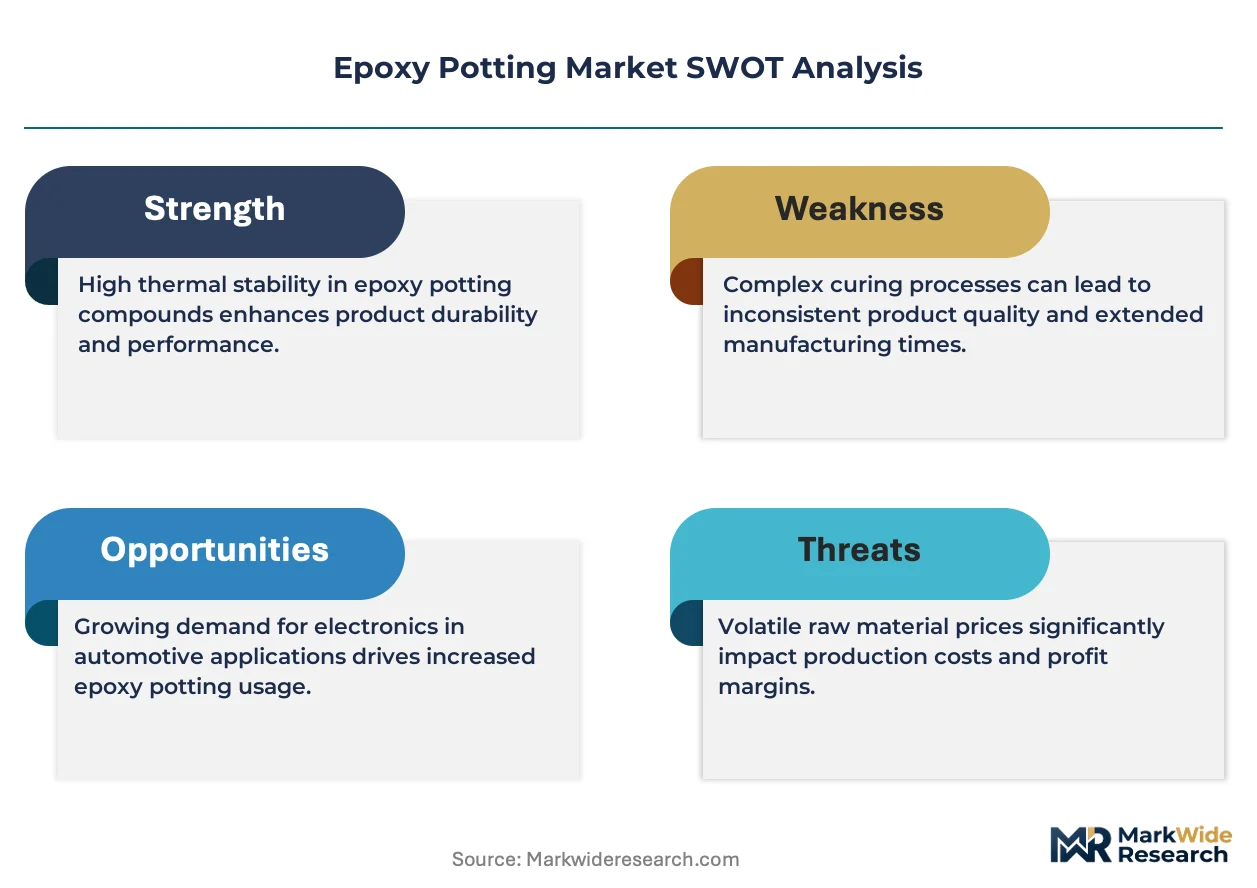
- Raw Material Volatility:Prices for key precursors like bisphenol-A are tied to volatile petrochemical markets, creating margin pressure for compound formulators.
- Production Bottlenecks:Long curing times for certain high-performance epoxies can slow throughput in high-volume electronics manufacturing operations.
- Regulatory Compliance:The EU's REACH directive imposes significant testing and documentation costs on formulators, restricting certain chemical substances.
Strategic Opportunities
- Bio-Based Formulations:Developing epoxies from renewable feedstocks meets sustainability goals and addresses regulatory pressure from bodies like ECHA.
- Fast-Curing Systems:UV-curable epoxies that cure rapidly can accelerate throughput in automated electronics and automotive assembly lines.
- Medical Device Encapsulation:Biocompatible epoxies can protect electronics in implantable devices, a high-value opportunity pending FDA or EMA approval.
Industry Challenges
- Supply Chain Complexity:Managing a global supply chain for precursors like epichlorohydrin is challenging due to geopolitical tensions and shifting trade policies affecting key producing regions.
- Formulation Expertise Scarcity:A shortage of chemical engineers skilled in developing and testing custom formulations for niche applications like aerospace electronics hinders innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Potting Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Epoxy, UV-Curable Epoxy, Thermal Conductive Epoxy, Flexible Epoxy, High Strength Epoxy Application: Electronics Encapsulation, LED Manufacturing, Aerospace Component Protection, Renewable Energy Modules, Marine Equipment End User: Consumer Electronics Makers, Aerospace Manufacturers, Energy Equipment Producers, Marine Technology Developers, Medical Device Innovators Form: Liquid Resin, Paste, Film, Preform, Powder |
| Companies Covered | Henkel AG & Co. KGaA, 3M, Dow, Huntsman Corporation, ELANTAS Beck GmbH, Dymax Corporation, MG Chemicals, H.B. Fuller Company, Master Bond Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Potting Market Strategic Shifts & Innovations
The convergence of material science and application-specific engineering is reshaping competitive positioning in the market. Formulators are moving beyond commodity products to develop highly specialized compounds that solve thermal, electrical, and mechanical challenges in tandem.
Advanced fillers like alumina and boron nitride provide high thermal conductivity while maintaining electrical insulation. Electronics manufacturers are rapidly adopting these materials for applications ranging from LED drivers to EV power modules. This development is unifying the once-separate functions of thermal management, electrical insulation, and structural protection into a single, multifunctional potting compound.
Global adoption of substance restrictions, modeled on the EU's RoHS directive, is forcing a reformulation of many legacy epoxy systems. These regulations prohibit hazardous materials like lead and certain flame retardants, compelling a shift to compliant alternatives. The consumer electronics supply chain, particularly in Asia, bears the primary burden of recertification and material validation.
A clear shift is visible from purchasing bulk resins to sourcing pre-qualified, application-specific potting systems. This change disrupts traditional distribution channels, as end-users in aerospace and medical device sectors increasingly partner directly with formulators for co-development. This procurement pattern prioritizes validated performance and supply chain traceability over pure cost.
Epoxy Potting Market Segmentation
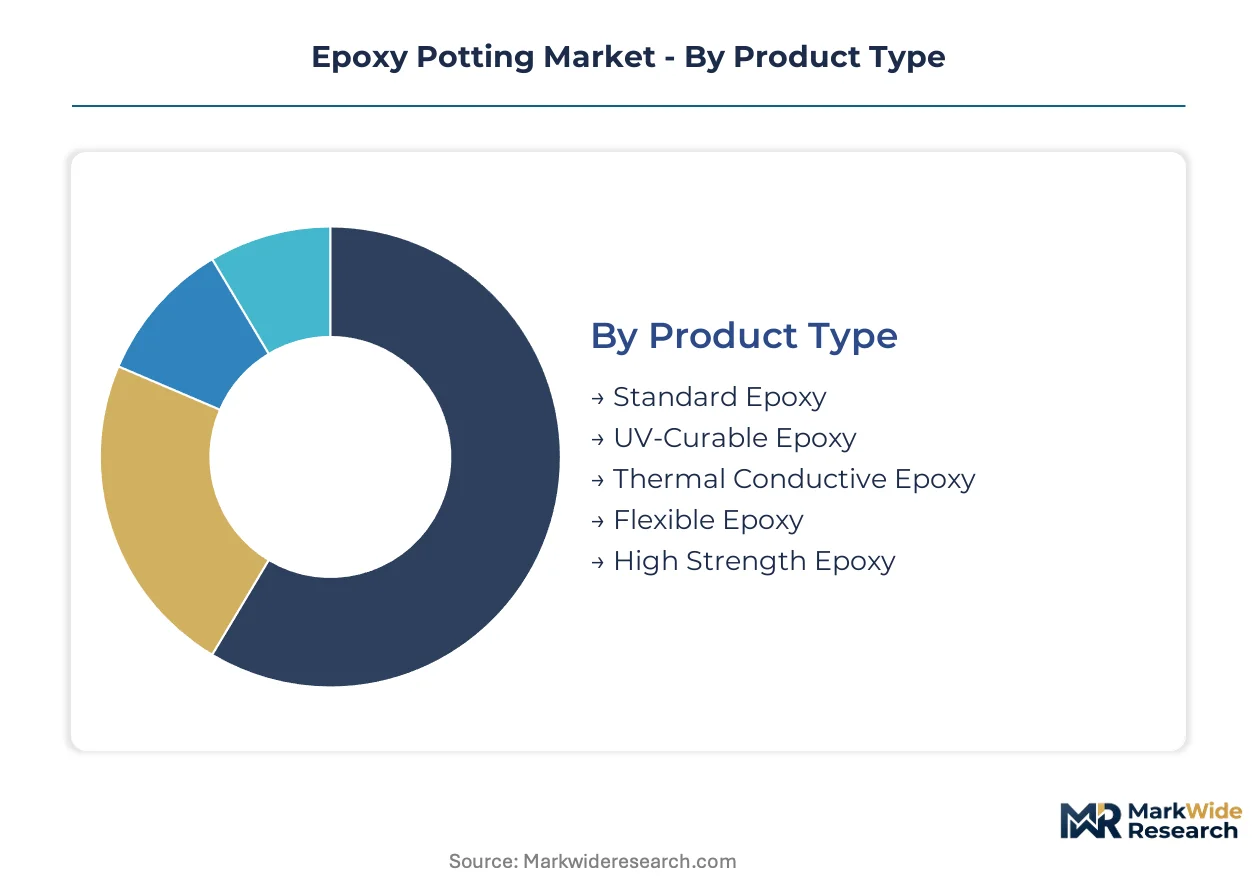
Understanding the varied segments within the epoxy potting market illuminates the specific material properties and application demands driving innovation. Each segment reflects distinct performance requirements, from electrical insulation to extreme thermal stability, directly influencing formulation choices and market value.
Product Type:
Some epoxy product types function as standalone protective coatings, while others are integral components within complex electronic assemblies.
- Thermal Conductive Epoxy:These formulations incorporate advanced fillers like alumina or boron nitride to efficiently dissipate heat from electronic components, crucial for high-power devices and miniaturized circuits in South Korea.
- UV-Curable Epoxy:These resins cure rapidly under ultraviolet light, accelerating production cycles in automated electronics and automotive assembly lines, meeting demand for high-throughput manufacturing.
- Standard Epoxy:General-purpose resins offer basic protection against moisture and vibration for less demanding applications.
- Flexible Epoxy:Designed to withstand repeated flexing or thermal cycling without cracking, often used in applications requiring stress relief.
- High Strength Epoxy:Provides superior mechanical integrity and impact resistance for structural bonding and heavy-duty encapsulation.
Standard Epoxy leads volumes today; UV-Curable Epoxy is gaining share fastest.
Application:
Epoxy potting applications range from safeguarding delicate microelectronics to fortifying large-scale industrial systems against harsh environmental factors.
- Electronics Encapsulation:This broad application involves sealing sensitive electronic components to protect against environmental damage, vibration, and thermal stress, particularly in consumer devices.
- Renewable Energy Modules:Epoxies protect critical electrical connections in solar panel junction boxes and wind turbine components, ensuring long-term reliability against outdoor elements in the EU and China.
- LED Manufacturing:Epoxies encapsulate LED chips and drivers, providing optical clarity, thermal management, and environmental protection.
- Aerospace Component Protection:High-performance epoxies shield avionics and sensors from extreme temperatures, radiation, and mechanical shock, meeting FAA standards.
- Marine Equipment:Potting compounds safeguard underwater sensors and electrical systems from saltwater corrosion and pressure.
Electronics Encapsulation represents a mature segment, while Renewable Energy Modules exhibit significant expansion.
End User:
End-users of epoxy potting materials span diverse industries, each with unique performance requirements and regulatory compliance needs.
- Consumer Electronics Makers:These manufacturers utilize epoxy potting for miniaturized components in smartphones, laptops, and wearables, demanding high-volume, cost-effective solutions.
- Medical Device Innovators:This segment requires biocompatible and sterilizable epoxies for implantable devices and diagnostic equipment, necessitating FDA or EMA approval.
- Aerospace Manufacturers:Companies producing aircraft and spacecraft components demand materials that meet stringent performance and safety specifications.
- Energy Equipment Producers:Manufacturers of solar inverters, wind turbine controls, and grid infrastructure rely on durable potting for outdoor protection.
- Marine Technology Developers:This group uses epoxies for sealing and protecting subsea electronics and navigation systems.
Consumer Electronics Makers drive substantial volume, whereas Medical Device Innovators command premium formulations.
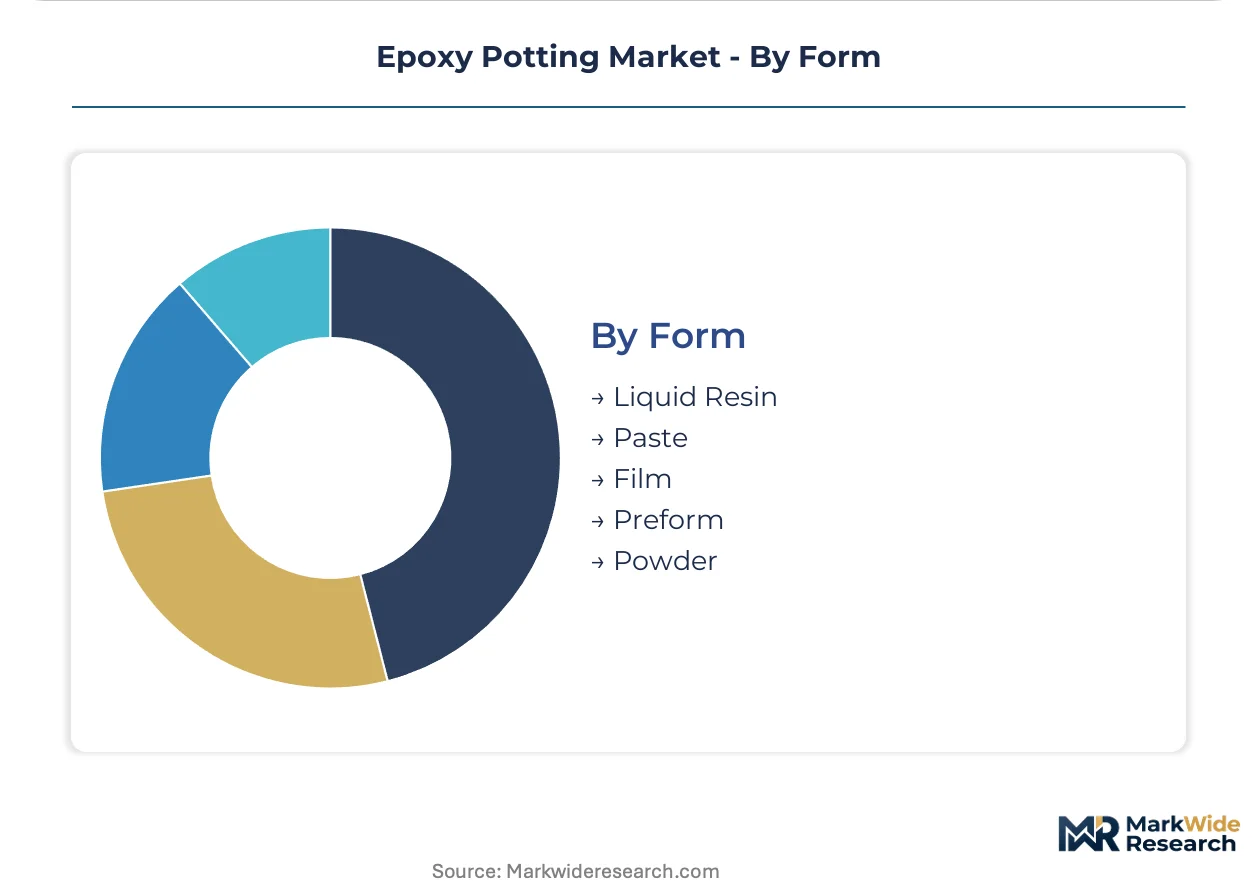
Form:
The physical form of epoxy potting compounds directly influences their ease of application and suitability for automated manufacturing processes.
- Liquid Resin:The most common form, liquid resins are poured or dispensed into molds or around components, then cured to a solid state.
- Film:Pre-formed epoxy films offer precise thickness control and eliminate dripping, ideal for automated placement in microelectronics manufacturing.
- Paste:Thicker than liquid resins, pastes are often used for dam-and-fill applications or for components that require a thixotropic material.
- Preform:Solid shapes of uncured epoxy are placed around components and then melted and cured, minimizing waste.
- Powder:Epoxy powders are typically applied via fluidized bed coating or electrostatic spraying, then melted and cured.
Liquid Resin remains the most widely adopted form, with Film and Preform offering specialized advantages for specific designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global epoxy potting market experiences shifts in production due to varying regulatory landscapes and operational costs. Producers often seek regions with favorable compliance environments or strong domestic demand for high-value applications. This dynamic influences investment and manufacturing footprints across key industrial hubs.
South Korea
Demand for thermal conductive epoxies is high in South Korea's advanced semiconductor and display manufacturing. The country's Ministry of Environment enforces strict chemical substance controls, influencing material formulation. Pyeongtaek and Gyeonggi Province house major electronics and semiconductor fabrication plants, driving specialized material consumption.
Germany
German automotive and industrial electronics sectors require high-performance potting compounds for electric vehicles and machinery. The EU's REACH directive mandates rigorous substance evaluation, impacting chemical producers in the region. Bavaria and Baden-Württemberg host significant automotive and industrial component manufacturers, focusing on precision encapsulation.
China
Renewable energy projects and vast consumer electronics production drive significant epoxy potting volumes in China. The country's dual carbon goals promote sustainable material development, including bio-based formulations. Shenzhen and the Yangtze River Delta are major manufacturing centers for electronics and solar components, utilizing diverse potting solutions.
United States
Aerospace and medical device industries in the United States demand specialized, high-reliability epoxy potting materials. The FAA and FDA impose stringent performance and biocompatibility standards for these critical applications. California and the Northeast corridor concentrate aerospace and medical technology firms, requiring advanced encapsulation expertise.
Japan
Japanese electronics and automotive manufacturers require precise epoxy formulations for miniaturized components and advanced vehicle systems. Japan's METI oversees industrial standards and chemical management, affecting material innovation. Tokyo and Nagoya are key centers for automotive and electronics R&D and production, driving demand for specialized epoxies.
Epoxy Potting Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue high-purity, fast-curing, and bio-based formulations. The market exhibits a tiered structure, with a few large chemical conglomerates alongside numerous specialized formulators. Strategic archetypes include diversified chemical giants, advanced material specialists, and niche application providers. Companies primarily engage in portfolio diversification, geographic expansion, and strategic partnerships to expand their market reach and adapt to evolving regulatory demands.
Among the diversified chemical giants, Henkel AG & Co. KGaA and Dow exemplify broad market coverage, leveraging extensive product portfolios across various end-markets. Huntsman Corporation, conversely, represents the advanced materials specialization archetype, focusing on demanding aerospace and industrial environments. These companies anchor different segments of the market by offering a range of solutions from high-volume industrial applications to highly specialized, performance-driven formulations, reflecting the varied needs of global manufacturers. Their presence underscores the market's reliance on both scale and specialized expertise for innovation and supply.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| Dow |
| Huntsman Corporation |
| ELANTAS Beck GmbH |
| Dymax Corporation |
| MG Chemicals |
| H.B. Fuller Company |
| Master Bond Inc. |
| Others |
Cost & Logistics Intelligence
Bisphenol-A pricing directly impacts the cost structure for epoxy resin producers, subsequently affecting the final price of potting compounds for electronics encapsulation. This volatility translates into variable pricing tiers for end-users like consumer electronics makers.
Pricing Analysis
Direct-to-OEM discounts characterize pricing for high-volume consumer electronics makers. The market operates on a contract-based long-term offtake model for specialized applications, with a three-tier pricing structure across premium, standard, and economy levels. Price differentiation stems from stringent certification levels like FAA standards and the degree of customization required for niche applications. Pricing softness reflects raw material volatility, particularly for standard epoxy formulations, with consumer electronics makers exhibiting the highest price sensitivity.
Supply Chain Analysis
Workforce availability in key manufacturing geographies like China and South Korea heavily influences epoxy potting production capacity. The supply chain draws heavily from precursor chemicals like bisphenol-A and epichlorohydrin, with advanced fillers like boron nitride sourced globally. Geopolitical tensions affecting key producing regions for epichlorohydrin present a structural supply chain risk. Distribution runs through direct sales channels for large automotive and electronics OEMs, while specialized distributors serve smaller medical device innovators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The epoxy potting market is transitioning into a late-cycle quality story, driven by the acute demand for advanced thermal management in miniaturized electronic components. This shift necessitates premium-grade, application-specific formulations over commodity products.
For Market Incumbents:
Hedge against regulatory shifts by proactively investing in bio-based and compliant formulation R&D, particularly for EU REACH directives. Expand production capacity for fast-curing UV-curable epoxies in manufacturing centers like South Korea to address production bottlenecks. Secure long-term supply agreements for key precursors to mitigate raw material volatility and maintain margin stability against emerging entrants.
For New Entrants and Emerging Players:
Capture high-value niches by specializing in biocompatible epoxies for medical device encapsulation, a segment commanding premium formulations. Focus on co-development partnerships with medical device innovators to achieve necessary FDA or EMA approvals. Target specialized aerospace component protection, offering high-performance materials that meet stringent FAA specifications.
For Investors and Strategic Acquirers:
Consolidation pressure builds where specialized formulation expertise meets stringent regulatory compliance, particularly for high-margin applications. The market offers long-term viability given the essential role of epoxy potting in protecting advanced electronics over the next decade. Target niche formulators possessing robust intellectual property in UV-curable or thermal conductive epoxies. A clear signal to watch is an uptick in strategic partnerships or acquisitions within specialized materials firms.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for UV-Curable Epoxies | This addresses production bottlenecks in high-volume electronics manufacturing in South Korea. |
| Joint Venture for Bio-Based Formulations | This meets sustainability goals and regulatory pressure from ECHA on European specialty chemical producers. |
| Product Launch of High-Purity Thermal Conductive Epoxies | This supports advanced thermal management requirements for EV power modules and miniaturized circuits. |
| Green Manufacturing Transition for Precursors | This ensures long-term compliance with global substance restrictions like the EU's RoHS directive. |
| Strategic Partnership with Aerospace OEMs | This facilitates co-development of high-performance potting materials meeting stringent FAA specifications for avionics. |
Research Approach
Coverage spans South Korea, Germany, China, the United States, and Japan, with primary inputs from each region. This involved in-depth interviews with R&D directors, procurement leads from consumer electronics and aerospace manufacturers, and regulatory affairs specialists. Secondary validation drew from company 10-K filings, industry association reports, and government trade statistics. A robust bottom-up and top-down triangulation approach ensured data consistency.
Granularity in modeling included detailed analysis across product type, application, end-user, form, and regional production hubs. Compound Annual Growth Rates were derived from historical trends and future projections across the analysis window. Industry-specific forecast inputs included electronic component miniaturization rates, electric vehicle production forecasts, and government renewable energy mandates.
Raw material price volatility, geopolitical supply chain disruptions, and evolving substance regulations are the dominant revision risks for this market. Forecasts reflect assumptions documented based on current industry dynamics. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
Quad-Flat-No-Lead Packaging (QFN) Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
2.5D IC Packaging Market
Semiconductor Packaging
ESD Stackable Boxes Market
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
Global Semiconductor Equipment Packaging and Test Market
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market