
 System in Package (Sip) Technology Market | 2026-2036
System in Package (Sip) Technology Market Size, Share, and Industry Trends Forecast 2026-2036
System in Package (Sip) Technology Market Intelligence
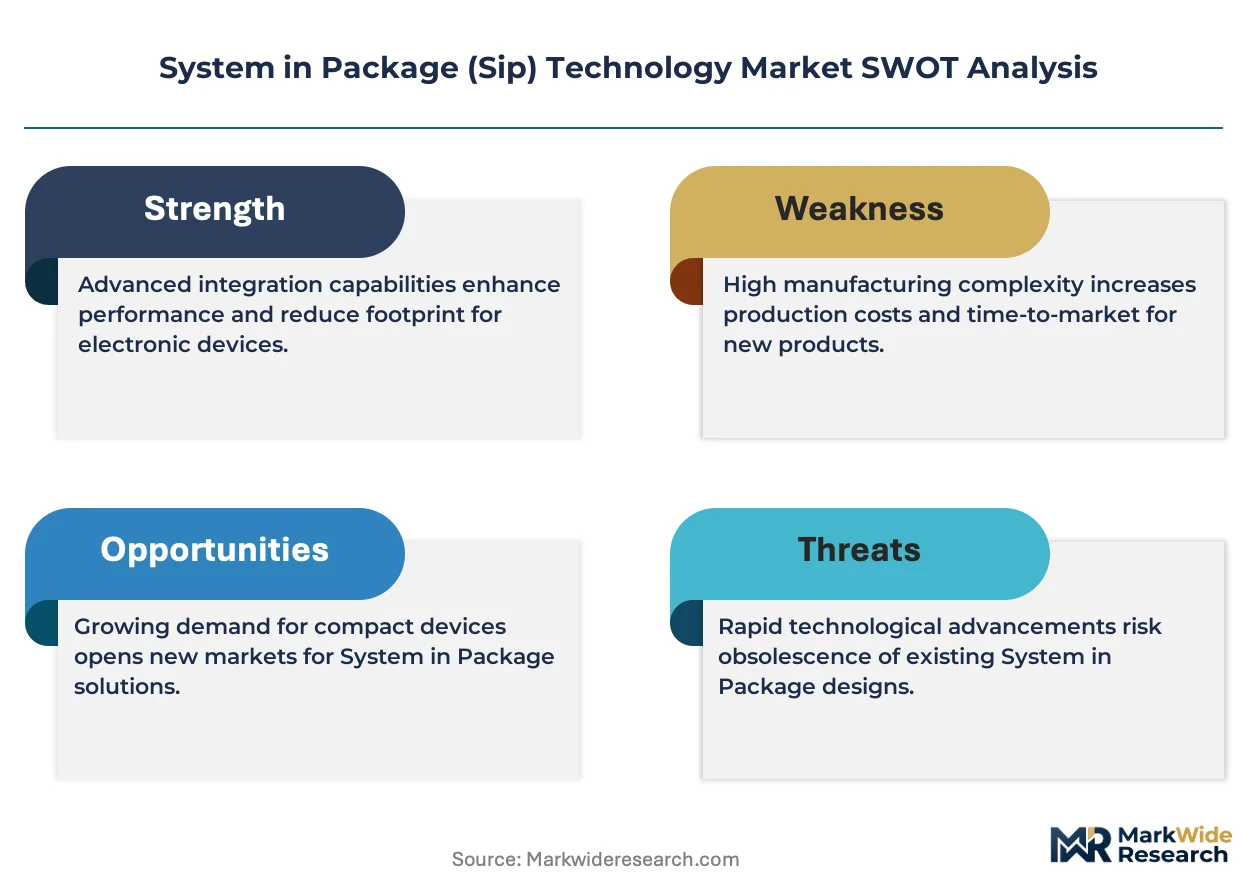
The transition from monolithic system-on-chip (SoC) designs to heterogeneous integration using chiplets is reconfiguring the semiconductor packaging landscape. ASE Group leverages its scale in advanced packaging to serve diverse high-volume markets. Samsung Electronics sustains its leadership through captive supply for its memory and mobile divisions. Amkor Technology competes by offering specialized RF and power management SiP solutions to fabless semiconductor firms.
System in Package (SiP) technology integrates multiple active electronic components and passive devices into a single compact module. Utilizing processes like flip-chip or 3D IC stacking on a common substrate, it functions as a complete system or subsystem, reducing latency and footprint. RF SIP and Power Management SIP modules command premium pricing due to design complexity in telecommunications and automotive electronics. Fan-Out technology is displacing older methods, offering superior I/O density for high-end applications.
Product reliability and material composition are governed by standards such as the EU's RoHS and REACH directives, which restrict hazardous substances. In parallel, China's GB standards and US EPA regulations on electronic waste influence material selection and end-of-life management. Vendor selection increasingly depends on demonstrated capability in advanced packaging technologies and compliance with evolving environmental mandates.
Market Dynamics
The semiconductor industry's structural pivot from monolithic chip design to heterogeneous integration via chiplets is the central force defining the System in Package market. This shift elevates packaging from a final assembly step to a critical enabler of system performance and miniaturization.
Growth Catalysts
- Automotive Electronics Integration:The proliferation of advanced driver-assistance systems (ADAS) and sophisticated in-vehicle infotainment (IVI) platforms requires compact, powerful, and reliable electronic modules, directly spurring SiP adoption.
- Telecommunications Infrastructure:Demand for low-latency, high-frequency RF SiP modules is accelerating with the global build-out of 5G and forthcoming 6G networks, which rely on dense antenna arrays and signal processors.
- OSAT Ecosystem Concentration:The world-leading outsourced assembly and test (OSAT) infrastructure, particularly in Taiwan, provides the scale, expertise, and capital investment necessary to produce advanced SiP modules in high volume.
Market Restraints
- High Design Complexity:The engineering and validation costs for complex, multi-die SiPs are substantial, creating a high barrier to entry for smaller firms and limiting adoption to high-volume or high-margin applications.
- Thermal Management:Dissipating heat effectively from densely packed 3D and 2.5D SiP configurations remains a significant technical hurdle, potentially throttling performance and impacting long-term reliability.
- Substrate Supply Bottlenecks:The supply chain for advanced substrates, such as those with fine-pitch lines and spaces required for high-density interconnects, is concentrated among a few suppliers, posing a risk of shortages and price volatility.
Strategic Opportunities
- Medical Technology Miniaturization:Significant opportunities exist in developing ultra-compact SiP modules for medical wearables, diagnostic sensors, and implantable devices, where size, power efficiency, and reliability are paramount.
- Photonics Integration:The convergence of silicon photonics and electronics within a single SiP offers a pathway to overcome data bottlenecks in AI accelerators and data center switches, creating a new class of high-performance components.
- Emerging Packaging Hubs:Government incentives, such as India's PLI scheme for semiconductors, present opportunities for establishing new SiP design and assembly capabilities outside of traditional East Asian hubs, diversifying the supply chain.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of engineers with expertise in RF design, power management, and advanced packaging technologies constrains the pace of innovation and product development across the industry.
- Interconnect Standardization:The lack of a universally adopted standard for chiplet-to-chiplet interconnects creates integration friction and vendor lock-in, slowing the development of a truly open, multi-vendor chiplet ecosystem.
- Material Compliance and Traceability:Verifying that every component and material within a complex SiP complies with evolving environmental regulations, like the EU's REACH directive, adds significant logistical overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | System in Package (Sip) Technology Market |
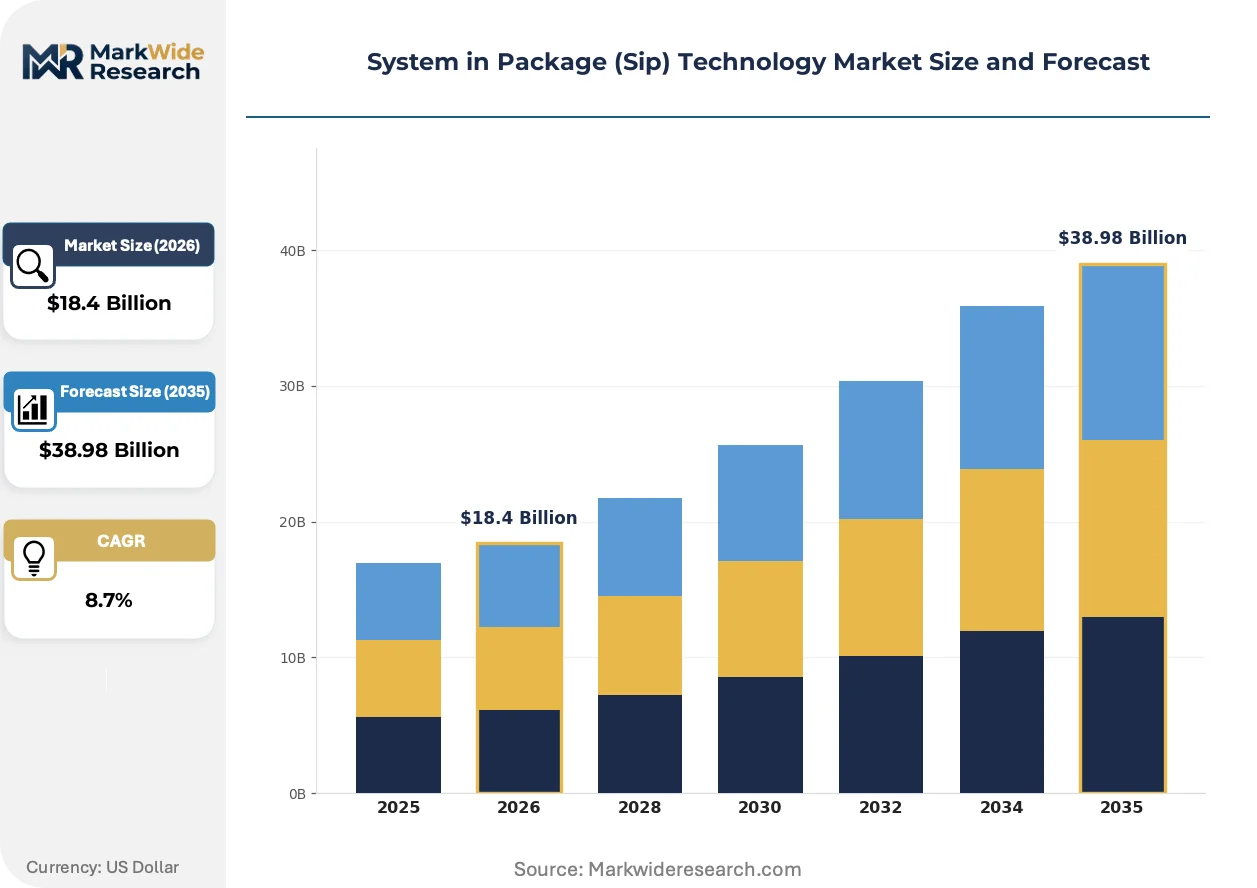
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 3D IC, Fan-Out, Flip-Chip, Wire Bonding, Embedded Die Product Type: Memory SIP, Logic SIP, Power Management SIP, RF SIP, Sensor SIP Application: Consumer Electronics, Aerospace & Defense, Telecommunications, Wearable Devices, Automotive Electronics End User: OEMs, Semiconductor Foundries, Electronic Manufacturing Services, Tier-1 Suppliers |
| Companies Covered | Samsung Electronics, Amkor Technology, ASE Group, ChipMOS Technologies, JCET Group, Texas Instruments, Renesas Electronics Corporation, Powertech Technology, SPIL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
System in Package (Sip) Technology Market Strategic Shifts & Innovations
Technological evolution is moving packaging from a protective housing to a core performance-defining element. This pivot emphasizes co-design of chips and packages, with innovations focused on increasing interconnect density, improving thermal performance, and integrating diverse functionalities into a single module.
Fan-Out Packaging for Higher I/O Density
Advanced Fan-Out Wafer-Level Packaging (FOWLP) provides a method for achieving higher I/O density and improved electrical performance. High-performance computing (HPC) and artificial intelligence sectors are rapidly adopting this technology for complex processors and accelerators. By enabling direct die-to-die connections without a traditional substrate, FOWLP is virtualizing a key component layer, thereby compressing the signal path and reducing latency.
RoHS and Material Composition Mandates
The European Union's Restriction of Hazardous Substances (RoHS) directive continues to influence material science in semiconductor packaging. Its mandates compel the industry to use lead-free solders and halogen-free substrates and encapsulants. This shift most directly affects suppliers to the automotive and consumer electronics verticals, who must invest in material re-qualification and process validation to maintain market access.
Rise of Multi-Vendor Chiplet Ecosystems
A notable behavioral shift is occurring as system architects move away from monolithic, single-vendor SoCs. They are increasingly designing custom SiPs by sourcing discrete chiplets, such as I/O, memory, and compute dies, from multiple specialized vendors. This trend is most prominent within the data center and server markets, where hyperscalers and enterprise hardware firms seek to optimize performance and cost by building bespoke silicon solutions.
System in Package (Sip) Technology Market Segmentation
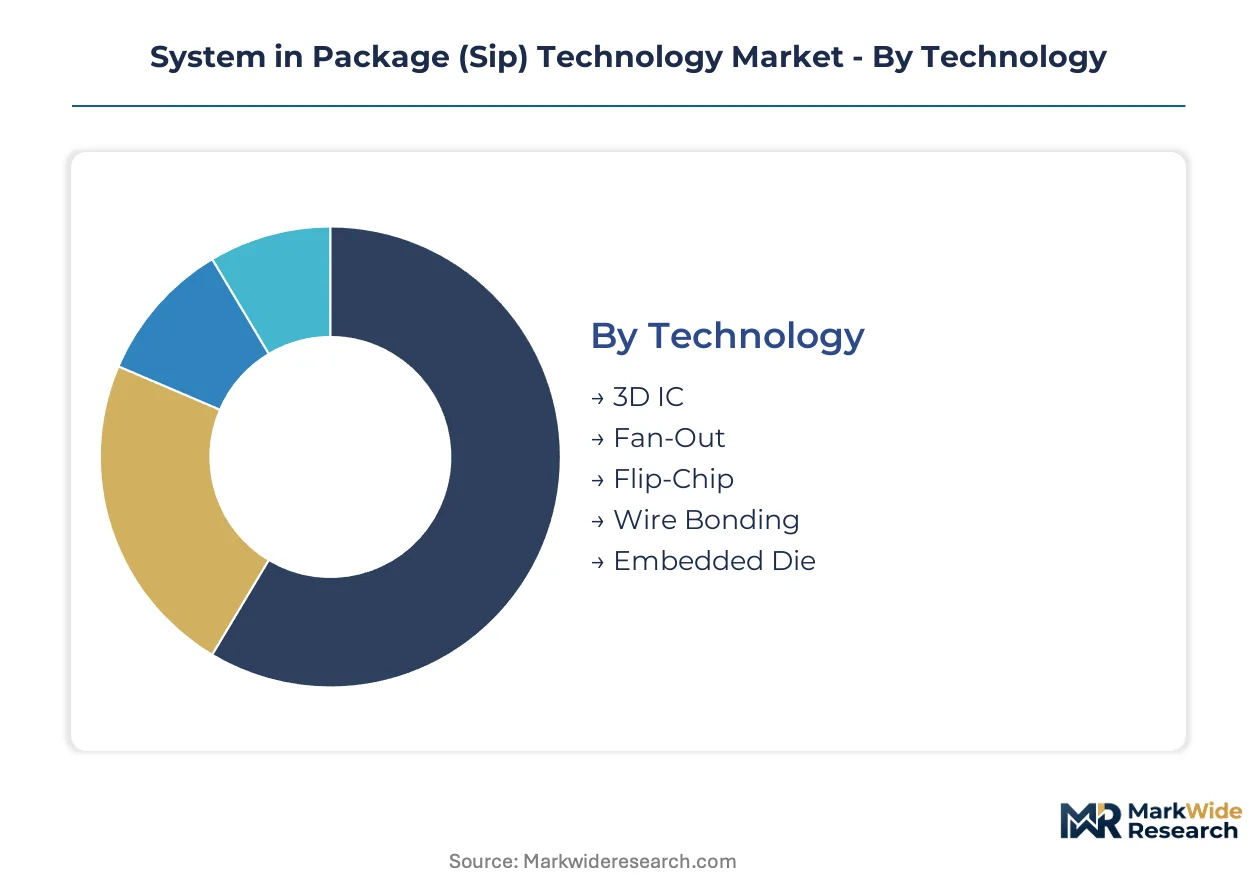
The System in Package (SiP) technology market exhibits diverse segmentation, reflecting its broad applicability across various electronic systems. Understanding these distinct segments provides clarity on technological preferences, product functionalities, and the specific end-use environments driving demand concentration. This granular view highlights areas of innovation and market concentration.
Technology:
SiP technologies span a spectrum of integration methods, each optimized for specific performance, density, and cost requirements across various electronic applications.
- Fan-Out:This advanced packaging method achieves higher I/O density and improved electrical performance by directly connecting dies without a traditional substrate. High-performance computing and artificial intelligence sectors are rapidly adopting Fan-Out technology for complex processors and accelerators.
- 3D IC:Three-dimensional integrated circuits stack multiple active electronic components vertically, interconnected through through-silicon vias (TSVs) or micro-bumps. This stacking reduces latency and footprint, driving demand in memory and high-bandwidth applications within data centers.
- Wire Bonding:Wire bonding connects the semiconductor die to the package substrate using fine wires, representing a mature and cost-effective packaging solution. This method remains prevalent for lower-cost and lower-performance SiP modules.
- Flip-Chip:Flip-chip technology connects integrated circuits directly to a substrate using solder bumps, offering superior electrical performance and thermal dissipation. It is widely used in microprocessors and graphics processing units.
- Embedded Die:Embedded die technology integrates active semiconductor components directly into the package substrate, enhancing miniaturization and reducing interconnect lengths. This approach finds application in compact modules for mobile and wearable devices.
Established volume favors Wire Bonding; emerging adoption favors Fan-Out.
Product Type:
SiP product types are differentiated by their primary functional block, catering to specialized application requirements across diverse electronic systems.
- RF SIP:Radio Frequency System in Package modules integrate multiple RF components, such as transceivers, filters, and power amplifiers, into a single compact unit. Demand is accelerating with the global build-out of 5G and forthcoming 6G networks, which rely on dense antenna arrays and signal processors.
- Power Management SIP:These SiP modules combine power management integrated circuits, inductors, and capacitors to regulate and distribute power efficiently within a system. Power Management SiP modules command premium pricing due to design complexity in automotive electronics and industrial applications.
- Memory SIP:Memory SiP integrates different types of memory with logic or other components into a single package. This product type is critical for high-density storage solutions in mobile devices and servers.
- Logic SIP:Logic SiP modules combine various logic functions, such as microcontrollers or digital signal processors, with supporting components. These modules provide complete processing capabilities for embedded systems and consumer electronics.
- Sensor SIP:Sensor SiP integrates various sensor types with processing and communication capabilities. Wearable devices and IoT applications drive demand for compact and low-power sensor SiPs.
RF SIP and Power Management SIP collectively influence a substantial portion of the market's value.
Application:
The application segments delineate the primary industries leveraging SiP technology, each driven by unique performance and form factor demands.
- Automotive Electronics:This segment includes SiP modules for advanced driver-assistance systems (ADAS), infotainment, and engine control units, requiring high reliability and compact form factors. The proliferation of sophisticated in-vehicle platforms directly spurs SiP adoption in this sector.
- Telecommunications:SiP use in telecommunications encompasses RF front-end modules, base station components, and network infrastructure, demanding high-frequency performance and low latency. The global build-out of 5G and 6G networks drives significant demand for these SiP solutions.
- Consumer Electronics:SiP technology is vital for miniaturization in smartphones, tablets, and smart home devices, integrating multiple functions into compact packages. This segment values cost-effectiveness and high-volume manufacturing capabilities.
- Wearable Devices:Ultra-compact SiP modules enable the small form factors and power efficiency required for smartwatches, fitness trackers, and hearables. Size, power efficiency, and reliability are paramount for these devices.
- Aerospace & Defense:This application segment utilizes SiP for high-reliability, ruggedized systems in avionics, missile guidance, and secure communication devices. Stringent environmental and performance specifications characterize demand in this sector.
Automotive Electronics and Telecommunications are experiencing the steepest expansion trajectory.
End User:
End-user segments reflect the various entities that integrate or utilize SiP products within the broader semiconductor and electronics value chain.
- OEMs:Original Equipment Manufacturers directly integrate SiP modules into their final products, such as smartphones, automotive systems, or industrial equipment. OEMs drive design specifications and volume demand for customized SiP solutions.
- Semiconductor Foundries:These entities fabricate the integrated circuits and often provide advanced packaging services, including SiP assembly, for fabless semiconductor companies. Foundries are critical partners in the production of complex SiP modules.
- Electronic Manufacturing Services:EMS providers offer manufacturing and assembly services for electronic components and systems, including the integration of SiP modules into larger assemblies. They support diverse industries with scalable production capabilities.
- Tier-1 Suppliers:In industries like automotive, Tier-1 suppliers develop and provide subsystems and components directly to OEMs. These suppliers play a crucial role in the automotive supply chain for complex electronic systems.
OEMs hold significant strategic importance by defining product requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-volume consumer electronics manufacturers in East Asia drive significant demand for System in Package technology. These companies require compact, high-performance modules for their devices. The region's robust semiconductor ecosystem supports this advanced packaging trend.
Taiwan
The country's world-leading semiconductor foundry and outsourced assembly and test (OSAT) ecosystem fuels SiP adoption. Taiwan's government supports advanced packaging through initiatives like the "5+2 Industrial Innovation Plan". Hsinchu Science Park remains a hub for SiP development and high-volume manufacturing.
United States
Advanced research and development in high-performance computing and AI accelerators stimulate SiP demand. The US CHIPS Act provides significant incentives for domestic semiconductor manufacturing and packaging. Silicon Valley and Austin serve as critical centers for SiP design and innovation.
China
Demand for sophisticated consumer electronics and 5G telecommunications infrastructure drives SiP integration. China's GB standards influence material selection and manufacturing processes for electronic components. Shenzhen and Shanghai host extensive electronics manufacturing clusters leveraging SiP technology.
South Korea
Innovation in memory solutions and mobile device miniaturization propels SiP market expansion. The Ministry of Trade, Industry and Energy supports semiconductor R&D and advanced packaging initiatives. The Gyeonggi Province region concentrates major SiP manufacturing and design facilities.
Germany
Automotive electronics integration, particularly for ADAS and infotainment, creates strong SiP demand. European Union RoHS and REACH directives mandate specific material compositions for electronic modules. Dresden and Munich are key centers for automotive and industrial SiP applications.
System in Package (Sip) Technology Market Key Industry Players
Channel-controlling players compete with product-specialist players across the System in Package market. The industry structure is tiered, with large integrated device manufacturers operating alongside specialized outsourced assembly and test providers. Key archetypes include vertically integrated electronics giants, dedicated advanced packaging service providers, and niche solution developers focusing on specific application areas. Companies pursue strategic partnerships to co-develop new technologies and expand their advanced packaging capabilities to gain market share.
Vertically integrated electronics giants like Samsung Electronics leverage captive supply for their memory and mobile divisions, ensuring consistent SiP module integration for their own products. Dedicated advanced packaging service providers such as Amkor Technology specialize in offering complex RF and power management SiP solutions, catering to the specific needs of fabless semiconductor firms. Similarly, ASE Group, a high-volume OSAT player, scales its advanced packaging services to diverse high-volume markets, anchoring a significant portion of the broader SiP ecosystem with its extensive capacity.
| Leading Market Players |
|---|
| Samsung Electronics |
| Amkor Technology |
| ASE Group |
| ChipMOS Technologies |
| JCET Group |
| Texas Instruments |
| Renesas Electronics Corporation |
| Powertech Technology |
| SPIL |
| Others |
Cost & Logistics Intelligence
Taiwan's dominant outsourced assembly and test (OSAT) ecosystem concentrates significant margin pools within advanced packaging services. This supply concentration influences pricing power across the System in Package value chain.
Pricing Analysis
Cost-plus contracts, often indexed to raw material prices and advanced labor rates, define much of the System in Package market. Pricing stratifies across premium, standard, and economy tiers, driven by design complexity for RF SiP and compliance with EU RoHS directives. Cost compression intensifies within high-volume consumer electronics segments due to competitive pressures. Automotive electronics and aerospace & defense applications exhibit the lowest price sensitivity, prioritizing reliability and performance over cost.
Supply Chain Analysis
ASE Group, Amkor Technology, and Samsung Electronics hold substantial capacity for System in Package contract manufacturing. The supply chain for advanced SiP modules centers on Taiwan, South Korea, and China, drawing from specialized substrate materials and silicon wafers. A structural risk involves substrate supply bottlenecks, concentrated among a few key suppliers. Distribution primarily runs through direct integration by Original Equipment Manufacturers into their final products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The System in Package market represents a high-growth disruption, driven by the semiconductor industry's pivot to heterogeneous integration via chiplets. This shift redefines system performance and miniaturization capabilities.
For Market Incumbents: Build intellectual property moats through aggressive investment in next-generation Fan-Out and 3D IC packaging R&D. Expand advanced packaging capacity in strategic regions like the United States, leveraging incentives from the US CHIPS Act. This defends against supply chain diversification to emerging hubs and potential erosion from interconnect standardization. Strategic partnerships with fabless firms can secure long-term design wins.
For New Entrants and Emerging Players: Pursue specialized market niches such as medical technology miniaturization and silicon photonics integration. The medical wearables segment, requiring ultra-compact and power-efficient SiP modules, remains highly penetrable for innovative solutions. A focused go-to-market angle involves offering complete, validated subsystem SiPs that reduce design complexity for smaller OEMs. Develop solutions compliant with stringent medical device regulations.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across advanced packaging facilities, reflecting the substantial investment required for next-generation SiP manufacturing. Long-term viability for firms enabling heterogeneous integration remains robust over the next decade. Target acquisition archetypes include specialized OSATs demonstrating leadership in Fan-Out or 3D IC technologies. A critical signal to watch is the industry's progress on chiplet-to-chiplet interconnect standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in 3D IC and Fan-Out Capacity | Expands manufacturing capability for high-performance computing and AI applications. |
| Develop Chiplet Interconnect Standards | Fosters open multi-vendor ecosystems, accelerating SiP design innovation. |
| Expand Automotive Electronics SiP Portfolio | Captures growing demand for ADAS and infotainment systems in vehicles. |
| Pursue Medical Device SiP Certifications | Unlocks new market opportunities in compact, reliable medical wearables. |
| Secure Advanced Substrate Supply Agreements | Mitigates risks from supply chain bottlenecks for critical SiP components. |
Research Approach
A standing panel of semiconductor architects, OSAT executives, and automotive electronics engineers provided ongoing calibration for market insights. This involved combining in-depth primary interviews with robust secondary validation from sources like SEC filings of major semiconductor firms, SEMI industry reports, and government technology roadmaps. Bottom-up and top-down triangulation methods ensured data consistency across various market segments.
Scenario-bracketing, encompassing optimistic, base, and pessimistic cases, informed the quantitative projections across the analysis window. The analytical framework modeled market dynamics by technology, product type, application, end user, and component density. Compound annual growth rates were derived from regression analysis of historical data and projected growth drivers like 5G network buildouts. ADAS feature penetration rates served as a key industry-specific forecast input.
Sensitivities concentrate around geopolitical trade tensions and the pace of chiplet interconnect standardization. Forecasts reflect assumptions regarding technological adoption curves and supply chain stability. Quarterly review of global semiconductor capital expenditure and OSAT utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Test Services (OSAT) Market
Semiconductor Packaging
Flip-Chip COB Technology Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
Global Semiconductor Equipment Packaging and Test Market
Semiconductor Packaging
Global Bare Die Shipping and Handling and Processing and Storage Market
Semiconductor Packaging
3D TSV Packages Market
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
Semiconductor Packaging Market
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Asia-Pacific Quad-Flat-No-Lead Packaging Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market