
 Through-Silicon via (TSV) IC Packaging Market | 2026-2036
Through-Silicon via (TSV) IC Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Through-Silicon via (TSV) IC Packaging Market Analysis
Automotive electronics is restructuring the Through-Silicon via IC Packaging landscape as advanced driver-assistance systems and electric vehicle powertrains require higher-density interconnects. Samsung Electronics leverages its captive memory and logic foundry integration to dominate 3D stack production for high-bandwidth applications. Intel Corporation anchors its packaging strategy at Arizona and New Mexico facilities to sustain domestic supply chain control over leading-edge TSV flows. Taiwan Semiconductor Manufacturing Company specializes in CoWoS and SoIC architectures, extending its foundry dominance into advanced packaging services.
Through-Silicon via technology creates vertical electrical interconnects passing completely through silicon wafers or dies, typically employing copper fill with barrier/seed layers and achieving aspect ratios exceeding 10:1 in production flows. This architecture enables 3D integration that reduces signal path length and power consumption for high-performance computing and memory systems. Memory stacks command the largest product type volume as HBM generation transitions drive via density requirements upward. Hybrid bonding represents the fastest-growing technology segment as pitch scaling below 10 micrometers displaces conventional microbump approaches in leading-edge logic stacking. System-in-Package configurations concentrate margin pools where heterogeneous integration combines chiplets from multiple process nodes.
EPA hazardous substance rules and OSHA workplace exposure limits shape chemical handling protocols in TSV etch and plating operations across United States manufacturing sites. FDA medical device regulations indirectly influence packaging reliability standards when TSV-enabled components enter diagnostic and implantable equipment supply chains. NHTSA functional safety requirements for automotive electronics are forcing foundries to implement traceable process controls and extended temperature qualification protocols. Stakeholders must monitor how export control classifications from the Bureau of Industry and Security affect equipment and material access for advanced via formation processes.
Market Dynamics
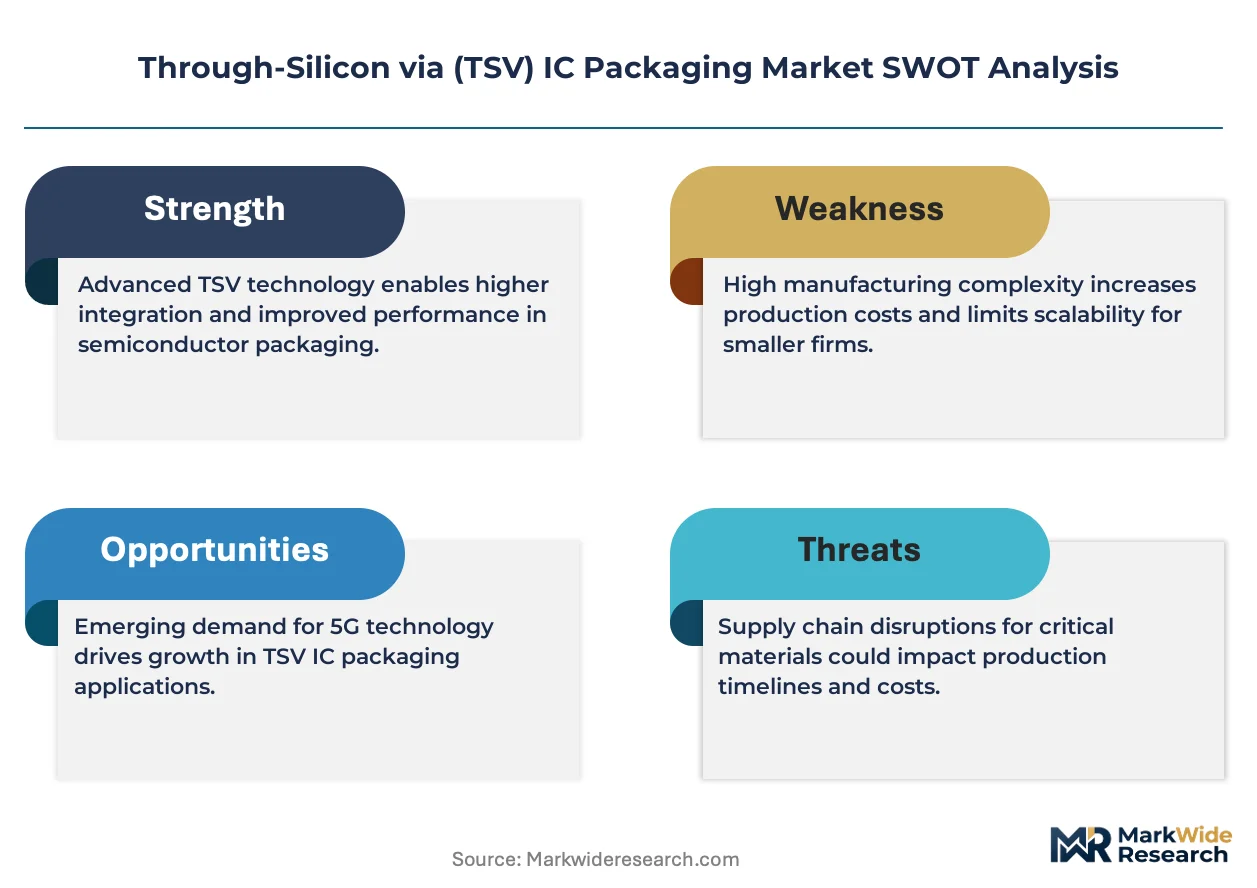
Hybrid bonding is compressing pitch requirements below 10 micrometers and forcing equipment suppliers to tighten process control specifications across etch, deposition, and planarization modules. This technology transition is redistributing margin pools from microbump-based flows toward dielectric-to-dielectric bonding architectures.
Growth Catalysts
- HBM Generation Transitions:Memory stack density requirements are pulling via aspect ratios above 10:1 in production flows. Advanced driver-assistance systems and electric vehicle powertrains are demanding higher-density interconnects from automotive electronics suppliers.
- OSHA Workplace Exposure Limits:Stricter chemical handling protocols in TSV etch and plating operations are accelerating capital expenditure cycles for compliant equipment upgrades at United States manufacturing sites.
- CoWoS and SoIC Architectures:Foundry service extensions into advanced packaging are creating captive 3D integration capacity concentration in Taiwan, South Korea, and the United States.
Market Restraints
- Copper Barrier/Seed Layer Material Costs:Precious metal volatility in barrier layer formulations is squeezing gross margins on high-aspect-ratio via fills.
- Equipment Supplier Concentration:Critical etch and deposition tool availability tightens when demand surges concentrate among three dominant equipment vendors.
- Hybrid Bonding Thermal Budget Constraints:Low-temperature anneal requirements limit throughput and create yield variability in leading-edge logic stacking flows.
Strategic Opportunities
- India Semiconductor Ecosystem:PLI scheme incentives and domestic packaging capacity buildouts are opening captive TSV service demand from fabless design houses.
- Diagnostic and Implantable Medical Devices:FDA reliability standards for TSV-enabled components are creating premium qualification pathways for hermetic packaging specialists.
- AI Accelerator Chiplets:Heterogeneous integration combining multiple process nodes is expanding System-in-Package margin pools beyond homogeneous memory stacking.
Industry Challenges
- Process Control Engineering Talent Scarcity:Deep expertise in sub-10 micrometer alignment and bond interface metrology is concentrated among a handful of specialist engineers.
- Extended Temperature Qualification Timelines:NHTSA functional safety traceability requirements are stretching automotive electronics validation cycles and compressing time-to-revenue windows.
- Export Control Classification Complexity:Bureau of Industry and Security restrictions on advanced via formation equipment are complicating international deployment of leading-edge production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Through-Silicon via (TSV) IC Packaging Market |
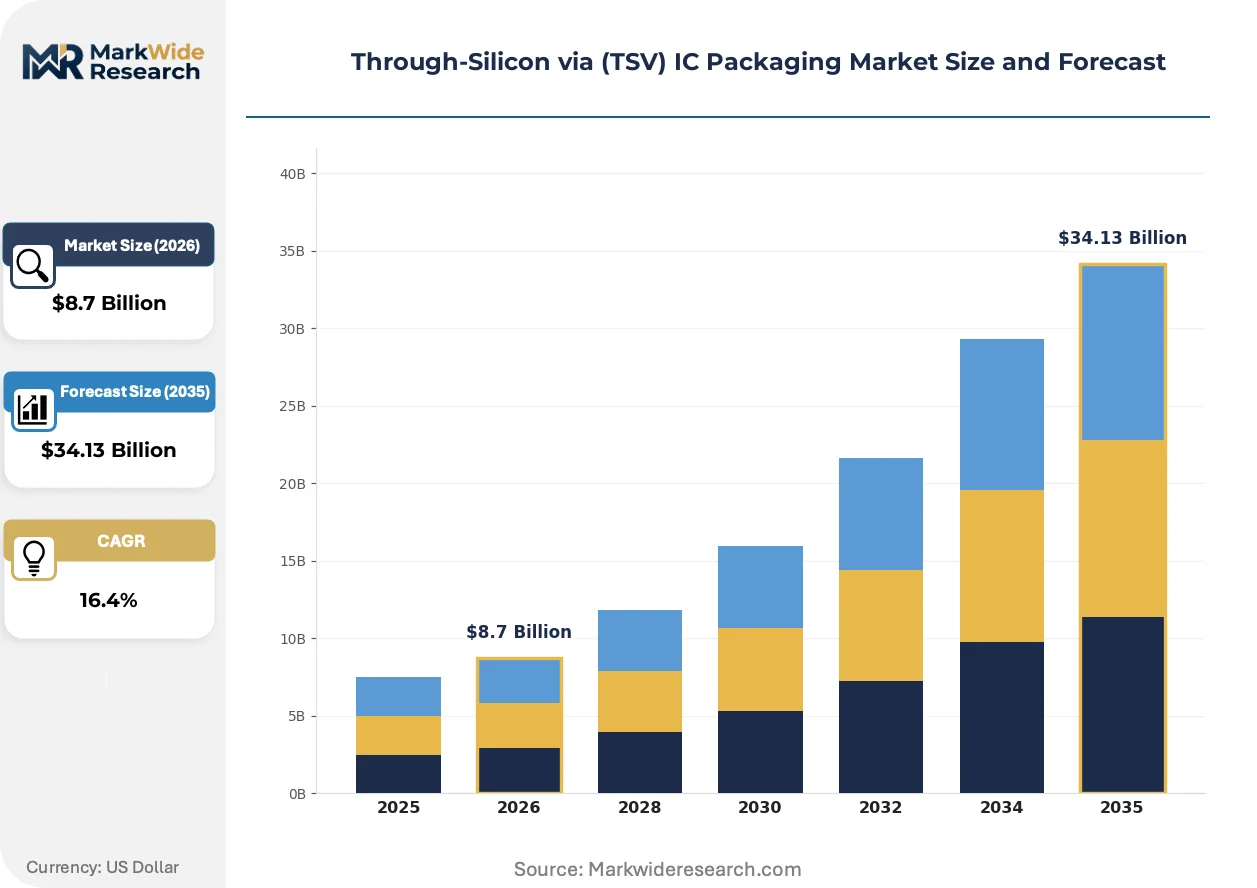
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D ICs, Memory Stacks, Logic Devices, System-in-Package End User: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Applications Technology: Wafer-Level Packaging, Flip Chip Technology, Hybrid Bonding, Fused Deposition Installation: On-Premises, Integrated Solutions, Outsourced Manufacturing, Custom Developments |
| Companies Covered | Taiwan Semiconductor Manufacturing Company, Samsung Electronics, Intel Corporation, Amkor Technology, ASE Group, Applied Materials, Texas Instruments, STATS ChipPAC Ltd, International Business Machines Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Through-Silicon via (TSV) IC Packaging Market Emerging Trajectories
Dielectric bonding interfaces are displacing solder-based interconnects across high-performance computing stacks. Equipment architectures, material sets, and inspection protocols are all adapting to accommodate oxide-to-oxide and oxide-to-silicon bonding workflows.
Hybrid bonding is electrifying the transition from microbump-based stacking to direct dielectric bonding in high-bandwidth memory and logic-on-logic configurations. Cloud service providers and AI accelerator designers are adopting this technology aggressively to reduce power consumption and signal latency. The structural consequence is compressing the addressable market for conventional flip-chip bumping equipment and redirecting capital toward precision wafer-to-wafer bonders.
REACH substance restrictions and EU Green Deal carbon accounting mandates are tightening material disclosure requirements for TSV process chemicals entering European supply chains. Formulators must now document full substance portfolios through the supply chain for etchants, cleaners, and planarization slurries. Memory module assemblers serving European data center operators are prioritizing suppliers with complete ECHA registration dossiers.
Consolidated procurement of advanced packaging services is concentrating negotiation leverage among hyperscale cloud operators and top-tier fabless semiconductor designers. These buyers are bypassing traditional OSAT intermediaries to contract directly with captive foundry packaging divisions. The United States and Taiwan are the geographies where this direct engagement model is most visible, with Arizona and New Mexico facilities capturing domestic supply chain preference.
Through-Silicon via (TSV) IC Packaging Market Segmentation
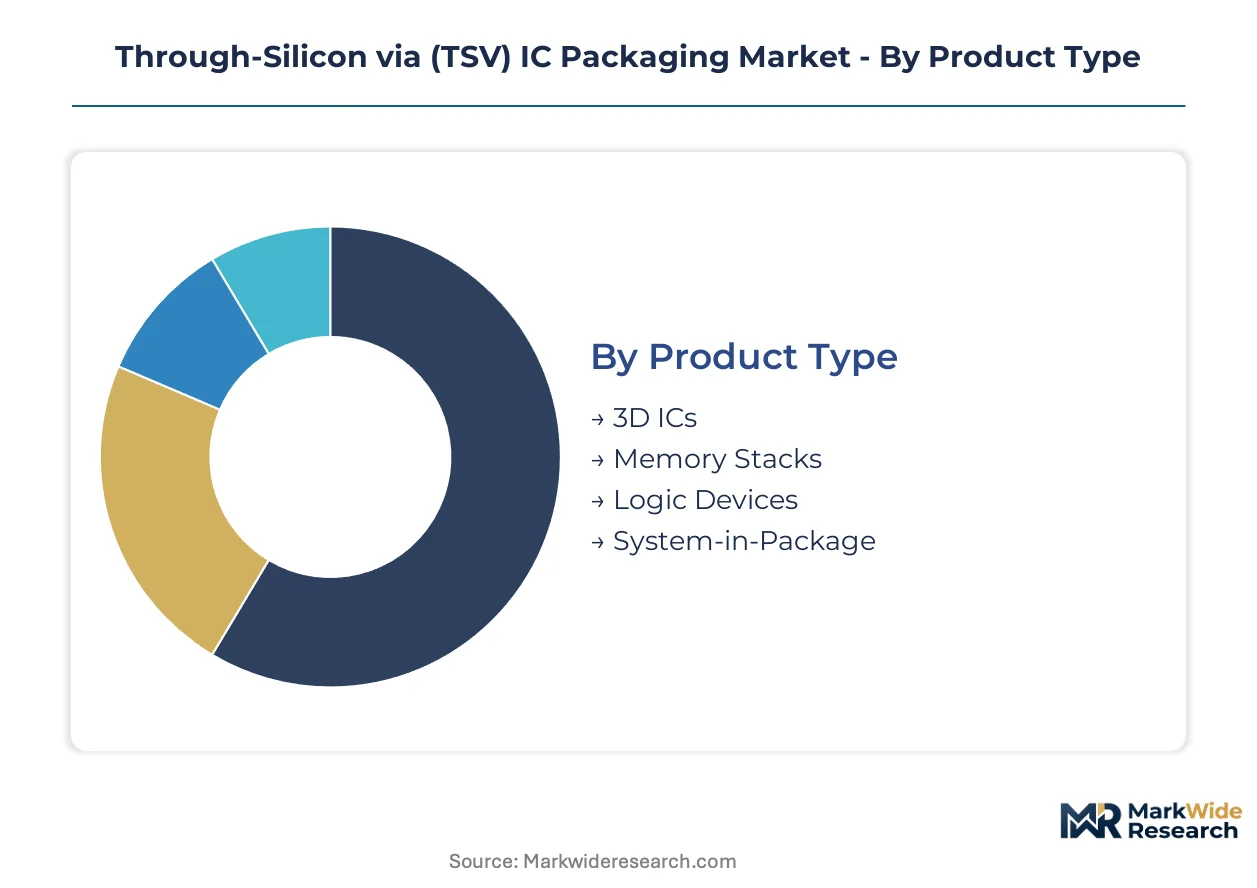
Through-Silicon via packaging architectures fragment across four distinct axes that determine capital allocation priorities. Product type and technology selection drive equipment procurement cycles, while end-user concentration shapes geographic deployment patterns.
Product Type:
Via density specifications and stack height requirements differentiate commercial applications across the product spectrum.
- Memory Stacks:High-bandwidth memory generations employ copper-filled vias with aspect ratios exceeding 10:1 to achieve vertical die stacking. Demand from AI accelerators and data center infrastructure in Taiwan and South Korea is pulling wafer starts toward higher-density configurations.
- System-in-Package:Heterogeneous integration combines chiplets from multiple process nodes under a single package lid. Margin pools concentrate where automotive electronics suppliers in the United States contract for extended temperature qualification protocols.
- 3D ICs:Full three-dimensional integration enables logic-on-logic stacking for high-performance computing.
- Logic Devices:Processor die stacking employs TSV for power delivery and signal routing.
Mature deployment sits with Memory Stacks. Newer deployment is concentrated in System-in-Package.
End User:
Application-specific reliability requirements and volume scales create divergent procurement patterns across customer verticals.
- Automotive Electronics:Advanced driver-assistance systems and electric vehicle powertrains mandate traceable process controls under NHTSA functional safety frameworks. Procurement is tightening around suppliers with captive 3D integration capacity in Arizona and New Mexico.
- Telecommunications:5G baseband processors and optical transceivers require hermetic sealing for field reliability. Network equipment manufacturers in South Korea are qualifying hybrid bonding flows for next-generation radio units.
- Consumer Electronics:Smartphone application processors and wearable sensors drive high-volume TSV demand.
- Industrial Applications:Factory automation controllers and power electronics specify wide-temperature operation.
Volume leadership rests with Consumer Electronics. Value concentration is shifting fastest into Automotive Electronics.
Technology:
Interconnect pitch and thermal budget constraints segment equipment and material supplier opportunities.
- Hybrid Bonding:Dielectric-to-dielectric bonding achieves sub-10 micrometer pitch without solder interconnects. Cloud service providers are redirecting capital from flip-chip bumping toward precision wafer-to-wafer bonders for AI accelerator production.
- Wafer-Level Packaging:Batch processing of TSV arrays at the wafer scale preserves alignment precision for memory stacking. Taiwan foundries dominate capacity deployment for CoWoS architectures serving fabless design houses.
- Flip Chip Technology:Solder-based microbump interconnects remain prevalent in cost-sensitive applications.
- Fused Deposition:Additive manufacturing approaches for package substrates remain exploratory.
Established production flows center on Wafer-Level Packaging. Steepest expansion trajectory belongs to Hybrid Bonding.
Installation:
Capital ownership models and process control requirements differentiate service delivery structures.
- Integrated Solutions:Captive packaging divisions within foundry operations maintain direct control over TSV formation and hybrid bonding workflows. Intel Corporation and Taiwan Semiconductor Manufacturing Company anchor this model in Arizona and Hsinchu.
- Outsourced Manufacturing:OSAT providers offer TSV processing as a service to fabless designers lacking captive capacity.
- On-Premises:IDM facilities retain full vertical control from wafer fabrication through final test.
- Custom Developments:Joint development programs align equipment suppliers with specific customer process requirements.
Capacity concentration favors Integrated Solutions. Emerging demand is concentrating in Outsource Manufacturing as fabless entrants proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in East Asian foundry clusters while consumption spreads across North American data center operators and automotive electronics suppliers. Taiwan and South Korea dominate captive 3D integration output. The United States, Germany, and Japan anchor advanced packaging demand from AI infrastructure and precision automotive systems.
United States
AI accelerator procurement from cloud service providers and NHTSA-mandated automotive traceability requirements are pulling TSV demand toward domestic suppliers. The CHIPS and Science Act directs federal incentives toward Arizona and New Mexico packaging facilities. Intel Corporation anchors captive capacity in these states to secure supply chain control over leading-edge flows.
Taiwan
CoWoS and SoIC architecture demand from fabless design houses is saturating available advanced packaging capacity. The National Development Council coordinates industrial policy to expand Hsinchu and Taichung foundry clusters. Taiwan Semiconductor Manufacturing Company extends its logic foundry dominance into heterogeneous integration services for high-bandwidth memory stacks.
South Korea
HBM generation transitions and 5G baseband processor qualification are driving via density requirements upward. MFDS medical device reliability standards create secondary demand from diagnostic equipment manufacturers. Samsung Electronics leverages captive memory and logic integration to dominate 3D stack production for network infrastructure and AI training systems.
Japan
Automotive sensor miniaturization and industrial automation controller specifications are sustaining demand for precision interconnects. METI technology roadmaps prioritize domestic packaging equipment supplier development. Tokyo and Osaka metropolitan areas concentrate specialized material formulators serving hybrid bonding process chemical requirements.
Germany
Electric vehicle powertrain electronics and factory automation systems are mandating extended temperature qualification protocols. REACH substance disclosure requirements and EU Green Deal carbon accounting tighten material traceability for TSV process chemicals entering European supply chains. Bavaria and Baden-Württemberg host automotive tier-one suppliers contracting directly for System-in-Package configurations.
Through-Silicon via (TSV) IC Packaging Market Vendor Landscape
Top-tier vendors anchor captive foundry packaging divisions, while specialized OSAT providers and equipment suppliers occupy supporting tiers. Market structure reflects semiconductor industry consolidation patterns where memory and logic fabricators internalize advanced packaging workflows. Three archetypes dominate: integrated device manufacturers with captive capacity, pure-play foundry packaging services, and precision equipment suppliers. Competitive moves concentrate on hybrid bonding technology licensing and geographic capacity expansion near customer clusters.
Among East Asian fabricators, Taiwan Semiconductor Manufacturing Company and Samsung Electronics exemplify the captive integration archetype, combining wafer fabrication with advanced packaging under unified process control. Intel Corporation occupies a position representing the Western IDM model, anchoring domestic supply chain strategies through Arizona and New Mexico facility investments. Amkor Technology sits within the outsourced specialist tier, serving fabless designers lacking internal TSV formation capability.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company |
| Samsung Electronics |
| Intel Corporation |
| Amkor Technology |
| ASE Group |
| Applied Materials |
| Texas Instruments |
| STATS ChipPAC Ltd |
| International Business Machines Corporation |
| Others |
Supply Flow & Price Mechanics
Captive foundry packaging divisions within vertically integrated semiconductor manufacturers anchor supply-side discipline, translating process control advantages into pricing power over outsourced assembly and test providers. Equipment supplier concentration in etch and deposition modules tightens procurement leverage, while hybrid bonding yield variability constrains volume scalability and props premium pricing for qualified capacity.
Pricing Analysis
Cost-down pressure on flip-chip bumping equipment accelerates because cloud service providers redirect capital toward precision wafer-to-wafer bonders for AI accelerator production. Three-tier pricing structure across premium, standard, and economy levels separates qualified automotive-grade TSV flows from consumer electronics memory stacks and exploratory prototype runs. Certification tier under NHTSA functional safety frameworks commands substantial premiums over industrial-temperature qualified product. Fabless designers lacking captive capacity exhibit highest price sensitivity, while hyperscale cloud operators prioritize supply security over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand as cloud service providers and top-tier fabless designers contract directly with captive foundry packaging divisions, bypassing traditional OSAT intermediaries. Taiwan, South Korea, and the United States concentrate supply for leading-edge TSV formation and hybrid bonding workflows. Copper barrier/seed layer formulations, high-purity etchant chemicals, and precision planarization slurries constitute critical input dependencies. Single-source vulnerability in advanced etch and deposition tool availability tightens when demand surges concentrate among three dominant equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid bonding capacity scarcity props pricing discipline across qualified production lines, with equipment lead times and yield engineering bottlenecks constraining volume expansion faster than demand accumulation from AI accelerator designers.
For Market Incumbents: To counter margin compression from precious metal volatility in barrier layer formulations, deepen captive control over copper seed layer deposition workflows and expand qualified capacity at Arizona and New Mexico facilities to secure domestic supply chain preference under CHIPS Act incentives. For New Entrants and Emerging Players: Begin with automotive electronics qualification pathways where NHTSA traceability requirements create barrier-to-entry protection for hermetic packaging specialists, targeting tier-one suppliers in Bavaria and Baden-Württemberg with extended temperature protocol expertise as the primary go-to-market angle. For Investors and Strategic Acquirers: Bureau of Industry and Security export control tightening on advanced via formation equipment is the leading indicator that captive equipment access will differentiate viable acquisition targets from stranded capacity plays. Focus on mid-cap specialists with in-house hybrid bonding process development capabilities and established foundry customer relationships as the preferred acquisition archetype across the long-term viability window.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Process Development | Sub-10 micrometer pitch capability displaces microbump architectures for AI accelerator production at cloud service providers. |
| Automotive Qualification Investment | NHTSA traceable process controls secure premium pricing from electric vehicle powertrain electronics suppliers in Germany. |
| Domestic Capacity Expansion | Arizona and New Mexico facility investments capture CHIPS Act incentives and supply chain control for Intel Corporation. |
| Equipment Supplier Partnership | Joint development programs with etch and deposition vendors tighten process control specifications for hybrid bonding workflows. |
| Hermetic Packaging Certification | FDA reliability standards for TSV-enabled components create premium qualification pathways for diagnostic and implantable medical devices. |
Methodological Framework
Document review covered SEC 10-K filings, equipment supplier technical disclosures, and foundry capacity announcements, complemented by interviews with packaging process engineers, fabless design house procurement leads, automotive tier-one supplier quality directors, and semiconductor equipment vendor application specialists. Secondary validation drew from Bureau of Industry and Security export control classifications, EPA hazardous substance handling protocols, and customs trade data for TSV formation equipment imports. Bottom-up wafer start projections and top-down packaging service revenue estimates underwent cross-triangulation to anchor volume and value outputs.
Segmentation-level forecasts across product type, technology, end user, and installation mode reflect penetration assumptions for hybrid bonding versus microbump architectures and captive versus outsourced capacity ownership models. CAGRs were derived from equipment procurement cycle analysis and foundry capital expenditure disclosure patterns. Memory stack density requirements from HBM generation transitions and automotive electronics reliability qualification timelines served as primary demand-side calibration inputs throughout the projection horizon.
Underlying measurement precision varies by segment; hybrid bonding technology forecasts carry tighter precision than exploratory fused deposition approaches given equipment supplier disclosure granularity. Forecasts reflect assumptions regarding equipment lead time normalization and yield engineering progression that Bureau of Industry and Security regulatory shifts or copper commodity volatility could materially revise. Periodic stress-testing of base assumptions against foundry capex guidance and hyperscaler AI infrastructure deployment announcements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
3D IC Packaging Market
Semiconductor Packaging
System-On-Package Market
Semiconductor Packaging
Semiconductor Packaging Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market
Semiconductor Packaging
Global Semiconductor Equipment Packaging and Test Market
Semiconductor Packaging
Global MEMS Packaging Market
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
Embedded Die Packaging Market
Semiconductor Packaging
Semiconductor Solder Flux Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market