
 3D TSV Packages Market | 2026-2036
3D TSV Packages Market Size, Share, and Industry Trends Forecast 2026-2036
3D TSV Packages Market Analysis
South Korea is fragmenting its 3D TSV packaging capacity across Pyeongtaek and Icheon complexes to reduce geographic concentration risk. Samsung Electronics leverages captive DRAM supply to anchor its HBM3E packaging roadmap. SK hynix sustains process leadership in hybrid bonding for high-stack memory modules. Intel Corporation competes through its Oregon and Arizona packaging development centers for US-based AI chip supply.
3D TSV packages interconnect stacked semiconductor dies using vertical copper-filled vias with diameters typically below 10 micrometers, enabling bandwidth densities exceeding 2 TB/s between memory and logic layers. Memory Packages dominate current shipment volumes as high-bandwidth memory stacks drive AI accelerator architectures. Interposer Technology commands premium positioning by enabling heterogeneous integration of chiplets from different process nodes. Processor Packages are gaining structural importance as chiplet-based CPU designs displace monolithic die strategies in data center deployments.
MIIT in China enforces domestic packaging material certification for imported 3D TSV equipment, shaping market access for foreign tool vendors. REACH and RoHS in Europe restrict lead-based solder alternatives in via-fill metallurgy, pushing suppliers toward copper-pillar and tin-silver compositions. The US Department of Commerce export controls on advanced packaging equipment to specific fabs are redirecting capital expenditure flows. Stakeholders must monitor which regulatory jurisdiction captures the next wave of HBM capacity build-outs.
Market Dynamics
Hybrid bonding technology is compressing interconnect pitches below 4 micrometers, forcing packaging houses to retool thermal management systems and retrain process engineers for die-to-wafer fusion workflows.
Growth Catalysts
- High-bandwidth memory stacks:AI training clusters in data centers require memory bandwidth densities exceeding 2 TB/s between logic and memory layers, pulling TSV adoption into mainstream accelerator architectures.
- MIIT domestic certification mandates:China's packaging material certification requirements for imported TSV equipment are accelerating local supply chain buildouts and creating captive demand for qualified domestic tool vendors.
- Wafer thinning advances:Sub-30-micron wafer handling capabilities are expanding yield rates for high-stack memory modules, reducing cost barriers for advanced packaging adoption.
Market Restraints
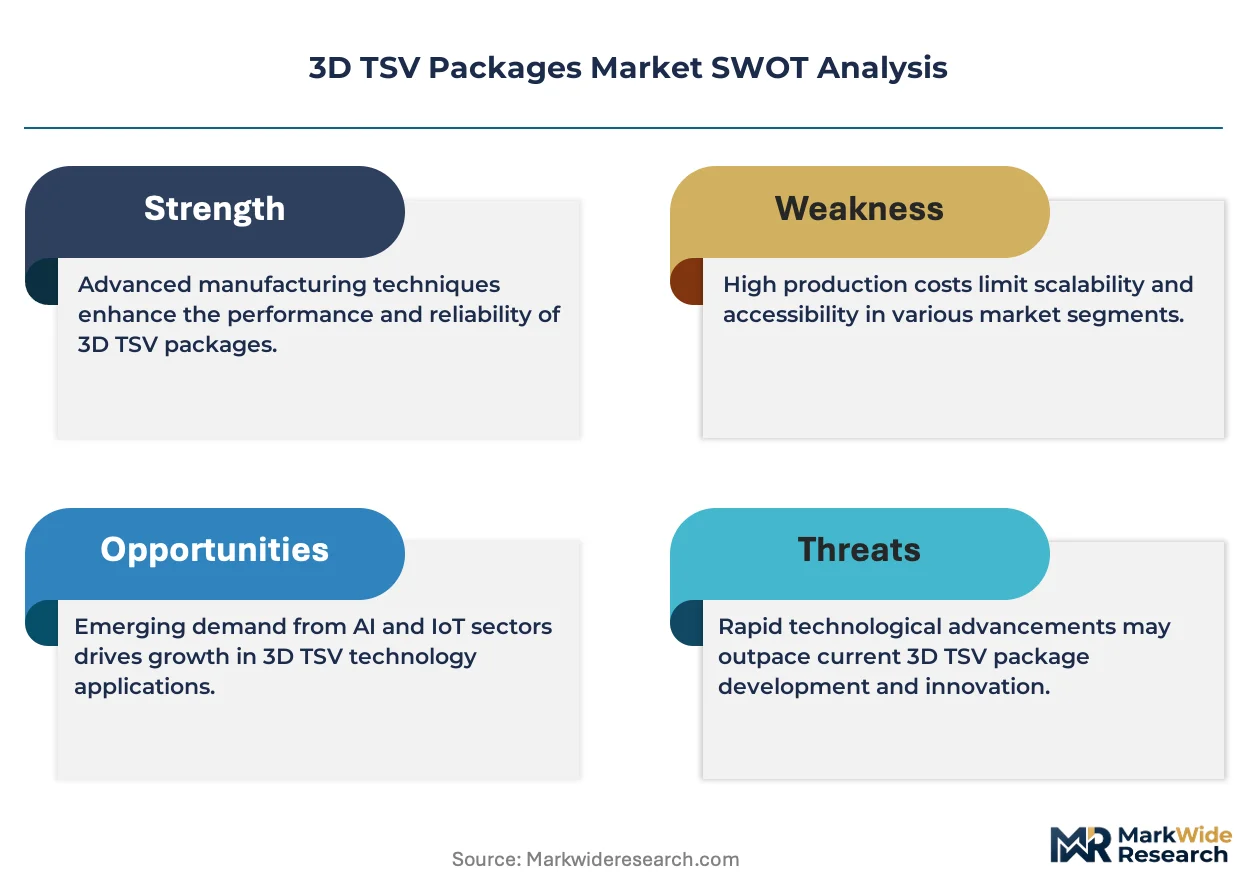
- Copper-pillar metallurgy cost volatility:Tin-silver alloy compositions required by REACH and RoHS restrictions carry premium raw material costs versus legacy lead-based alternatives, compressing margin structures for via-fill processes.
- Geographic supply concentration:Advanced packaging capacity clusters heavily in South Korea's Pyeongtaek and Icheon complexes, creating single-point-of-failure exposure for global HBM supply chains.
- Yield loss rates at high aspect ratios:Via-fill metallization at sub-10-micrometer diameters with depth-to-width ratios exceeding 10:1 generates defect densities that constrain throughput scaling.
Strategic Opportunities
- US-based packaging development:Intel's Oregon and Arizona facilities are building captive capacity for domestic AI chip supply, creating white space for equipment vendors qualifying under US Department of Commerce frameworks.
- Heterogeneous integration via interposers:Chiplets from different process nodes are converging on silicon interposer substrates, opening architecture flexibility for system designers previously locked to monolithic die strategies.
- EU Green Deal material mandates:REACH-compliant metallurgy requirements are pushing European packaging houses toward copper-pillar and tin-silver compositions, generating retrofit demand for plating tool vendors.
Industry Challenges
- Hybrid bonding technician scarcity:Die-to-wafer fusion processes require specialized cleanroom operators with sub-micron alignment expertise, creating recruitment bottlenecks as capacity expands.
- Equipment qualification timelines:MIIT certification protocols for imported TSV tools extend deployment cycles by 12-18 months, delaying fab ramp schedules.
- Legacy thermal interface integration:Existing underfill and TIM materials degrade performance at hybrid bonding's reduced interconnect pitches, forcing material stack redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D TSV Packages Market |
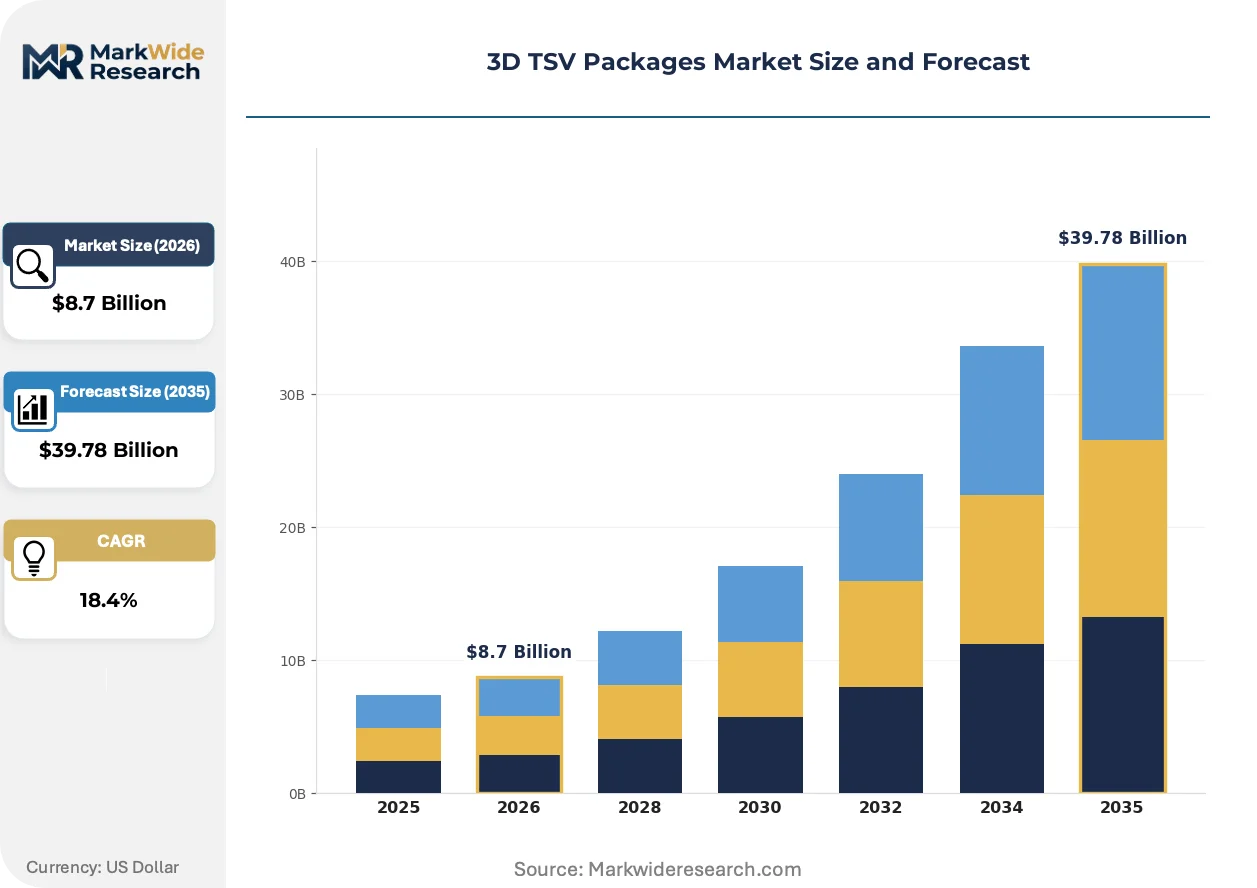
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Packages, Sensor Packages, Processor Packages, ASIC Packages Technology: Wafer-Level Packaging, Flip Chip, Stacked Die, Interposer Technology End User: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Applications Application: High-Performance Computing, Mobile Devices, IoT Devices, Cloud Computing |
| Companies Covered | Taiwan Semiconductor Manufacturing Company, Samsung Electronics, Intel Corporation, Amkor Technology, ASE Technology Holding, Micron Technology, SK hynix, GLOBALFOUNDRIES, JCET Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D TSV Packages Market Emerging Trajectories
Process architectures are bifurcating between memory-dense HBM stacks and logic-centric chiplet assemblies, each demanding distinct TSV pitch, aspect ratio, and thermal management specifications.
Hybrid bonding is migrating from wire-bonded memory stacks to copper-to-copper direct fusion interfaces. Data center GPU and AI accelerator designers are adopting this transition aggressively to eliminate solder-based thermal bottlenecks. The technology is migrating from niche high-performance computing applications toward mainstream consumer AI inference engines, compressing pricing premiums for first-generation adopters.
REACH and RoHS restrictions on lead-based solder alternatives are mandating copper-pillar and tin-silver via-fill compositions across European packaging facilities. This regulatory pressure is elevating plating equipment complexity and material purity requirements. Memory package manufacturers serving EU-bound AI hardware are responding by qualifying new metallurgy chemistries with extended reliability testing protocols.
Buyer concentration among hyperscale cloud operators is consolidating procurement leverage for high-volume HBM contracts. Traditional distribution through memory module integrators is fragmenting as NVIDIA, Google, and Amazon Web Services negotiate direct packaging house relationships. This disintermediation is most visible in South Korea, where Samsung Electronics and SK hynix now maintain dedicated account teams for individual hyperscaler specifications.
3D TSV Packages Market Segmentation
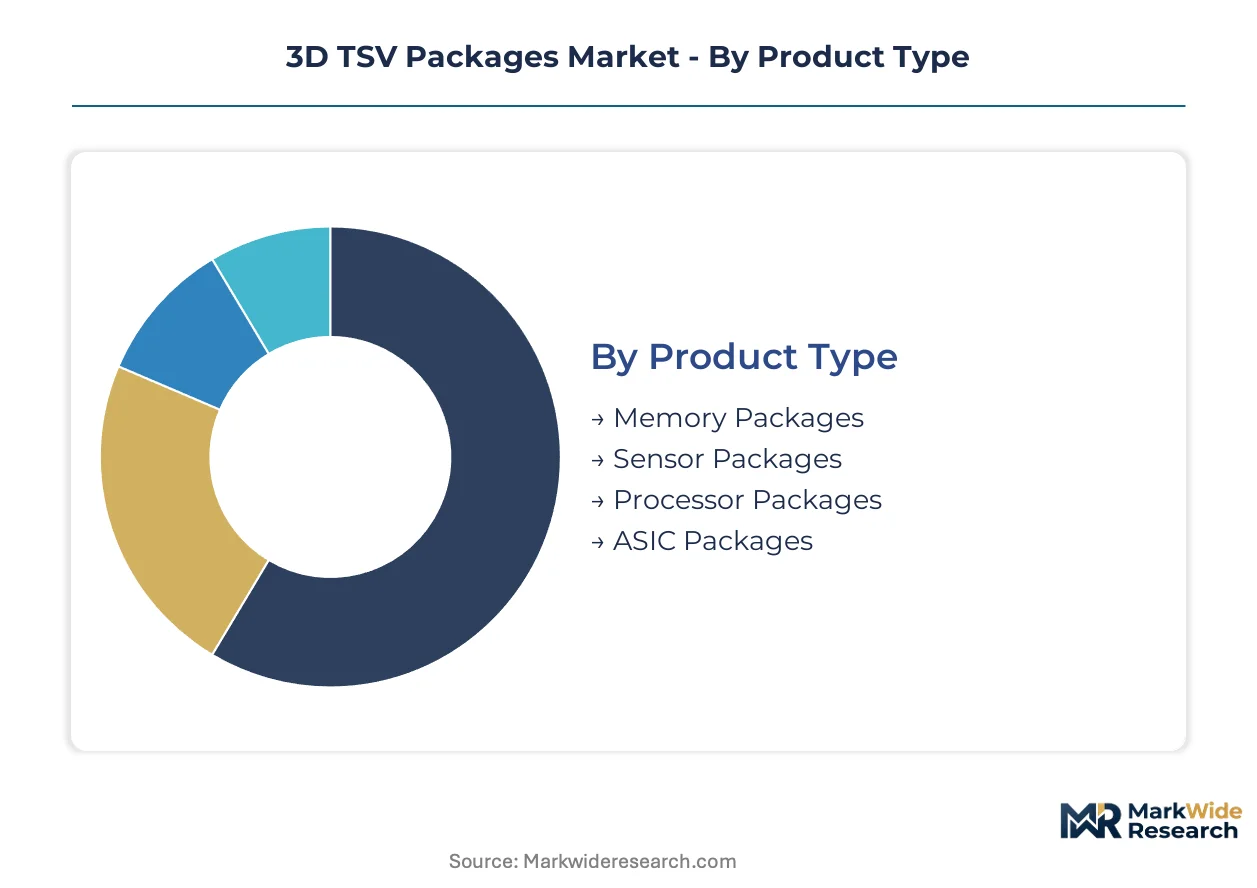
Segmentation in the 3D TSV Packages Market reveals how technical specifications align with distinct service and support requirements across memory, logic, and sensor integration workflows. Each category exposes different vulnerability points in yield management, equipment qualification, and customer technical support intensity.
Product Type:
After-sales service intensity varies sharply across product categories, with memory packages demanding continuous yield engineering support while processor packages require co-development partnerships for thermal-structural validation.
- Memory Packages:High-bandwidth memory stacks interconnect DRAM dies through sub-10-micrometer copper vias, achieving bandwidth densities exceeding 2 TB/s. Demand concentrates in South Korea's Pyeongtaek and Icheon complexes where Samsung Electronics and SK hynix operate dedicated packaging fabs for AI accelerator supply. Yield engineering support extends through module-level qualification, creating captive service relationships with hyperscale cloud operators.
- Processor Packages:Chiplet-based CPU and GPU designs displace monolithic architectures, requiring heterogeneous integration of compute tiles from disparate process nodes. Intel's Oregon and Arizona development centers anchor US-based capacity, pulling packaging houses into multi-year co-development contracts for thermal interface material validation and power delivery optimization.
- Sensor Packages:Image sensor and MEMS stacks leverage TSV for vertical signal routing in compact form factors. Automotive LiDAR and smartphone camera modules drive specification diversity, fragmenting tooling requirements across packaging houses.
- ASIC Packages:Custom accelerator designs for cryptocurrency mining and AI inference demand rapid turnaround on specialized interconnect pitches. Fabless designers prioritize packaging partners with in-house redistribution layer capability to compress time-to-tapeout.
Memory Packages holds the largest share; momentum sits with Processor Packages as chiplet architectures displace monolithic die strategies in data center deployments.
Technology:
Cost tier stratification separates mature wire-bond alternatives from premium hybrid bonding workflows, with interposer technology commanding the highest capital intensity per wafer start.
- Interposer Technology:Silicon interposers enable heterogeneous chiplet integration with sub-micrometer wiring pitches, bridging logic and memory dies from different foundry processes. Cloud computing and high-performance computing clusters in US and South Korean facilities drive qualification demand, with NVIDIA and Google negotiating direct packaging house relationships for custom specifications.
- Stacked Die:Vertical die stacking through TSV eliminates wire-bond inductance penalties for memory bandwidth scaling. SK hynix sustains process leadership in hybrid-bonded high-stack modules, compressing interconnect pitches below 4 micrometers for next-generation HBM roadmaps.
- Wafer-Level Packaging:Fan-out and fan-in configurations redistribute I/O for mobile and IoT form factors. Cost-sensitive consumer electronics applications favor this approach for die-size optimization without substrate-level interposers.
- Flip Chip:Solder-bump interconnect remains prevalent in automotive and industrial applications where thermal cycling reliability outweighs bandwidth density requirements. REACH and RoHS restrictions on lead-based compositions elevate material qualification burdens for European-bound shipments.
Interposer Technology commands premium positioning; Stacked Die is climbing the fastest as hybrid bonding displaces wire-bonded memory architectures.
End User:
Volume concentration among hyperscale cloud operators fragments traditional distribution channels, with direct procurement relationships replacing module integrator intermediation.
- Telecommunications:5G baseband and network processor packaging demands high-reliability TSV for millimeter-wave signal integrity. Equipment vendors in South Korea and Japan prioritize domestic packaging capacity for supply security.
- Consumer Electronics:Smartphone AP and image sensor modules drive high-volume demand for cost-optimized TSV configurations. Seasonal production ramps stress packaging house capacity allocation during flagship device launch windows.
- Automotive Electronics:ADAS processors and LiDAR sensors require AEC-Q100 qualification for thermal cycling endurance. European packaging houses face EU Green Deal material mandates for REACH-compliant metallurgy in via-fill processes.
- Industrial Applications:Edge AI and machine vision systems adopt TSV for compact multi-sensor fusion. Long product lifecycles favor packaging configurations with extended reliability data and second-source qualification.
Telecommunications captures the largest revenue concentration; momentum sits with Automotive Electronics as ADAS penetration drives LiDAR and processor packaging demand.
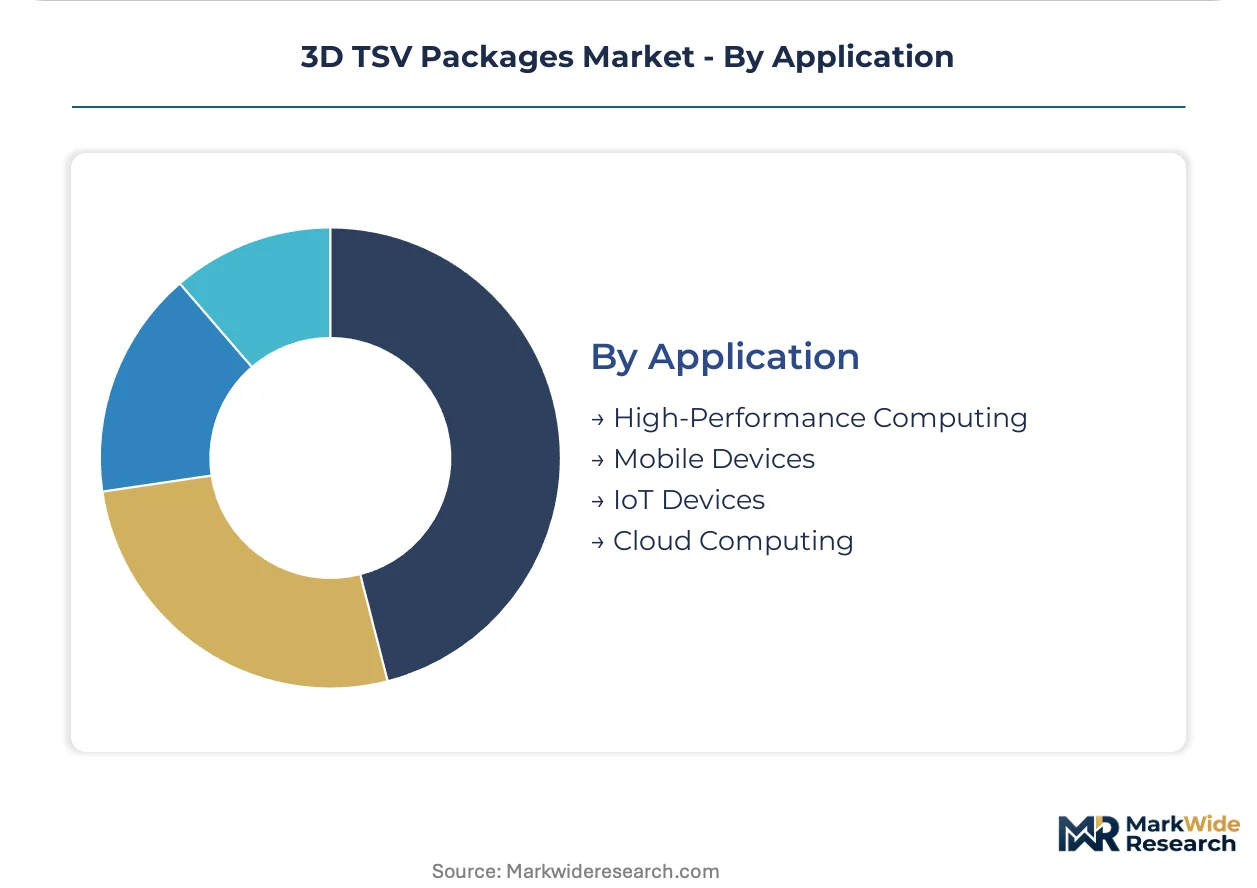
Application:
Supply chain maturity separates established high-performance computing workflows from emerging IoT volume opportunities, with cloud computing creating the most concentrated procurement leverage.
- High-Performance Computing:Exascale systems and AI training clusters require HBM3E stacks with hybrid-bonded interfaces for thermal performance. US Department of Commerce export controls redirect capital expenditure toward domestic packaging development centers.
- Cloud Computing:Hyperscale operators consolidate procurement for custom AI accelerator packages, disintermediating traditional memory module integrators. Amazon Web Services and Google maintain dedicated account teams at Samsung Electronics and SK hynix for specification co-development.
- Mobile Devices:Smartphone form factor constraints drive fan-out wafer-level packaging adoption for AP and modem integration. MIIT domestic certification mandates in China accelerate local supply chain buildouts for qualified packaging capacity.
- IoT Devices:Distributed sensor networks and edge inference engines create volume opportunity at reduced interconnect density requirements. Cost pressure favors wire-bond alternatives unless bandwidth constraints mandate TSV adoption.
High-Performance Computing holds the largest share; Cloud Computing is expanding most quickly as hyperscale operators vertically integrate packaging procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT certification protocols in China are redirecting equipment procurement flows, while South Korea's Pyeongtaek and Icheon complexes anchor current HBM capacity. The US Department of Commerce export controls are accelerating domestic packaging development across multiple geographies.
South Korea
HBM3E packaging roadmaps drive capital allocation toward hybrid bonding capacity expansions. The Ministry of Trade, Industry and Energy coordinates domestic supply chain security initiatives for advanced packaging equipment. Pyeongtaek and Icheon complexes fragment production across separate geographic zones to reduce concentration risk.
United States
AI accelerator demand from hyperscale cloud operators pulls packaging capacity toward domestic development centers. The Department of Commerce export control frameworks redirect foreign capital expenditure toward qualified US-based facilities. Intel's Oregon and Arizona sites anchor captive packaging development for domestic AI chip supply chains.
China
Domestic AI training cluster deployments create captive demand for locally qualified packaging capacity. MIIT enforces material certification requirements for imported TSV equipment, extending deployment cycles by 12-18 months. Yangtze River Delta packaging houses accelerate local supply chain buildouts to meet qualification mandates.
Japan
Automotive LiDAR and image sensor packaging demand diversifies TSV application beyond memory-centric workloads. METI coordinates national semiconductor strategy funding toward advanced packaging capability. Kyushu and Tohoku industrial corridors concentrate equipment vendor qualification activity for heterogeneous integration processes.
Germany
Automotive electronics qualification requirements for ADAS processors elevate packaging reliability standards. REACH and RoHS restrictions mandate copper-pillar and tin-silver via-fill compositions across European facilities. Bavaria and Baden-Württemberg automotive clusters drive retrofit demand for REACH-compliant plating equipment.
3D TSV Packages Market Vendor Landscape
Capability concentration sits with memory specialists commanding hybrid bonding expertise; scale advantage sits with diversified packaging houses serving multiple end markets. The competitive structure bifurcates between captive semiconductor manufacturers and merchant packaging service providers. Three archetypes dominate: integrated device manufacturers with captive DRAM supply, pure-play packaging houses with heterogeneous integration expertise, and foundry-affiliated packaging operations. Capacity expansion and strategic partnerships represent the dominant competitive vectors as players position for hyperscale cloud procurement relationships.
Among integrated device manufacturers, Samsung Electronics and SK hynix occupy positions anchored by captive memory supply, while Intel Corporation exemplifies the foundry-affiliated model building domestic US capacity. These three entities represent distinct strategic postures: memory-centric vertical integration, hybrid bonding process leadership, and geographic diversification under export control frameworks. Merchant packaging houses compete through heterogeneous integration capabilities rather than captive silicon supply.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company |
| Samsung Electronics |
| Intel Corporation |
| Amkor Technology |
| ASE Technology Holding |
| Micron Technology |
| SK hynix |
| GLOBALFOUNDRIES |
| JCET Group |
| Others |
Supply Flow & Price Mechanics
Undercapacity in South Korea's Pyeongtaek and Icheon packaging complexes tightens supplier pricing power while hyperscale cloud operators negotiate long-term offtake contracts for HBM3E supply security. This utilization squeeze feeds into raw material cost pass-through dynamics and accelerates geographic diversification investments among buyers seeking supply resilience.
Pricing Analysis
Price spreads between South Korean and US-based packaging services reflect hybrid bonding capability premiums and MIIT certification cost burdens for China-bound equipment. Three-tier pricing structure across premium hybrid-bonded memory, standard TSV interposer, and economy wire-bond alternatives segments buyer tiers. Cost compression in standard TSV tiers intensifies because tin-silver alloy compositions carry premium raw material costs under REACH and RoHS restrictions. Fabless AI chip designers exhibit highest price sensitivity, while hyperscale cloud operators with captive specification teams absorb premiums for supply security.
Supply Chain Analysis
Tariff exposure between US and Chinese semiconductor equipment flows dominates supply chain risk planning for packaging houses qualifying tools under divergent regulatory frameworks. Manufacturing concentrates in South Korea, Taiwan, and the United States, with each jurisdiction anchoring distinct technology specializations. The supply chain rests on high-purity copper feedstock, specialized plating chemistries, and sub-micron alignment equipment. Single-source vulnerability concentrates in hybrid bonding tool vendors qualified for HBM3E production. Distribution runs through direct procurement relationships between packaging houses and hyperscale cloud operators, displacing traditional memory module integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical memory oversupply as AI training cluster deployments absorb HBM3E capacity ahead of schedule. Capital expenditure timing among hyperscale cloud operators provides the cyclical justification.
For Market Incumbents: Build process technology moats through hybrid bonding yield leadership. Defensive moves center on captive DRAM supply integration and dedicated account team deployment for hyperscale specification co-development. Threat from Intel's Oregon and Arizona packaging development centers pressures geographic positioning. Capacity addition in US-qualified facilities under Department of Commerce frameworks provides channel control leverage. For New Entrants and Emerging Players: Establish a beachhead in automotive LiDAR sensor packaging where AEC-Q100 qualification barriers remain lower than HBM3E memory tiers. White-space targets include European packaging houses retrofitting REACH-compliant plating equipment and China-based facilities navigating MIIT certification timelines for domestic AI cluster supply. Go-to-market angle emphasizes rapid turnaround on specialized interconnect pitches for fabless ASIC designers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among packaging houses with multi-year co-development contracts for thermal-structural validation. Long-term viability over the next decade hinges on heterogeneous integration capability rather than captive silicon supply. Acquisition target archetype: merchant packaging specialists with interposer technology expertise and qualified cleanroom capacity. Signal to watch is qualification velocity for hybrid bonding technicians as capacity expansion outpaces specialized labor supply.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | SK hynix and Samsung Electronics anchor HBM3E roadmaps through die-to-wafer fusion workflows. |
| US-Based Packaging Development | Intel's Oregon and Arizona facilities qualify under Department of Commerce export control frameworks. |
| MIIT Certification Investment | China-based packaging houses accelerate local supply chain buildouts for imported TSV equipment. |
| REACH-Compliant Metallurgy Transition | European packaging houses retrofit plating tools for tin-silver via-fill compositions. |
| Hyperscale Direct Procurement | NVIDIA and Google negotiate dedicated account teams at Samsung Electronics and SK hynix. |
Methodological Framework
Initial hypotheses were tested against primary input from packaging process engineers, hyperscale cloud procurement officers, semiconductor equipment sales directors, and regulatory compliance leads and refined through secondary validation. Primary fieldwork combined structured interviews with TSV packaging specialists at Samsung Electronics, SK hynix, and Intel development centers with channel checks among plating chemistry suppliers and alignment equipment vendors. Secondary sources encompassed SEC filings from listed packaging houses, MIIT equipment certification databases, REACH compliance registries, and hyperscaler capital expenditure disclosures. Bottom-up capacity modeling triangulated against top-down AI accelerator shipment forecasts.
Demand-supply balance modeling anchored volume projections across the analysis window. Segmentation dimensions encompassed product type, technology node, end-user vertical, and application workload intensity. CAGRs derived from installed base growth rates for AI training clusters and bandwidth density requirements per accelerator. Industry-specific forecast inputs included hybrid bonding yield learning curves and wafer thinning capability expansion timelines.
Sensitivities concentrate around equipment qualification delays under MIIT protocols, hybrid bonding technician recruitment bottlenecks, and tin-silver alloy cost volatility. Forecasts reflect assumptions about HBM3E adoption velocity and chiplet architecture displacement rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Outsourced Semiconductor Assembly and Test Services (OSAT) Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Semiconductor Packaging Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
Microtube Box Market
Semiconductor Packaging
Flip-Chip COB Technology Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
Embedded Die Packaging Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
Embedded Die Packaging Technology Market