
 2.5D IC Packaging Market | 2026-2036
2.5D IC Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
2.5D IC Packaging Market Outlook
Multi-sourcing of interposer substrates is rebalancing leverage between captive foundries and outsourced semiconductor assembly and test providers. Taiwan Semiconductor Manufacturing Company anchors advanced node packaging through massive capital deployment in CoWoS capacity. Samsung Electronics leverages its memory-to-logic integration strength to compete in high-bandwidth module assemblies. ASE Technology Holding sustains its position through scale in fan-out wafer level packaging services across multiple customer portfolios.
2.5D IC packaging stacks multiple active dies side-by-side on a passive silicon interposer with through-silicon vias, enabling inter-die bandwidth exceeding 2 Tbps while maintaining individual chip yields. The architecture serves high-performance computing where monolithic die scaling faces reticle limits and yield degradation. Interposer based packaging dominates current revenue as NVIDIA and AMD AI accelerators consume CoWoS capacity, while fan-out wafer level packaging grows fastest in mobile RF and automotive radar modules where substrate cost reduction matters. High-density interconnect technology leads R&D investment, though direct bonding is displacing microbump architectures in next-generation memory-logic stacks.
US CHIPS Act funding through NIST and Department of Commerce shapes domestic packaging reshoring incentives, while EU Chips Act disbursements require REACH-compliant material flows and CE-marked process equipment. Japan's METI coordinates subsidies for advanced substrate suppliers under its semiconductor national project. Stakeholders must monitor which jurisdictions convert incentive commitments into operational cleanroom capacity versus stranded construction, as equipment lead times and lithography availability determine actual output timelines.
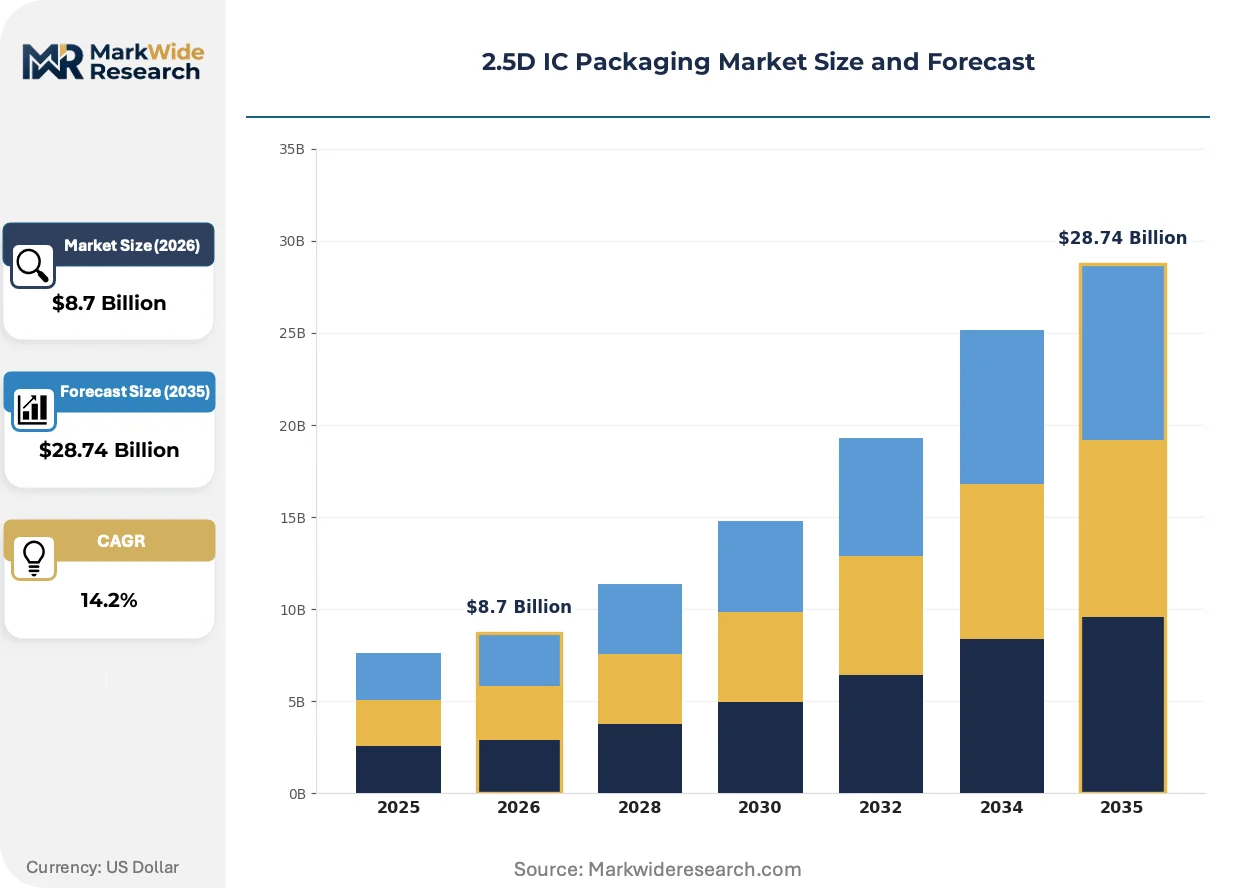
Market Dynamics
CoWoS capacity exhaustion is forcing a fundamental re-architecture of supply relationships, with AI accelerator demand outstripping interposer substrate availability and compelling buyers to qualify second-source packaging houses.
Growth Catalysts
- High-Performance Computing Clusters:Data center operators are mandating interposer-based architectures for training workloads, creating pull-through for 2.5D packaging across cloud infrastructure deployments.
- US CHIPS Act Disbursements:Department of Commerce funding is accelerating domestic cleanroom construction for advanced packaging, redirecting capital toward substrate and interposer capacity.
- Silicon Photonics Integration:Optical I/O chiplets are requiring 2.5D interposer platforms to manage electrical-optical conversion at package level, opening new application vectors.
Market Restraints
- Silicon Interposer Cost Structure:300mm passive interposer wafers command premium pricing due to lithography requirements, compressing margins for mid-range AI inference accelerators.
- Equipment Lead Time Concentration:Advanced packaging lithography systems face 18-24 month delivery windows from single-source suppliers, constraining capacity expansion velocity.
- Reticle Limit Constraints:Monolithic die scaling beyond 800mm² encounters yield degradation that 2.5D architectures address but cannot fully eliminate from total cost equations.
Strategic Opportunities
- Automotive Radar Modules:Fan-out wafer level packaging is penetrating 77GHz and 4D imaging radar substrates, with tier-one suppliers qualifying panel-level processing for cost reduction.
- EU Chips Act REACH Compliance:Incentivized capacity buildout in Germany and France is creating demand for CE-marked process equipment and compliant material flows.
- Hybrid Bonding Convergence:Direct copper-to-copper bonding is converging with interposer platforms, enabling memory-logic stacks without microbump pitch limitations.
Industry Challenges
- Process Integration Talent Scarcity:Cleanroom technicians with compound semiconductor and TSV process expertise command compensation premiums that strain emerging packaging house economics.
- IP Licensing Complexity:Microbump and interposer design patents held by foundry incumbents create royalty stacking for outsourced semiconductor assembly and test providers entering advanced nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2.5D IC Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fan-Out Wafer Level Packaging, Through-Silicon Via, Wafer Level Packaging, Interposer Based Packaging Technology: High-Density Interconnect, 3D Integration, Chip-on-Wafer, Direct Bonding Application: Data Centers, Mobile Devices, High-Performance Computing, Consumer Electronics End User: OEMs, Semiconductor Manufacturers, Electronics Companies, Telecom Providers |
| Companies Covered | Samsung Electronics, Taiwan Semiconductor Manufacturing Company, Intel Corporation, ASE Technology Holding, Amkor Technology, Broadcom, Texas Instruments, United Microelectronics Corporation, JCET Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2.5D IC Packaging Market Strategic Shifts
Process technology migration and substrate material evolution are compressing interposer pitch while expanding thermal management options, reshaping competitive requirements for packaging houses.
Hybrid bonding is rewriting the interconnect hierarchy by eliminating solder microbumps below 10μm pitch. AI accelerator designers at cloud service providers are adopting copper-to-copper interfaces for memory stacks, compressing z-height and thermal resistance simultaneously. This shift is forcing equipment refreshes at assembly houses that built capacity around thermocompression bonding.
Japan's METI semiconductor national project is coordinating subsidies for glass core substrate suppliers, targeting 2027 mass production for interposer alternatives. The initiative requires domestic equipment qualification, redirecting lithography and deposition tool procurement toward Japanese vendors. Memory module assemblers are most affected, re-qualifying processes for coefficient-of-thermal-expansion matching.
Consolidated procurement at hyperscale data center operators is compressing supplier qualification cycles from 18 months to 9 months for second-source packaging houses. Direct sourcing agreements with substrate vendors are displacing traditional OSAT-mediated procurement, concentrating volume commitments with interposer foundries. This pattern is most visible in Taiwan and South Korea, where captive packaging capacity anchors supply security negotiations.
2.5D IC Packaging Market Segmentation
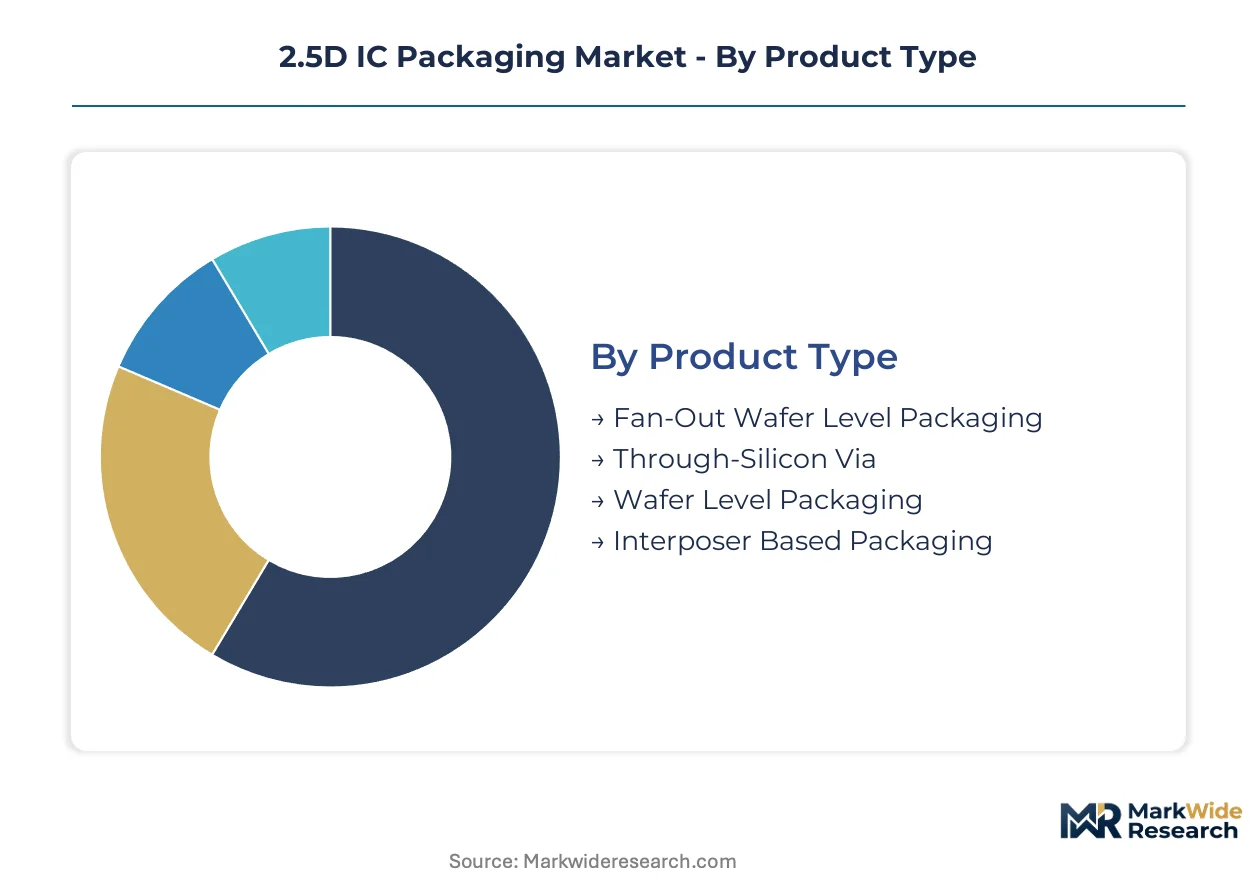
2.5D IC packaging segments diverge sharply in capital requirements, with interposer-based architectures demanding billion-dollar cleanroom investments while fan-out alternatives scale through equipment reuse. Technology selection directly determines which suppliers capture AI accelerator versus mobile RF module volumes.
Product Type:
Interposer-based packaging commands the steepest upfront capital deployment, requiring lithography systems with 18-24 month lead times that constrain capacity expansion velocity.
- Interposer Based Packaging:Passive silicon interposers with through-silicon vias enable inter-die bandwidth exceeding 2 Tbps. NVIDIA and AMD AI accelerators consume the bulk of CoWoS capacity in Taiwan, where foundry captive supply dominates procurement negotiations.
- Fan-Out Wafer Level Packaging:Redistribution layers on reconstituted wafers eliminate substrate costs for mid-range applications. Mobile RF and automotive radar modules in South Korea and Germany drive fastest expansion as tier-one suppliers qualify panel-level processing for cost reduction.
- Through-Silicon Via:Vertical interconnects through silicon dies enable 3D stacking with reduced signal path lengths. Memory module assemblers leverage TSV for high-bandwidth stacks in data center deployments.
- Wafer Level Packaging:Front-end compatible processing enables chip-scale footprints for space-constrained applications. Consumer electronics OEMs in Japan prioritize this format for image sensor modules.
Interposer Based Packaging absorbs the bulk of installed capacity; Fan-Out Wafer Level Packaging is expanding most quickly.
Technology:
Process maturity separates technologies already shipping at volume from those requiring equipment refreshes and requalification cycles.
- High-Density Interconnect:Sub-2μm line-width redistribution layers enable fine-pitch routing on organic or silicon substrates. Data center operators mandate this technology for training workload accelerators, creating pull-through across cloud infrastructure.
- Direct Bonding:Copper-to-copper interfaces eliminate solder microbumps below 10μm pitch, compressing z-height and thermal resistance simultaneously. AI accelerator designers at cloud service providers drive adoption, forcing assembly houses to retire thermocompression bonding capacity.
- 3D Integration:True vertical stacking with hybrid bonding enables memory-logic integration beyond interposer limitations. Japan's METI coordinates subsidies for substrate suppliers targeting mass production timelines.
- Chip-on-Wafer:Die placement on active or passive wafers supports heterogeneous integration for photonics modules. Silicon photonics integration in the United States creates demand for electrical-optical conversion at package level.
High-Density Interconnect dominates current shipment volumes; Direct Bonding is climbing the fastest as microbump architectures face pitch limitations.
Application:
End-use performance requirements dictate substrate material selection and thermal management complexity, with data center workloads justifying premium interposer costs.
- Data Centers:Training clusters mandate interposer-based architectures for GPU and AI accelerator deployment. Cloud operators in the United States and Taiwan compress supplier qualification cycles from 18 months to 9 months for second-source packaging houses.
- High-Performance Computing:Scientific computing and simulation workloads require memory bandwidth exceeding monolithic die limits. National laboratories in Germany and France anchor demand under EU Chips Act capacity buildout requirements.
- Mobile Devices:Handset form factors prioritize fan-out wafer level packaging for application processors and RF modules. South Korean electronics companies drive substrate cost reduction through consolidated procurement.
- Consumer Electronics:Gaming consoles and wearables balance performance against unit economics. Japanese OEMs qualify glass core substrate alternatives for coefficient-of-thermal-expansion matching.
Data Centers command the highest substrate allocation; High-Performance Computing is gaining share fastest as sovereign AI initiatives accelerate.
End User:
Procurement authority concentrates with entities controlling both silicon design and system integration, reshaping traditional OSAT-mediated supply chains.
- Semiconductor Manufacturers:Foundries with captive packaging capacity anchor supply security negotiations through direct substrate sourcing. Taiwan Semiconductor Manufacturing Company and Samsung Electronics leverage in-house CoWoS and I-Cube platforms respectively.
- OEMs:Hyperscale data center operators increasingly contract directly with interposer foundries, displacing traditional assembly and test provider relationships. This pattern concentrates volume commitments in Taiwan and South Korea.
- Electronics Companies:System integrators without captive silicon capacity rely on outsourced semiconductor assembly and test providers for advanced packaging access. REACH compliance requirements in Germany and France filter supplier selection.
- Telecom Providers:5G infrastructure and optical networking equipment drive silicon photonics packaging demand. Equipment vendors in the United States qualify 2.5D interposer platforms for coherent optical modules.
Semiconductor Manufacturers retain the largest committed capacity; OEMs are capturing procurement share fastest through direct sourcing agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AI accelerator procurement concentrates in jurisdictions with captive foundry capacity, redirecting packaging demand toward Taiwan, South Korea, and the United States. Government semiconductor incentives in each geography are reshaping where interposer substrates and advanced assembly capacity materialize.
Taiwan
CoWoS capacity exhaustion has triggered emergency expansion of interposer foundry operations. The National Development Council coordinates subsidies under the Chip Industry Development Program for domestic equipment procurement. Hsinchu Science Park anchors the highest concentration of 2.5D packaging cleanrooms, with second-source qualification cycles compressing to nine months.
South Korea
Memory-to-logic integration strength drives I-Cube platform deployment for high-bandwidth module assemblies. The Ministry of Trade, Industry and Energy directs K-Chips Act funding toward advanced substrate suppliers in Yongin and Pyeongtaek. Samsung Electronics leverages in-house packaging to secure supply security negotiations with hyperscale cloud operators.
United States
Domestic reshoring incentives from the Department of Commerce are accelerating cleanroom construction in Arizona and Oregon. NIST funding through the CHIPS Act requires domestic content thresholds for advanced packaging equipment. Intel Corporation's New Mexico and Oregon facilities anchor the western advanced packaging corridor.
Japan
Glass core substrate alternatives are qualifying for coefficient-of-thermal-expansion matching in consumer electronics modules. METI coordinates subsidies under the semiconductor national project for domestic lithography tool procurement. Kyushu and Nagoya industrial clusters host re-qualification programs for memory module assemblers.
Germany
EU Chips Act disbursements require REACH-compliant material flows for incentivized capacity buildout. The Federal Ministry for Economic Affairs directs funding toward Saxony and Bavaria cleanroom construction. Dresden's semiconductor cluster anchors sovereign AI initiative packaging demand from national laboratories.
2.5D IC Packaging Market Competitive Environment
Capacity expansion dominates the current landscape as CoWoS exhaustion forces buyers to qualify second-source packaging houses. The vendor base concentrates around foundry-captive operations and outsourced semiconductor assembly providers with billion-dollar cleanroom investments. Three archetypes define positioning: captive foundries controlling substrate supply, memory-integrated conglomerates leveraging vertical stack expertise, and scale-focused OSATs diversifying through fan-out wafer level services. Equipment lead time concentration and direct bonding technology refreshes constitute the dominant competitive moves reshaping assembly house economics.
Within the captive foundry tier, Taiwan Semiconductor Manufacturing Company and Samsung Electronics exemplify the integration archetype that anchors supply security negotiations through direct interposer sourcing. ASE Technology Holding occupies a position among scale-driven outsourced providers, representing the OSAT model that sustains competitiveness through fan-out wafer level packaging across multiple customer portfolios. Intel Corporation sits within the IDM-reshoring vector, exemplifying the western capacity expansion pattern driven by CHIPS Act disbursements.
| Leading Market Players |
|---|
| Samsung Electronics |
| Taiwan Semiconductor Manufacturing Company |
| Intel Corporation |
| ASE Technology Holding |
| Amkor Technology |
| Broadcom |
| Texas Instruments |
| United Microelectronics Corporation |
| JCET Group |
| Others |
Value Chain & Pricing Dynamics
Interposer-based packaging bifurcation from fan-out wafer level alternatives manifests in both pricing power concentration and supply chain configuration divergence. Premium CoWoS capacity commands long-term offtake commitments from hyperscale data center operators, while cost-sensitive automotive radar modules drive panel-level processing qualification in Germany and South Korea.
Pricing Analysis
Volume concentration in AI accelerator procurement against margin compression in mid-range inference chips defines the pricing landscape. Three-tier pricing structure across premium CoWoS, standard fan-out wafer level, and economy panel-level alternatives tracks lithography intensity and thermal management complexity. Cost compression in fan-out segments is intensifying because substrate material suppliers face REACH compliance premiums in EU-subsidized capacity buildouts. Hyperscale cloud operators exhibit the lowest price sensitivity, while automotive tier-one suppliers negotiate aggressively on panel-level processing contracts.
Supply Chain Analysis
Dual-sourcing mandates from NVIDIA and AMD are forcing second-source qualification cycles that restructure traditional foundry-OSAT relationships. Supply concentrates in Taiwan, South Korea, and the United States, with lithography systems and passive interposer wafers as critical dependencies. Single-source vulnerability in advanced packaging equipment from Japanese and Dutch vendors creates expansion bottlenecks. Distribution runs through direct sourcing agreements between hyperscale operators and interposer foundries, displacing traditional assembly and test provider mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CoWoS capacity exhaustion is consolidating procurement leverage with captive foundries, forcing outsourced semiconductor assembly and test providers into specialty packaging niches or acquisition targets.
For Market Incumbents: Lock in interposer substrate supply through multi-year offtake agreements with silicon wafer suppliers before equipment lead times extend further. Secure thermocompression bonding capacity replacement with hybrid bonding tool installations to defend against direct bonding technology displacement. Taiwan Semiconductor Manufacturing Company and Samsung Electronics anchor this consolidation pattern through captive packaging investments. For New Entrants and Emerging Players: Enter via automotive radar module packaging where panel-level processing qualification timelines remain accessible to non-captive providers. Target Germany and France under EU Chips Act subsidy flows for REACH-compliant capacity buildout. Qualify glass core substrate alternatives for consumer electronics OEMs seeking coefficient-of-thermal-expansion matching as the most penetrable entry vector. For Investors and Strategic Acquirers: Re-rating potential sits with scale-focused OSATs possessing existing fan-out wafer level infrastructure given hybrid bonding equipment refresh requirements. Long-term viability over the next decade hinges on backward integration into substrate supply or forward integration into test services. Watch for NIST funding disbursement velocity under the US CHIPS Act as the signal indicating domestic reshoring momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Equipment Refresh | Assembly houses in Taiwan and South Korea retire thermocompression capacity for copper-to-copper interfaces. |
| Interposer Substrate Multi-Sourcing | AI accelerator designers qualify second-source packaging houses to reduce CoWoS dependency. |
| Glass Core Substrate Qualification | Japanese memory module assemblers re-qualify processes for METI-subsidized domestic alternatives. |
| Direct Sourcing Agreement Expansion | Hyperscale operators in the United States bypass OSATs to contract captive foundry packaging directly. |
| REACH-Compliant Capacity Buildout | German and French facilities secure EU Chips Act disbursements through certified material flow documentation. |
Study Parameters
Independent corroboration across packaging process engineers, semiconductor procurement directors, and cleanroom equipment specialists underwrites the qualitative findings. Primary interviews with interposer foundry operations managers, OSAT business development leads, and substrate vendor sales executives combined with secondary validation from SEC 10-K filings, Department of Commerce CHIPS Act disbursement records, and METI subsidy announcements. Bottom-up capacity modeling and top-down demand triangulation from hyperscaler capex disclosures anchored the analysis.
Rate-of-change decomposition across technology migration timelines, equipment installation velocities, and subsidy disbursement schedules structured the forecast framework. Segmentation dimensions modeled include interposer versus fan-out architecture, high-density interconnect versus direct bonding technology, data center versus automotive application, and captive foundry versus outsourced provider end user type. CAGRs derived from installed capacity expansion curves weighted by equipment lead time constraints. Lithography system availability and silicon interposer wafer pricing volatility served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control expansion or lithography tool shipment delays. Deviation in CoWoS capacity expansion velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Test Services (OSAT) Market
Semiconductor Packaging
Asia-Pacific Quad-Flat-No-Lead Packaging Market
Semiconductor Packaging
IC Packaging and Testing Market
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Quad-Flat-No-Lead Packaging (QFN) Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
3D Semiconductor Packaging Market
Semiconductor Packaging
Global High-End Semiconductor Packaging Market