
 Global MEMS Packaging Market | 2026-2036
Global MEMS Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global MEMS Packaging Market Foresight
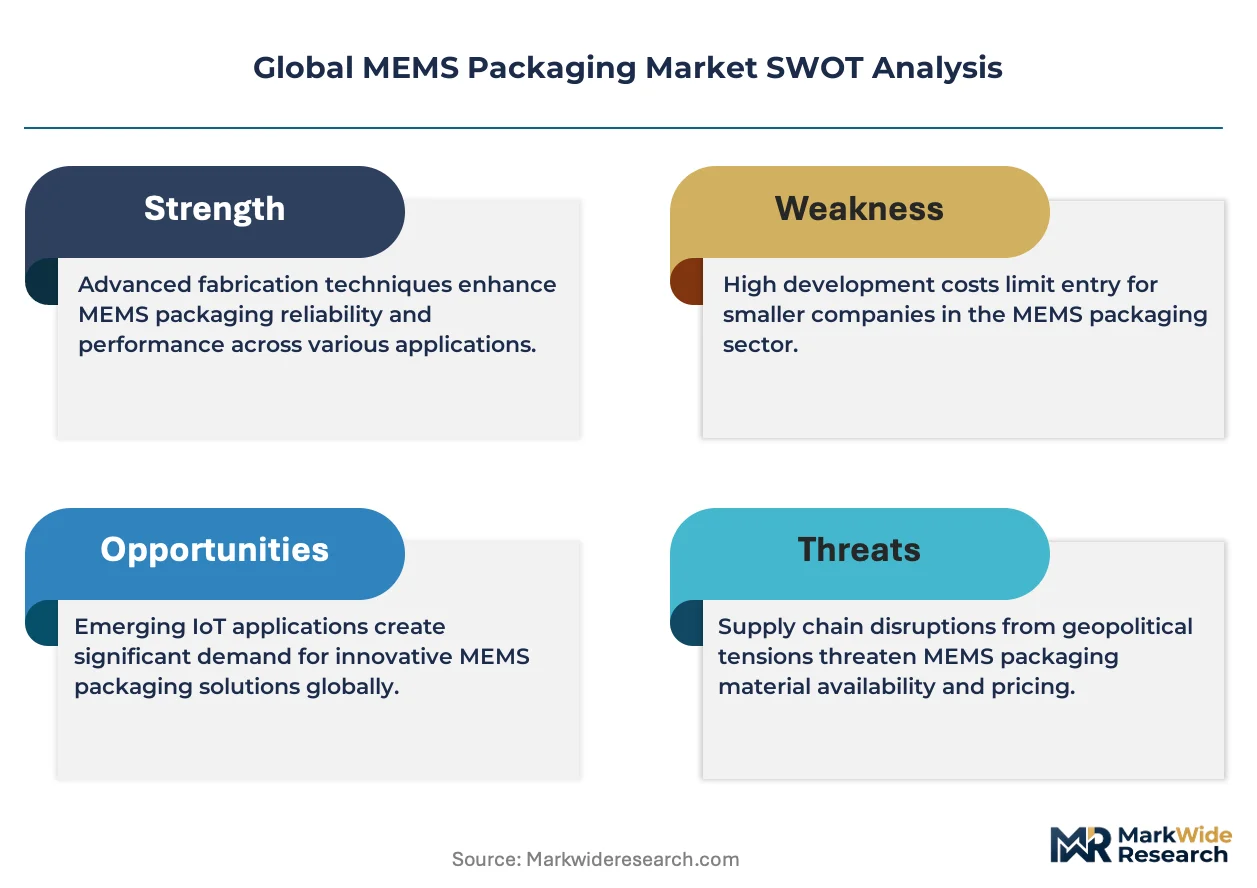
Software-defined calibration services for inertial measurement units is consolidating value around recurring revenue models rather than one-time hardware sales. Amkor Technology leverages its scale in system-in-package assembly to anchor high-volume consumer MEMS programs. ASE Group sustains competitive positioning through advanced fan-out wafer-level packaging capacity across multiple Asian manufacturing sites. Texas Instruments Incorporated specializes in integrating packaging with its captive MEMS fabrication, controlling margin capture from wafer through final test.
MEMS packaging encloses microelectromechanical systems in protective housings that maintain vacuum or controlled atmospheres, with hermeticity specifications often requiring helium leak rates below 5×10⁻⁸ atm·cc/s for gyroscopes and pressure sensors. The primary purpose is to shield delicate moving micromechanical structures from moisture, particulates, and thermal stress while enabling electrical interconnect to external circuits. Wafer-level packaging dominates unit economics for consumer accelerometers and microphones by enabling thousands of devices to be sealed simultaneously before dicing. System-in-package configurations are capturing margin in aerospace and defense applications where multi-sensor fusion demands heterogeneous integration of MEMS dies with ASICs and passive components. Ceramic packages retain structural importance in automotive underhood environments where junction temperatures exceed 150°C and hermetic integrity prevents corrosive gas ingress.
The U.S. FDA regulates MEMS-based medical implants through biocompatibility and sterilization validation requirements that extend packaging development timelines for pressure sensors and drug delivery devices. The EU MDR and REACH frameworks restrict hazardous substances in consumer-facing MEMS products, pushing medical device makers and automotive suppliers toward lead-free solder alternatives and halogen-free mold compounds. Japan's METI enforces JIS standards for automotive reliability that OEMs and tier-one suppliers reference when qualifying MEMS barometers and tire pressure monitors. Stakeholders must monitor how evolving automotive functional safety standards and medical device traceability mandates reshape qualification protocols and supplier certification burdens.
Market Dynamics
Hermetic packaging specifications for automotive LiDAR and inertial sensors are tightening as OEMs push functional safety requirements toward ASIL-D levels, forcing suppliers to requalify ceramic and metal packages for helium leak rates below 5×10⁻⁹ atm·cc/s.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating conversion from traditional sealing processes to laser-activated glass frit bonding in pressure sensor packages.
- LiDAR sensor proliferation:Automotive Tier-1 suppliers in Germany and Japan are qualifying wafer-level vacuum packages for solid-state LiDAR emitters, creating pull for anodic bonding capacity.
- Silicon interposers:Fan-out wafer-level packaging with embedded passive integration is expanding into consumer IMUs, compressing z-height while maintaining hermetic integrity.
Market Restraints
- Palladium price volatility:Thick-film metallization on ceramic packages relies on palladium-gold conductor systems, exposing mid-tier suppliers to precious metal cost swings.
- Japan equipment concentration:Precision dicing and pick-and-place tools for thin-wafer handling concentrate among Tokyo and Osaka-based equipment makers, creating single-source risk.
- Glass transition temperature limits:Epoxy mold compounds face hard boundaries above 175°C junction temperatures, excluding them from powertrain-adjacent sensor modules.
Strategic Opportunities
- India automotive electronics:The PLI scheme for semiconductor packaging is attracting test and assembly investments for tire pressure monitoring systems targeting domestic OEMs.
- Photonic integration:MEMS mirrors for optical switching are converging with silicon photonics, opening heterogeneous packaging demand from datacom equipment manufacturers.
- EU MDR traceability mandates:Implantable pressure sensors now require lot-level serialization, creating attach opportunities for packaging houses with laser-marking and blockchain integration capabilities.
Industry Challenges
- Reliability physics expertise:Finite element modeling of thermomechanical stress in multi-material stacks requires specialists combining MEMS process knowledge with packaging simulation tools.
- Automotive qualification timelines:AEC-Q100 Grade 0 certification for underhood pressure sensors extends development cycles to 24-36 months, straining R&D amortization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global MEMS Packaging Market |
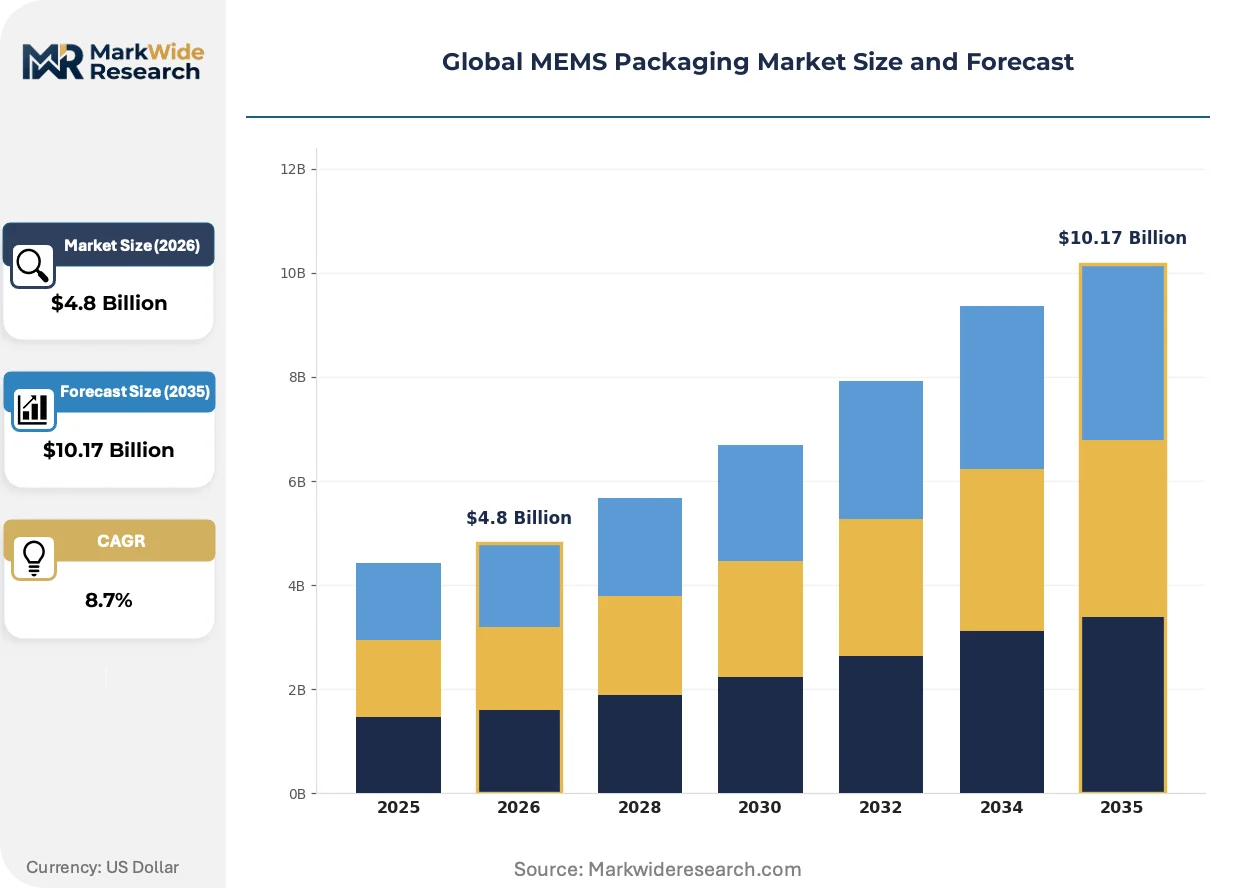
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Package Type: Wafer Level, Multi-Chip Module, System in Package, Fan-Out, Chip Scale, Ceramic Technology: Surface Micromachining, Bulk Micromachining, LIGA, Wafer Bonding, Electroplating, Dry Etching Application: Consumer Electronics, Aerospace & Defense, Industrial Automation, Telecommunications, Environmental Sensing, Wearable Devices End User: OEMs, System Integrators, Research Institutes, Automotive Suppliers, Medical Device Makers, Semiconductor Foundries |
| Companies Covered | Amkor Technology, ASE Group, STMicroelectronics, Texas Instruments Incorporated, Infineon Technologies AG, Robert Bosch GmbH, Analog Devices Inc., TDK Corporation, ChipMos Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global MEMS Packaging Market Shifts & Advancements
Packaging architectures are fragmentating across thermal performance tiers, with vacuum-encapsulated gyroscopes diverging from overmolded consumer accelerometers in process equipment, materials, and supplier bases.
Through-silicon vias with aspect ratios exceeding 20:1 are expanding into inertial measurement unit stacking, enabling z-axis gyroscope integration without wire bond loops. Automotive safety module makers in South Korea are adopting these interposers for camera-stabilization packages. The technology is expanding into medical endoscopy, where hermetic TSV arrays now seal CMOS imagers against autoclave sterilization cycles.
REACH restrictions on lead and cadmium in consumer electronics are forcing mold compound reformulation across European-bound MEMS microphone shipments. ECHA substance-of-very-high-concern listings now cover specific brominated flame retardants used in epoxy packaging. German automotive suppliers are responding by qualifying halogen-free green molding compounds for cabin humidity sensors, ahead of anticipated MDR alignment.
Sensor fusion modules are compressing procurement decisions from discrete component sourcing to subsystem-level supplier selection. Tier-1 automotive buyers in Japan now specify barometer-IMU-ASIC combinations as single line items. This consolidation concentrates volume with packaging houses capable of fan-out wafer-level integration, marginalizing wire-bond-only suppliers in Nagoya and Hiroshima prefectures.
Global MEMS Packaging Market Segmentation
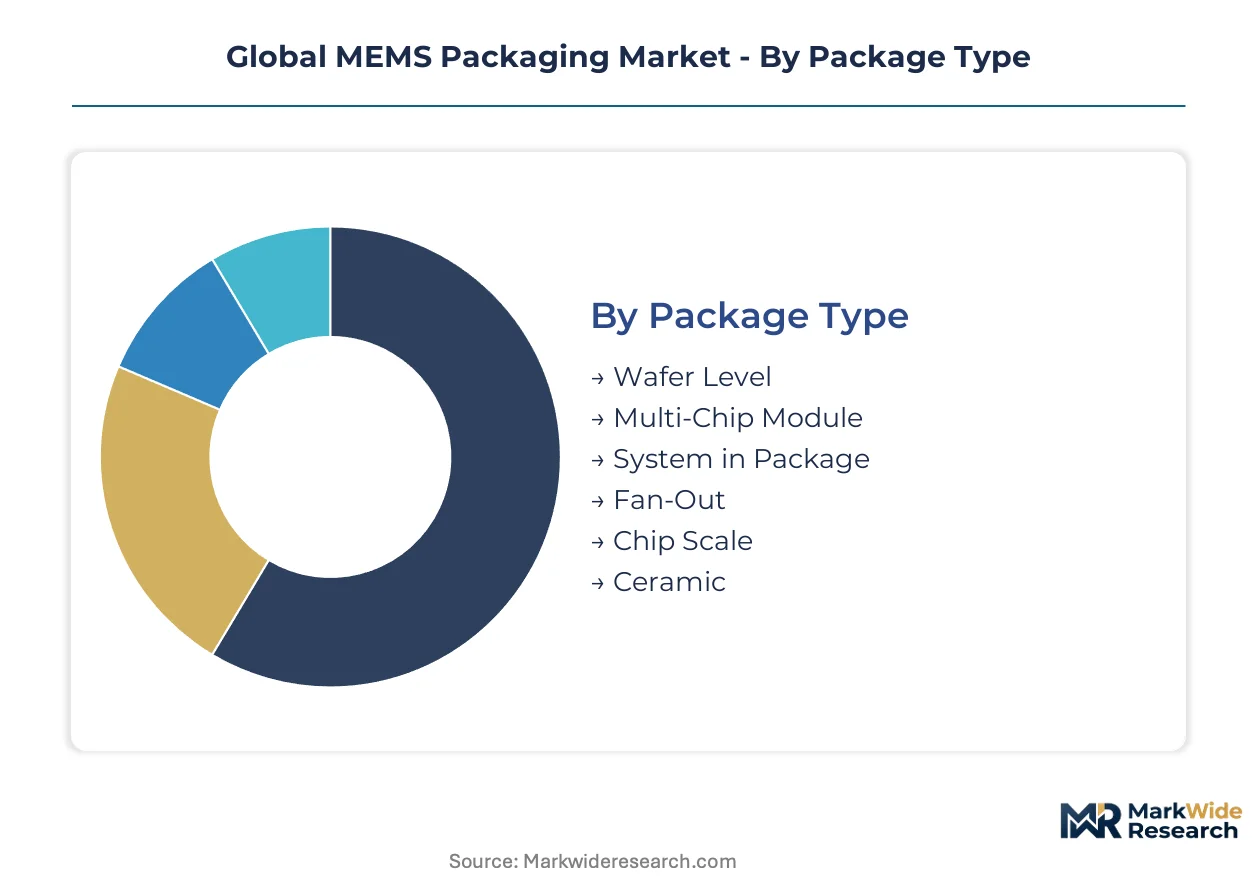
Packaging architecture selection determines thermal budgets, hermetic integrity thresholds, and unit economics across MEMS applications. Process technology choices constrain which package formats remain viable for specific device geometries. End-user procurement power and qualification timelines further stratify supplier access across segments.
Package Type:
Supply concentration clusters around formats enabling high-volume wafer-scale sealing versus specialized ceramic hermetic solutions for extreme environments.
- Wafer Level:Simultaneous encapsulation of thousands of dice before singulation dominates consumer accelerometer and microphone production. South Korean foundries anchor capacity for smartphone OEMs demanding sub-millimeter z-height profiles.
- System in Package:Heterogeneous stacking of MEMS dies with ASICs and passives captures margin in automotive safety modules where multi-sensor fusion is mandatory. German Tier-1 suppliers specify SiP configurations for LiDAR receiver arrays.
- Fan-Out:Embedded passive integration compresses footprint for wearable inertial measurement units.
- Multi-Chip Module:Ceramic substrate-based stacking persists in aerospace gyroscopes requiring radiation tolerance.
- Chip Scale:Near-die-size encapsulation serves cost-constrained environmental sensors.
- Ceramic:Alumina and aluminum nitride packages retain dominance for pressure sensors in powertrain-adjacent locations where junction temperatures exceed 150°C.
Wafer-level formats absorb the bulk of installed capacity; fan-out configurations are expanding most quickly.
Technology:
Process maturity and equipment availability determine which fabrication routes achieve commercial scale versus remaining confined to research or defense applications.
- Surface Micromachining:Sacrificial oxide release processes enable complex mechanical structures in accelerometers and gyroscopes. Japanese equipment makers dominate the deposition and etch tools for this technology.
- Bulk Micromachining:Deep reactive ion etching of silicon substrates produces high-aspect-ratio structures for pressure sensors and inkjet nozzles. German automotive suppliers specify bulk-micromachined piezoresistive elements for tire pressure monitors.
- Wafer Bonding:Anodic and glass-frit sealing creates vacuum cavities for resonant structures. EU F-Gas Regulation compliance is accelerating laser-activated glass frit adoption over traditional sealing methods.
- LIGA:Synchrotron-based lithography and electroforming produces metallic microstructures for specialized optical applications.
- Electroplating:Thick nickel and copper deposition forms magnetic components and interconnect traces.
- Dry Etching:Plasma-based material removal defines sidewall profiles for capacitive sensing elements.
Bulk micromachining commands the largest share of automotive-qualified capacity; wafer bonding is climbing the fastest on LiDAR sensor demand.
Application:
Volume concentration versus performance requirements fragment packaging specifications across end-use domains.
- Consumer Electronics:Smartphone and tablet integration drives the highest unit volumes for accelerometers, gyroscopes, and microphones. Chinese OEMs specify wafer-level packaged microphones in 8-10 device arrays per handset.
- Aerospace & Defense:Radiation-hardened and hermetic specifications for satellite and munition applications command premium pricing. US defense contractors require MIL-STD-883 qualification for inertial navigation units.
- Automotive:Functional safety requirements through ASIL-D levels impose traceability and failure rate specifications on packaging houses. Japanese OEMs are consolidating barometer-IMU-ASIC procurement into single subsystem awards.
- Industrial Automation:Vibration sensors and flow meters demand IP-rated encapsulation for factory floor deployment.
- Telecommunications:Optical MEMS switches and tunable filters require sub-micron alignment precision in packaging.
- Environmental Sensing:Gas and humidity sensors for smart city infrastructure specify low-cost overmolded packages.
- Wearable Devices:Miniaturized biometric sensors combine photonic and MEMS elements in fan-out configurations.
Consumer electronics absorbs the bulk of installed capacity; wearable devices represent the steepest expansion trajectory.
End User:
Procurement authority and qualification burden distribution determine which supplier tiers capture value across the demand base.
- Automotive Suppliers:Tier-1 module makers specify packaging requirements for tire pressure monitors, LiDAR, and inertial sensors. German and Japanese suppliers are qualifying new ceramic package sources to reduce palladium cost exposure.
- OEMs:Consumer electronics and industrial equipment manufacturers with captive packaging capabilities internalize high-volume programs. South Korean smartphone OEMs operate dedicated fan-out lines for flagship device sensors.
- Medical Device Makers:FDA and EU MDR compliance requirements extend packaging development timelines for implantable pressure sensors and drug delivery devices.
- System Integrators:Subsystem assemblers without captive fabrication source packaged MEMS from merchant houses.
- Semiconductor Foundries:Pure-play fabs offer packaging as value-added service for fabless MEMS designers.
- Research Institutes:Academic and government laboratories prototype novel packaging approaches before commercial transfer.
Automotive suppliers command the largest share of qualified capacity; medical device makers are gaining share fastest on implantable sensor demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in East Asian manufacturing clusters while consumption pulls strongest from German automotive engineering centers and US medical device corridors. This geographic split shapes logistics networks and qualification protocol harmonization challenges.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich are qualifying lead-free ceramic packages for LiDAR and pressure sensors under KBA functional safety guidelines. The EU F-Gas Regulation accelerates laser-activated glass frit bonding adoption at Dresden-area packaging facilities. Bavarian precision engineering clusters anchor hermetic packaging R&D for ASIL-D sensor modules.
Japan
METI-enforced JIS standards drive qualification timelines for tire pressure monitors and barometers supplied to Toyota and Honda. Nagoya-area packaging houses specialize in wafer-level vacuum encapsulation for inertial measurement units. Osaka equipment makers concentrate precision dicing tools for thin-wafer MEMS handling.
United States
FDA biocompatibility requirements extend development cycles for implantable pressure sensors and drug delivery devices. Texas and Arizona host captive packaging operations tied to defense contractors requiring MIL-STD-883 qualification. Boston medical device corridors demand lot-level serialization for traceability compliance.
South Korea
Seoul Capital Area smartphone OEMs operate dedicated fan-out wafer-level packaging lines for flagship device sensors. Busan-Ulsan automotive module makers adopt through-silicon via interposers for camera-stabilization packages. Government semiconductor packaging incentives attract test and assembly investments for consumer MEMS programs.
India
The PLI scheme for semiconductor packaging draws tire pressure monitoring system assembly investments targeting domestic OEMs like Tata Motors and Mahindra. Karnataka and Tamil Nadu electronics manufacturing zones host emerging MEMS test facilities. CDSCO medical device regulations are aligning with EU MDR traceability standards for implantable sensors.
Global MEMS Packaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures. Integrated device manufacturers with captive fabrication anchor high-reliability automotive and aerospace segments, while merchant packaging houses capture scale in consumer electronics. Three archetypes dominate: foundry-linked assemblers with system-in-package expertise, IDMs controlling wafer-to-test vertical chains, and regional specialists serving qualification-intensive medical and defense niches. Competitive dynamics center on capacity expansion in fan-out wafer-level formats and strategic partnerships for heterogeneous integration.
Within the integrated device manufacturer tier, Texas Instruments Incorporated and Robert Bosch GmbH exemplify vertical control from MEMS fabrication through final test. STMicroelectronics occupies a position bridging merchant and captive models with European automotive qualification strength. Among Asia-Pacific packaging specialists, Amkor Technology and ASE Group anchor high-volume consumer programs through system-in-package and fan-out wafer-level capacity. These five entities collectively represent the competitive spectrum from IDM margin capture to foundry-linked scale assembly.
| Leading Market Players |
|---|
| Amkor Technology |
| ASE Group |
| STMicroelectronics |
| Texas Instruments Incorporated |
| Infineon Technologies AG |
| Robert Bosch GmbH |
| Analog Devices Inc. |
| TDK Corporation |
| ChipMos Technologies Inc. |
| Others |
Supply & Pricing Matrix
Captive packaging integration at IDMs like Texas Instruments and Robert Bosch anchors pricing power through wafer-to-test margin control, while merchant houses compete on scale economies in consumer-facing wafer-level formats. This structural split concentrates premium pricing in automotive and medical hermetic segments while compressing margins in high-volume smartphone sensor programs.
Pricing Analysis
Margin tightening in ceramic hermetic packages reflects palladium-gold conductor cost volatility and extended AEC-Q100 Grade 0 qualification timelines. Three-tier pricing structure across ASIL-D automotive, industrial-grade, and consumer-level certification tiers separates German Tier-1 procurement from Chinese smartphone OEM sourcing. Cost-down pressure on wafer-level formats accelerates because South Korean foundries are expanding fan-out capacity for flagship device sensors. Automotive suppliers exhibit lowest price sensitivity due to functional safety liability exposure, while environmental sensor buyers in smart city infrastructure demand commodity-level unit economics.
Supply Chain Analysis
Precision dicing and pick-and-place equipment rests on Tokyo and Osaka-based equipment makers, creating single-source vulnerability for thin-wafer MEMS handling. Raw material dependencies center on palladium-gold thick-film metallization systems, high-purity alumina ceramic substrates, and halogen-free epoxy mold compounds. Palladium price volatility and Japan equipment concentration generate structural exposure to precious metal cost swings and geographic supply disruption. Distribution runs through Tier-1 automotive module makers in Germany and Japan who specify packaging requirements, alongside captive OEM lines in South Korea for consumer electronics programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over wafer bonding and hermetic sealing capacity determines margin capture from automotive LiDAR and medical implant programs.
For Market Incumbents: Extend fan-out wafer-level packaging capacity in South Korea and Taiwan to anchor high-volume consumer programs against ASE Group and Amkor Technology scale advantages. Defend automotive hermetic positioning by qualifying lead-free ceramic packages ahead of EU MDR alignment and REACH substance restrictions. Certification investment in AEC-Q100 Grade 0 and MIL-STD-883 pathways protects premium pricing against emerging Asian packaging houses. For New Entrants and Emerging Players: Direct-to-designer digital channels for fabless MEMS startups bypass incumbent qualification barriers in automotive and medical segments. Target India's PLI-supported semiconductor packaging zones for tire pressure monitoring system assembly serving Tata Motors and Mahindra. Photonic integration for datacom MEMS mirrors offers the most penetrable white-space given silicon photonics convergence trends and heterogeneous packaging demand from equipment manufacturers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by IDMs seeking captive packaging integration or by foundry-linked assemblers filling fan-out capacity gaps. Long-term viability favors packaging houses with AEC-Q100 and FDA dual-certification capabilities spanning automotive safety modules and implantable sensors. Watch laser-activated glass frit bonding adoption rates as inflection indicator for EU F-Gas Regulation compliance-driven equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Fan-Out Wafer-Level Capacity Expansion | South Korean smartphone OEMs demand sub-millimeter z-height profiles for flagship sensors. |
| Laser-Activated Glass Frit Bonding Adoption | Dresden-area facilities convert from traditional sealing to meet EU F-Gas phasedown mandates. |
| Lead-Free Ceramic Package Qualification | German Tier-1 suppliers reduce palladium cost exposure while maintaining ASIL-D hermetic integrity. |
| Through-Silicon Via Interposer Integration | Busan-Ulsan automotive module makers adopt TSV stacking for camera-stabilization packages. |
| Blockchain-Enabled Lot Serialization | Boston medical device corridors require traceability compliance for implantable pressure sensors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with MEMS packaging engineering directors, automotive Tier-1 procurement managers, medical device regulatory affairs leads, and semiconductor foundry operations heads. FDA 510(k) submissions, EU MDR technical documentation, METI JIS standard registrations, and Korea Customs Service import records provided validation triangulation against bottom-up capacity estimates and top-down demand modeling.
Granularity-level modeling deployed package-type, technology process, application end-use, and geographic production cluster dimensions at the country level across the analysis window. CAGRs derived from shipment volume trajectories by format, cross-referenced with capital expenditure disclosures from packaging equipment makers and foundry capacity announcements. Forecast inputs incorporated AEC-Q100 qualification timeline data and EU F-Gas Regulation compliance phase schedules.
The model holds under stable palladium pricing and continued automotive functional safety standard harmonization; deviation in precious metal cost spikes or REACH substance restriction acceleration would shift ceramic package economics. A small set of named triggers warrants ongoing watch: Japan equipment export restrictions, FDA biocompatibility guideline revisions, and India PLI scheme disbursement pacing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
IC Packaging and Testing Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Test Services (OSAT) Market
Semiconductor Packaging
Ball Grid Array (BGA) Packaging Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Global Bare Die Shipping and Handling and Processing and Storage Market
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
3D IC Packaging Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
3D TSV Packages Market