
 3D Bioprinting Market | 2026-2036
3D Bioprinting Market Size, Share, and Industry Trends Forecast 2026-2036
3D Bioprinting Market Intelligence
The emergence of specialized bioink producers is restructuring the supply chain for 3D bioprinting, creating new opportunities for material innovation. BICO Group AB leverages its broad portfolio of printers and consumables to serve diverse research needs. Organovo Holdings Inc. specializes in developing therapeutic tissues for clinical applications. 3D Systems Inc. competes by integrating its hardware with advanced software for medical device prototyping.
3D bioprinting is an additive manufacturing technique that precisely deposits bioinks, which are materials containing living cells, to fabricate complex biological structures. Its primary purpose is to create functional tissue models for drug discovery and to engineer tissues for the field of regenerative medicine. Extrusion bioprinting technology currently dominates due to its versatility with various bioink viscosities. Within applications, tissue engineering represents the largest segment, while drug testing models show rapid adoption by pharmaceutical companies.
Regulatory frameworks from the US FDA, Europe's EMA, and Japan's PMDA govern the clinical translation of bioprinted products. These agencies' guidelines on good manufacturing practices and material biocompatibility directly shape market access for therapeutic applications. Stakeholders must now decide whether to prioritize near-term revenue from research and drug testing models or invest in the long-term, high-risk pathway of clinical organ fabrication.
Market Dynamics
The strategic divergence between near-term research applications and long-term clinical organ fabrication defines the market's core tension. Stakeholder investment decisions are shaped by the clear revenue from pharmaceutical drug testing models versus the high-risk, high-reward pathway of developing therapeutic tissues under stringent regulatory oversight.
Growth Catalysts
- Bioink Innovation:Advances in biocompatible and functional bioinks are enabling the fabrication of more complex and physiologically relevant tissue structures, expanding research and therapeutic possibilities.
- Pharmaceutical Adoption:Pharmaceutical companies are increasingly utilizing bioprinted tissue models for preclinical drug screening, seeking more accurate and human-relevant data to reduce failure rates in later trial stages.
- R&D Hub Concentration:Dedicated research and development ecosystems within the United States and Germany provide a critical mass of talent, funding, and institutional collaboration that accelerates technological progress.
Market Restraints
- High Capital & Material Costs:The substantial expense of precision bioprinters and specialized, cell-grade bioinks creates a significant financial barrier to entry for smaller research institutions and startups.
- Vascularization Complexity:A major technical limitation is the inability to effectively create stable, perfusable vascular networks within larger printed tissues, which is essential for their long-term viability and function.
- Regulatory Pathway Ambiguity:While frameworks from the FDA and EMA are evolving, the long, expensive, and uncertain path to clinical approval for therapeutic bioprinted products deters investment in regenerative medicine applications.
Strategic Opportunities
- Personalized Medicine:The development of patient-specific tissue models using a patient's own cells offers a significant opportunity for personalized drug screening and disease modeling.
- AI-Driven Design:Integrating artificial intelligence and machine learning algorithms with bioprinting systems can optimize tissue scaffold design and printing parameters, accelerating development and improving reproducibility.
- Emerging Market Investment:Government initiatives and increased healthcare spending in certain Asia-Pacific countries are creating new opportunities for market entry and collaboration in the field of regenerative medicine.
Industry Challenges
- Lack of Standardization:The absence of universally accepted standards for bioink characterization, printing protocols, and quality control metrics hinders the comparability and reproducibility of results across different labs.
- Interdisciplinary Talent Scarcity:A shortage of professionals with combined expertise in cell biology, material science, and additive manufacturing engineering constrains innovation and operational scaling.
- Manufacturing Scalability:Transitioning bioprinting processes from a lab-scale, one-off fabrication model to an automated, high-throughput manufacturing workflow for commercial production remains a significant operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Bioprinting Market |
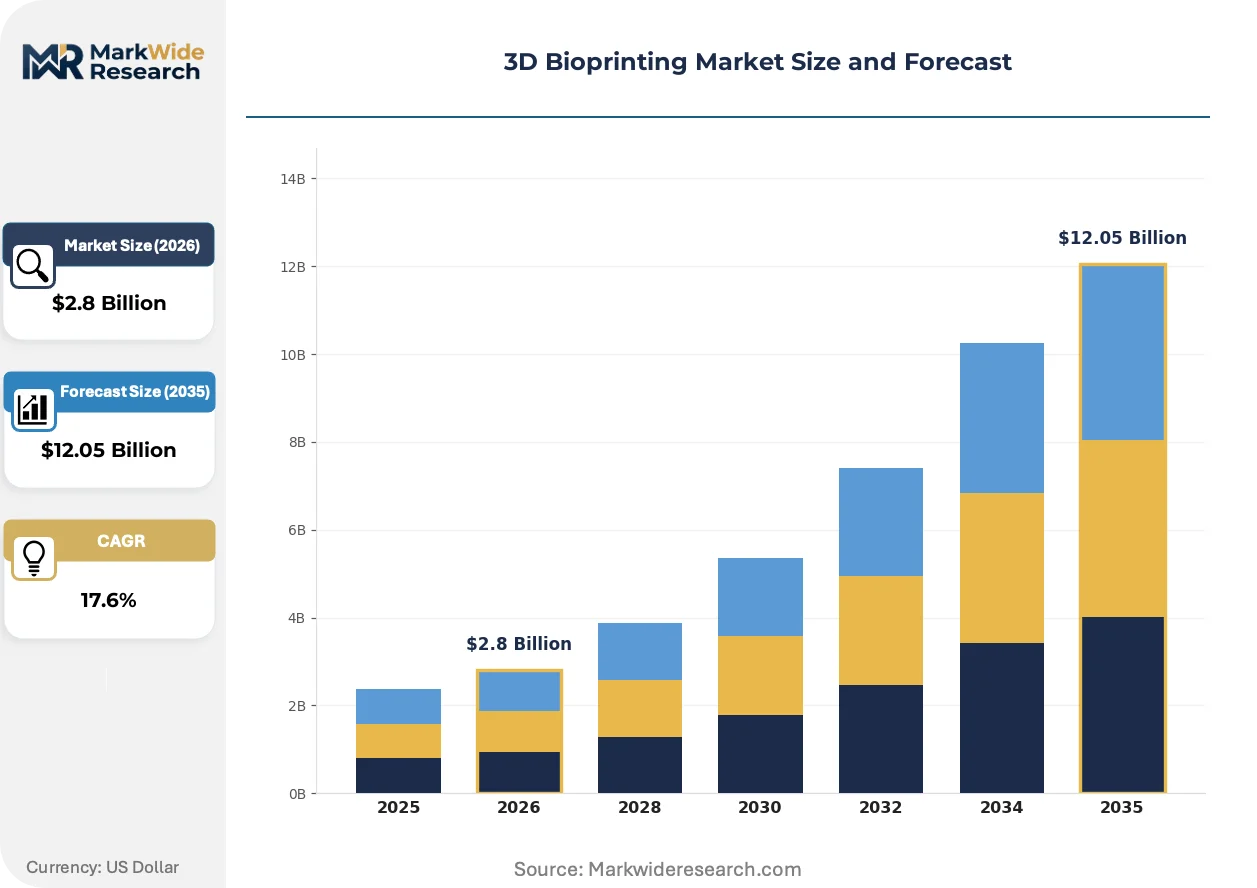
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.05 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Inkjet Bioprinting, Laser-Assisted Bioprinting, Extrusion Bioprinting, Stereolithography, Microvalve Bioprinting Application: Tissue Engineering, Drug Testing Models, Organ Fabrication, Cancer Research, Cosmetic Testing Product Type: Bioprinters, Bioinks, Software Platforms, Consumables End User: Research Institutions, Pharmaceutical Companies, Biotechnology Firms, Academic Labs, Regenerative Clinics |
| Companies Covered | BICO Group AB, 3D Systems Inc., Organovo Holdings Inc, Merck KGaA, Aspect Biosystems Ltd, Cyfuse Biomedical K.K, regenHU, Collplant Biotechnologies Ltd, Rokit Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Bioprinting Market Strategic Shifts & Innovations
Material science advancements and computational modeling are fundamentally altering the market's trajectory. These forces are enabling a critical shift from fabricating simple cellular monolayers to engineering complex, multi-cellular constructs that more accurately mimic native human tissue function.
Advanced bioinks with precisely tunable properties, such as sacrificial or stimuli-responsive hydrogels, provide greater control over the fabrication process. Research institutions and pharmaceutical R&D units are rapidly adopting these materials for creating sophisticated microphysiological systems. This new material capability is absorbing the limitations of earlier, simpler bio-hydrogels, enabling the creation of perfusable vascular channels and more biomimetic architectures.
Evolving guidelines from regulatory bodies like the US FDA, Europe's EMA, and Japan's PMDA are establishing clearer pathways for Advanced Therapy Medicinal Products. This regulatory maturation, while stringent, provides a more defined route for the clinical translation of bioprinted tissues and implants. The regenerative medicine segment is most affected, aligning its quality management systems and manufacturing practices with emerging Good Manufacturing Practice standards for cell-based therapies.
A distinct shift is occurring from purchasing standalone equipment to acquiring fully integrated workflow solutions. This trend disrupts the component-based sales model, favoring suppliers who provide a validated package of hardware, bio-validated software, and pre-formulated bioink kits. This procurement pattern is most prominent within pharmaceutical and contract research organizations, where protocol standardization and result reproducibility are essential for drug discovery and toxicology screening.
3D Bioprinting Market Segmentation
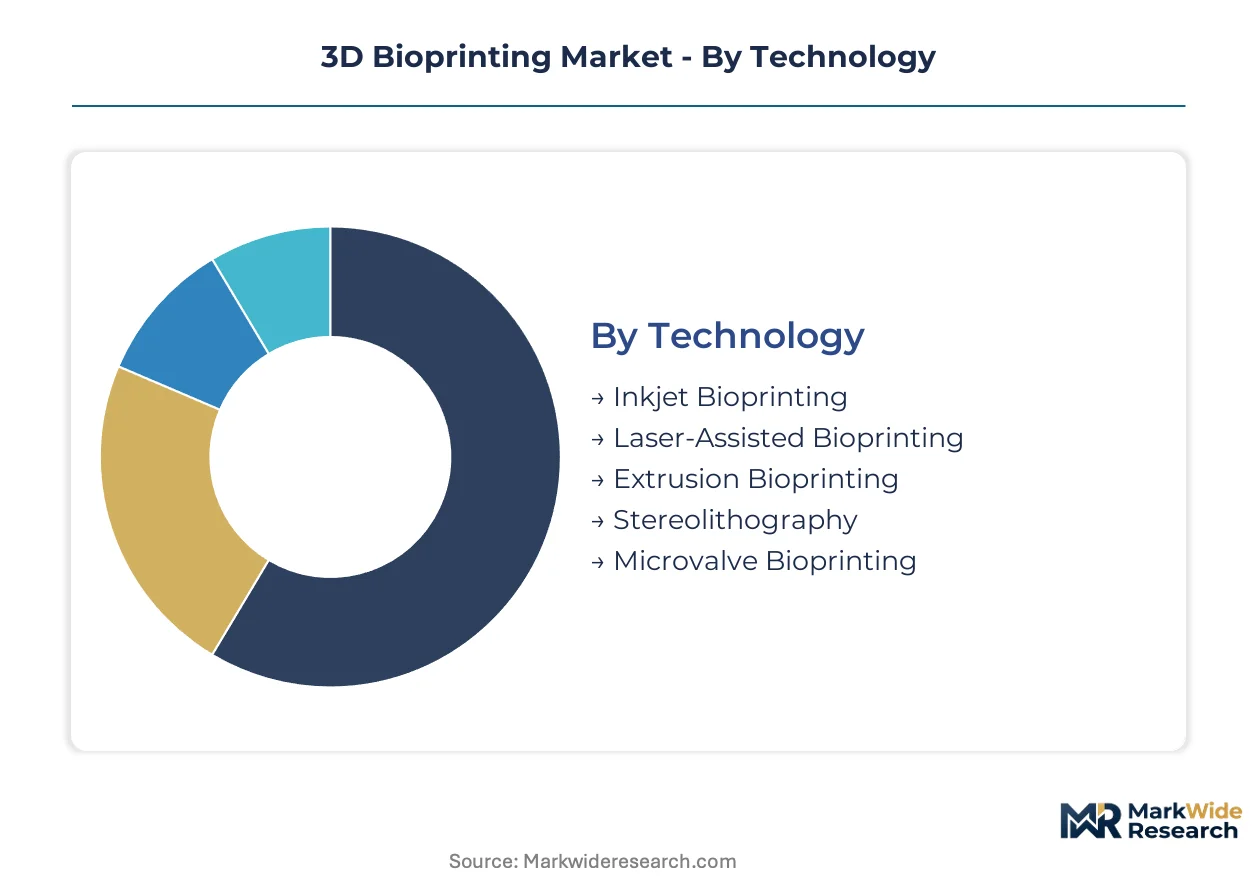
The 3D bioprinting market segments define distinct operational focuses and technological preferences across its diverse applications. Understanding these categories is crucial for identifying areas of concentrated investment and emerging demand. Each segment reflects unique requirements for precision, material compatibility, and regulatory compliance.
Technology:
The choice of bioprinting technology often differentiates buyers based on their required resolution, cell viability, and material versatility.
- Extrusion Bioprinting:This technology precisely deposits bioink filaments using pneumatic or mechanical forces, accommodating a wide range of viscosities. Pharmaceutical companies commonly use this for creating drug testing models due to its versatility with various bioinks.
- Stereolithography:Stereolithography systems cure photo-crosslinkable bioinks with focused light, enabling high-resolution and complex 3D structures. Research institutions leverage this for intricate tissue engineering applications demanding precise spatial control.
- Inkjet Bioprinting:Inkjet bioprinting ejects bioink droplets with high speed and precision, suitable for low-viscosity materials and high-throughput applications.
- Laser-Assisted Bioprinting:This method uses laser pulses to transfer bioink, offering high cell viability and precise patterning for thin layers.
- Microvalve Bioprinting:Microvalve bioprinting utilizes precise valve control to dispense bioink droplets, allowing for high resolution and cell density.
Volume sits with Extrusion Bioprinting; growth tilts toward Stereolithography.
Application:
Application areas are defined by the biological objective, ranging from fundamental research to clinical translation efforts.
- Tissue Engineering:Tissue engineering focuses on creating functional biological constructs to repair, replace, or enhance damaged tissues and organs. Academic labs and biotechnology firms drive demand for complex tissue models for regenerative medicine research.
- Drug Testing Models:Drug testing models utilize bioprinted tissues to mimic human physiological responses for preclinical drug screening and toxicology assessment. Pharmaceutical companies are rapidly adopting these models to improve drug discovery accuracy.
- Organ Fabrication:Organ fabrication aims to bioprint entire functional organs for transplantation, representing a long-term, high-risk pathway under stringent regulatory oversight.
- Cancer Research:Bioprinting supports cancer research by creating complex 3D tumor models, enabling more accurate study of tumor microenvironments and drug efficacy.
- Cosmetic Testing:Bioprinted skin models provide ethical and accurate platforms for cosmetic product development and safety testing, reducing reliance on animal trials.
Tissue Engineering maintains the largest share; Drug Testing Models represent the fastest-growing trajectory.
Product Type:
Product types are categorized by their function within the bioprinting workflow, from foundational hardware to essential consumables.
- Bioinks:Bioinks are specialized materials containing living cells and biomolecules, designed for precise deposition and structural integrity. Material science advancements are leading to complex, stimuli-responsive bioinks for advanced tissue constructs.
- Bioprinters:Bioprinters are precision additive manufacturing systems that accurately deposit bioinks layer by layer. Research institutions and pharmaceutical R&D units require diverse printer capabilities for experimental flexibility.
- Software Platforms:Software platforms provide design tools, print parameter control, and data analysis capabilities essential for optimizing bioprinting processes.
- Consumables:Consumables include sterile disposables, cell culture media, and other ancillary materials necessary for bioprinting operations.
Bioprinters represent the foundational equipment; Bioinks are experiencing the most intense innovation.
End User:
End-user segments reflect the primary institutional focus and funding mechanisms driving bioprinting adoption.
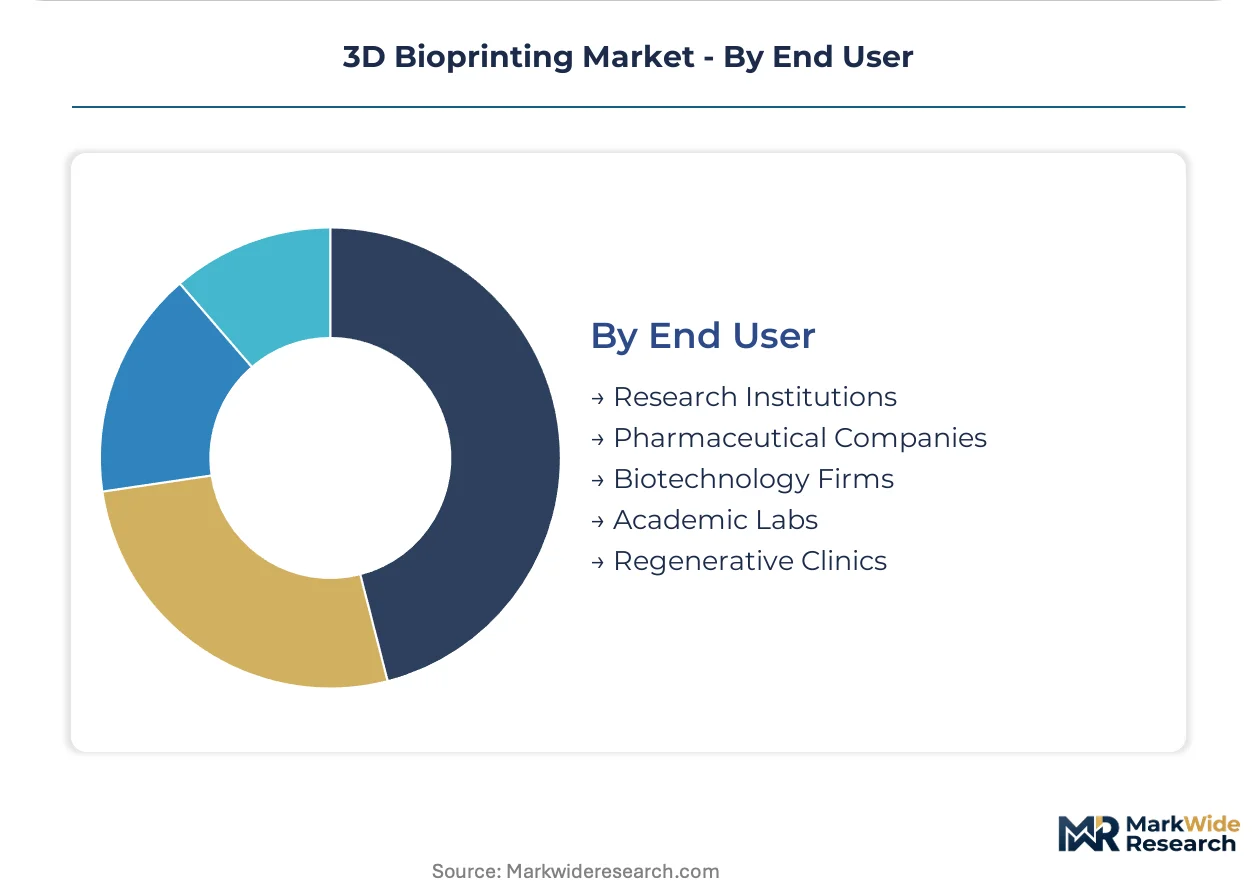
- Research Institutions:Research institutions encompass universities and government labs utilizing bioprinting for fundamental biological studies and proof-of-concept development. These entities drive early-stage innovation across various bioprinting applications.
- Pharmaceutical Companies:Pharmaceutical companies employ bioprinting to create human-relevant tissue models for preclinical drug screening and toxicity testing. Their adoption reduces animal testing and improves the predictive power of drug discovery.
- Biotechnology Firms:Biotechnology firms leverage bioprinting for developing novel therapeutic products and advanced cell-based assays.
- Academic Labs:Academic labs utilize bioprinting for educational purposes and exploratory research into new materials and methodologies.
- Regenerative Clinics:Regenerative clinics represent a nascent segment focused on translating bioprinted tissues into clinical therapies for patients.
Research Institutions currently drive broader adoption; Pharmaceutical Companies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany anchor significant bioink innovation, a critical feedstock for advanced 3D bioprinting applications. These regions drive the development of complex tissue structures for both research and potential therapeutic uses. Global demand for these specialized materials is expanding rapidly.
United States
Pharmaceutical companies in the United States increasingly demand bioprinted tissue models for preclinical drug screening and toxicology assessment. The US FDA provides evolving guidelines for good manufacturing practices, shaping market access for therapeutic bioprinted products. Boston's vibrant biotech corridor actively fosters advanced bioink development and integrated bioprinting solutions.
Germany
German research institutions spearhead advancements in regenerative medicine and specialized bioink production for complex tissue engineering. Europe's EMA frameworks for Advanced Therapy Medicinal Products guide the clinical translation of bioprinted constructs. Munich's leading research institutes actively collaborate on engineering multi-cellular tissue structures.
Japan
Japanese academic centers pursue clinical translation of bioprinted products, alongside extensive fundamental research efforts. The PMDA's evolving guidelines for medical devices establish clearer pathways for novel bioprinting technologies. Tokyo's medical technology firms concentrate on patient-specific tissue models for personalized medicine applications.
China
Chinese government initiatives are boosting healthcare spending and R&D investment in bioprinting for tissue repair and drug discovery. The NMPA's stringent standards for medical device approval influence product development and market entry. Shanghai's burgeoning bio-industrial parks support manufacturing scalability for bioprinted constructs.
United Kingdom
Academic laboratories in the United Kingdom conduct extensive research into tissue engineering and innovative drug discovery platforms. The UK's MHRA provides oversight for clinical trials involving advanced bioprinted therapies. Cambridge's renowned bioscience cluster advances multi-cellular construct development and functional validation.
3D Bioprinting Market Key Industry Players
Global majors compete with regional champions across core technology platforms and bioink innovation, defining the 3D bioprinting market structure. This landscape includes integrated solution providers, specialized bioink developers, and therapeutic tissue engineering firms. Companies increasingly engage in strategic partnerships and portfolio diversification to capture market share.
Specialized providers like BICO Group AB exemplify the trend toward comprehensive offerings, bundling printers with a wide range of consumables for diverse research needs. Organovo Holdings Inc. occupies a position among firms focused on developing therapeutic tissues for clinical applications. Meanwhile, 3D Systems Inc. anchors the segment integrating hardware with advanced software for medical device prototyping solutions.
| Leading Market Players |
|---|
| BICO Group AB |
| 3D Systems Inc. |
| Organovo Holdings Inc |
| Merck KGaA |
| Aspect Biosystems Ltd |
| Cyfuse Biomedical K.K |
| regenHU |
| Collplant Biotechnologies Ltd |
| Rokit Healthcare |
| Others |
Cost & Logistics Intelligence
Advanced bioink complexity creates a significant tier divergence, influencing both pricing strategies for specialized materials and the geographic concentration of their production supply chains.
Pricing Analysis
Warranty and service bundling significantly influence bioprinter pricing, where integrated solutions offer comprehensive support packages. The market exhibits a hybrid pricing model, with contract-based long-term offtake for integrated systems and per-unit transactional pricing for consumables. Price differentiation stems from cell-grade bioink certification and the customization level required for patient-specific models. Pricing softness affects commodity bioinks due to increasing competition, while pharmaceutical companies prioritize performance over cost for high-value drug testing models.
Supply Chain Analysis
Logistics and freight costs for temperature-sensitive bioinks add complexity, impacting final product pricing. Supply concentration for advanced bioinks and bioprinters primarily sits within the United States, Germany, and Japan. The industry relies heavily on specialized polymers, cell culture media, and precision optics for bioprinter fabrication. Single-source vulnerability for highly specialized, cell-grade bioinks represents a structural risk. Direct sales channels dominate for bioprinters, while specialized distributors handle bioink delivery to end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D bioprinting market is poised for consolidation, as high capital and material costs force smaller research institutions and startups to seek strategic partnerships or exit the market.
For Market Incumbents: Deepen investments in advanced bioink research and development to maintain a technological edge against emerging specialized bioink producers. Offer fully integrated workflow solutions, bundling hardware, software, and pre-formulated bioinks, to enhance customer stickiness and control the procurement pattern. Expand manufacturing scalability for bioprinted constructs in key regions like China to address growing demand. Prioritize regulatory compliance with evolving FDA and EMA guidelines to secure market access for therapeutic applications.
For New Entrants and Emerging Players: US FDA guidelines for Advanced Therapy Medicinal Products in the United States open a window for new entrants focusing on patient-specific tissue models for personalized medicine. Target underpenetrated segments like AI-driven design optimization for tissue scaffolds, leveraging computational modeling expertise. Penetrate emerging Asia-Pacific markets through strategic collaborations with local research institutions and government initiatives. Focus on niche applications within cancer research, offering specialized 3D tumor models with unique biological characteristics.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized bioink producers and software platform developers, offering synergistic value to larger hardware manufacturers. The long-term viability favors entities investing in regenerative medicine, despite its high-risk, high-reward nature, while research tools provide stable near-term returns. Acquire firms with strong intellectual property in biocompatible materials or AI-driven design capabilities. The signal to watch is the increasing clarity and standardization within regulatory frameworks from agencies like the EMA and PMDA for therapeutic bioprinted products.
| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Diversification | BICO Group AB can expand its offerings beyond research tools into therapeutic tissue development. |
| Platform Integration | 3D Systems Inc. strengthens its position by integrating hardware with advanced bio-validated software. |
| Manufacturing Scale-Up | Rokit Healthcare aims to transition bioprinted constructs from lab-scale to commercial production. |
| Regulatory Approval Pathway | Organovo Holdings Inc. navigates FDA and EMA guidelines for clinical translation of therapeutic tissues. |
| Joint Venture | Merck KGaA could collaborate on novel bioink development with specialized material science firms. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, providing foundational market intelligence. Primary interviews engaged cell biologists, material scientists, bioprinting engineers, and pharmaceutical R&D executives to gather qualitative insights. This approach combined bottom-up data aggregation with top-down market validation, ensuring comprehensive data triangulation. Academic research papers and company annual reports also served as crucial secondary validation sources.
Market volume and value were modeled at a granular level across technology, application, product type, end-user, and regional regulatory cluster segments. Compound Annual Growth Rates were derived from an analysis of historical growth trends and projected market drivers over the projection horizon. Key forecast inputs included advancements in bioink material science and pharmaceutical R&D spending on drug testing models. This framework provided a robust quantitative outlook for the market.
The model assumes a particular technology adoption path; alternative pathways for clinical organ fabrication would alter the outlook. Forecasts reflect assumptions regarding bioink innovation and regulatory maturation. Unexpected breakthroughs in competing regenerative medicine technologies or significant shifts in global R&D funding represent risk factors. Stakeholders should weigh these assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market
Biomedical Engineering
Topical Bioadhesives Market
Biomedical Engineering
Global Bionics Market
Biomedical Engineering
Medical Biomimetics Market
Biomedical Engineering
Bioresorbable Scaffolds Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
Protein Engineering Market
Biomedical Engineering
Tissue Expansion Market
Biomedical Engineering
Bio-Engineered Stent Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Bionic Eye Market
Biomedical Engineering
Bioabsorbable Implant Market
Biomedical Engineering
Biocompatible 3D Printing Market
Biomedical Engineering
Bioactive Bone Grafts Market