
 Topical Bioadhesives Market | 2026-2036
Topical Bioadhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Topical Bioadhesives Market Analytics
The topical bioadhesives market is restructuring around a sharp split between premium surgical sealants and commodity wound-closure strips. Ethicon leverages its Johnson & Johnson parent infrastructure to dominate hospital procurement channels for high-performance formulations. Baxter International sustains competitive position through specialized hemostasis portfolios that anchor its surgical segment presence. Henkel AG & Co. KGaA competes in the broader medical adhesive space, extending its industrial polymer expertise into regulated healthcare applications.
Topical bioadhesives comprise biocompatible polymers—fibrin, cyanoacrylate, polyethylene glycol, or polysaccharide formulations—that form adherent layers on tissue surfaces through cross-linking or polymerization, primarily serving wound closure, hemostasis, and localized drug delivery functions. Hydrogel formulations lead in moisture-retentive wound care where chronic wound prevalence drives recurring demand, while adhesive films capture margin pools in post-surgical barrier applications. Surgical procedures represent the fastest-growing application dimension as minimally invasive techniques expand tissue-sealant requirements across laparoscopic and catheter-based interventions.
FDA 510(k) clearance pathways and EMA Medical Device Regulation (MDR) biocompatibility standards shape product development timelines and market access costs for manufacturers targeting transatlantic distribution. ISO 10993 biological evaluation protocols further constrain material selection, favoring suppliers with in-house toxicology and sterilization validation capabilities. Stakeholders must monitor evolving FDA guidance on antimicrobial-integrated bioadhesives and EMA scrutiny of persistent polymer degradation products as these frameworks will determine which technology platforms secure sustainable commercial traction.
Market Dynamics
Minimally invasive surgical expansion is compressing suture demand while elevating tissue-sealant specifications across laparoscopic and catheter-based procedures. This procedural shift is forcing manufacturers to reformulate bioadhesives for confined-space application and rapid polymerization under humid conditions.
Growth Catalysts
- Chronic wound prevalence:Diabetes-related ulcer incidence in hospital settings sustains recurring demand for moisture-retentive hydrogel formulations. Long-term care facilities in Germany and Japan anchor volume consumption.
- FDA 510(k) pathway clarity:Streamlined premarket notification for fibrin-based sealants accelerates product iteration cycles. Device manufacturers leverage this predictability to pipeline next-generation formulations.
- Cyanoacrylate polymerization speed:Sub-30-second setting times enable ambulatory surgical center adoption where throughput determines profitability. Outpatient facilities in the United States prioritize these efficiency gains.
Market Restraints
- Raw material concentration:Pharmaceutical-grade bovine thrombin supply concentrates in Argentine and Brazilian processing facilities. Geopolitical friction or livestock disease outbreaks threaten formulation continuity.
- EMA MDR biocompatibility escalation:Persistent polymer degradation product scrutiny extends validation timelines. Small manufacturers lacking in-house toxicology capabilities face exclusion from transatlantic distribution.
- Suture substitution resilience:Cost-conscious wound closure in emerging markets retains mechanical fastening preference. Staple and clip systems capture price-sensitive volume despite inferior cosmetic outcomes.
Strategic Opportunities
- Antimicrobial integration:FDA draft guidance on silver-ion and PHMB-embedded bioadhesives creates first-mover advantage for compliant platforms. Wound care segments in the United States reward infection-prevention premiums.
- Localized drug delivery convergence:Bioadhesive matrices combining hemostasis with antibiotic or analgesic release address post-surgical pain management. Orthopedic and dental applications in Japan demonstrate early uptake.
- Home care channel expansion:Direct-to-patient distribution of chronic wound dressings bypasses hospital procurement consolidation. German reimbursement frameworks increasingly cover outpatient bioadhesive therapy.
Industry Challenges
- Sterilization validation bottlenecks:ISO 11135 ethylene oxide residual limits and ISO 11137 radiation dose verification demand specialized contract laboratory partnerships. Startups face 18-24 month timeline compression pressures.
- Polymer science talent scarcity:Cross-functional expertise spanning organic chemistry, toxicology, and regulatory affairs concentrates at established medical device employers. Recruitment competition intensifies in Massachusetts and Baden-Württemberg clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Topical Bioadhesives Market |
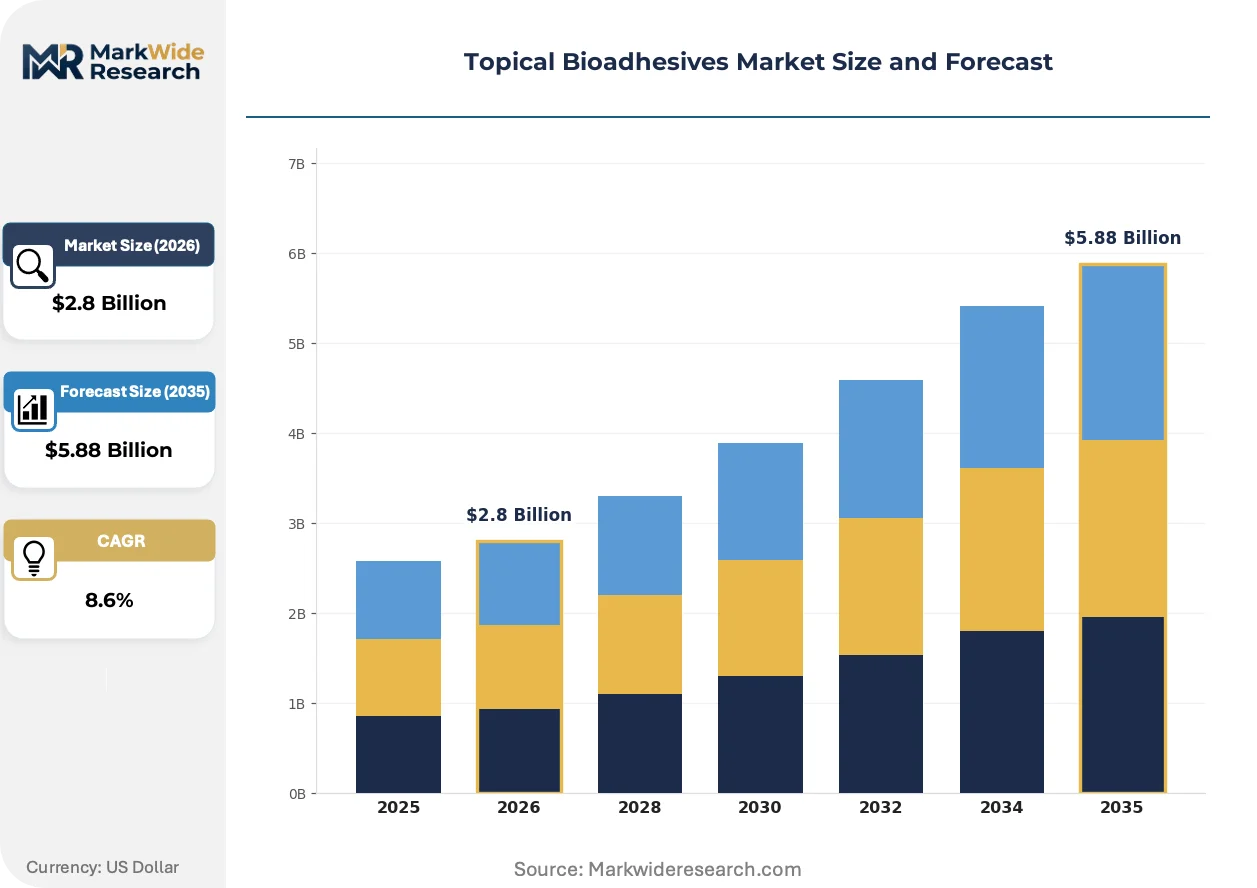
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogel, Microparticles, Nanoparticles, Adhesive Films Application: Wound Care, Surgical Procedures, Drug Delivery, Dermal Fillers End User: Hospitals, Ambulatory Surgical Centers, Home Care, Clinics Technology: Polymerization, Cross-Linking, Solvent Casting, Electrospinning |
| Companies Covered | Ethicon, Inc. (Johnson & Johnson), Baxter International Inc., B. Braun Melsungen AG, Cohera Medical, Inc., MedTrade Products Ltd., DuPont de Nemours, Inc., Henkel AG & Co. KGaA, Arkema SA, Ashland Global Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Topical Bioadhesives Market Evolving Landscape
Biomaterial engineering is dissolving the boundary between passive wound closure and active therapeutic intervention. This convergence is redirecting R&D investment toward multifunctional platforms that simultaneously seal, medicate, and monitor tissue status.
Photocrosslinkable polyethylene glycol hydrogels is rewriting surgical sealant deployment standards. Cardiac and neurological surgeons in tertiary United States hospitals adopt these formulations for precision adhesion in confined anatomical spaces. The technology is compressing traditional fibrin glue market share by eliminating batch-to-batch biological variability.
EMA Medical Device Regulation Annex I general safety and performance requirements are elevating clinical evidence thresholds for bioabsorbable polymer claims. Manufacturers must now submit longitudinal degradation kinetic data for CE marking renewal. Surgical sealant portfolios targeting European hospital procurement face 12-18 month documentation expansion.
Hospital value analysis committees now mandate head-to-head economic modeling against sutures and staples prior to formulary inclusion. This purchasing evolution is displacing traditional surgeon preference-based adoption in United States integrated delivery networks. Vendor contracting teams must populate real-world cost-effectiveness datasets to secure category access.
Topical Bioadhesives Market Segmentation
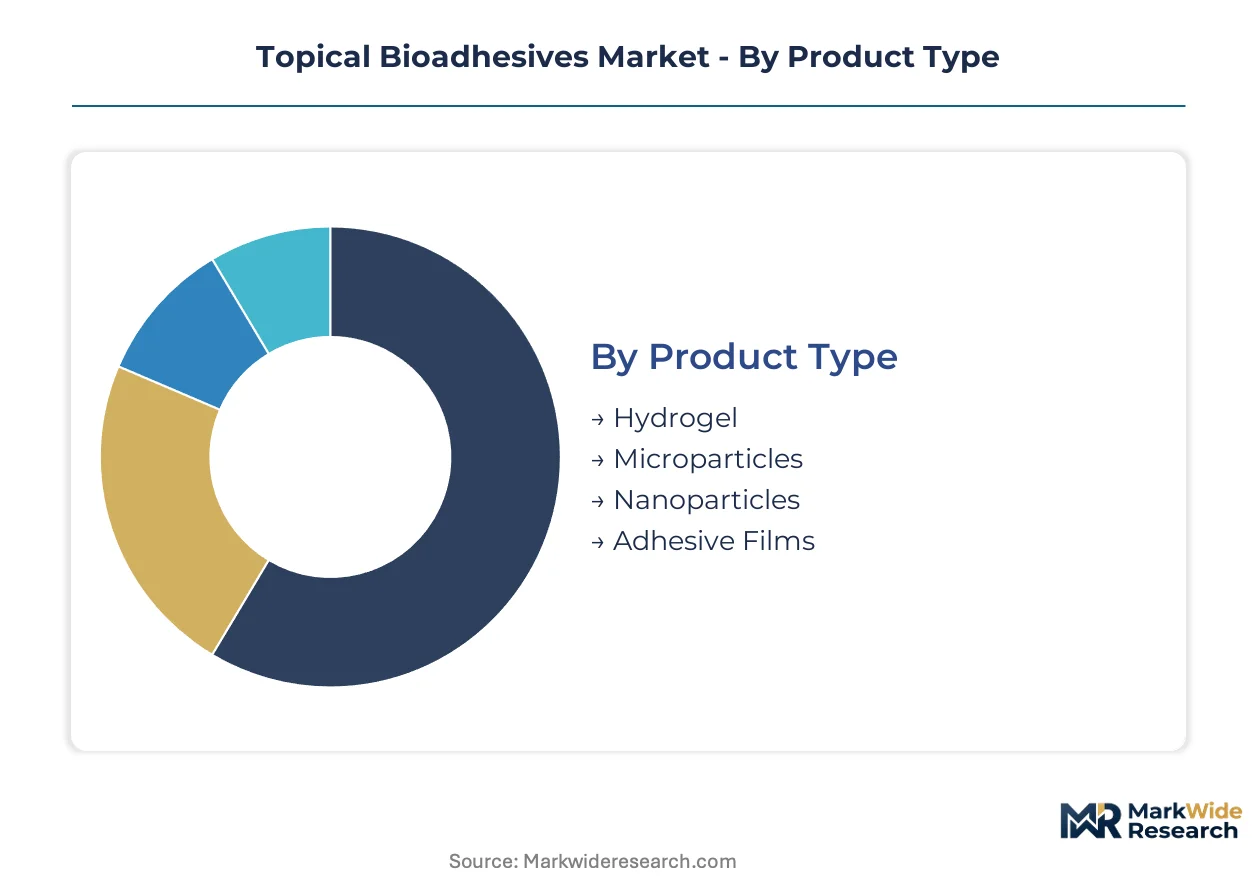
Topical bioadhesives serve heterogeneous clinical environments where formulation requirements diverge sharply between emergency hemostasis and chronic moisture management. Segmentation clarity enables manufacturers to align R&D investment with specific reimbursement codes and sterilization validation pathways rather than pursuing undifferentiated platform development.
Product Type:
Supply concentration in pharmaceutical-grade polymer feedstocks shapes competitive positioning across formulation categories, with hydrogel precursors consolidating among German and Japanese chemical suppliers.
- Hydrogel:Three-dimensional polymer networks of polyethylene glycol or polysaccharide matrices retain 90% water content for moist wound healing. Hospital wound care units in Germany and long-term care facilities in Japan anchor recurring consumption as diabetic ulcer prevalence climbs.
- Microparticles:Biodegradable spheres ranging 1-1000 micrometers enable controlled-release drug delivery through tunable degradation kinetics. Orthopedic and dental applications in Japan demonstrate early clinical uptake for localized antibiotic elution.
- Nanoparticles:Sub-micron carriers penetrate tissue barriers for targeted cellular delivery.
- Adhesive Films:Thin polymer barriers protect surgical incisions from external contamination.
Today's leader: Hydrogel. Tomorrow's challenger: Microparticles.
Application:
Cost tier stratification separates premium reimbursed surgical sealants from commodity outpatient dressings, with FDA 510(k) pathway economics determining viable entry points.
- Wound Care:Moisture-retentive dressings for chronic ulcers and burns leverage hydrogel or hydrocolloid compositions. Long-term care facilities in Germany and hospital outpatient departments in the United States sustain volume demand through recurring dressing changes.
- Surgical Procedures:Hemostatic sealants and tissue adhesives replace or reinforce sutures in laparoscopic and open interventions. Tertiary hospitals in the United States drive premium pricing for cardiac and neurological applications where precision adhesion commands reimbursement premiums.
- Drug Delivery:Bioadhesive matrices enable localized pharmaceutical release.
- Dermal Fillers:Cross-linked hyaluronic acid formulations address cosmetic tissue augmentation.
Surgical Procedures capture margin concentration. Wound Care sustains volume foundations.
End User:
Customer type fragmentation creates channel-specific formulation requirements, with ambulatory surgical centers prioritizing rapid-set cyanoacrylates over moisture-management hydrogels.
- Hospitals:Integrated delivery networks in the United States and university medical centers in Germany consolidate procurement through value analysis committees demanding head-to-head economic modeling against mechanical closure. Inpatient surgical volumes support premium sealant uptake.
- Ambulatory Surgical Centers:Outpatient facilities prioritize sub-30-second polymerization speeds and single-use applicator efficiency. United States ASCs drive cyanoacrylate adoption where throughput economics determine formulary access.
- Home Care:Direct-to-patient distribution channels bypass hospital procurement consolidation.
- Clinics:Dermatology and wound care practices manage chronic conditions.
Hospitals defend revenue concentration. Ambulatory Surgical Centers gain share fastest.
Technology:
Maturity gradients separate established polymerization platforms from emerging electrospinning methods still navigating ISO 10993 biocompatibility validation.
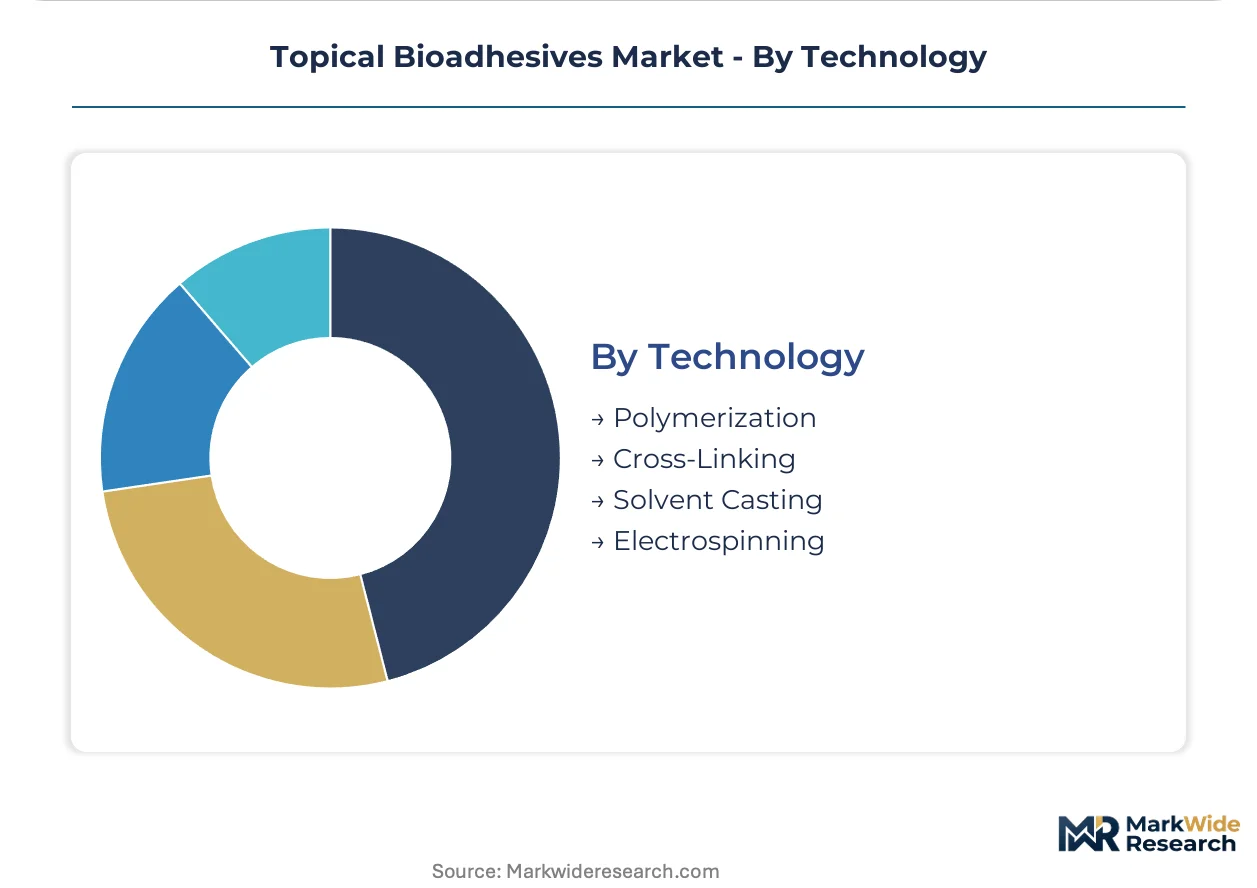
- Polymerization:Cyanoacrylate and fibrin formulations polymerize through moisture-activated or enzyme-catalyzed reactions forming instant tissue bonds. United States ambulatory surgical centers and German hospital emergency departments anchor demand for rapid-setting hemostasis.
- Cross-Linking:Covalent bond formation between polymer chains creates stable three-dimensional networks. Photocrosslinkable polyethylene glycol hydrogels gain traction in United States tertiary cardiac and neurosurgical suites where precision adhesion eliminates biological variability.
- Solvent Casting:Evaporation-induced film formation produces adhesive barriers.
- Electrospinning:Electric field-driven fiber deposition creates nanostructured scaffolds.
Polymerization commands installed base. Cross-Linking climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer science talent clusters in Massachusetts and Baden-Württemberg anchor formulation innovation, while surgical volume concentration in tertiary hospital networks drives commercial deployment across three continents.
United States
Tertiary cardiac centers in Cleveland and Houston deploy photocrosslinkable hydrogels for precision neurosurgical adhesion. FDA 510(k) pathway clarity accelerates fibrin sealant iteration cycles for domestic manufacturers. Massachusetts biotechnology corridors concentrate cross-functional expertise spanning organic chemistry and regulatory affairs.
Germany
Long-term care facilities in Bavaria sustain recurring hydrogel consumption for diabetic ulcer management. EMA MDR biocompatibility standards elevate clinical evidence thresholds for CE marking renewal. Baden-Württemberg industrial clusters house pharmaceutical-grade polymer precursor suppliers serving medical device fabricators.
Japan
Orthopedic and dental applications in Tokyo and Osaka demonstrate early uptake for microparticle-based antibiotic elution. PMDA consultation pathways guide antimicrobial-integrated bioadhesive development timelines. Nagoya medical device manufacturing corridors specialize in precision applicator systems for confined-space surgical deployment.
United Kingdom
London integrated delivery networks consolidate procurement through value analysis committees demanding economic modeling against mechanical closure. MHRA post-Brexit regulatory autonomy maintains alignment with ISO 10993 biological evaluation protocols. Cambridge biotechnology clusters advance electrospinning methods for nanostructured wound scaffolds.
China
Shanghai and Beijing hospital systems expand minimally invasive surgical volumes elevating tissue-sealant specifications. NMPA medical device registration pathways extend validation timelines for imported bioabsorbable polymers. Yangtze River Delta chemical processing hubs concentrate cyanoacrylate monomer production for domestic formulation.
Topical Bioadhesives Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the topical bioadhesives landscape, creating a tiered structure where integrated healthcare conglomerates anchor hospital procurement channels while specialized chemical suppliers capture feedstock margin pools. The vendor base separates into three archetypes: diversified medical device portfolios with surgical segment presence, industrial polymer specialists extending into regulated healthcare applications, and pure-play hemostasis developers. Dominant competitive moves include strategic partnerships for sterilization validation capabilities and geographic expansion into ambulatory surgical center channels.
Within the diversified healthcare tier, Ethicon and Baxter International exemplify procurement channel dominance through parent-company infrastructure and specialized hemostasis portfolios respectively. Henkel AG & Co. KGaA occupies a position representing industrial polymer expertise migration into medical-grade formulations. These three anchors illustrate how competitive positioning depends on whether players originate from healthcare device lineages or chemical material science foundations.
| Leading Market Players |
|---|
| Ethicon, Inc. (Johnson & Johnson) |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Cohera Medical, Inc. |
| MedTrade Products Ltd. |
| DuPont de Nemours, Inc. |
| Henkel AG & Co. KGaA |
| Arkema SA |
| Ashland Global Holdings Inc. |
| Others |
Value Network & Pricing Analysis
United States integrated delivery networks and German hospital procurement consortia anchor demand concentration, enabling manufacturers to command premium pricing for FDA 510(k)-cleared and CE-marked formulations while commodity wound-closure strips compete on volume economics.
Pricing Analysis
Bundled service contracts dominate hospital procurement, unbundling into per-unit pricing for ambulatory surgical centers. Three-tier pricing structure across premium surgical sealants, standard hydrogel dressings, and economy-grade adhesive strips separates reimbursement-eligible hospital products from direct-pay outpatient alternatives. Cost compression in the economy tier intensifies as suture substitution retains price-sensitive emerging market volume. Ambulatory surgical centers exhibit highest price sensitivity due to throughput economics, while tertiary cardiac centers accept premium positioning for precision adhesion.
Supply Chain Analysis
Pharmaceutical-grade bovine thrombin supply rests on Argentine and Brazilian processing facilities, with polymer precursor production anchoring in German Baden-Württemberg clusters and Japanese Nagoya corridors. Critical inputs span bovine-derived biologicals, medical-grade cyanoacrylate monomers, and polyethylene glycol formulations. Single-source vulnerability in South American biological feedstock exposes formulation continuity to livestock disease outbreaks. Distribution runs through hospital GPO contracts in the United States, direct manufacturer-to-facility arrangements in Germany, and layered distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder where chronic wound prevalence and surgical volume expansion generate recurring revenue streams with limited cyclical exposure.
For Market Incumbents: Lock in hospital procurement channel control through exclusive GPO contracting and sterilization validation partnerships that raise barriers for challengers. Deepen backward integration into pharmaceutical-grade polymer precursor production to secure margin pools currently captured by German and Japanese chemical suppliers. Counter photocrosslinkable hydrogel substitution threats by accelerating FDA submissions for next-generation cross-linked formulations. For New Entrants and Emerging Players: Home care direct-to-patient channels represent the most penetrable white-space target, bypassing consolidated hospital procurement where Ethicon and Baxter anchor incumbency. German long-term care facilities and Japanese outpatient wound clinics offer secondary entry points with less formulary committee resistance. Pursue antimicrobial-integrated bioadhesive development aligned with FDA draft guidance to capture infection-prevention premium positioning. For Investors and Strategic Acquirers: Diversified healthcare conglomerates with surgical segment presence are the most active acquirer in this space, seeking hemostasis portfolio expansion and geographic channel fill-ins. Target pure-play developers with validated ISO 10993 biocompatibility dossiers and established sterilization partnerships. Watch EMA MDR enforcement intensity as the signal indicating whether small manufacturers face accelerated consolidation or extended independent viability.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Integration R&D | FDA draft guidance on silver-ion formulations creates first-mover regulatory advantage for compliant platforms. |
| Sterilization Validation Partnership | ISO 11135 ethylene oxide residual compliance compresses 18-24 month timelines for startup market entry. |
| Home Care Channel Expansion | German reimbursement frameworks increasingly cover outpatient bioadhesive therapy bypassing hospital procurement. |
| Photocrosslinkable Hydrogel Launch | United States tertiary cardiac centers adopt precision adhesion eliminating fibrin glue biological variability. |
| Backward Integration into Precursors | Captive supply of pharmaceutical-grade polymers secures margin pools from German chemical suppliers. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and China, with primary inputs from each market cluster. The research combines structured interviews with hospital procurement managers, biomedical engineers, regulatory affairs specialists, and GPO contracts directors alongside secondary validation through FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and ISO 10993 biological evaluation protocols. Bottom-up demand modeling triangulates against top-down market sizing across formulation categories.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions span product type, application, end user, and technology platform, with surgical procedure intensity and chronic wound prevalence serving as core demand drivers. CAGRs derive from procedure volume forecasts, reimbursement code analysis, and polymer feedstock cost trajectory modeling. Forecast inputs incorporate PMDA consultation pathway timelines and NMPA registration pathway extensions for imported bioabsorbable polymers.
Underlying measurement precision varies by segment; surgical sealants carry tighter precision than commodity wound-closure strips due to defined reimbursement codes and hospital procurement transparency. Forecasts reflect assumptions regarding regulatory pathway stability, bovine-derived biological supply continuity, and sterilization validation capacity expansion. Antimicrobial integration compliance costs, EMA MDR documentation requirements, and ambulatory surgical center penetration rates warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Bioink Market
Biomedical Engineering
Tissue Engineering Market
Biomedical Engineering
Global Continuous Bioprocessing Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Global Bionics Market
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market
Biomedical Engineering
Global Bionic Ear Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
3D Bioprinted Organ Transplants Market
Biomedical Engineering
Tissue Expansion Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Biocompatible 3D Printing Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
Bioprosthetics Market