
 Bionic Eye Market | 2026-2036
Bionic Eye Market Size, Share, and Industry Trends Forecast 2026-2036
Bionic Eye Market Intelligence
A surge in venture capital funding for neurotechnology startups is rewriting the competitive landscape for bionic eye development. Second Sight Medical Products leverages its early-market presence and clinical data to maintain its position. Pixium Vision specializes in innovative retinal implant systems to address specific forms of blindness. Bionic Vision Technologies competes on the basis of next-generation devices with higher resolution capabilities.
A bionic eye is an electronic medical prosthesis designed to restore functional vision in individuals with profound blindness. These systems typically consist of an external camera, a signal processor, and a microelectrode array implanted on the retina or visual cortex to stimulate remaining neural pathways. Retinal implants constitute the most established product category, primarily targeting the retinitis pigmentosa patient population. Growth is also significant for applications in macular degeneration, with specialty clinics and academic hospitals serving as the main end-user channels for these advanced procedures.
Market access is governed by stringent regulatory approvals from bodies like the FDA in the United States and the EMA in Europe. These agencies mandate extensive clinical trials and post-market surveillance to ensure device safety and efficacy, shaping product development timelines. Future success depends on securing favorable reimbursement policies and demonstrating long-term clinical benefits to drive broader patient adoption.
Market Dynamics
The convergence of accelerated regulatory pathways and a surge in neurotechnology venture funding is the central force defining market entry and competitive intensity. This dynamic enables startups with novel device architectures to challenge established players, compressing product development timelines and intensifying the race for clinical validation.
Growth Catalysts
- Favorable Regulatory Frameworks:Programs like the FDA's Breakthrough Devices Program in the United States expedite the review and approval process for novel medical devices, reducing the time-to-market for innovative bionic eye systems targeting unmet medical needs.
- Rising Degenerative Disease Prevalence:An aging global population is leading to a higher incidence of conditions such as retinitis pigmentosa and macular degeneration, expanding the addressable patient pool for visual prosthetics.
- Expanding Clinical Infrastructure:The growing number of specialized vision rehabilitation centers and academic medical hospitals equipped to perform complex implant surgeries and provide post-operative care serves as a critical channel for device adoption.
Market Restraints
- High Procedural and Device Costs:The substantial cost associated with the bionic eye prosthesis, combined with the expense of surgery and long-term rehabilitation, limits accessibility for a large segment of the potential patient population.
- Limited Reimbursement Policies:Inconsistent or absent reimbursement codes from public and private insurers in many countries creates significant financial barriers for patients, hindering broader market penetration and adoption.
- Technical Performance Limitations:Current-generation retinal implants offer limited visual acuity and field of view, restoring functional but not natural vision, which can temper patient expectations and adoption rates.
Strategic Opportunities
- Expansion into New Indications:Developing and validating bionic eye systems for more common forms of blindness, such as severe age-related macular degeneration (AMD), represents a significant opportunity to expand beyond the niche retinitis pigmentosa market.
- Integration of Artificial Intelligence:Incorporating AI and machine learning algorithms into external signal processors can enhance object recognition, improve image interpretation, and adapt to individual user needs, creating a key point of differentiation.
- Targeting Developed Asian Markets:Countries with advanced healthcare infrastructure and rapidly aging populations, such as Japan and South Korea, present untapped markets for bionic eye technologies, provided regulatory and reimbursement hurdles are addressed.
Industry Challenges
- Specialized Talent Shortages:A scarcity of ophthalmic surgeons trained in retinal prosthesis implantation and rehabilitation specialists skilled in post-operative patient training creates a bottleneck for scaling procedures and ensuring optimal patient outcomes.
- Complex Clinical Trial Navigation:The lengthy and costly process of conducting clinical trials to meet the stringent safety and efficacy requirements of regulatory bodies like the FDA and EMA poses a substantial operational hurdle.
- Long-Term Device Durability:Ensuring the long-term biocompatibility and functional stability of implanted microelectrode arrays over many years presents a significant engineering and materials science challenge for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bionic Eye Market |
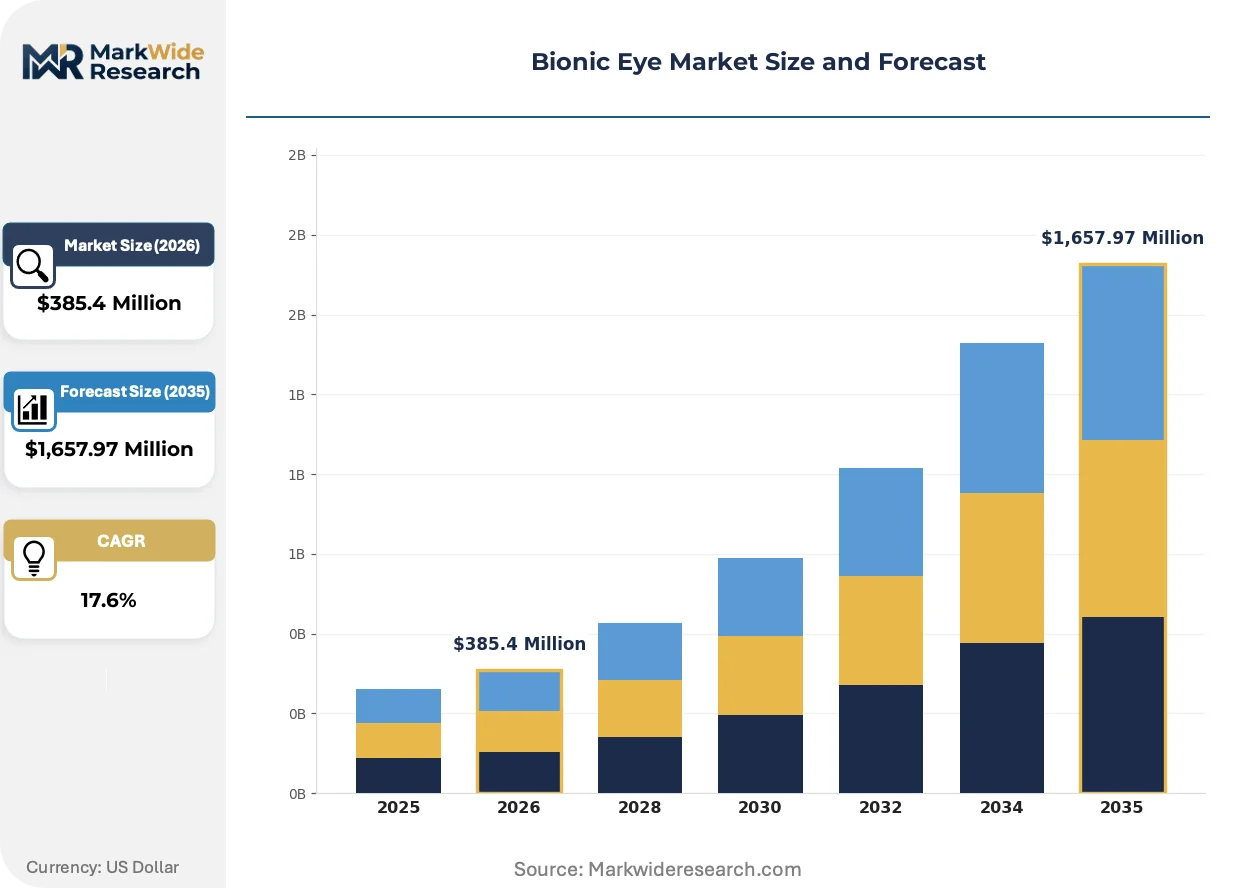
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,657.97 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retinal Implants, Cortical Implants, Optical Sensors, Visual Processors Technology: Electrodes Array, Microelectromechanical Systems, Neural Interface, Photovoltaic Cells Application: Retinitis Pigmentosa, Macular Degeneration, Optic Nerve Trauma, Visual Cortex Damage End User: Research Institutes, Vision Rehabilitation Centers, Specialty Clinics, Academic Hospitals |
| Companies Covered | Bionic Vision Technologies, Nano Retina, Second Sight Medical Products, Monash Vision Group, Optobionics Corporation, Pixium Vision, iBionics, Nidek Co., Retina Implant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bionic Eye Market Strategic Shifts & Innovations
Product evolution is focused on enhancing the resolution and functional utility of visual prosthetics, moving beyond basic light perception. This progression is driven by innovations in microfabrication, neural interface technology, and computational processing, fundamentally altering the potential for vision restoration.
Advanced polymers and high-density materials are being used to create more flexible and biocompatible microelectrode arrays. These next-generation implants are being pioneered by neurotechnology startups and academic research centers to achieve a more intimate and stable neural interface. This development is collapsing the boundary between biological tissue and prosthetic hardware, aiming for more seamless and high-fidelity neural stimulation.
The European Union's Medical Device Regulation (MDR) has introduced more rigorous requirements for market approval. It mandates a higher level of clinical evidence and continuous post-market surveillance for high-risk devices, including bionic eyes. This regulation forces manufacturers targeting the European market to invest more heavily in robust quality management systems and lifecycle data collection to obtain and maintain CE marking.
A notable behavioral shift is the growing influence of patient advocacy organizations in shaping research priorities and clinical trial designs. This trend displaces the traditional model where device specifications are solely defined by engineers, emphasizing functional outcomes valued by end-users, like independent mobility. This movement is most visible in the United States and Europe, where patient groups for retinitis pigmentosa collaborate directly with developers.
Bionic Eye Market Segmentation
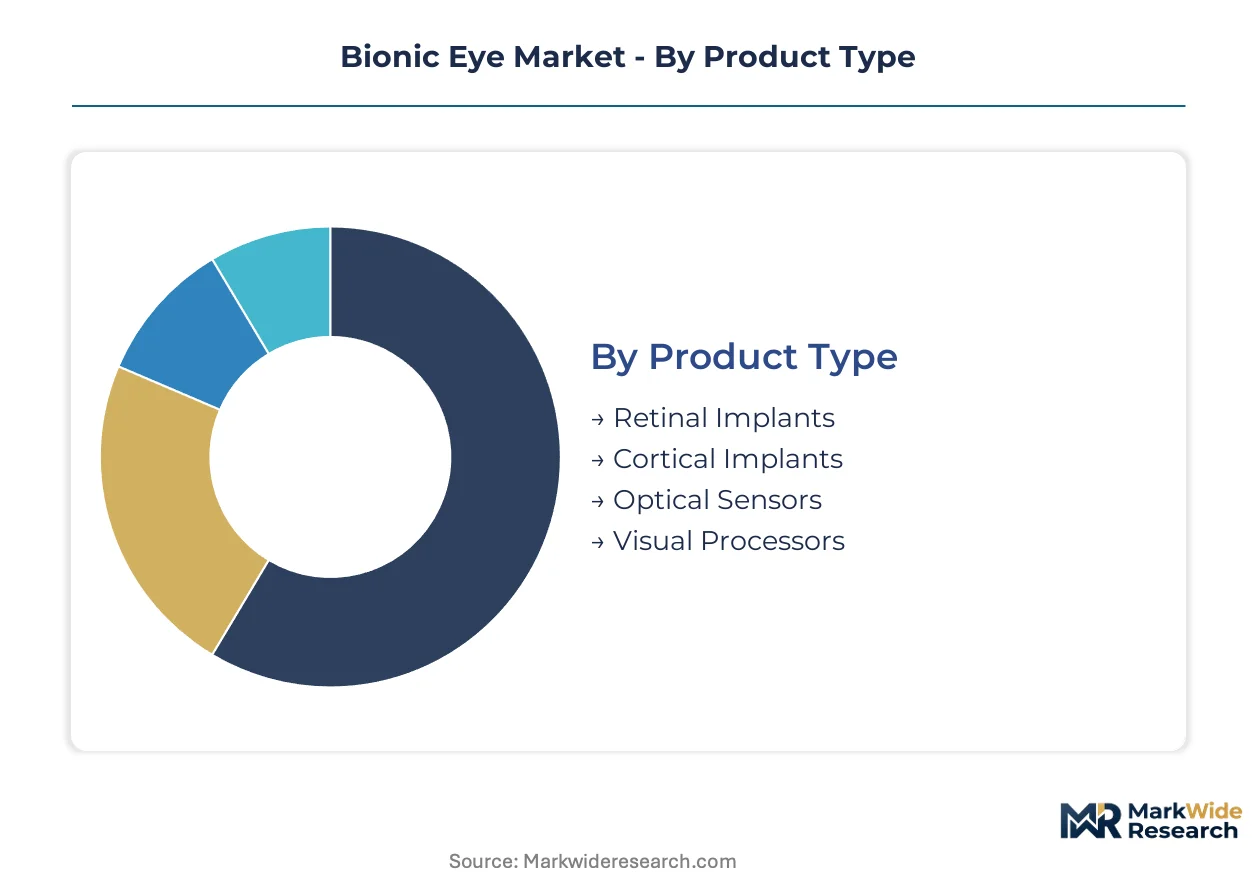
The bionic eye market's segmentation reveals the diverse technological approaches and patient populations driving its evolution. Understanding these distinct categories provides clarity on product development priorities and market access strategies. This granular view highlights where innovation is concentrated and which end-user channels are most critical for device adoption.
Product Type:
The product type spectrum ranges from mature, established retinal implants to emerging, experimental cortical systems.
- Retinal Implants:These devices are surgically placed on or within the retina to stimulate remaining healthy retinal cells. Demand concentrates in Europe and the United States due to retinitis pigmentosa prevalence and established clinical pathways.
- Cortical Implants:These advanced prostheses bypass the optic nerve, directly stimulating the visual cortex to create a perception of light and form. Research funding in North America and Asia-Pacific supports their development for severe retinal or optic nerve damage.
- Optical Sensors:External cameras capture visual information, converting it into electrical signals for processing. These components are critical for image acquisition.
- Visual Processors:These external units interpret signals from optical sensors, translating them into patterns for neural stimulation. Advancements enhance image clarity and functional vision.
Retinal Implants handle the majority of throughput; Cortical Implants are the fastest mover on share.
Technology:
Technological differentiation is primarily driven by the specific neural interface and signal transduction mechanisms employed in bionic eye systems.
- Electrodes Array:These microfabricated structures deliver electrical pulses to neural tissues, forming the core interface for stimulating visual pathways. Miniaturization and biocompatibility improve long-term stability.
- Neural Interface:This encompasses the system bridging electronic components and biological neural circuits. Advances in material science and surgical techniques improve precision and efficacy.
- Microelectromechanical Systems:MEMS technology creates highly integrated, miniaturized components for bionic eyes, including tiny sensors and actuators. Their application reduces device size and improves power efficiency.
- Photovoltaic Cells:These components convert light into electrical energy, potentially allowing for wireless power delivery to implanted retinal prostheses. Research in Japan explores their use.
Electrodes Array technology underpins most existing systems, while Neural Interface solutions are rapidly expanding their functional capabilities.
Application:
The volume of bionic eye procedures is largely dictated by the prevalence of specific degenerative eye conditions and the device's clinical efficacy for each.
- Retinitis Pigmentosa:This inherited degenerative disease causes progressive vision loss, making it the primary target indication for many approved retinal prostheses. Specialized clinics in the United States perform significant implantations.
- Macular Degeneration:Age-related macular degeneration (AMD) is a leading cause of blindness globally, with bionic eye systems addressing its profound forms. Clinical trials in the United Kingdom validate devices for this larger patient population.
- Optic Nerve Trauma:Bionic eyes offer potential vision restoration for individuals with damaged optic nerves, bypassing compromised pathways.
- Visual Cortex Damage:For patients with severe damage to the visual cortex, direct cortical stimulation prostheses are being investigated. This is a complex application.
Retinitis Pigmentosa represents the largest current application segment, with Macular Degeneration demonstrating the steepest expansion trajectory.
End User:
The operational focus and infrastructure of different end-user channels determine their capacity for bionic eye implantation and patient management.
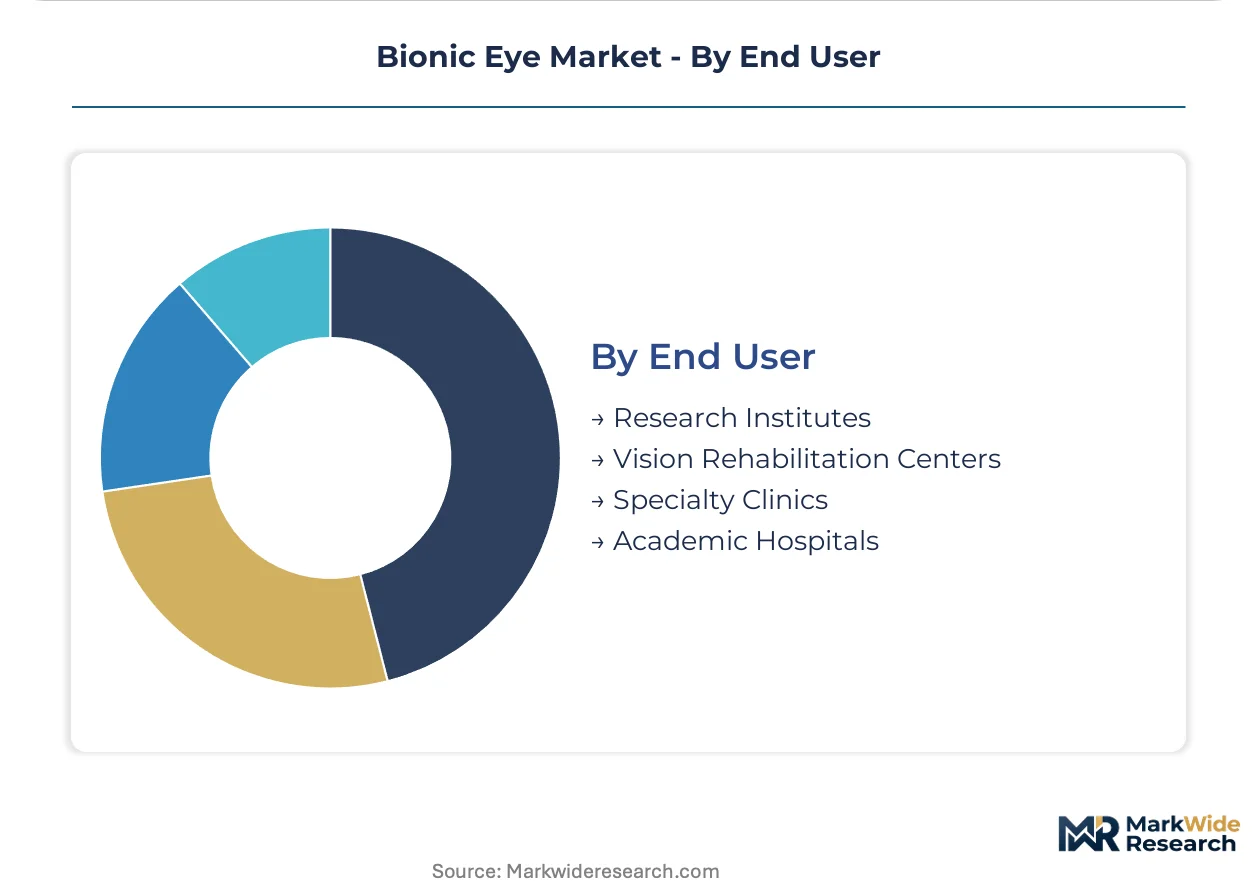
- Vision Rehabilitation Centers:These specialized facilities provide comprehensive pre-operative assessment, surgical coordination, and critical post-operative training for recipients. Their expertise maximizes functional vision outcomes.
- Academic Hospitals:University-affiliated medical centers often lead in bionic eye research, clinical trials, and complex surgical procedures. They serve as key hubs for innovation and advanced patient care.
- Specialty Clinics:Private and public specialty eye clinics offer diagnostic services and surgical expertise for bionic eye implantation.
- Research Institutes:These organizations focus on fundamental and applied research into novel bionic eye technologies and neural interfaces.
Vision Rehabilitation Centers manage the majority of post-operative care, while Academic Hospitals are climbing the fastest in terms of procedural volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A notable pricing-power asymmetry characterizes the bionic eye market, with higher procedural and device costs concentrating in the United States while European markets emphasize value-based healthcare outcomes. Demand patterns are influenced by advanced medical infrastructure, specific disease prevalence, and the presence of favorable regulatory frameworks across different regions.
United States
The United States experiences high demand for bionic eye systems due to a significant prevalence of degenerative eye diseases and advanced healthcare infrastructure. The FDA's Breakthrough Devices Program expedites approval for novel visual prosthetics, reducing time-to-market. Vision rehabilitation centers in major cities like Boston and San Francisco drive post-operative care and crucial research into functional outcomes.
Germany
Germany's market for bionic eyes is driven by an aging population and a robust medical technology sector focused on innovation. The EMA's stringent Medical Device Regulation (MDR) influences device development and market entry for manufacturers. Academic medical centers in Berlin and Munich are central to clinical trials and specialized implant procedures, fostering advanced patient care.
Japan
Japan presents a significant market opportunity, characterized by a rapidly aging population and a strong focus on advanced medical technologies. The PMDA regulates medical device approvals, ensuring high standards for safety and efficacy in the market. Research institutes in Tokyo and Kyoto explore photovoltaic cells and next-generation neural interfaces for vision restoration applications.
United Kingdom
The United Kingdom's bionic eye market benefits from a notable prevalence of macular degeneration and an established clinical trial infrastructure. NICE guidelines influence reimbursement decisions for high-cost medical devices, impacting patient access. Clinical trials for bionic eye systems validate devices for larger patient populations in London and Manchester, expanding treatment options.
South Korea
South Korea supports the bionic eye market through its advanced healthcare infrastructure and significant research funding in neurotechnology. The MFDS oversees medical device approval, fostering the development of innovative visual prosthetics within the country. Seoul's medical technology hubs focus on high-resolution bionic eye systems and advanced neural interface solutions, driving product evolution.
Bionic Eye Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream providing critical microelectrode arrays and visual processors. The bionic eye market exhibits a tiered structure, with established medical device companies competing with agile neurotechnology startups. Strategic partnerships between research institutes and commercial entities accelerate product development and validation processes. Technology licensing, geographic expansion, and targeted M&A are primary competitive moves in this evolving sector, aiming to secure market share and innovation leadership.
Specialists in retinal implant systems, Second Sight Medical Products leverages its early-market presence and extensive clinical data to anchor a significant segment of the bionic eye market. Pixium Vision occupies a position as an innovator, exemplifying companies focused on specific forms of blindness with advanced implant designs and novel surgical approaches. Bionic Vision Technologies represents the archetype of firms pushing for next-generation devices, emphasizing higher resolution capabilities and improved functional vision outcomes for patients. These entities, alongside other R&D-focused organizations, collectively drive advancements in neural interface technology and visual prosthetics, fostering a dynamic competitive environment.
| Leading Market Players |
|---|
| Bionic Vision Technologies |
| Nano Retina |
| Second Sight Medical Products |
| Monash Vision Group |
| Optobionics Corporation |
| Pixium Vision |
| iBionics |
| Nidek Co. |
| Retina Implant AG |
| Others |
Cost & Logistics Intelligence
Seoul's medical technology hubs, with their focus on high-resolution bionic eye systems, influence global component pricing. Their advanced manufacturing capacity directly impacts the cost structure for complex neural interfaces.
Pricing Analysis
Industrial OEM buyers anchor value-based pricing for bionic eye components, reflecting the device's functional outcomes. Price differentiation stems from FDA/EMA certification levels and the resolution capabilities of retinal implants. Pricing softness reflects limited reimbursement policies, creating significant financial barriers for patients. Academic hospitals, focused on advanced research, exhibit lower price sensitivity compared to individual patients.
Supply Chain Analysis
Export-control regimes for advanced medical technologies limit the free flow of critical bionic eye components. Supply concentrations reside in the United States, Germany, and Japan for microelectrode arrays and optical sensors. Single-source vulnerability for highly specialized microfabrication poses a structural risk. Distribution runs through direct sales channels to specialized vision rehabilitation centers and academic hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bionic eye market presents a defensive-moat story, primarily due to significant regulatory entrenchment. Extensive clinical trial requirements and post-market surveillance create high barriers to entry for new competitors.
For Market Incumbents: Insulate core market share by deepening clinical data collection and expanding reimbursement advocacy. This counteracts the threat from agile neurotechnology startups with novel device architectures. Invest in R&D for higher resolution capabilities and AI integration to enhance functional vision outcomes. Secure favorable long-term contracts with academic hospitals to maintain procedural volume. For New Entrants and Emerging Players: Pursue expansion into new indications like severe age-related macular degeneration, a larger patient population. Target developed Asian markets, such as Japan and South Korea, by addressing local regulatory and reimbursement hurdles. Leverage accelerated regulatory pathways, like the FDA's Breakthrough Devices Program, to compress time-to-market. Focus on novel device architectures for improved visual acuity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized neurotechnology startups with proprietary neural interface intellectual property. The market offers long-term viability driven by an aging global population and persistent unmet medical needs for vision restoration. Acquire firms demonstrating superior long-term device durability and biocompatibility. Watch for broader reimbursement policy adoption in major European markets as an inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates device validation and secures regulatory approvals from bodies like the FDA. |
| AI Integration in Processors | Enhances object recognition and adapts to individual user needs for improved function. |
| Reimbursement Policy Advocacy | Expands patient access by reducing financial barriers in key healthcare systems. |
| Advanced Material Science R&D | Improves long-term biocompatibility and stability of implanted microelectrode arrays. |
| Strategic Partnerships with Hospitals | Drives clinical adoption and facilitates post-operative patient training and care. |
Research Approach
Initial hypotheses were tested against primary input from ophthalmic surgeons, vision rehabilitation specialists, and neurotechnology R&D directors, then refined. This involved interviews with key industry stakeholders, validated by secondary data from FDA filings, EMA submissions, and clinical trial registries. Bottom-up and top-down triangulation ensured data consistency across various market dimensions.
Demand-supply-balance underpins the analytical framework for the bionic eye market across the analysis window. Modeled segmentation dimensions include product type, technology, application, end user, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical trends and projected adoption rates. Degenerative eye disease prevalence and regulatory approval timelines served as critical forecast inputs.
Sensitivities concentrate around shifts in reimbursement policies and unforeseen clinical trial outcomes. Forecasts reflect current market assumptions, but technological breakthroughs could alter projections. Material shifts in regulatory frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Bioresorbable Scaffolds Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
Argentina Artificial Organs and Bionic Implants Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
Global Single Use Bioprocessing Probes and Sensors Market
Biomedical Engineering
Global Bionic Ear Market
Biomedical Engineering
Tissue Engineered Skin Substitute Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Bioactive Coating Devices Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Topical Bioadhesives Market