
 Nano-Silicon Drug Delivery Platform Market | 2026-2036
Nano-Silicon Drug Delivery Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Nano-Silicon Drug Delivery Platform Market Outlook
Asset-light licensing and milestone-based partnership structures is rewriting competitive entry in nano-silicon therapeutics, allowing biotech firms to access manufacturing capacity without capital-heavy facility builds. NanoMed Solutions leverages its vertical integration into porous silicon synthesis to control raw material quality. SilicaBio Technologies sustains R&D intensity through dedicated funding from government nanotechnology grants. SiliconDx Pharma anchors its position in North American markets through specialized regulatory consulting capabilities.
Nano-silicon drug delivery platforms employ biocompatible porous silicon or silica-based nanostructures with tunable pore sizes of 2-50 nm and high surface-area-to-volume ratios exceeding 500 m²/g, designed to encapsulate, protect, and release therapeutic payloads with controlled pharmacokinetic profiles. These systems serve primarily to improve bioavailability of poorly soluble drugs, enable targeted delivery to tumor microenvironments, and reduce systemic toxicity of potent biologics. Nanoparticles occupy the largest addressable volume pool due to manufacturing scalability, while liposomes command premium pricing in oncology applications where stealth coating technology extends circulation half-life. Hydrogels represent the fastest-growing product category for sustained-release depot formulations in subcutaneous delivery modes.
The FDA maintains stringent chemistry-manufacturing-controls requirements for nanotechnology products under its emerging technology program, while the EMA applies specific guidance on nanomedicine quality attributes through its reflection papers. ISO 10993 biocompatibility testing standards and ICH Q3D elemental impurity guidelines further constrain material sourcing and purification protocols. Stakeholders must monitor evolving regulatory distinctions between drug and device classifications for combination products incorporating nano-silicon carriers.
Market Dynamics
The FDA's emerging technology program is compressing chemistry-manufacturing-controls timelines for nanotechnology therapeutics, while manufacturing clusters concentrate around MIT, TU Munich, and Osaka University. This dual pressure accelerates competitive entry for asset-light biotech licensors.
Growth Catalysts
- Accelerated FDA Pathways:The FDA's nanotechnology-specific guidance under its emerging technology program reduces IND-to-approval cycles for porous silicon carriers. Oncology departments at academic medical centers now drive fastest-expanding procurement volumes.
- Surface Chemistry Advances:Tunable pore architectures of 2-50 nm enable precise payload release kinetics for biologics with narrow therapeutic windows. Stealth coating technologies extend circulation half-life in tumor microenvironments.
- German Manufacturing Density:Silicon nanoparticle synthesis clusters around TU Munich and Fraunhofer institutes create captive supplier networks. Local EMA reflection paper compliance expertise attracts formulation partnerships.
Market Restraints
- Elemental Purity Costs:ICH Q3D elemental impurity guidelines impose multi-stage purification protocols on silicon feedstocks. High-purity silicon precursor costs constrain margin structures for generic drug applications.
- ISO 10993 Testing Burden:Biocompatibility validation requirements for novel surface chemistries extend preclinical timelines. Cytotoxicity and hemocompatibility assays consume 18-24 months for each formulation modification.
- Device-Drug Classification Friction:FDA combination product determinations for implantable nano-silicon depots create regulatory uncertainty. Jurisdictional disputes between CDER and CDRH delay market authorization.
Strategic Opportunities
- Japanese Geriatric Applications:METI's healthcare technology subsidies target sustained-release formulations for polypharmacy management in aging populations. Subcutaneous depot hydrogels address medication adherence in rural prefectures.
- CRISPR-Nano Convergence:Porous silicon vectors for gene editing payloads combine with lipid nanoparticle co-delivery systems. Dual-platform approaches penetrate inherited disease markets with limited viral vector capacity.
- EMA Orphan Designation Pathways:Nanomedicine-specific quality attribute guidance streamlines pediatric oncology applications. Reflection papers on surface characterization reduce regulatory risk for rare disease indications.
Industry Challenges
- Scarce Silicon Process Engineers:Porous silicon electrochemical etching expertise concentrates at a handful of European and Japanese research institutions. Commercial-scale anodization parameter optimization requires tacit knowledge transfer from academic labs.
- Legacy ERP Integration:Batch records for nanoscale manufacturing parameters overwhelm pharmaceutical quality management systems. Real-time pore size distribution monitoring demands custom SCADA configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano-Silicon Drug Delivery Platform Market |
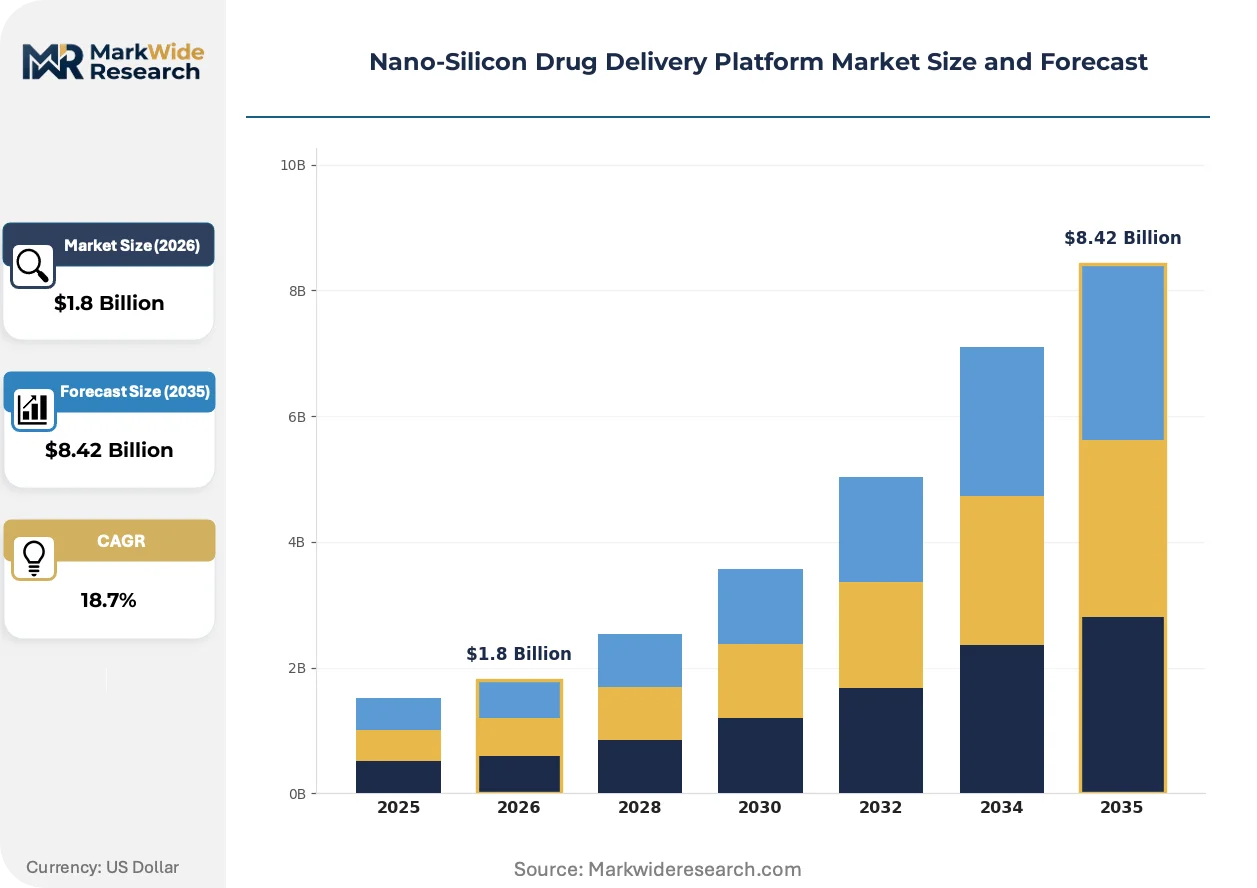
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microspheres, Nanoparticles, Liposomes, Hydrogels Application: Cancer Therapy, Vaccine Delivery, Antibody Development, Gene Therapy End User: Pharmaceutical Companies, Research Institutions, Hospitals, Contract Manufacturing Delivery Mode: Intravenous, Subcutaneous, Oral, Transdermal |
| Companies Covered | NanoMed Solutions, SilicaBio Technologies, SiliconDx Pharma, NanoSphere Therapeutics, MicroSilica Innovations, BioNano Systems, SiMedica, NanoPharm Solutions, Silitec Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano-Silicon Drug Delivery Platform Market Strategic Shifts
Computational materials design is displacing empirical formulation development, compressing candidate screening from years to months. Three convergent forces reshape competitive positioning.
Multiscale molecular dynamics simulation is virtualizing porous silicon architecture optimization. Pharmaceutical formulators at academic medical centers now model drug-pore wall interactions before synthesis. This capability collapses design-test cycles and enables patient-specific release profiles.
EMA's 2023 nanomedicine reflection paper on quality attributes tightens surface characterization requirements for batch release. Manufacturers must demonstrate pore size distribution consistency within 5% coefficient of variation across production lots. German and Swiss contract development organizations invest in small-angle neutron scattering capabilities to meet documentation standards.
Academic medical center procurement committees now require pharmacoeconomic modeling for nano-silicon premium pricing justification. Oncology departments demand real-world evidence protocols before formulary inclusion. This behavioral shift concentrates early adoption at US National Cancer Institute-designated centers with dedicated nanomedicine pharmacoeconomics units.
Nano-Silicon Drug Delivery Platform Market Segmentation
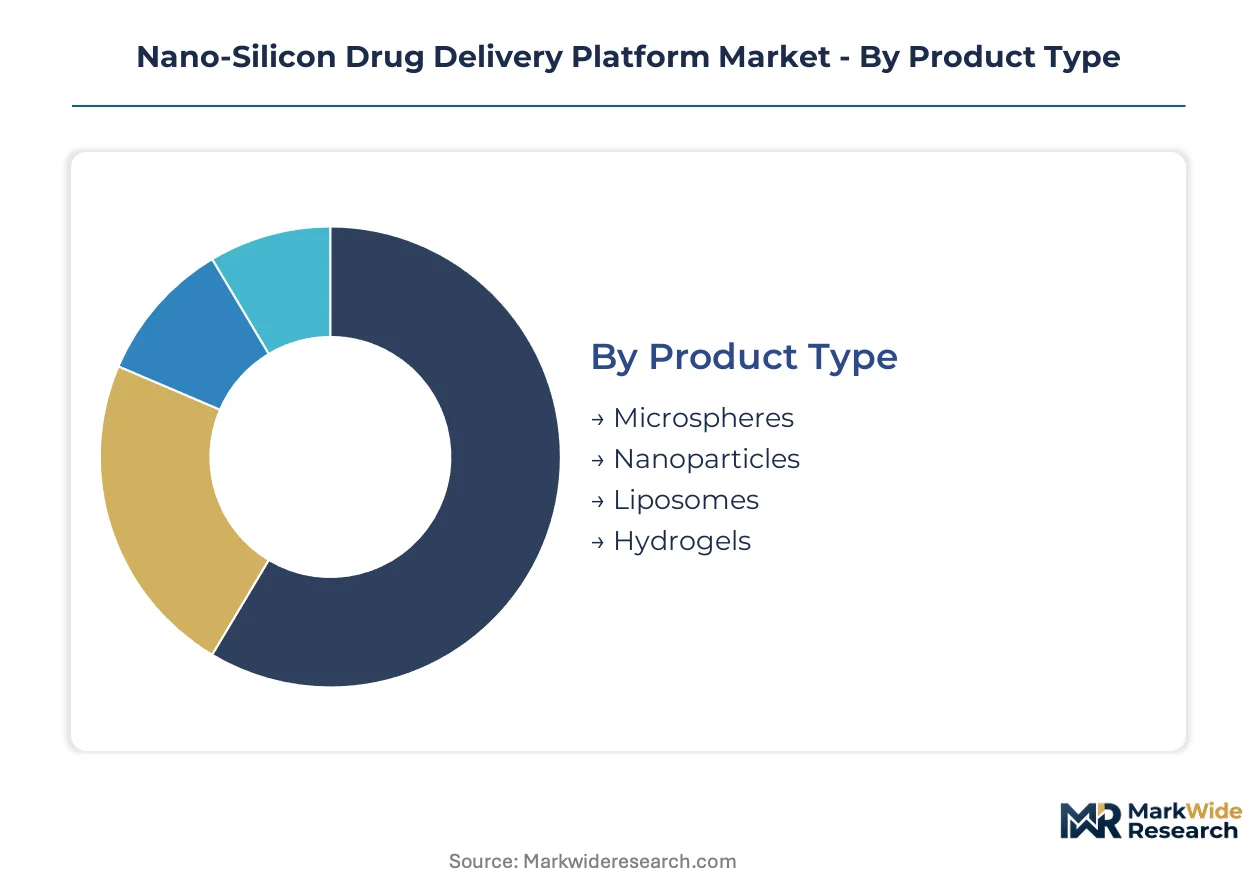
Segmentation in nano-silicon drug delivery reveals divergent technical requirements across therapeutic modalities. Product architectures, application targets, and administration routes each impose distinct manufacturing constraints and regulatory pathways that reshape vendor specialization.
Product Type:
After-sales service intensity varies sharply across product categories, with complex formulations demanding sustained technical support for pore architecture validation and batch release documentation.
- Nanoparticles:Solid or mesoporous silicon structures with tunable diameters of 50-200 nm dominate manufacturing scale-up due to established electrochemical etching protocols. Pharmaceutical companies in the United States and Germany concentrate procurement for oncology applications where EMA reflection papers on surface characterization guide quality agreements.
- Hydrogels:Crosslinked porous silicon matrices enable sustained-release depot formulations with zero-order release kinetics. Subcutaneous delivery applications in Japanese geriatric markets drive fastest-expanding volumes as METI healthcare subsidies support polypharmacy management programs.
- Microspheres:Larger 1-10 μm porous silicon particles suit intratumoral injection protocols with localized payload retention.
- Liposomes:Phospholipid bilayers incorporating silicon dioxide cores command premium pricing through stealth coating technologies extending circulation half-life.
By volume, nanoparticles lead. By growth pace, hydrogels are ahead.
Application:
Cost tier stratification separates indication categories, with oncology commanding premium development budgets and rare disease applications accessing accelerated regulatory pathways.
- Cancer Therapy:Porous silicon carriers enable passive targeting to tumor microenvironments through enhanced permeability and retention effects. Academic medical centers with dedicated nanomedicine pharmacoeconomics units concentrate procurement in the United States.
- Gene Therapy:CRISPR payload protection and controlled nuclear entry kinetics position porous silicon as non-viral vector alternatives. Inherited disease markets with limited adeno-associated virus manufacturing capacity drive steepest expansion trajectory.
- Vaccine Delivery:Adjuvant-compatible surface chemistries support subunit antigen presentation with reduced cold-chain requirements.
- Antibody Development:Silicon nanoparticles stabilize biologic formulations against aggregation during lyophilization and reconstitution cycles.
Revenue concentration favors cancer therapy. Regulatory momentum accelerates gene therapy.
End User:
Customer type determines contract structure complexity, with research institutions favoring milestone-based partnerships and pharmaceutical companies demanding full technology transfer packages.
- Pharmaceutical Companies:Integrated drug-device combination product developers seek captive silicon nanoparticle synthesis capacity to secure supply chain continuity. FDA emerging technology program engagement compresses chemistry-manufacturing-controls timelines for sponsors with prior nanomedicine submissions.
- Contract Manufacturing:Specialized porous silicon foundries in Switzerland and Germany invest in small-angle neutron scattering capabilities to meet EMA batch release documentation standards. Quality attribute verification services expand most quickly as sponsor companies outsource technical capabilities.
- Research Institutions:Academic medical centers with National Cancer Institute designation drive formulary inclusion through real-world evidence protocol requirements.
- Hospitals:Compounding pharmacy integration of nano-silicon formulations remains limited by device-drug classification uncertainties.
Pharmaceutical companies anchor current revenue. Contract manufacturing captures fastest-growing service demand.
Delivery Mode:
Supply concentration clusters around administration route expertise, with intravenous formulations demanding distinct sterility assurance and particulate control compared to depot systems.
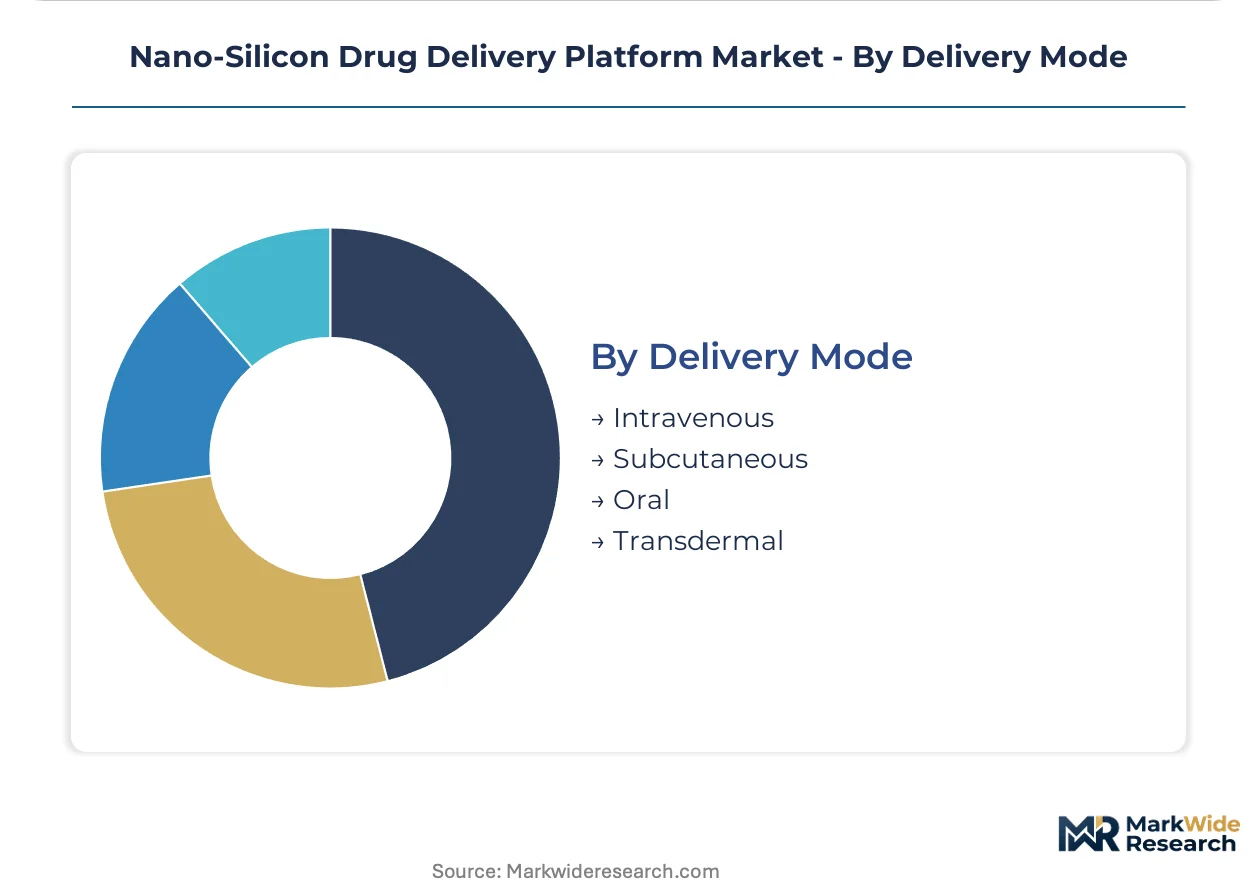
- Intravenous:Parenteral nano-silicon formulations require endotoxin limits below 0.5 EU/mL and subvisible particle monitoring per USP 788. Oncology departments at academic medical centers concentrate procurement volumes where stealth coating technologies extend circulation half-life.
- Subcutaneous:Depot hydrogel formulations enable weekly or monthly dosing intervals improving adherence in aging populations. Japanese rural prefecture healthcare access initiatives support fastest-expanding adoption.
- Oral:Gastrointestinal stability challenges limit porous silicon application despite bioavailability advantages for poorly soluble drugs.
- Transdermal:Microneedle-assisted nano-silicon penetration remains preclinical with device-drug classification friction at FDA.
Intravenous dominates current utilization. Subcutaneous gains share fastest through geriatric applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in nano-silicon drug delivery platforms tilt toward net imports in most markets, with specialized manufacturing concentrated in select research-intensive economies. The United States, Germany, and Japan maintain production surpluses while emerging markets rely on technology licensing for platform access.
United States
Oncology departments at academic medical centers drive procurement volumes, particularly National Cancer Institute-designated centers with dedicated nanomedicine pharmacoeconomics units. The FDA's emerging technology program compresses chemistry-manufacturing-controls timelines for sponsors with prior nanomedicine submissions. Manufacturing clusters concentrate around MIT and Greater Boston, where porous silicon electrochemical etching expertise anchors contract development capacity.
Germany
Silicon nanoparticle synthesis clusters around TU Munich and Fraunhofer institutes create captive supplier networks for European pharmaceutical companies. EMA reflection papers on nanomedicine quality attributes tighten surface characterization requirements, attracting formulation partnerships seeking regulatory expertise. Bavaria-based contract manufacturers invest in small-angle neutron scattering capabilities to meet batch release documentation standards.
Japan
METI healthcare technology subsidies target sustained-release formulations for polypharmacy management in aging populations, driving fastest-expanding hydrogel adoption. Subcutaneous depot applications address medication adherence challenges in rural prefectures with limited healthcare access. Osaka University anchors manufacturing clusters where porous silicon process engineering expertise concentrates.
Switzerland
Specialized porous silicon foundries leverage proximity to German pharmaceutical clusters while maintaining independent regulatory pathways through Swissmedic. Quality attribute verification services expand most quickly as sponsor companies outsource technical capabilities for EMA compliance. Zurich and Basel host contract development organizations with advanced scattering characterization infrastructure.
United Kingdom
Research institutions with nanomedicine programs drive early-stage demand, though commercial manufacturing scale remains limited post-Brexit. MHRA alignment with EMA nanomedicine guidance maintains regulatory continuity for quality attribute documentation. London-Oxford-Cambridge corridor concentrates academic partnerships seeking technology transfer to continental manufacturing partners.
Nano-Silicon Drug Delivery Platform Market Competitive Environment
On the supply side, the industry is structured around three distinct capability tiers rather than consolidated volume leadership. Asset-light biotech licensors partner with specialized foundries to avoid capital-heavy facility builds, while vertically integrated players control porous silicon synthesis for quality assurance. Strategic archetypes include captive manufacturers with backward integration into raw material production, pure-play contract development organizations with regulatory consulting capabilities, and research spinouts leveraging academic process engineering expertise. Dominant competitive moves center on milestone-based partnership structures for market entry and capacity expansion through dedicated government nanotechnology grant funding.
Among North American specialists, SiliconDx Pharma and NanoMed Solutions occupy positions at opposite ends of the integration spectrum. SiliconDx Pharma exemplifies the regulatory-centric archetype through specialized consulting capabilities that anchor North American market access. NanoMed Solutions represents vertical control strategies with in-house production of porous silicon synthesis. SilicaBio Technologies, with its government grant funding model, demonstrates how sustained R&D intensity can substitute for commercial revenue in early-stage platform development.
| Leading Market Players |
|---|
| NanoMed Solutions |
| SilicaBio Technologies |
| SiliconDx Pharma |
| NanoSphere Therapeutics |
| MicroSilica Innovations |
| BioNano Systems |
| SiMedica |
| NanoPharm Solutions |
| Silitec Biologics |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on high-purity silicon precursor suppliers in Germany and Japan determines both pricing tier spreads and supply chain shape, compressing margins for generic applications while enabling premium capture for oncology-grade formulations with validated EMA quality attributes.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers command spreads based on FDA emerging technology program engagement and ISO 10993 biocompatibility certification depth, while standard tiers compete on volume scale from German manufacturing clusters. Pricing pressure stems from ICH Q3D elemental impurity compliance costs feeding into feedstock expenses. Academic medical centers with dedicated pharmacoeconomics units exhibit lowest price sensitivity; generic drug developers face highest.
Supply Chain Analysis
Extended payment terms from pharmaceutical sponsors to contract manufacturers now stretch 90-120 days, straining porous silicon foundry working capital. Supply concentrates in the United States, Germany, and Japan where MIT, TU Munich, and Osaka University anchor manufacturing clusters. Raw material dependencies center on high-purity silicon wafers, electrochemical etching electrolytes, and stealth coating polymers. Single-source vulnerability persists for academic-derived process engineering expertise. Distribution runs through specialized contract development organizations with regulatory consulting capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's nanotechnology-specific guidance under its emerging technology program creates a regulatory inflection that accelerates IND-to-approval cycles, positioning asset-light biotech licensors to capture disproportionate value from platform disruption.
For Market Incumbents: Entrench position through backward integration into porous silicon synthesis and captive supply of high-purity precursors. Add capacity in Bavaria to exploit EMA reflection paper compliance expertise. Defend against asset-light licensors by embedding regulatory consulting into partnership structures.
For New Entrants and Emerging Players: Japanese geriatric hydrogel applications for polypharmacy management represent the most penetrable entry point, with METI healthcare subsidies reducing customer acquisition costs. CRISPR-nano convergence for inherited diseases offers second white-space target with limited viral vector competition. Pursue milestone-based partnership structures with academic medical centers to bypass capital-heavy facility requirements.
For Investors and Strategic Acquirers: The market sits at a platform-validation phase that favors vertically integrated specialists with in-house porous silicon production and regulatory track records. Five-to-ten year viability hinges on FDA combination product classification clarity. Watch for EMA nanomedicine reflection paper updates on surface characterization as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Emerging Technology Program Engagement | Compresses chemistry-manufacturing-controls timelines for sponsors with prior nanomedicine submissions. |
| Small-Angle Neutron Scattering Capability Investment | Enables German and Swiss contract manufacturers to meet EMA batch release documentation standards. |
| Academic Medical Center Partnership Structure | Secures formulary inclusion through real-world evidence protocols at National Cancer Institute-designated centers. |
| CRISPR-Nano Convergence Platform Development | Positions porous silicon vectors to penetrate inherited disease markets with limited adeno-associated virus capacity. |
| METI Healthcare Subsidy Alignment | Captures Japanese geriatric hydrogel demand for rural prefecture polypharmacy management programs. |
Study Parameters
Desk research of FDA emerging technology program filings, EMA nanomedicine reflection papers, and ClinicalTrials.gov porous silicon entries preceded structured interviews with regulatory affairs leads, formulary directors at academic medical centers, porous silicon process engineers, and contract manufacturing executives. Secondary validation drew from ISO 10993 biocompatibility testing standards, ICH Q3D elemental impurity guidelines, and hospital procurement databases. Bottom-up segment sizing triangulated against top-down market reconstruction.
Forecast assumptions held FDA emerging technology program participation rates and EMA reflection paper compliance timelines fixed across the analysis window, while varying oncology department procurement intensity and Japanese geriatric hydrogel adoption curves. Modeled dimensions span product architecture, therapeutic application, end-user type, and administration route. CAGRs derived from segment-level growth trajectory synthesis with porous silicon manufacturing capacity expansion schedules and academic medical center formulary inclusion timelines as primary inputs.
Practitioners should monitor FDA combination product classification determinations and EMA nanomedicine quality attribute guidance updates for early signals. Forecasts reflect assumptions about regulatory pathway stability and manufacturing cluster concentration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
North America Proteomics Market
Biomedical Technology
Europe Transfection Technologies Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
Global Autologous Conditioned Plasma Market
Biomedical Technology
Tissue Clearing Market
Biomedical Technology
Polymerase Chain Reaction Technologies Market
Biomedical Technology
Northern Blotting Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Structural Biology and Molecular Modeling Techniques Market
Biomedical Technology
PD L1 Biomarker Testing Market
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
Bone Marrow Aspirate Concentrates (BMAC) Market
Biomedical Technology
Global Biosimulation Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Drug Discovery Enzymes Market