
 Regenerative Medicine Market | 2026-2036
Regenerative Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Regenerative Medicine Market Intelligence
Specialized cell processing technicians is rotating from academic laboratories into commercial manufacturing facilities, tightening talent pipelines across the sector. Novartis leverages its CAR-T production infrastructure to anchor European supply chains. Pfizer sustains gene therapy investments through partnered platform technologies. Johnson & Johnson competes in orthopedic regenerative applications via its DePuy Synthes channel network.
Regenerative medicine encompasses therapeutic approaches that repair, replace, or regenerate human cells, tissues, or organs through stem cell applications, gene editing vectors, engineered scaffolds, and biologically active matrices manufactured under cGMP conditions with viability thresholds exceeding 90 percent. Cell therapy dominates current revenue pools as hospitals adopt chimeric antigen receptor protocols for hematologic indications. Gene therapy represents the fastest-expanding segment as adeno-associated viral vector manufacturing scales. Tissue engineering occupies mature margin positions in dermal and cartilage applications where reimbursement pathways have stabilized.
FDA's regenerative medicine advanced therapy designation compresses review timelines for qualifying products, while EMA's adaptive pathway framework accelerates European access for unmet medical needs. ISO 14155 governs clinical investigation standards for cell and tissue products, shaping trial design costs across development portfolios. Stakeholders must monitor emerging FDA guidance on genome editing permanence as payers reassess long-term value frameworks for curative interventions.
Market Dynamics
Cell therapy manufacturing is consolidating around automated closed-system bioreactors, compressing batch variability and shifting competitive advantage from manual processing expertise to platform standardization.
Growth Catalysts
- FDA's RMAT designation:The accelerated review pathway compresses development timelines for qualifying regenerative therapies, pulling investment toward hematologic and solid tumor indications.
- Orthopedic surgical suites:Hospital systems in the United States are embedding autologous cell therapies into standard arthroscopy protocols, creating institutional demand pull.
- Gene editing permanence:CRISPR-based ex vivo modifications are opening curative pathways for previously untreatable monogenic disorders, expanding addressable patient populations.
Market Restraints
- Viral vector supply concentration:AAV manufacturing capacity clusters among contract manufacturers in the United States and Europe, creating single-source dependencies for gene therapy developers.
- cGMP facility capex thresholds:Cleanroom construction and qualification for cell therapy production requires capital commitments exceeding $50 million, filtering participant pools.
- Reimbursement latency:CMS and private payers maintain evidence requirements that lag FDA approval by 18-36 months, freezing commercial uptake for novel modalities.
Strategic Opportunities
- Japan's Sakigake designation:PMDA's priority review framework offers conditional approval pathways for regenerative products, enabling earlier revenue recognition than US timelines.
- Allogeneic "off-the-shelf" platforms:Universal donor cell lines eliminate patient-specific manufacturing logistics, opening scale economics previously reserved for small molecules.
- Tissue engineering-digital surgery convergence:3D bioprinting integrated with preoperative planning software is creating patient-specific implant workflows in craniofacial reconstruction.
Industry Challenges
- Cell processing technician scarcity:Experienced aseptic operators are migrating from academic centers to commercial facilities, hollowing out training pipelines.
- Cold chain integrity:Cryopreserved cellular products require uninterrupted liquid nitrogen logistics, with deviations above minus 150 degrees Celsius triggering batch discard.
- Vector manufacturing standardization:AAV yield variability across serotypes complicates cost-of-goods forecasting and contract manufacturing negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regenerative Medicine Market |
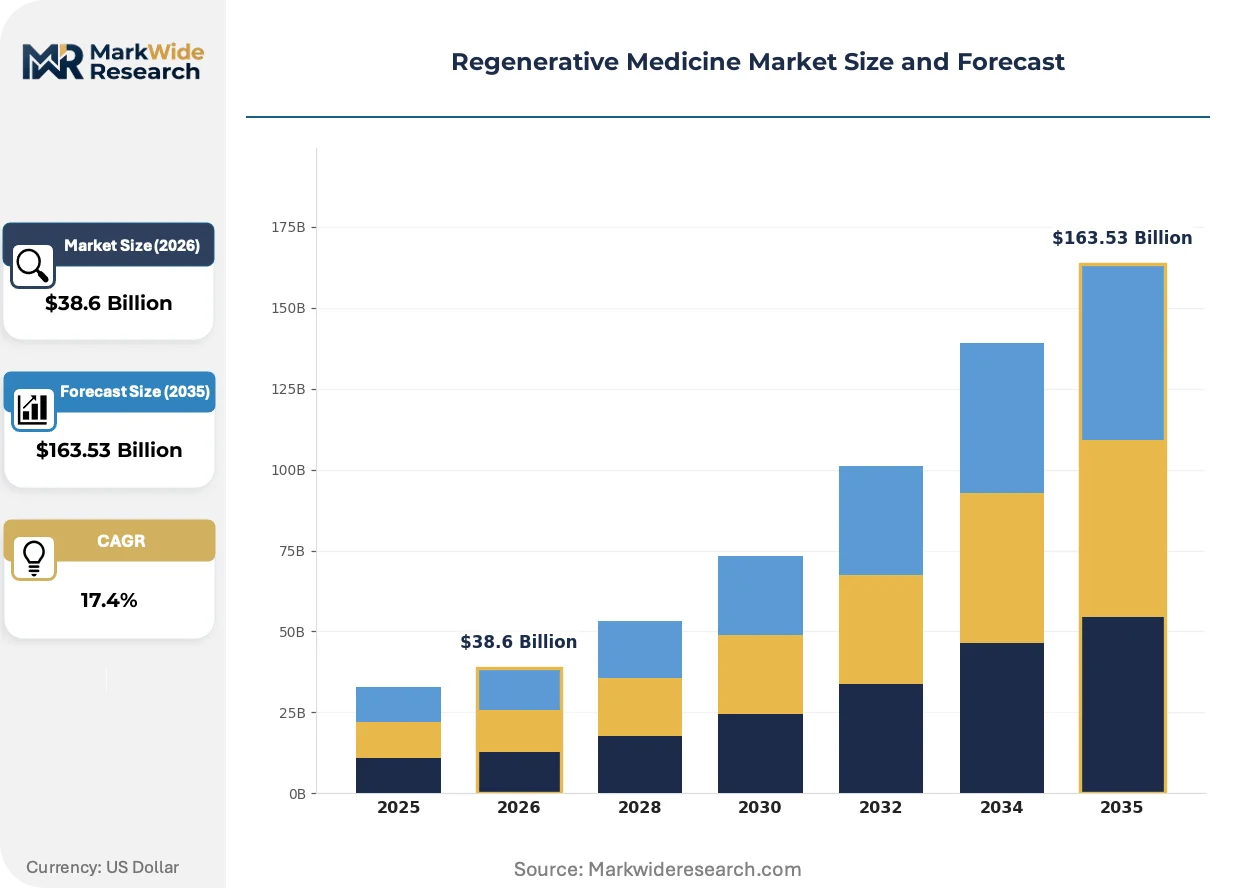
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $163.53 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Therapy, Tissue Engineering, Gene Therapy, Biomaterials Application: Orthopedics, Cardiovascular, Neurology, Dermatology Delivery Mode: Injectable, Implantable, Topical, Inhalation End User: Hospitals, Clinics, Research Laboratories, Academic Institutions |
| Companies Covered | Bluebird bio, Spark Therapeutics, Pfizer, Vericel Corporation, AbbVie, Johnson & Johnson, Novartis, Roche, Rocket Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regenerative Medicine Market Strategic Shifts & Innovations
Automation is displacing manual cell culture across manufacturing suites, while regulatory frameworks adapt to curative therapy economics and procurement models shift toward outcomes-based contracts.
Closed-system bioreactors are displacing open laminar flow hoods as the dominant cell expansion platform. Contract manufacturers are adopting Sartorius and Cytiva automated perfusion systems to reduce contamination risk. This shift is displacing labor-intensive manual passage protocols and compressing per-batch operator hours by 60 percent.
EMA's adaptive pathway framework is enabling conditional marketing authorization for regenerative medicines addressing unmet needs. The policy permits real-world evidence collection post-authorization, reducing upfront clinical trial burden. Gene therapy developers targeting rare diseases are prioritizing European filings to exploit this regulatory flexibility.
Hospital procurement committees are consolidating supplier relationships around integrated service contracts rather than per-dose purchasing. Academic medical centers in Germany and the Netherlands are negotiating multi-year partnerships with cell therapy manufacturers. This restructuring is most visible in CAR-T adoption, where bundled pricing covers apheresis, manufacturing, and infusion logistics.
Regenerative Medicine Market Segmentation
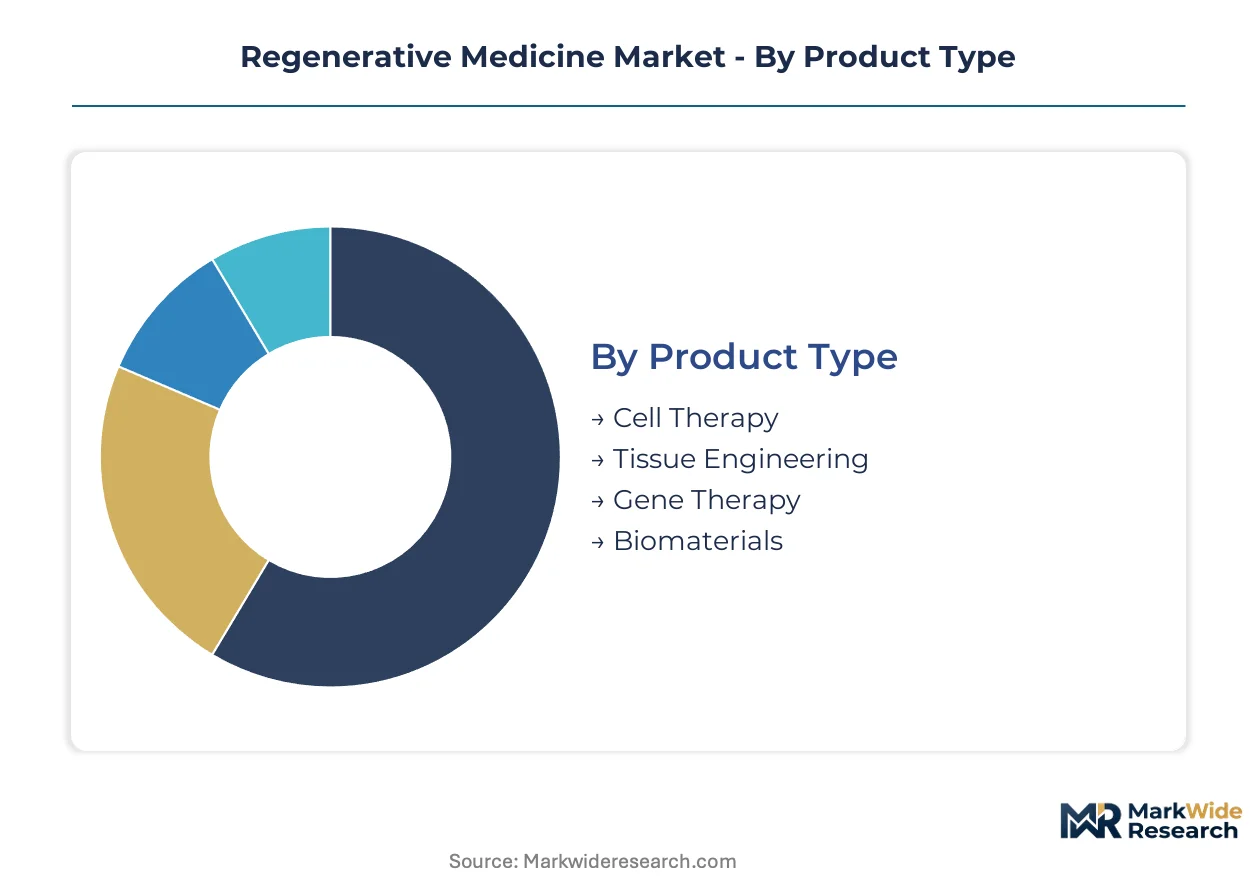
Regenerative medicine segmentation reflects divergent manufacturing requirements, regulatory pathways, and reimbursement structures across therapeutic modalities. Each dimension shapes investment allocation, partnership strategies, and geographic prioritization for developers and healthcare systems.
Product Type:
Cell therapy dominates domestic hospital adoption in the United States, while gene therapy pipelines target export-led revenue from European and Asian markets seeking curative interventions.
- Cell Therapy:Autologous and allogeneic cellular products manufactured under cGMP conditions with viability thresholds exceeding 90 percent. Demand concentrates in United States hospital systems integrating chimeric antigen receptor protocols into hematologic oncology standard care, driven by FDA's regenerative medicine advanced therapy designation compressing commercial timelines.
- Gene Therapy:Adeno-associated viral vector-based and ex vivo modified cell products delivering functional genetic material. European filings prioritize EMA's adaptive pathway framework for conditional marketing authorization, with German and Dutch academic medical centers negotiating bundled procurement contracts covering manufacturing and infusion logistics.
- Tissue Engineering:Engineered scaffolds and biologically active matrices for structural repair applications.
- Biomaterials:Synthetic and natural substrates supporting cellular attachment, proliferation, and differentiation in vivo.
Cell therapy holds the largest share; momentum sits with gene therapy.
Application:
Orthopedic applications command premium pricing tiers due to established reimbursement codes, while neurology represents the highest-risk, highest-reward development frontier.
- Orthopedics:Autologous cell therapies embedded in arthroscopy protocols for cartilage and bone regeneration. United States hospital systems drive institutional demand pull through standardized surgical suite integration, constrained by cGMP facility capex thresholds exceeding $50 million for commercial-scale manufacturing.
- Neurology:Gene and cell therapies targeting neurodegenerative and monogenic disorders with limited existing treatment options. Japanese developers exploit PMDA's Sakigake priority review framework for earlier revenue recognition than FDA timelines, accelerating conditional approval pathways.
- Cardiovascular:Regenerative interventions for myocardial repair and vascular regeneration.
- Dermatology:Engineered skin substitutes and cellular products for wound healing and aesthetic applications.
Orthopedics generates the deepest revenue pools; neurology presents the steepest expansion trajectory.
Delivery Mode:
Injectable formats align with outpatient clinic economics and scalable manufacturing, whereas implantable systems require surgical infrastructure concentration.
- Injectable:Parenteral administration of cellular suspensions, viral vectors, or biomaterial carriers. Cryopreserved products demand uninterrupted liquid nitrogen logistics with deviations above minus 150 degrees Celsius triggering batch discard, creating cold chain integrity constraints across distribution networks.
- Implantable:Surgically placed scaffolds, matrices, or cellular constructs. 3D bioprinting convergence with preoperative planning software enables patient-specific workflows in craniofacial reconstruction at German and Netherlands academic centers.
- Topical:Surface-applied cellular or biomaterial products for dermal and ocular indications.
- Inhalation:Aerosolized delivery for pulmonary and respiratory tract regenerative applications.
Injectable formats capture the broadest addressable market; implantable systems command the highest per-procedure value.
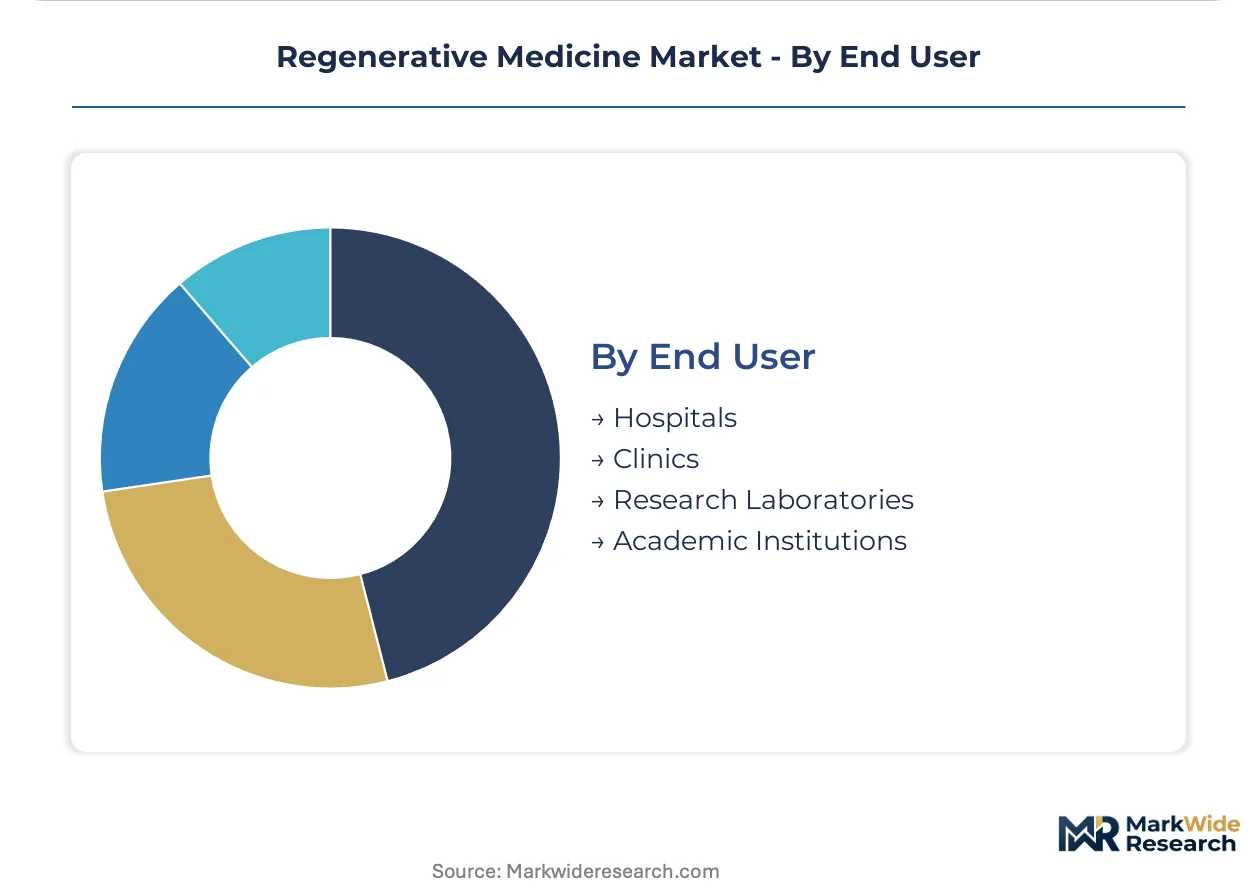
End User:
Hospitals anchor procurement volume through integrated service contracts, while research laboratories feed pipeline innovation despite talent migration pressures.
- Hospitals:Tertiary care systems with apheresis, manufacturing, and infusion capabilities. United States health systems consolidate supplier relationships around multi-year partnerships covering CAR-T logistics, shifting from per-dose purchasing to bundled pricing structures.
- Research Laboratories:Preclinical and early-phase clinical development facilities. Experienced aseptic operators are migrating from academic centers to commercial manufacturing facilities, hollowing out training pipelines and tightening technician scarcity.
- Clinics:Outpatient settings for administration of injectable and topical regenerative products.
- Academic Institutions:University-affiliated medical centers conducting investigator-initiated trials and technology translation.
Hospitals represent the dominant revenue channel; research laboratories face the most acute operational constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems in the United States consume regenerative medicine products through bundled service contracts, while European markets prioritize conditional approval pathways that accelerate patient access ahead of commercial scale.
United States
Tertiary care hospitals drive institutional demand through integrated CAR-T logistics and autologous therapy protocols. FDA's regenerative medicine advanced therapy designation compresses review timelines for qualifying products. The Greater Boston and San Francisco Bay Area clusters anchor cell therapy manufacturing infrastructure with cGMP facilities exceeding $50 million capital thresholds.
Germany
Academic medical centers in Heidelberg and Munich negotiate multi-year partnerships covering apheresis through infusion logistics. EMA's adaptive pathway framework enables conditional marketing authorization with real-world evidence collection post-authorization. The Rhine-Main and Upper Bavaria regions concentrate contract manufacturing capacity for viral vector production serving European gene therapy pipelines.
Japan
PMDA's Sakigake priority review framework attracts developers seeking earlier revenue recognition than FDA timelines permit. Conditional approval pathways for regenerative products accelerate commercialization of cell therapies targeting monogenic disorders. The Kanto region around Tokyo hosts the majority of domestic cGMP manufacturing infrastructure for induced pluripotent stem cell applications.
Switzerland
Swissmedic maintains alignment with EMA procedures while offering streamlined access for products addressing rare disease indications. Basel and Zurich anchor European headquarters for multinational developers leveraging the country's bilateral agreements with EU regulatory frameworks. The Lake Geneva region concentrates contract research organizations supporting early-phase regenerative medicine trials.
United Kingdom
The Medicines and Healthcare products Regulatory Agency operates an innovation passport scheme that accelerates development of transformative regenerative therapies. London and Cambridge cluster cell and gene therapy manufacturing alongside academic translation centers. The Golden Triangle between Oxford, Cambridge, and London feeds pipeline innovation despite technician migration pressures toward commercial facilities.
Regenerative Medicine Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in regenerative medicine, with pharmaceutical conglomerates leveraging existing manufacturing infrastructure while biotechnology specialists concentrate on platform technologies. The integrated tier commands distribution relationships with hospital systems and academic medical centers. Specialist players occupy positions in viral vector manufacturing, cell processing automation, and disease-specific therapeutic development. Competitive dynamics center on manufacturing capacity expansion and strategic partnerships that secure access to limited cGMP facility slots.
Among the integrated pharmaceutical tier, Novartis and Pfizer exemplify archetypes of leveraging existing biologics infrastructure for cell and gene therapy manufacturing. Johnson & Johnson occupies a position in orthopedic regenerative applications through its surgical channel network. These entities represent the scale-driven end of competitive positioning, where capital commitments for cleanroom construction and automated bioreactor deployment filter participation pools.
| Leading Market Players |
|---|
| Bluebird bio |
| Spark Therapeutics |
| Pfizer |
| Vericel Corporation |
| AbbVie |
| Johnson & Johnson |
| Novartis |
| Roche |
| Rocket Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
FDA's cGMP certification gates both manufacturing qualification and price differentiation in regenerative medicine, with facilities bearing the designation commanding premium contract manufacturing rates while uncertified competitors face exclusion from hospital system procurement lists. This regulatory threshold simultaneously constrains supply base expansion and stratifies pricing tiers across the value chain.
Pricing Analysis
Long-term offtake agreements dominate cell therapy manufacturing contracts, with hospital systems in the United States locking in multi-year bundled pricing covering apheresis through infusion logistics. Price differentiation rests on cGMP certification tier and cold chain capability grade, with cryopreserved product specialists capturing premiums over fresh-cell providers. Cost compression in autologous manufacturing is intensifying as automated bioreactors displace manual processing. Academic medical centers exhibit highest price sensitivity due to constrained research budgets, while integrated delivery networks show lowest sensitivity given outcomes-based contracting structures.
Supply Chain Analysis
Strategic stockpiling of viral vectors and cryopreserved cellular materials characterizes inventory strategy, with developers maintaining six-to-nine-month safety stocks against manufacturing slot scarcity. Supply concentrates in the United States, Germany, and Japan for cGMP manufacturing, with the Kanto region and Greater Boston anchoring induced pluripotent stem cell and CAR-T production respectively. Raw material dependencies center on fetal bovine serum, synthetic scaffolds, and AAV plasmid banks. Single-source vulnerability pervades contract manufacturing organization relationships, where limited qualified facility slots create allocation bottlenecks. Distribution runs through specialized cold chain logistics providers with liquid nitrogen infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regenerative medicine sits in early-cycle expansion, with FDA's RMAT designation accelerating commercial timelines and pulling institutional capital toward manufacturing infrastructure buildout ahead of reimbursement pathway maturation.
For Market Incumbents: Shield manufacturing margins by securing exclusive multi-year hospital system partnerships before automated platform standardization commoditizes processing expertise. Novartis and Pfizer archetypes should deepen backward integration into viral vector production to escape single-source dependencies. Capacity addition in the Rhine-Main region offers defensive positioning against EMA adaptive pathway competitors. For New Entrants and Emerging Players: Japan's Sakigake priority review fast-track enables earlier revenue recognition than FDA timelines, creating white-space entry for neurology-focused gene therapy developers. Target allogeneic off-the-shelf platforms as the most penetrable segment, where universal donor cell lines eliminate patient-specific logistics. Go-to-market through German academic medical center bundled procurement contracts offers established reimbursement precedent. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gene therapy manufacturing as AAV yield variability forces yield engineering investments and facility duplication. Long-term viability favors platform technology specialists with automated bioreactor deployment over manual processing-dependent assets. Acquisition target archetype: contract manufacturers with Sartorius or Cytiva perfusion system deployments and existing hospital system relationships. Watch FDA guidance on genome editing permanence as inflection signal for payer value framework reassessment.| Strategic Initiative | Industry Significance |
|---|---|
| RMAT Designation Pursuit | FDA's accelerated review compresses development timelines for qualifying hematologic therapies. |
| Automated Bioreactor Deployment | Sartorius and Cytiva perfusion systems reduce contamination risk and operator hour requirements. |
| Allogeneic Platform Development | Universal donor cell lines unlock scale economics previously reserved for small molecules. |
| Hospital System Partnership | Multi-year integrated service contracts shift procurement from per-dose to bundled pricing. |
| Viral Vector Manufacturing Scale-Up | Internal AAV production escapes single-source dependencies in contract manufacturing. |
Research Approach
A spread of perspectives from cell therapy manufacturing executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions driving this analysis. Primary interviews combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population modeling and top-down manufacturing capacity triangulation anchored volume and value estimates.
Segmentation dimensions modeled include therapeutic modality, application area, delivery format, and end-user channel across the projection horizon. CAGRs derived from manufacturing capacity expansion trajectories, regulatory approval velocity, and reimbursement pathway maturation curves. Forecast inputs incorporated cGMP facility construction pipelines, automated bioreactor adoption rates, and cold chain logistics infrastructure deployment.
Decision-makers should treat outputs as directional under assumptions of sustained FDA RMAT designation utilization and stable CMS reimbursement evidence requirements; material deviation would warrant model refresh. Revision becomes warranted when viral vector manufacturing yield improvements or allogeneic platform clinical success rates cross thresholds that alter competitive economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Hemophilia Treatment Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Induced Pluripotent Stem Cells Production Market
Cell & Gene Therapy
Regenerative Therapies Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
RNA Therapy Clinical Trials Market
Cell & Gene Therapy
Ipilimumab Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market
Cell & Gene Therapy
Asia-Pacific Gene Therapy Market
Cell & Gene Therapy
Global Dendritic Cell Cancer Vaccines Market
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market