
 Global Robotic Prosthetic Market | 2026-2036
Global Robotic Prosthetic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Robotic Prosthetic Market Foresight
Military rehabilitation programs are recalibrating procurement priorities toward advanced myoelectric systems. Ottobock SE & Co. KGaA leverages its German manufacturing base to dominate European defense contracts. Össur hf anchors its position through sustained R&D intensity in carbon fiber socket interfaces. HDT Global Inc. specializes in ruggedized military-grade prosthetic platforms for combat veteran populations.
A robotic prosthetic integrates electromechanical actuators, myoelectric sensors, and microprocessor-controlled joints to restore biomechanical function for amputees. These systems typically achieve response latencies under 300 milliseconds through electromyography signal processing and machine learning pattern recognition. Lower limb prosthetics command the largest installed base due to diabetes-related amputation volumes, while sensorized prosthetics represent the fastest-growing margin pool as haptic feedback commands premium pricing. Myoelectric prosthetics occupy the technology leadership position where artificial intelligence integration differentiates clinical outcomes.
The FDA breakthrough device program compresses timelines for novel prosthetic neurocontrollers, while the EU Medical Device Regulation imposes clinical evidence requirements that reshape competitive access across European markets. ISO 10328 structural testing standards govern mechanical validation for lower limb systems in international commerce. Stakeholders must monitor reimbursement policy shifts in Medicare and Germany's statutory health insurance as these determine effective market access for premium bionic platforms.
Market Dynamics
The FDA breakthrough device pathway compresses neurocontroller approval timelines, while Medicare reimbursement determinations in the United States and Germany's statutory health insurance rulings create binary market access conditions for premium bionic systems.
Growth Catalysts
- Myoelectric sensor fusion:Machine learning pattern recognition algorithms now process electromyography signals with sub-300 millisecond latencies, expanding clinical adoption among upper limb amputees in veteran rehabilitation programs.
- Japan's PMDA fast-track framework:The regulator's priority review designation for AI-enabled prosthetic controllers accelerates commercialization timelines for sensorized lower limb systems.
- Carbon fiber socket interfaces:Advanced composite manufacturing reduces component weight while improving load distribution, driving replacement demand among diabetes-related amputation populations.
Market Restraints
- Premium component cost concentration:Rare earth magnet supply for electromechanical actuators concentrates in Chinese processing facilities, creating input price volatility for myoelectric hand manufacturers.
- EU MDR clinical evidence requirements:The regulation's post-market surveillance obligations impose documentation burdens that extend certification timelines for Class III prosthetic neurocontrollers.
- Mechanical durability limitations:ISO 10328 structural testing standards expose fatigue failure modes in titanium knee joint assemblies under cyclic loading conditions.
Strategic Opportunities
- India's PLI scheme for medical devices:The production-linked incentive program offers tariff advantages for domestic manufacturing of prosthetic components, reducing import dependency for carbon fiber socket systems.
- Haptic feedback convergence:Integration of pressure-sensitive tactile sensors with myoelectric control systems creates premium pricing power in upper limb prosthetics for industrial workplace rehabilitation.
- Direct-to-patient digital channels:Telehealth-enabled fitting protocols bypass traditional orthotic clinic networks, opening access to rural amputee populations in Australia's remote territories.
Industry Challenges
- Bioelectrical signal processing expertise:Shortages of biomedical engineers trained in electromyography pattern recognition constrain R&D throughput for AI controller development teams.
- Multi-joint synchronization complexity:Integration of wrist rotation, grip force modulation, and finger individuation in myoelectric hands demands firmware architectures that exceed legacy microcontroller capabilities.
- Socket fit standardization gaps:Absence of universal volumetric measurement protocols forces custom fabrication workflows that extend patient onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Robotic Prosthetic Market |
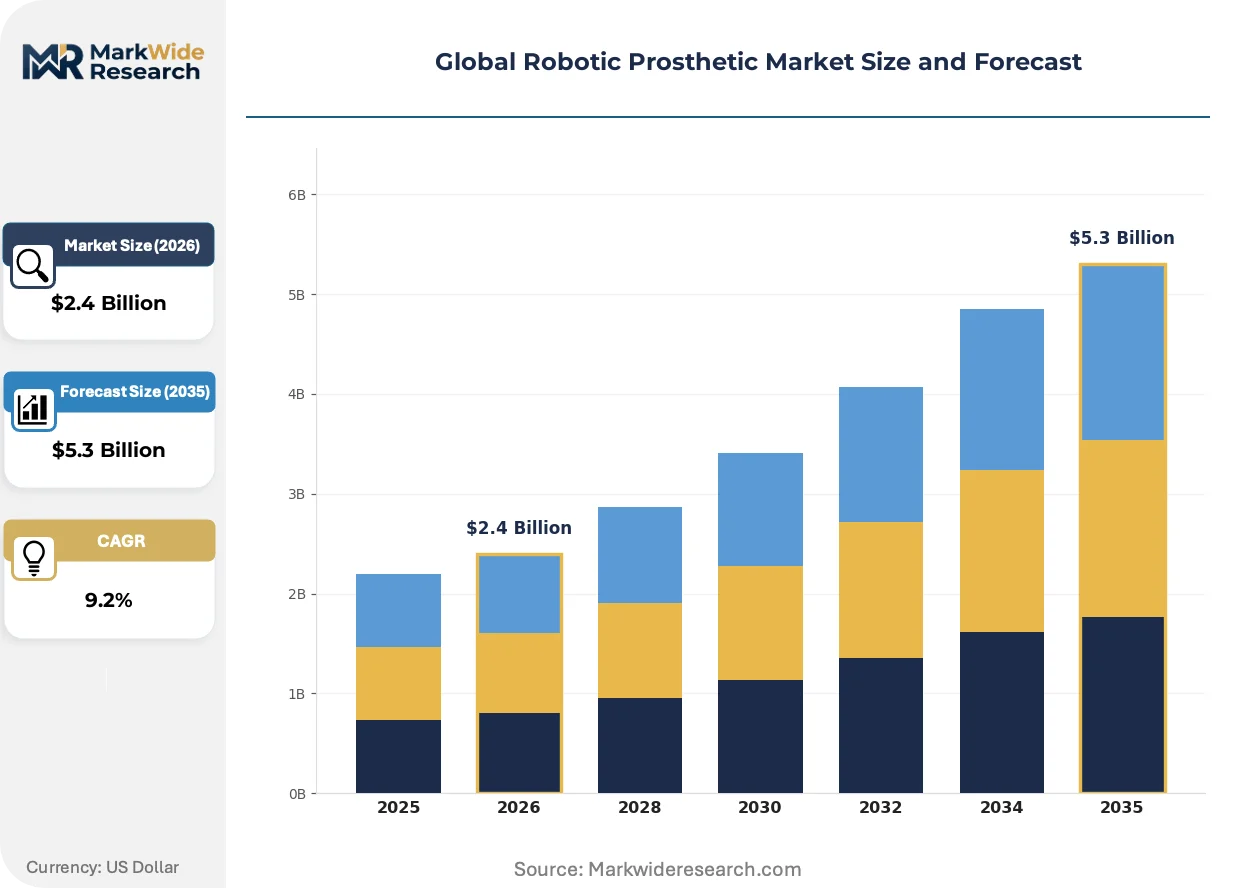
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.3 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upper Limb Prosthetics, Lower Limb Prosthetics, Myoelectric Prosthetics, Bionic Limbs, Sensorized Prosthetics Technology: Electromyography, Inertial Measurement Units, Force Sensors, Artificial Intelligence, Machine Learning Application: Amputation Rehabilitation, Physical Therapy, Sports Enhancement, Military Use, Personal Mobility End User: Prosthetic Clinics, Rehabilitation Centers, Research Institutions, Home Care, Veteran Support Agencies |
| Companies Covered | Blatchford Group Ltd, HDT Global Inc., Ottobock SE & Co. KGaA, Mobius Bionics LLC, SynTouch, Inc., Össur hf, Fillauer LLC, Myomo Inc., Touch Bionics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Robotic Prosthetic Market Shifts & Advancements
Artificial intelligence inference is migrating from cloud architectures to edge processors embedded within prosthetic joints, compressing response latencies while reducing dependency on continuous connectivity. This architectural shift is redrawing competitive boundaries between component suppliers and system integrators.
Edge AI processors embedded directly within myoelectric hand assemblies execute real-time grip pattern classification without external computing dependencies. Military rehabilitation programs in the United States and Germany are piloting these systems for field-deployable veteran care. The technology is decentralizing clinical decision-making authority from centralized prosthetic clinics to point-of-care fitting specialists.
The EU Medical Device Regulation's post-market clinical follow-up requirements are forcing manufacturers to deploy embedded diagnostic telemetry in lower limb systems. This mandate generates continuous biomechanical performance data that feeds back into design iterations. Sensorized knee and ankle assemblies face the steepest compliance documentation burdens, compressing product development cycles for European market entrants.
Veteran affairs procurement offices are unbundling after-sales service contracts from hardware acquisition, creating separate competitive arenas for maintenance providers. Germany's statutory health insurance funds are piloting similar service-separation models for myoelectric upper limb systems. This purchasing pattern shift is most visible in United States Department of Defense rehabilitation contracts, where third-party technical service specialists now bid independently of device manufacturers.
Global Robotic Prosthetic Market Segmentation
Segmentation in the robotic prosthetic market reveals how technology specialization, clinical application, and procurement channel each create distinct competitive arenas. Manufacturers configure their product portfolios around specific signal processing architectures and end-user workflows rather than pursuing undifferentiated coverage.
Product Type:
Electromechanical sophistication and sensor integration density define product tiering across prosthetic categories.
- Lower Limb Prosthetics:Titanium and carbon fiber structural assemblies with microprocessor-controlled knee and ankle joints manage ground reaction forces for diabetes-related and trauma amputations. Demand concentrates in Germany and the United States where statutory reimbursement frameworks cover premium hydraulic and computerized knee systems.
- Myoelectric Prosthetics:Surface electromyography sensors detect residual muscle contractions to trigger electromechanical hand and wrist actuation with sub-300 millisecond response latencies. Veteran rehabilitation programs in the United States military procurement channels drive volume for multi-articulating hand systems with individual finger control.
- Upper Limb Prosthetics:Body-powered cable systems and passive cosmetic devices serve cost-sensitive patient segments through prosthetic clinic networks.
- Bionic Limbs:Fully integrated electromechanical systems combining powered joints with sensory feedback loops target premium clinical outcomes in research institution settings.
- Sensorized Prosthetics:Embedded pressure and inertial sensors enable closed-loop control algorithms for gait optimization and object manipulation.
Lower limb prosthetics lead on scale; myoelectric systems lead on momentum.
Technology:
Signal processing architecture determines clinical functionality and regulatory classification pathways.
- Artificial Intelligence:Edge-deployed neural networks execute real-time pattern classification for grip selection and gait phase detection without cloud connectivity dependencies. Japan's PMDA fast-track designation accelerates approval timelines for AI-enabled controllers in sensorized lower limb systems.
- Electromyography:Surface electrode arrays capture residual muscle electrical activity for proportional control of prosthetic hand opening velocity and grip force. Signal processing expertise shortages constrain R&D throughput for advanced pattern recognition algorithms.
- Machine Learning:Adaptive algorithms personalize control parameters to individual patient biomechanics through continuous use data.
- Inertial Measurement Units:Accelerometer and gyroscope fusion enables spatial orientation tracking for stumble recovery and terrain adaptation.
- Force Sensors:Strain gauge and capacitive pressure transducers provide haptic feedback channels for closed-loop motor control.
Electromyography dominates current installations; artificial intelligence is gaining share fastest.
Application:
Clinical setting and functional objective shape device specification requirements and procurement authority.
- Amputation Rehabilitation:Post-surgical fitting protocols and gait training programs in rehabilitation centers require adjustable socket interfaces and progressive component upgrades. Medicare reimbursement determinations in the United States create binary market access conditions for microprocessor-controlled systems.
- Military Use:Ruggedized platforms for combat veteran populations demand field-serviceable components and rapid deployment logistics through defense procurement channels.
- Physical Therapy:Progressive resistance loading and biomechanical feedback systems support motor relearning in clinical environments.
- Sports Enhancement:Specialized sprinting prostheses and swimming adaptations serve competitive athlete segments through custom fabrication workflows.
- Personal Mobility:Daily living activity support drives replacement demand for durable mechanical knee systems in home care settings.
Amputation rehabilitation commands the largest patient volume; military use shows the steepest expansion trajectory.
End User:
Procurement authority and technical service capability determine channel structure and pricing power distribution.
- Prosthetic Clinics:Orthotic and prosthetic practitioner networks conduct patient assessment, socket fabrication, and device fitting with direct billing to national health insurance funds. Germany's statutory health insurance pilot programs are unbundling after-sales service from hardware acquisition.
- Veteran Support Agencies:United States Department of Veterans Affairs and comparable military rehabilitation programs in Germany issue consolidated tenders for myoelectric upper limb systems with multi-year maintenance contracts.
- Rehabilitation Centers:Hospital-affiliated facilities manage acute post-amputation care and initial prosthetic training protocols.
- Research Institutions:Academic medical centers pilot neuroprosthetic interfaces and brain-machine control systems.
- Home Care:Direct-to-patient digital channels and telehealth-enabled fitting protocols expand access for rural amputee populations.
Prosthetic clinics anchor commercial volume; veteran support agencies are restructuring procurement most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EU MDR compliance costs diverge sharply from India's production-linked incentive structures. Manufacturers now route carbon fiber socket production through South Asian facilities while retaining neurocontroller assembly in German precision clusters.
United States
Veteran Affairs procurement channels and Medicare reimbursement determinations drive premium bionic limb volumes. The FDA breakthrough device pathway compresses neurocontroller approval timelines for AI-enabled upper limb systems. Pittsburgh and Minneapolis anchor defense rehabilitation research clusters where military contract specifications shape technical requirements.
Germany
Statutory health insurance rulings create binary market access conditions for myoelectric systems, with Ottobock's Duderstadt manufacturing base dominating European defense contracts. The EU MDR imposes clinical evidence requirements that reshape competitive access across continental markets. Bavaria's medical technology corridor concentrates precision actuator fabrication and socket interface R&D.
Japan
PMDA fast-track designation for AI-enabled prosthetic controllers accelerates commercialization timelines for sensorized lower limb systems. METI funding programs support edge AI processor integration in myoelectric hand assemblies. The Kanto region's robotics research institutes pilot closed-loop haptic feedback systems for industrial workplace rehabilitation.
India
The PLI scheme for medical devices offers tariff advantages for domestic manufacturing of prosthetic components, reducing import dependency for carbon fiber socket systems. CDSCO regulatory harmonization with ISO standards streamlines market entry for foreign device manufacturers. Gujarat and Karnataka host emerging fabrication clusters targeting export markets in Southeast Asia and Africa.
Australia
Telehealth-enabled fitting protocols bypass traditional orthotic clinic networks, expanding access for rural amputee populations in remote territories. The TGA's priority review pathway aligns with FDA breakthrough timelines for neurocontroller submissions. Queensland's veteran rehabilitation centers pilot direct-to-patient digital channels for upper limb system procurement.
Global Robotic Prosthetic Market Competitive Landscape
Strategic partnerships dominate the current landscape as component suppliers and system integrators redraw competitive boundaries around edge AI architectures. The vendor base clusters into three tiers: German precision manufacturers with defense contract anchoring, Icelandic and American specialists in carbon fiber interfaces and ruggedized platforms, and emerging Asia-Pacific fabricators leveraging production incentives. Two strategic archetypes define positioning: vertically integrated device-originators controlling socket-to-joint workflows, and modular assemblers sourcing electromechanical actuators from rare-earth magnet suppliers. Technology licensing and geographic expansion constitute the dominant competitive moves, with unbundling of after-sales service contracts creating separate bidding arenas for maintenance providers.
Within the defense-contract anchoring tier, HDT Global Inc. and Ottobock SE & Co. KGaA exemplify divergent geographic specializations—American ruggedization expertise versus German precision manufacturing integration. Össur hf occupies a position representing Nordic carbon fiber interface specialization, while Blatchford Group Ltd anchors British lower-limb system fabrication. These named entities sit within a broader ecosystem where Mobius Bionics LLC, SynTouch Inc., Fillauer LLC, Myomo Inc., and Touch Bionics Inc. populate specialist niches across myoelectric control and sensory feedback domains.
| Leading Market Players |
|---|
| Blatchford Group Ltd |
| HDT Global Inc. |
| Ottobock SE & Co. KGaA |
| Mobius Bionics LLC |
| SynTouch, Inc. |
| Össur hf |
| Fillauer LLC |
| Myomo Inc. |
| Touch Bionics Inc. |
| Others |
Supply & Pricing Matrix
Rare earth magnet processing costs cascade through myoelectric hand assemblies from Chinese refining facilities to German precision manufacturers, stratifying final device pricing across defense procurement tiers and statutory reimbursement ceilings.
Pricing Analysis
Orthotic clinic network markups separate premium bionic systems from standard myoelectric devices. Pricing stratifies across premium, standard, and economy tiers based on AI controller certification level and after-sales service bundling. Cost compression in sensorized lower limb systems intensifies because veteran affairs procurement offices unbundle maintenance contracts from hardware acquisition. Military rehabilitation programs show least price sensitivity; rural home care segments through telehealth channels exhibit highest.
Supply Chain Analysis
India's PLI scheme domestic-content mandates reshape carbon fiber socket sourcing away from Icelandic and German incumbent suppliers. Component fabrication concentrates in China for rare earth magnet actuators, Germany for precision neurocontrollers, and India for emerging carbon fiber assembly. Raw material dependencies span neodymium magnet alloys, medical-grade titanium, and aerospace-specification carbon fiber prepregs. Single-source vulnerability concentrates in Chinese rare earth processing. Distribution runs through prosthetic clinic networks with direct-to-patient digital channels expanding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in AI-enabled controller tiers where edge processor cost curves steepen and veteran procurement premiums sustain.
For Market Incumbents: Deepen backward integration into rare earth magnet supply chains to offset Chinese processing volatility. Expand captive socket fabrication capacity in India's PLI-eligible zones. Defend against modular assembler entrants by locking multi-year defense rehabilitation contracts before service unbundling spreads to Germany's statutory health insurance funds. For New Entrants and Emerging Players: Rural Australian amputee populations underserved by traditional orthotic clinic networks offer telehealth-enabled fitting protocol entry points. Target India's domestic manufacturing incentive zones for carbon fiber socket export platforms. Pursue direct-to-patient digital channel partnerships with Queensland veteran rehabilitation centers. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR clinical evidence burdens exceed mid-tier R&D budgets. Long-term viability favors vertically integrated device-originators controlling socket-to-joint workflows over modular assemblers dependent on actuator suppliers. Signal to watch: PMDA fast-track approval velocity for AI-enabled controllers as predictor of tier reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Processor Integration | Embedded neural networks in myoelectric hands bypass cloud latency for sub-300 millisecond response. |
| FDA Breakthrough Device Submission | Accelerated neurocontroller approval compresses commercialization timelines for veteran rehabilitation channels. |
| Carbon Fiber Socket Manufacturing Scale-Up | India PLI tariff advantages reduce import dependency for diabetes-related amputation populations. |
| Telehealth-Enabled Fitting Protocol Launch | Direct-to-patient channels bypass orthotic clinic networks in Australia's remote territories. |
| After-Sales Service Unbundling | Separate maintenance bidding arenas emerge as US Department of Defense procurement patterns shift. |
Research Methodology
Multiple input streams — prosthetist practitioner interviews, defense procurement officer consultations, biomedical engineer surveys, and regulatory affairs specialist panels — were reconciled against FDA 510(k) filings, PMDA approval databases, Medicare reimbursement determinations, and EU MDR notified body documentation. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation anchored segmentation outputs.
Historical reimbursement policy trajectories cross-referenced against panel-based clinical adoption assumptions across the projection horizon. Segmentation dimensions spanned product type, signal processing technology, application setting, and procurement channel authority. CAGRs derived from fitted patient population growth rates and premium tier mix shifts. Forecast inputs incorporated veteran affairs budget appropriations and statutory health insurance ruling calendars.
Underlying measurement precision varies by segment; military procurement channels carry tighter precision than emerging telehealth direct-to-patient volumes. Forecasts reflect documented reimbursement policy assumptions. Regulatory timeline delays, rare earth supply disruptions, or AI controller safety events could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Bioartificial Renal Assist Devices Market
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
Tissue Expansion Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
3D Bioprinting Market
Biomedical Engineering
Biological Derived Devices Market
Biomedical Engineering
Bio-Engineered Stent Market
Biomedical Engineering
Tissue Engineered Skin Substitute Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
Global Single Use Bioprocessing Probes and Sensors Market
Biomedical Engineering
Protein Engineering Market
Biomedical Engineering
Bionic Eye Market
Biomedical Engineering
Medical Biomimetics Market