
 Tissue Expansion Market | 2026-2036
Tissue Expansion Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Expansion Market Insights
The tissue expansion device landscape is recalibrating around a widening gap between premium silicone expanders with integrated ports and commodity-grade alternatives serving price-sensitive procurement channels. Mentor Worldwide LLC leverages its vertically integrated silicone supply chain to sustain margin capture in the premium reconstructive segment. Guangzhou Wanhe Plastic Materials Co., Ltd. competes on manufacturing scale, while Polytech Health & Aesthetics GmbH differentiates through specialized surface texturing technologies that reduce capsular contracture rates.
Tissue expansion refers to the controlled mechanical distension of skin and soft tissue through implanted or external devices that generate sustained tension, typically employing silicone elastomer shells filled with saline via remote injection ports to stimulate neovascularization and histogenesis for subsequent defect coverage. Implantable expanders dominate current procedural volume, though vacuum expanders are gaining traction in burn treatment protocols where serial excision timing demands non-invasive incremental expansion. Hydraulic expansion technology leads in reconstructive surgery applications, while pneumatic approaches occupy niche positions in pediatric craniofacial programs where pressure modulation precision proves critical.
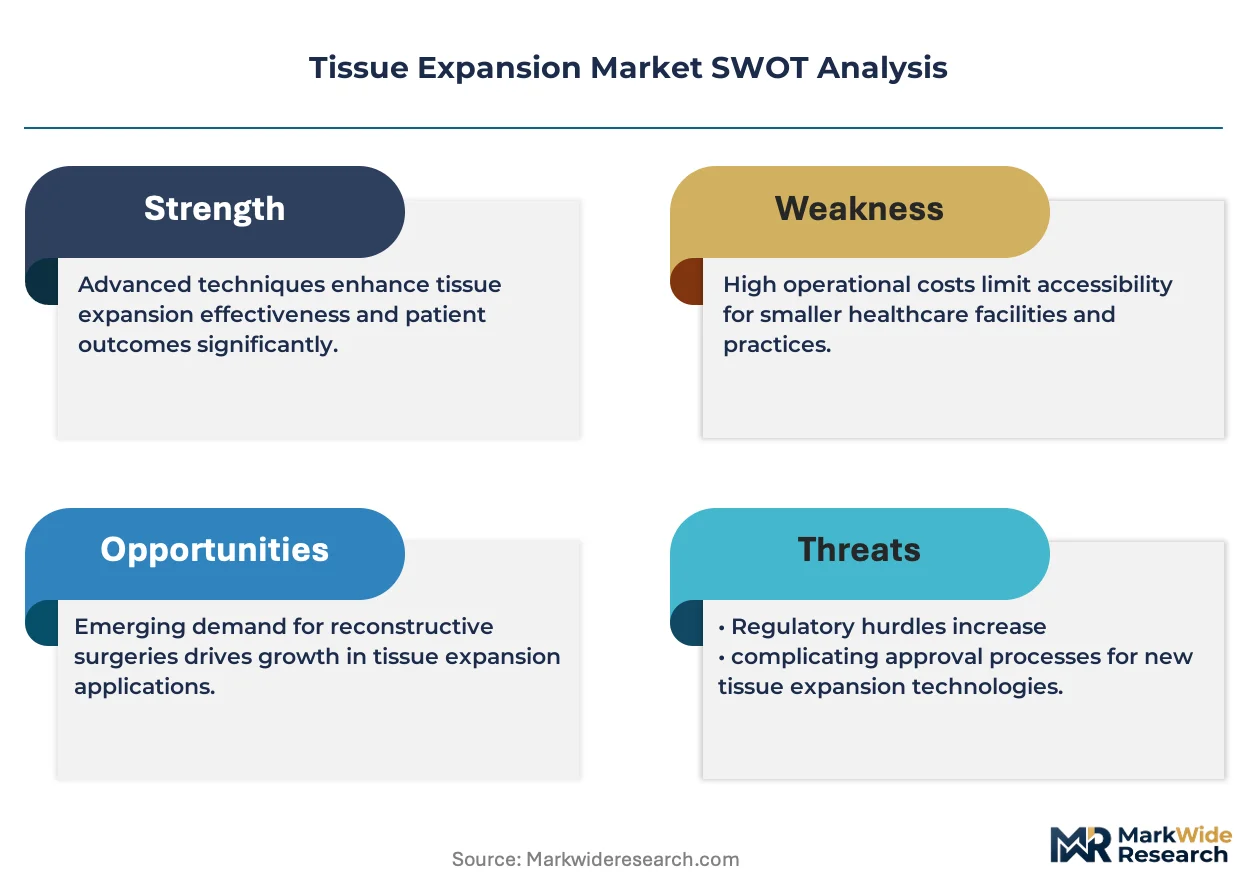
FDA 510(k) premarket notification requirements and the EU MDR's reinforced biocompatibility testing under ISO 10993 are elevating compliance costs and extending approval timelines for new expander geometries. Japan's PMDA maintains distinct material qualification standards for long-term implantable silicone devices, creating additional regulatory segmentation for manufacturers seeking multi-region commercialization. Stakeholders must monitor evolving reimbursement thresholds for post-oncologic reconstruction across national health systems, as coverage determination shifts will directly reshape volume allocation between hospital-based surgical suites and ambulatory surgical centers.
Market Dynamics
Reimbursement policy divergence between national health systems and private payers is fragmenting procedural volume allocation across hospital-based surgical suites and ambulatory surgical centers.
Growth Catalysts
- Post-mastectomy reconstruction mandates:The United States and Germany maintain statutory coverage for breast reconstruction following oncologic surgery, sustaining implantable expander demand through predictable procedural pipelines.
- EU MDR biocompatibility frameworks:Reinforced ISO 10993 testing requirements under the Medical Device Regulation are accelerating manufacturer investment in surface modification technologies that reduce capsular contracture incidence.
- Vacuum-assisted tissue expansion:Non-invasive external devices are capturing share in burn treatment protocols where serial excision timing benefits from incremental, needle-free distension.
Market Restraints
- Silicone raw material concentration:Medical-grade elastomer supply chains cluster in Germany and Japan, exposing manufacturers to input cost volatility and qualification timeline extensions.
- PMDA material qualification divergence:Japan's Pharmaceuticals and Medical Devices Agency maintains distinct long-term implantable silicone standards, forcing redundant testing for multi-region commercialization.
- External tissue expansion substitutes:Autologous tissue transfer techniques and acellular dermal matrices compete for defect coverage applications, compressing addressable volume for implantable devices.
Strategic Opportunities
- Pediatric craniofacial programs:Pneumatic expansion systems with precision pressure modulation are penetrating underdeveloped North American and European pediatric reconstructive centers.
- Ambulatory surgical center channel expansion:Outpatient procedural migration creates demand for pre-filled or rapid-fill expander configurations that reduce injection visit frequency.
- Integrated port telemetry convergence:Pressure-sensing expanders combined with wireless monitoring systems enable remote volume tracking, opening subscription-based service models.
Industry Challenges
- Specialized surgical training scarcity:Tissue expansion technique mastery requires extended fellowship exposure, limiting qualified operator pools in community hospital settings.
- 510(k) documentation burden:FDA premarket notification pathways for novel expander geometries demand extensive mechanical testing and clinical equivalence data, extending development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Expansion Market |
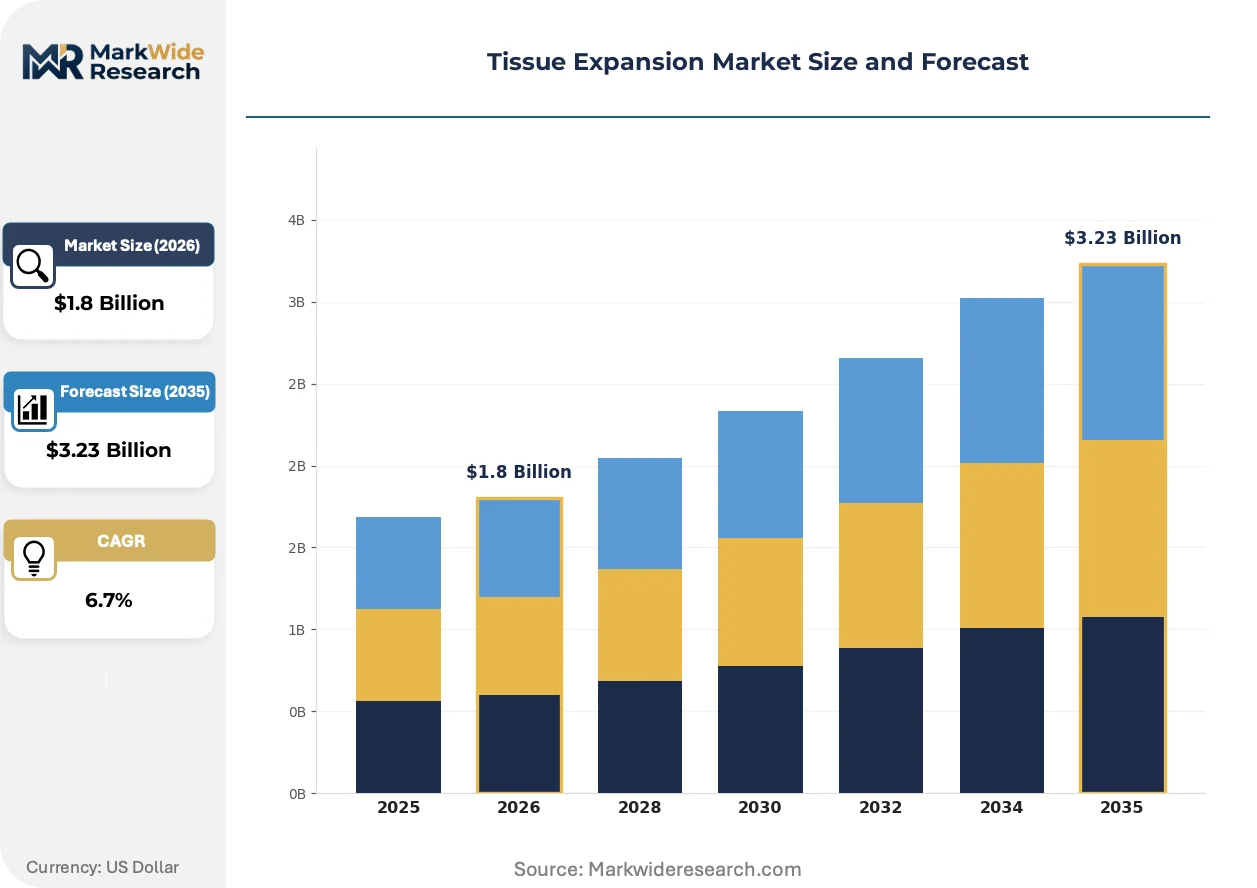
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Expanders, Vacuum Expanders, Balloon Expanders, Tissue Expanders End User: Hospitals, Surgical Centers, Clinics, Research Laboratories Application: Reconstructive Surgery, Burn Treatment, Trauma Repair, Cosmetic Surgery Technology: Mechanical Expansion, Hydraulic Expansion, Pneumatic Expansion, Dynamic Expansion |
| Companies Covered | Mentor Worldwide LLC, PMT Corporation, AbbVie Inc., Sientra, Inc., Groupe SEBBIN SAS, Guangzhou Wanhe Plastic Materials Co., Ltd., KOKEN CO., LTD., GC Aesthetics, Polytech Health & Aesthetics GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Expansion Market Trends and Innovations
Device architecture is converging around integrated functionality that reduces procedural touchpoints while expanding indication scope beyond traditional reconstructive applications.
Shape-memory polymer ports are integrating self-sealing valve mechanisms that eliminate the external injection dome, reducing infection vectors and improving patient comfort during expansion phases. Academic medical centers in the United States and Japan are piloting these configurations in post-mastectomy protocols. This convergence is compressing the competitive moat between premium silicone expanders and mid-tier alternatives by standardizing port reliability as a baseline expectation.
The EU MDR's reinforced biocompatibility surveillance requirements are compelling manufacturers to maintain post-market clinical follow-up registries for silicone-based implants. Industrial consequence includes elevated compliance staffing and documentation infrastructure that favors larger device portfolios capable of amortizing fixed regulatory costs. Surface texturing technologies with demonstrated capsular contracture reduction are capturing disproportionate notified body attention and faster conformity assessment timelines.
Hospital procurement committees are consolidating supplier relationships through dual-source contracting frameworks that mandate redundant manufacturing capacity for critical implant categories. Ambulatory surgical centers are displacing traditional distributor intermediaries through direct manufacturer agreements that bundle expander supply with disposable injection kits. This channel restructuring is most visible in United States metropolitan markets where health system consolidation has concentrated purchasing authority.
Tissue Expansion Market Segmentation
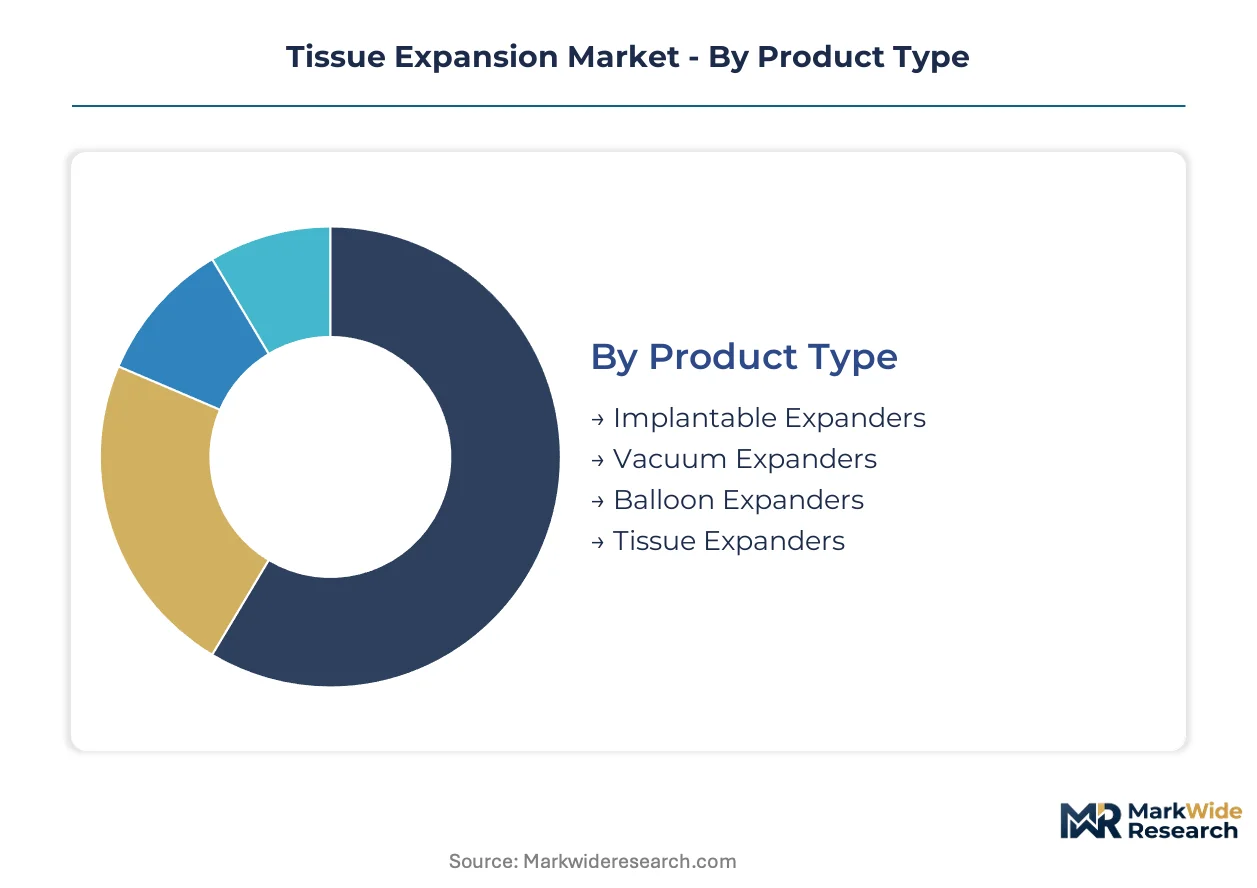
Tissue expansion device selection hinges on procedural setting, anatomical target, and expansion timeline requirements. Procurement patterns diverge sharply between academic medical centers prioritizing precision control and ambulatory facilities optimizing for throughput economics.
Product Type:
Hospital procurement committees distinguish devices by invasiveness profile and port integration sophistication when allocating capital budgets across surgical service lines.
- Implantable Expanders:Silicone elastomer shells with remote injection ports enable controlled saline distension over weeks. Post-mastectomy reconstruction programs in the United States and Germany drive sustained volume through statutory reimbursement mandates.
- Vacuum Expanders:External negative-pressure devices apply non-invasive incremental tension via sealed domes. Burn centers in Japan and specialized trauma units adopt these configurations where needle-free expansion preserves fragile tissue beds.
- Balloon Expanders:Rapid-inflation designs suit acute defect coverage with shorter expansion windows.
- Tissue Expanders:General-purpose configurations serve lower-acuity applications with standardized geometries.
Implantable expanders lead volumes today; vacuum expanders are gaining share fastest in burn treatment protocols.
End User:
Facility reimbursement structure and case complexity determine device specification tier and supplier relationship depth.
- Hospitals:Academic medical centers with fellowship-trained plastic surgery programs handle complex craniofacial and oncologic reconstruction requiring precision pressure modulation. These institutions command premium device portfolios with integrated telemetry.
- Surgical Centers:Outpatient migration in United States metropolitan markets favors pre-filled or rapid-fill configurations that compress injection visit frequency and align with bundled payment structures.
- Clinics:Lower-volume settings rely on distributor-mediated procurement with limited technical support.
- Research Laboratories:Preclinical and biomechanical testing facilities drive demand for prototype geometries and custom-specification expanders.
Hospitals dominate absolute volume; surgical centers are expanding most quickly as procedural migration accelerates.
Application:
Clinical indication dictates expansion rate, pressure tolerance, and surface texturing requirements for optimal histogenic response.
- Reconstructive Surgery:Post-oncologic breast and head-neck procedures require months-long expansion with capsular contracture mitigation through specialized surface architectures.
- Burn Treatment:Serial excision timing in thermal injury protocols benefits from vacuum-assisted external expansion that preserves vascularized wound beds.
- Trauma Repair:Acute soft-tissue loss from mechanical injury employs rapid-expansion techniques with shorter latency periods.
- Cosmetic Surgery:Elective augmentation and revision procedures concentrate in private-pay markets with price-sensitive procurement.
Reconstructive surgery anchors current volume; burn treatment applications show the steepest expansion trajectory as external device technology matures.
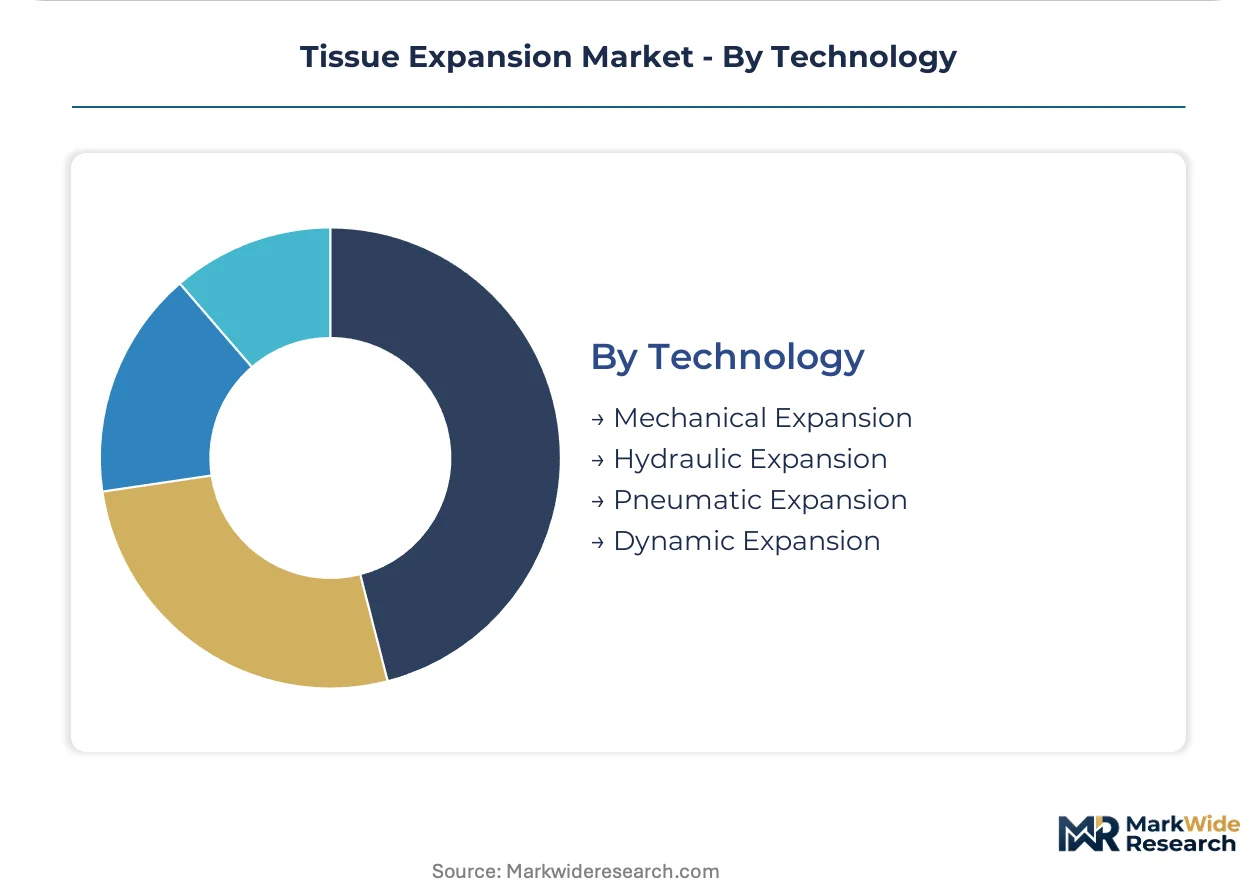
Technology:
Pressure generation mechanism determines precision, patient compliance, and operator training burden across procedural contexts.
- Hydraulic Expansion:Saline-mediated distension through implanted reservoirs delivers predictable volume increments with established reimbursement pathways.
- Mechanical Expansion:Screw or ratchet-based devices provide tactile feedback for craniofacial applications requiring millimeter-scale advancement.
- Pneumatic Expansion:Compressed gas systems enable fine pressure modulation in pediatric programs where tissue compliance varies significantly.
- Dynamic Expansion:Programmable feedback loops with sensor integration represent emerging configurations for remote monitoring trials.
Hydraulic expansion maintains dominant share; pneumatic systems are climbing the fastest in specialized pediatric centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium reconstructive volume through statutory reimbursement guarantees, while Japan's PMDA material standards create a parallel qualification pathway that segments commercialization strategies for silicone-based devices.
United States
Post-mastectomy reconstruction mandates under federal law sustain implantable expander demand through predictable procedural pipelines. FDA 510(k) pathways enforce mechanical testing and clinical equivalence documentation for novel geometries. Academic medical centers in Boston and New York anchor complex craniofacial programs requiring precision pressure modulation.
Germany
Statutory health insurance coverage for oncologic reconstruction stabilizes procedural volume across hospital-based surgical suites. EU MDR biocompatibility frameworks under ISO 10993 accelerate surface modification investments. Industrial clusters in North Rhine-Westphalia concentrate medical-grade silicone elastomer supply chains for device manufacturers.
Japan
Burn treatment protocols in specialized trauma units drive vacuum expander adoption for needle-free tissue preservation. PMDA maintains distinct long-term implantable silicone standards requiring redundant testing protocols. Tokyo and Osaka metropolitan areas concentrate pediatric craniofacial programs where pneumatic pressure modulation proves critical.
China
Expanding reconstructive surgery capacity in tier-one hospitals generates demand for rapid-fill expander configurations. NMPA device registration pathways are tightening biocompatibility documentation for imported silicone implants. Yangtze River Delta manufacturing bases supply commodity-grade alternatives to price-sensitive procurement channels.
Tissue Expansion Market Competitive Landscape
Top-tier vendors anchor premium silicone portfolios with integrated supply chains, while mid-tier fabricators compete on manufacturing scale and surface texturing specialization. The vendor base stratifies across three functional tiers: vertically integrated specialists with captive elastomer supply, regional scale manufacturers serving price-sensitive channels, and surface technology innovators differentiating through capsular contracture mitigation. Consolidation pressures favor portfolios capable of amortizing fixed regulatory costs across multiple device geometries. Dominant competitive moves include backward integration into medical-grade silicone supply and direct contracting with ambulatory surgical centers.
Among North American and European manufacturers, Mentor Worldwide LLC and Polytech Health & Aesthetics GmbH exemplify premium-tier positioning through specialized surface architectures, while Guangzhou Wanhe Plastic Materials Co., Ltd. occupies the scale-driven fabrication segment serving high-volume procurement channels.
| Leading Market Players |
|---|
| Mentor Worldwide LLC |
| PMT Corporation |
| AbbVie Inc. |
| Sientra, Inc. |
| Groupe SEBBIN SAS |
| Guangzhou Wanhe Plastic Materials Co., Ltd. |
| KOKEN CO., LTD. |
| GC Aesthetics |
| Polytech Health & Aesthetics GmbH |
| Others |
Pricing and Supply Chain Analysis
Specialized silicone molding technicians in the Yangtze River Delta and North Rhine-Westphalia anchor manufacturing labor pools, with wage differentials between these regions driving three-tier pricing spreads across premium, standard, and economy device tiers.
Pricing Analysis
Bundled service contracts that combine expander supply with disposable injection kits and remote monitoring subscriptions now command premium positioning against unbundled transactional procurement. Pricing stratifies across premium, standard, and economy tiers based on surface texturing certification grade and after-sales telemetry integration. Cost compression in the economy tier is intensifying because Chinese manufacturers are scaling rapid-fill configurations for price-sensitive ambulatory surgical centers. Hospital procurement committees show least price sensitivity, while metropolitan outpatient clinics exhibit highest elasticity.
Supply Chain Analysis
Workforce availability for medical-grade silicone compounding concentrates in Germany, Japan, and select Chinese provinces, creating geographic asymmetries in qualified production capacity. Raw material sourcing draws from specialized elastomer feedstock in North Rhine-Westphalia, precision molding equipment from Japanese suppliers, and sterilization packaging from domestic converters. Single-source vulnerability runs through concentrated medical-grade silicone resin qualification pathways. Distribution runs through direct manufacturer agreements with consolidated health systems and distributor-mediated channels for independent surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tissue expansion market functions as a stable compounder anchored by statutory post-mastectomy reconstruction mandates that generate predictable procedural pipelines across multiple national health systems.
For Market Incumbents: Hedge against vacuum expander substitution in burn treatment by securing backward integration into medical-grade silicone supply chains and accelerating surface texturing R&D investments that reduce capsular contracture rates. Channel control through direct ambulatory surgical center contracting provides defensive moat against Chinese scale competitors.
For New Entrants and Emerging Players: EU MDR biocompatibility frameworks in Europe open a window for surface technology specialists to capture notified body attention through demonstrated ISO 10993 compliance. Pediatric craniofacial pneumatic systems in underpenetrated North American academic centers and rapid-fill configurations for United States outpatient migration represent the most penetrable white-space targets. Go-to-market execution should prioritize hospital biomedical engineering relationships over distributor networks.
For Investors and Strategic Acquirers: Private equity firms with healthcare device portfolios are the most active acquirer in this space, seeking platforms capable of amortizing fixed regulatory costs across multiple expander geometries. Acquisition target archetype: mid-tier manufacturers with captive silicone supply and EU MDR technical documentation already filed. Signal to watch: reimbursement threshold shifts for post-oncologic reconstruction across national health systems.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Streamlined premarket notification accelerates novel expander geometry commercialization in United States reconstructive surgery. |
| EU MDR Technical Documentation | Comprehensive ISO 10993 biocompatibility dossiers enable faster notified body conformity assessment for surface-textured devices. |
| Hospital System Partnership | Dual-source contracting with academic medical centers secures volume commitment for complex craniofacial expansion protocols. |
| Software Companion Development | Wireless pressure-sensing telemetry integration enables subscription-based remote monitoring service models. |
| Reimbursement Strategy | Statutory coverage alignment with post-mastectomy mandates in Germany and United States stabilizes procedural pipeline predictability. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plastic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Comparable historical periods through the base year established trajectory reference points for projection modeling across the analysis window. Segmentation dimensions included product invasiveness profile, end-user facility reimbursement structure, clinical indication, and pressure generation mechanism. CAGRs derived from regression analysis against procedural volume drivers and input cost indices, with specific incorporation of silicone raw material price volatility and regulatory approval timeline distributions.
Revisions become necessary when reimbursement policy divergence, raw material supply disruption, or regulatory standard harmonization efforts materialize outside modeled parameters. Forecasts reflect documented assumptions regarding procedural migration rates and biocompatibility testing burden evolution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
Biological Derived Devices Market
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Bioartificial Renal Assist Devices Market
Biomedical Engineering
Global Bionic Ear Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Global Single Use Bioprocessing Probes and Sensors Market
Biomedical Engineering
Bioabsorbable Implant Market
Biomedical Engineering
Biocompatible 3D Printing Market
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
Global Continuous Bioprocessing Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
3D Bioprinted Organ Transplants Market
Biomedical Engineering
Bioink Market
Biomedical Engineering
Tissue Engineering Market