
 Genetic Engineering Market | 2026-2036
Genetic Engineering Market Size, Share, and Industry Trends Forecast 2026-2036
Genetic Engineering Market Analysis
The FDA's updated guidance on intentional genomic alterations in animals is realigning the cost-of-entry calculus for developers seeking commercial approval. Thermo Fisher Scientific leverages its end-to-end reagent and instrument portfolio to sustain dominance across research and clinical workflows. Lonza anchors its position through specialized contract development and manufacturing services for cell and gene therapies. CRISPR Therapeutics differentiates by concentrating therapeutic programs on ex vivo edited cell therapies.
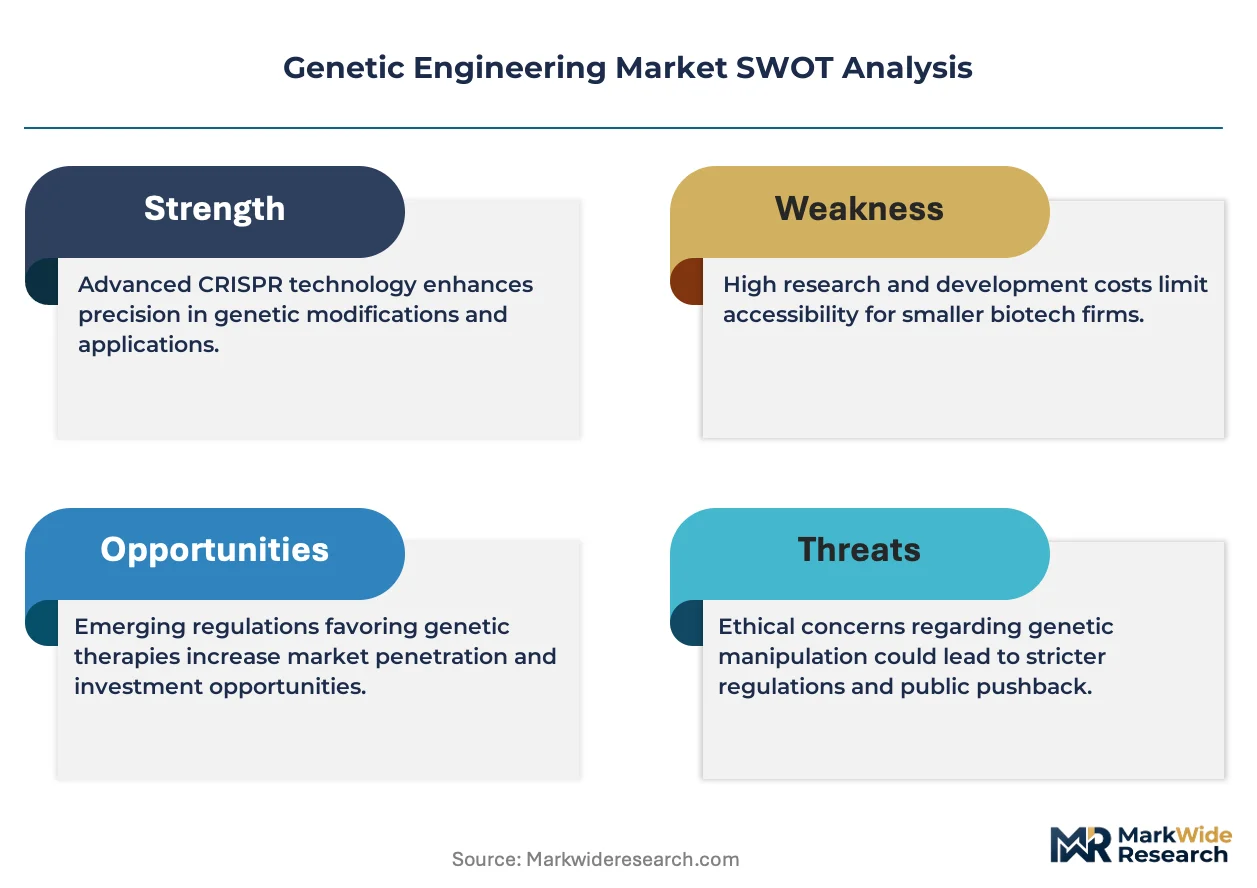
Genetic engineering encompasses the directed modification of DNA sequences using molecular tools such as restriction enzymes, viral vectors, and programmable nucleases to alter organismal traits. CRISPR systems operate at temperatures between 37°C and 42°C with guide RNA specificity exceeding 20 base pairs, enabling precise insertions, deletions, or base substitutions for therapeutic protein production, trait enhancement, or metabolic pathway optimization. Gene therapy products command premium valuation due to manufacturing complexity and orphan-disease targeting, while synthetic genes experience accelerating demand from industrial biotechnology applications seeking optimized microbial chassis. Agricultural biotechnology applications face margin compression from regulatory burden despite expanding acreage approvals, whereas diagnostics applications benefit from recurring consumable pull-through.
The FDA, USDA, and EPA maintain overlapping jurisdiction over genetically engineered products in the United States, with the FDA asserting authority over gene-edited animals as new animal drugs under the FD&C Act. The USDA's SECURE rule streamlines oversight of certain plant-trait modifications, reducing regulatory friction for developers of gene-edited crops without foreign DNA. The EMA's evolving advanced therapy medicinal products framework and China's NMPA gene-editing guidelines add compliance layers for multinational developers. Stakeholders must monitor how divergent national classifications of gene-edited organisms reshape market access strategies and intellectual property filing priorities.
Market Dynamics
CRISPR-Cas9 protocol maturation is compressing R&D timelines and redistributing value capture from large pharmaceutical incumbents toward agile biotechnology developers with specialized editing platforms.
Growth Catalysts
- USDA SECURE Rule:Streamlined oversight of gene-edited crops without foreign DNA reduces pre-market regulatory burden for agricultural biotechnology developers.
- Ex vivo cell therapy protocols:Autologous and allogeneic CAR-T manufacturing pipelines are expanding demand for precision genome editing services.
- Boston-San Francisco corridor:Dense clustering of venture capital networks and research institutions accelerates commercial translation of academic discoveries.
Market Restraints
- Guide RNA synthesis costs:Chemically modified synthetic guides remain the dominant cost driver in CRISPR workflows, compressing margins for high-throughput screening applications.
- FDA animal drug classification:Intentional genomic alterations in animals face multi-year approval timelines under the FD&C Act, deterring investment in livestock editing programs.
- Proprietary delivery vector concentration:Licensing dependence on limited lipid nanoparticle and viral vector suppliers creates supply vulnerability for gene therapy developers.
Strategic Opportunities
- China NMPA gene-editing guidelines:Evolving domestic regulatory clarity opens pathway for multinational developers to establish localized manufacturing and clinical trial infrastructure.
- Microbial chassis optimization:Synthetic biology applications in industrial biotechnology are creating demand for multi-gene pathway engineering beyond therapeutic contexts.
- AI-guided guide RNA design:Machine learning convergence with CRISPR screening data is reducing off-target rates and accelerating target identification workflows.
Industry Challenges
- GMP-grade plasmid manufacturing capacity:Viral vector and cell therapy production bottlenecks are extending contract development timelines for early-stage developers.
- Cross-border IP fragmentation:Divergent national classifications of gene-edited organisms complicate freedom-to-operate analyses and patent filing strategies.
- Skilled cell therapy manufacturing workforce:Shortages of aseptic processing specialists and quality control personnel constrain facility expansion plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetic Engineering Market |
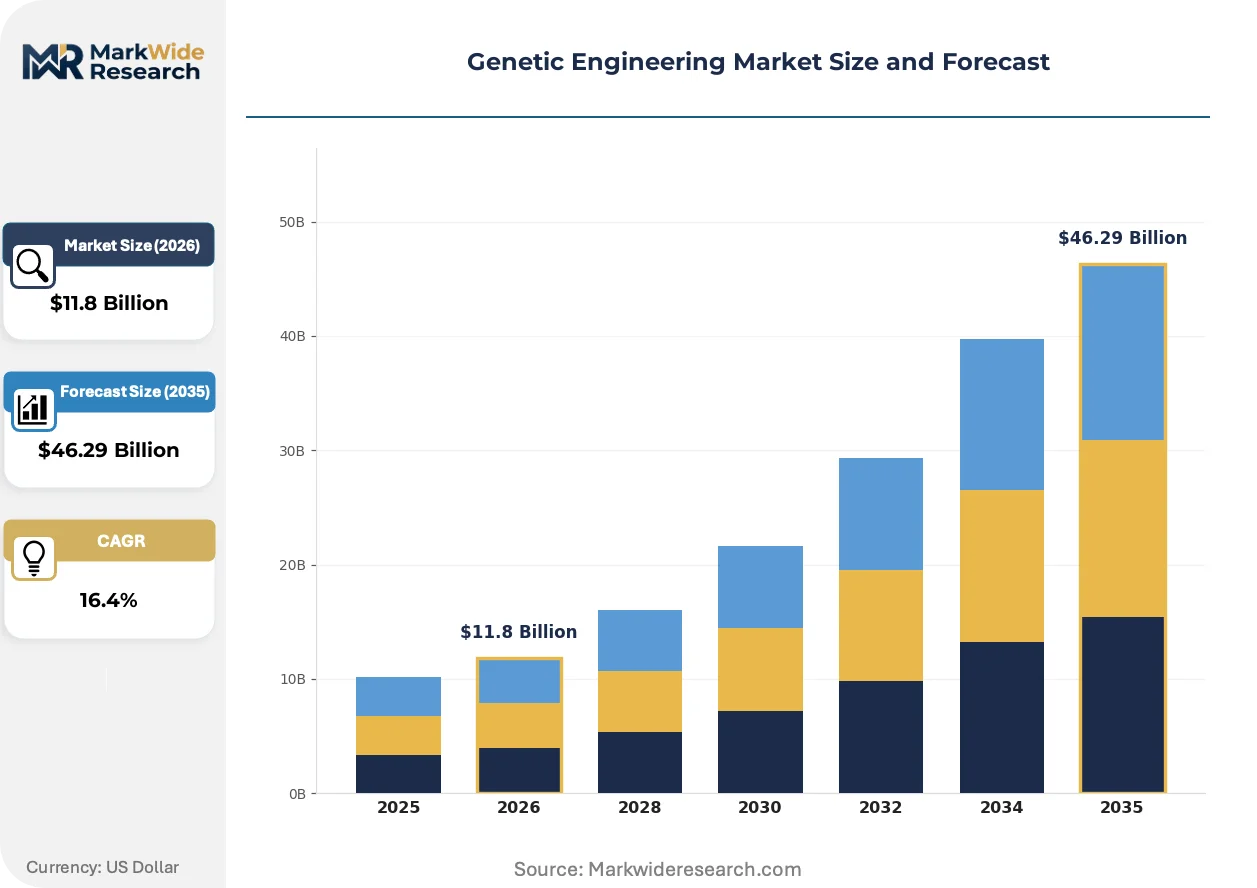
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $46.29 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRISPR, Recombinant Proteins, Gene Therapy Products, Synthetic Genes Application: Agricultural Biotechnology, Diagnostics, Therapeutics, Industrial Biotechnology End User: Pharmaceutical Companies, Academic Research Institutions, Agricultural Firms, Biotech Companies Technology: Gene Editing, Gene Silencing, Synthetic Biology, Genetic Mapping |
| Companies Covered | Thermo Fisher Scientific Inc., Lonza, Merck KGaA, CRISPR Therapeutics AG, Intellia Therapeutics Inc., Cibus, Sangamo, GenScript Biotech Corporation, Recombinetics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetic Engineering Market Emerging Trajectories
Base editing and prime editing platforms are displacing conventional CRISPR-Cas9 in precision medicine applications, while regulatory sandboxes in select jurisdictions are compressing the gap between proof-of-concept and commercial authorization.
Prime editing technology enables precise base substitutions without double-strand breaks or donor DNA templates. Academic medical centers and contract research organizations are adopting these systems for disease-model generation and therapeutic candidate validation. This capability is decentralizing gene correction workflows from centralized core facilities toward distributed laboratory networks.
The EMA's advanced therapy medicinal products framework is harmonizing manufacturing and clinical evidence standards across EU member states. Developers gain predictable approval pathways for somatic cell therapies and tissue-engineered products. Germany and France are capturing disproportionate clinical trial volume as sponsors consolidate European regulatory submissions.
Biopharmaceutical procurement departments are consolidating reagent purchasing through enterprise agreements with end-to-end platform providers. Smaller biotechnology firms lose negotiating leverage as volume discounts concentrate spend with integrated instrument and consumable suppliers. This pattern is most pronounced in the United States, where procurement centralization accompanies laboratory consolidation among contract development organizations.
Genetic Engineering Market Segmentation
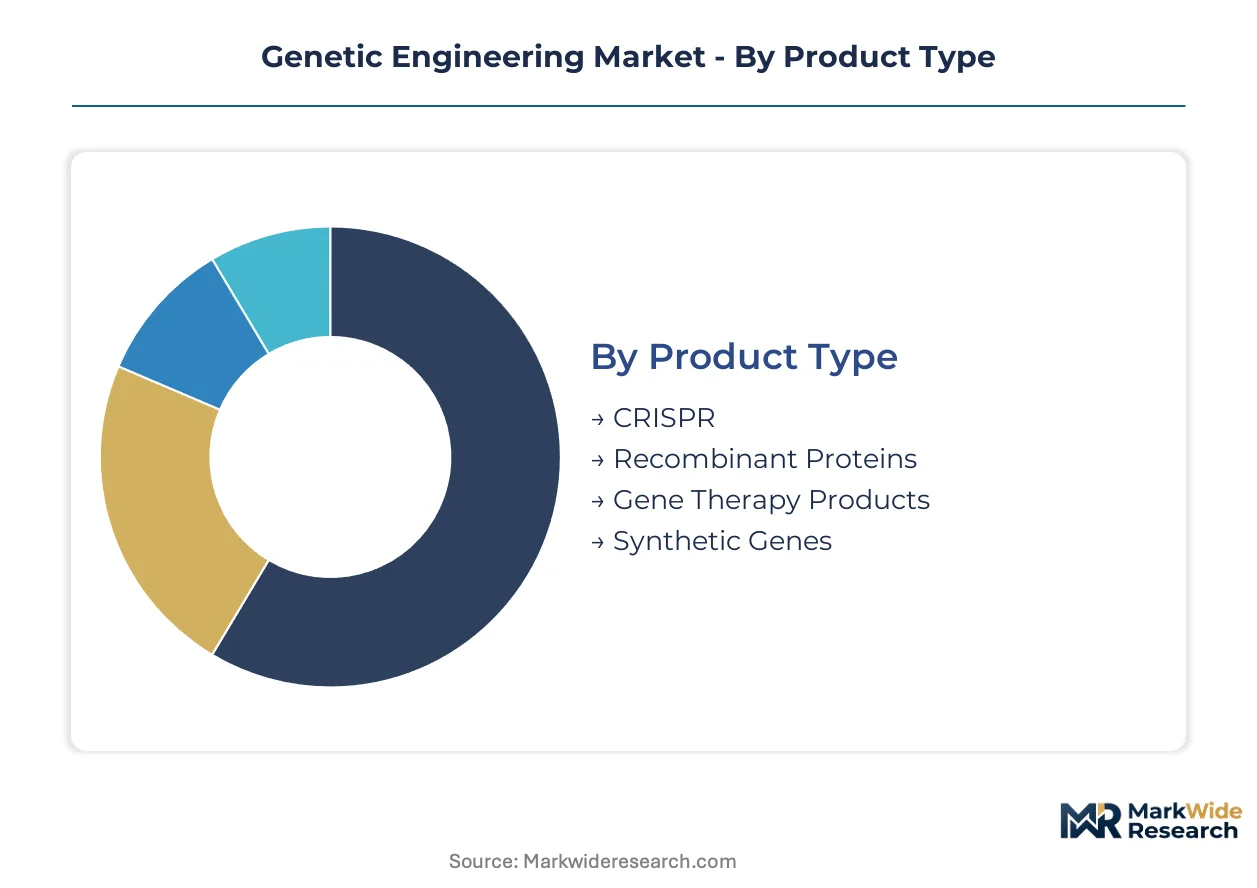
Segmentation in genetic engineering reveals distinct procurement patterns across therapeutic and non-therapeutic applications. Product specifications, regulatory pathways, and end-user sophistication create tiered demand profiles that reshape vendor strategies.
Product Type:
Buyers differentiate by workflow integration needs—clinical-grade products command premium validation while research-grade tools compete on customization speed.
- CRISPR:Programmable nuclease systems with guide RNA-directed specificity enable precise genomic modifications. Demand concentrates in academic core facilities and CDMOs serving CAR-T developers, driven by protocol maturation compressing R&D timelines. CRISPR leads volumes today; synthetic genes are gaining share fastest.
- Recombinant Proteins:Heterologously expressed therapeutic proteins and industrial enzymes manufactured through microbial or mammalian cell culture. Biopharmaceutical manufacturers in the United States and Germany anchor procurement, constrained by glycosylation consistency requirements for biosimilar equivalence.
- Gene Therapy Products:Viral vector-delivered genetic payloads for in vivo and ex vivo therapeutic interventions.
- Synthetic Genes:Custom-designed DNA sequences optimized for codon usage and regulatory elements in chassis organisms.
CRISPR workflows dominate current purchasing volumes; synthetic gene demand expands most quickly in industrial biotechnology applications.
Application:
Application selection correlates with margin structure—therapeutic segments absorb manufacturing complexity premiums while agricultural applications face price compression from regulatory overhead.
- Therapeutics:Somatic gene editing and cell therapy products targeting orphan diseases and oncology indications. FDA advanced therapy designations and EMA ATMP framework approvals in Germany and France concentrate clinical-stage demand, though GMP manufacturing bottlenecks extend development timelines.
- Agricultural Biotechnology:Trait-engineered crops and livestock developed through gene editing or transgenic insertion. USDA SECURE rule streamlining in the United States reduces pre-market burden for foreign-DNA-free modifications, while EU regulatory classification uncertainty limits European field trial expansion.
- Diagnostics:CRISPR-based nucleic acid detection and companion diagnostic assays.
- Industrial Biotechnology:Microbial strain engineering for biofuels, specialty chemicals, and enzyme production.
Therapeutics commands premium pricing today; industrial biotechnology shows steepest expansion trajectory as synthetic biology scales.
End User:
End-user sophistication determines service intensity—pharmaceutical procurement centralizes through enterprise agreements while academic buyers prioritize technical support flexibility.
- Pharmaceutical Companies:Integrated biopharmaceutical manufacturers with captive gene therapy development capabilities. Internal manufacturing investments by firms in the Boston-San Francisco corridor reduce external dependency, though plasmid and viral vector supply gaps force selective outsourcing.
- Biotech Companies:Venture-backed developers lacking integrated manufacturing infrastructure. CDMO partnerships with Lonza and specialized cell therapy manufacturers in Switzerland and Singapore dominate procurement strategy, constrained by facility capacity waitlists.
- Academic Research Institutions:University core facilities and principal investigator laboratories.
- Agricultural Firms:Seed developers and livestock genetics companies pursuing trait commercialization.
Pharmaceutical companies lead absolute spend; biotech companies are expanding procurement fastest as clinical pipelines mature.
Technology:
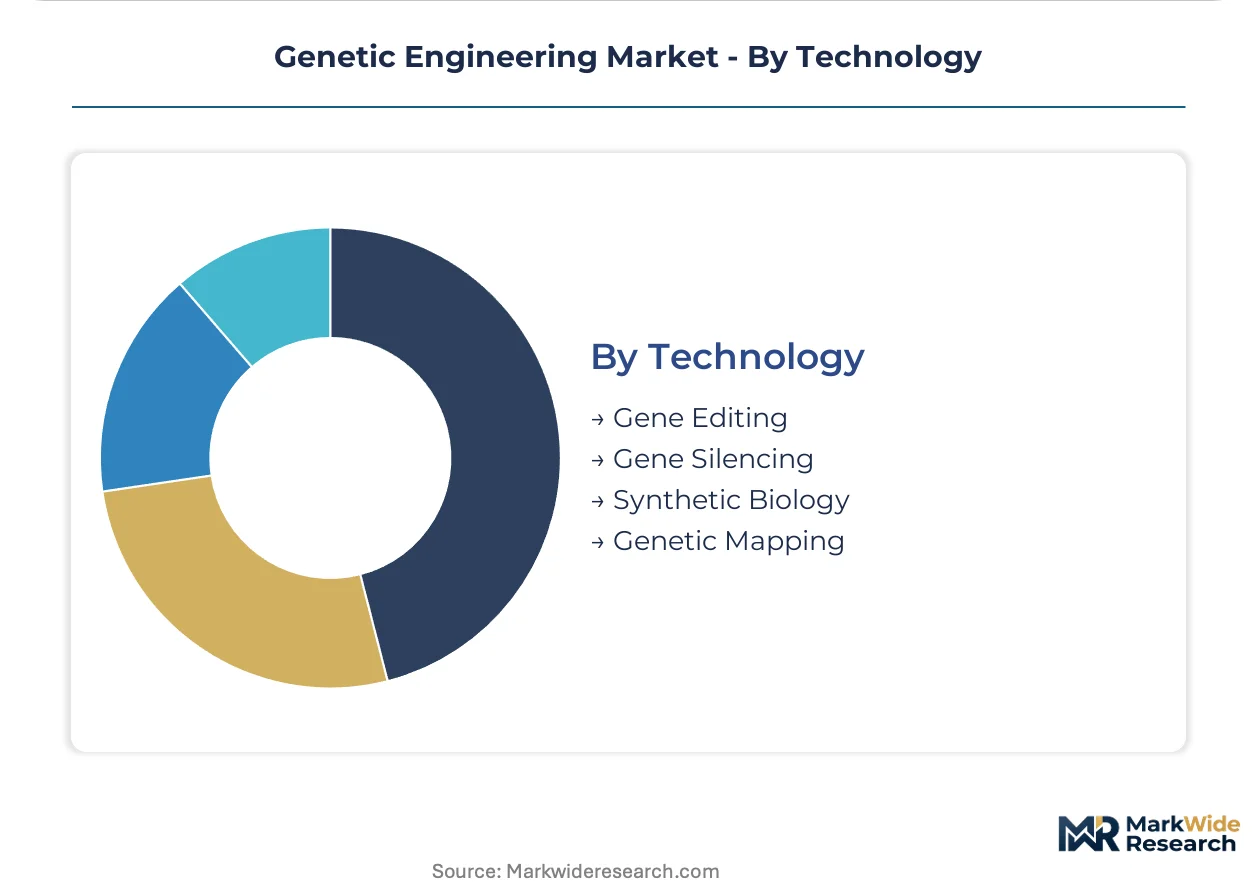
Technology adoption tracks precision requirements—clinical applications migrate toward break-free editing platforms while research workflows tolerate conventional nuclease systems.
- Gene Editing:CRISPR-Cas9, base editing, and prime editing platforms for directed genomic modification. Clinical translation in the United States and China accelerates as FDA and NMPA guidance clarifies regulatory expectations for intentional genomic alterations.
- Synthetic Biology:Design-build-test cycles for multi-gene pathway engineering and chassis optimization. Industrial biotechnology applications in biofuels and specialty chemicals drive demand, particularly among contract manufacturers serving European chemical conglomerates.
- Gene Silencing:RNA interference and antisense oligonucleotide technologies for transcript knockdown.
- Genetic Mapping:High-throughput sequencing and linkage analysis for trait association.
Gene editing dominates current technology spend; synthetic biology climbs fastest as microbial engineering scales beyond pharmaceutical contexts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cell therapy manufacturing technicians concentrate in the Boston-San Francisco corridor, anchoring North American capacity expansion. German precision fermentation engineers and Swiss bioprocess specialists supply adjacent European demand. Chinese molecular biologists and Singaporean CDMO operators are scaling Asia-Pacific infrastructure.
United States
FDA advanced therapy designations and venture capital deployment in Cambridge and South San Francisco drive clinical pipeline maturation. The USDA's SECURE rule reduces pre-market burden for gene-edited crops without foreign DNA. Lonza's Portsmouth, New Hampshire facility expands viral vector manufacturing capacity to serve CAR-T developers.
Germany
EMA advanced therapy medicinal products framework harmonization attracts centralized European clinical trial submissions. Germany's national pharmaceutical regulator enforces GMP standards for plasmid and viral vector production. The Rhine-Main biotech cluster around Frankfurt anchors contract development operations for industrial biotechnology applications.
China
NMPA gene-editing guidelines clarify regulatory expectations for intentional genomic alterations in animals and cell therapies. The Yangtze River Delta biopharmaceutical manufacturing base scales CRISPR reagent production. Shanghai and Suzhou host expanding CDMO infrastructure serving domestic and multinational developers.
Switzerland
Specialized bioprocess engineering talent concentrates around Basel and Zurich, supporting precision fermentation and cell therapy manufacturing. Swissmedic maintains stringent quality standards for advanced therapy medicinal products. The Basel biotech corridor anchors Lonza's global contract development and manufacturing services headquarters.
United Kingdom
Research-intensive universities in Cambridge and Oxford generate gene-editing intellectual property and spin-out companies. The Medicines and Healthcare products Regulatory Agency aligns with EMA standards post-Brexit while maintaining distinct approval pathways. The Golden Triangle research cluster sustains academic-commercial translation pipelines.
Genetic Engineering Market Vendor Landscape
The competitive structure tilts toward integrated platform providers with captive reagent-instrument workflows. Consolidation concentrates purchasing power among end-to-end suppliers while fragmenting specialized service niches. Three archetypes dominate: diversified life science conglomerates with workflow integration, pure-play gene editing technology developers, and contract manufacturing specialists with GMP infrastructure. Capacity expansion and strategic technology licensing represent the dominant competitive moves as developers secure viral vector and cell therapy manufacturing access.
Among diversified platform providers, Thermo Fisher Scientific Inc. and Merck KGaA exemplify the integrated reagent-instrument archetype with broad workflow coverage. Lonza occupies a position as the contract manufacturing specialist archetype, anchoring cell and gene therapy CDMO services. CRISPR Therapeutics AG represents the pure-play gene editing developer archetype, concentrating therapeutic programs on ex vivo edited cell therapies.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Lonza |
| Merck KGaA |
| CRISPR Therapeutics AG |
| Intellia Therapeutics Inc. |
| Cibus |
| Sangamo |
| GenScript Biotech Corporation |
| Recombinetics Inc. |
| Others |
Supply Flow & Price Mechanics
Venture-backed CDMO specialists concentrated in Switzerland and Singapore anchor supply-side discipline through captive GMP infrastructure investments, translating manufacturing scarcity into sustained pricing power for clinical-grade gene editing services while research-grade reagent markets fragment under volume consolidation pressure.
Pricing Analysis
Bundled end-to-end platform contracts dominate pharmaceutical procurement, while unbundled research-grade reagent sales compete on customization speed. Three-tier pricing structure across GMP-certified, ISO-validated, and research-grade levels separates clinical cell therapy developers from academic core facilities. Pricing pressure stems from guide RNA synthesis cost compression in high-throughput screening workflows. Academic buyers exhibit highest price sensitivity, whereas CAR-T developers absorb premiums for validated supply security.
Supply Chain Analysis
ISO 13485 and FDA quality system certifications gate supplier eligibility for clinical-grade plasmid and viral vector manufacturing. Supply concentrates in the United States, Switzerland, and China, with German precision fermentation engineers anchoring European capacity. The chain draws from synthetic oligonucleotide precursors, lipid nanoparticle formulations, and cell culture media. Single-source vulnerability in proprietary delivery vector licensing creates supply risk. Distribution runs through direct enterprise agreements with integrated platform providers and specialized CDMO partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in genetic engineering rests on AI-guided guide RNA design cost compression and the premium-tier shift toward break-free editing platforms displacing conventional CRISPR-Cas9 in clinical applications.
For Market Incumbents: Anchor manufacturing capacity in the Boston-San Francisco corridor and the Yangtze River Delta to defend against emerging CDMO competition from Singaporean operators. Deepen backward integration into GMP-grade plasmid production to reduce dependency on limited viral vector suppliers. Invest in base editing and prime editing certification pipelines ahead of FDA advanced therapy designation shifts. For New Entrants and Emerging Players: Direct-to-academic-core-facility digital channels offer lowest-friction entry for research-grade CRISPR reagent sales. Target industrial biotechnology applications in microbial chassis optimization, where synthetic gene demand expands fastest and regulatory burden remains lowest. Pursue white-label CDMO partnerships with established Swiss or German GMP facilities rather than greenfield capacity investment. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play agricultural biotechnology developers facing EU regulatory classification uncertainty and margin compression from SECURE rule streamlining in the United States. Long-term viability favors contract manufacturing specialists with validated cell therapy infrastructure over reagent-only platform providers. Watch NMPA gene-editing guideline implementation velocity in China as inflection indicator for multinational manufacturing relocation decisions.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Lonza's Portsmouth expansion validates CDMO capacity scarcity thesis for CAR-T developers. |
| Regulatory Approval Pathway | FDA advanced therapy designations compress development timelines for ex vivo edited cell therapies. |
| Technology Licensing Agreement | Prime editing platform access differentiates precision medicine portfolios from conventional CRISPR-Cas9 competitors. |
| Backward Integration | In-house guide RNA synthesis capabilities reduce margin compression from chemically modified synthetic guide costs. |
| Geographic Expansion | Shanghai and Suzhou CDMO infrastructure captures NMPA regulatory clarity for multinational clinical trial sponsors. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with gene therapy development executives, regulatory affairs leads at FDA and EMA, CDMO procurement managers, and academic core facility directors. Secondary validation draws from FDA filings, EMA advanced therapy medicinal products submissions, ClinicalTrials.gov records, and USDA SECURE rule documentation. Bottom-up segment sizing triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models segmentation by product type, application, end user, and technology platform, with additional dimensioning by regulatory approval pathway cluster. CAGRs derive from fitted growth curves incorporating CRISPR protocol maturation rates, GMP manufacturing capacity expansion schedules, and national gene-editing guideline implementation trajectories.
The model assumes a particular technology adoption path; alternative pathways for base editing and prime editing platform displacement would alter the outlook. Forecasts reflect assumptions regarding FDA animal drug classification stability, USDA SECURE rule durability, and NMPA guideline enforcement consistency. A model refresh is warranted upon material change in GMP-grade plasmid manufacturing capacity utilization or EMA advanced therapy medicinal products framework harmonization velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Genetically Modified Animal Model Market
Gene Editing & CRISPR
Gene Editing Tools Market
Gene Editing & CRISPR
France Gene Editing Market
Gene Editing & CRISPR
India Gene Editing Market
Gene Editing & CRISPR
CRISPR Technology Market
Gene Editing & CRISPR
Italy Gene Editing Market
Gene Editing & CRISPR
Genome Editing Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
UK Gene Editing Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
Gene Editing Off-Target Effect Detection Test Systems Market
Gene Editing & CRISPR
Immunodeficient Mouse Models Market
Gene Editing & CRISPR
CRISPR Gene Detection and Diagnostic Market
Gene Editing & CRISPR
Germany Gene Editing Market
Gene Editing & CRISPR
Knock Out Mouse Model Market
Gene Editing & CRISPR
CRISPR Gene Editing Market