
 In Situ Gel Drug Delivery Market | 2026-2036
In Situ Gel Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
In Situ Gel Drug Delivery Market Intelligence
Ophthalmology is consolidating as the dominant end-use vertical for in situ gel systems, displacing earlier orthopedic-centric deployment patterns. Merck KGaA leverages its polymer science heritage to anchor European supply relationships for biodegradable gel platforms. Johnson & Johnson Services, Inc. sustains manufacturing scale across thermoresponsive formulations for hospital networks. Pfizer Inc. competes through R&D intensity in nanoparticle-integrated gel architectures.
In situ gel drug delivery comprises liquid formulations that undergo phase transition upon administration to form semisolid depots, typically employing poloxamer or chitosan matrices with gelation temperatures between 25°C and 37°C, enabling controlled release of active pharmaceutical ingredients over days to weeks. Thermoresponsive gels lead product type demand due to their syringeable simplicity and reproducible sol-gel kinetics, while hydrogel technology dominates R&D pipelines for ophthalmic applications where corneal residence time determines therapeutic efficacy. Polymeric technology occupies the mature margin pool, though nanoparticle integration is displacing conventional approaches in oncology depots.
The FDA shapes formulation standards through bioequivalence requirements for modified-release parenterals, while the EMA's MDR framework governs CE marking for class III implantable gel devices in Europe. Health Canada and Japan's PMDA enforce comparable stability and sterility protocols that determine market access timelines for multinational filings. Stakeholders must monitor evolving pharmacopeial monographs for gel characterization methods as regulators tighten in vitro release testing standards.
Market Dynamics
The transition from hospital-administered parenterals to outpatient-compatible depot systems is compressing formulation development cycles and redistributing value capture toward polymer engineering capabilities.
Growth Catalysts
- Thermoresponsive gel platforms:Poloxamer-based systems enable syringeable administration at room temperature with reliable gelation at body temperature, accelerating adoption in ophthalmology clinics seeking reduced dosing frequency.
- FDA bioequivalence pathways:Streamlined guidance for modified-release parenterals reduces clinical trial burden for gel depot formulations compared to novel molecular entities.
- Biodegradable polymer maturation:Chitosan and PLGA supply chains have achieved pharmaceutical-grade consistency, enabling scalable manufacturing for sustained-release oncology applications.
Market Restraints
- High-purity chitosan supply concentration:Pharmaceutical-grade chitosan production concentrates among Asian suppliers, exposing formulation houses to raw material qualification delays and price volatility.
- Sterility assurance complexity:Terminal sterilization of heat-sensitive gel matrices requires aseptic processing with validated filtration, elevating capital intensity for manufacturing facilities.
- Injectable suspension alternatives:Lipid-based and microparticle depot formulations compete directly for the same sustained-release indications, fragmenting R&D investment.
Strategic Opportunities
- Pediatric oncology applications:Underpenetrated demand exists for implantable gel depots eliminating repeated venous access in pediatric leukemia protocols, with Health Canada and FDA orphan drug incentives accelerating development.
- Home administration channels:Pre-filled syringe formats for thermorespective gels enable subcutaneous self-injection, opening outpatient and home health segments previously restricted to clinical settings.
- Nanoparticle-gel hybrid architectures:Convergence of lipid nanoparticle encapsulation with in situ gel matrices enables dual-release kinetics for combination therapies in immuno-oncology.
Industry Challenges
- Formulation scientist scarcity:Specialized expertise in sol-gel transition rheology and in vitro release method development remains concentrated among a limited pool of industrial pharmacists, constraining pipeline expansion.
- Pharmacopeial standardization gaps:USP and EP monographs for gel characterization lag behind formulation innovation, forcing sponsors to negotiate case-by-case validation protocols with regulators.
- Scale-up reproducibility:Batch-to-batch consistency in gelation temperature and mechanical strength requires tight control of polymer polydispersity, complicating technology transfer from development to commercial manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Situ Gel Drug Delivery Market |
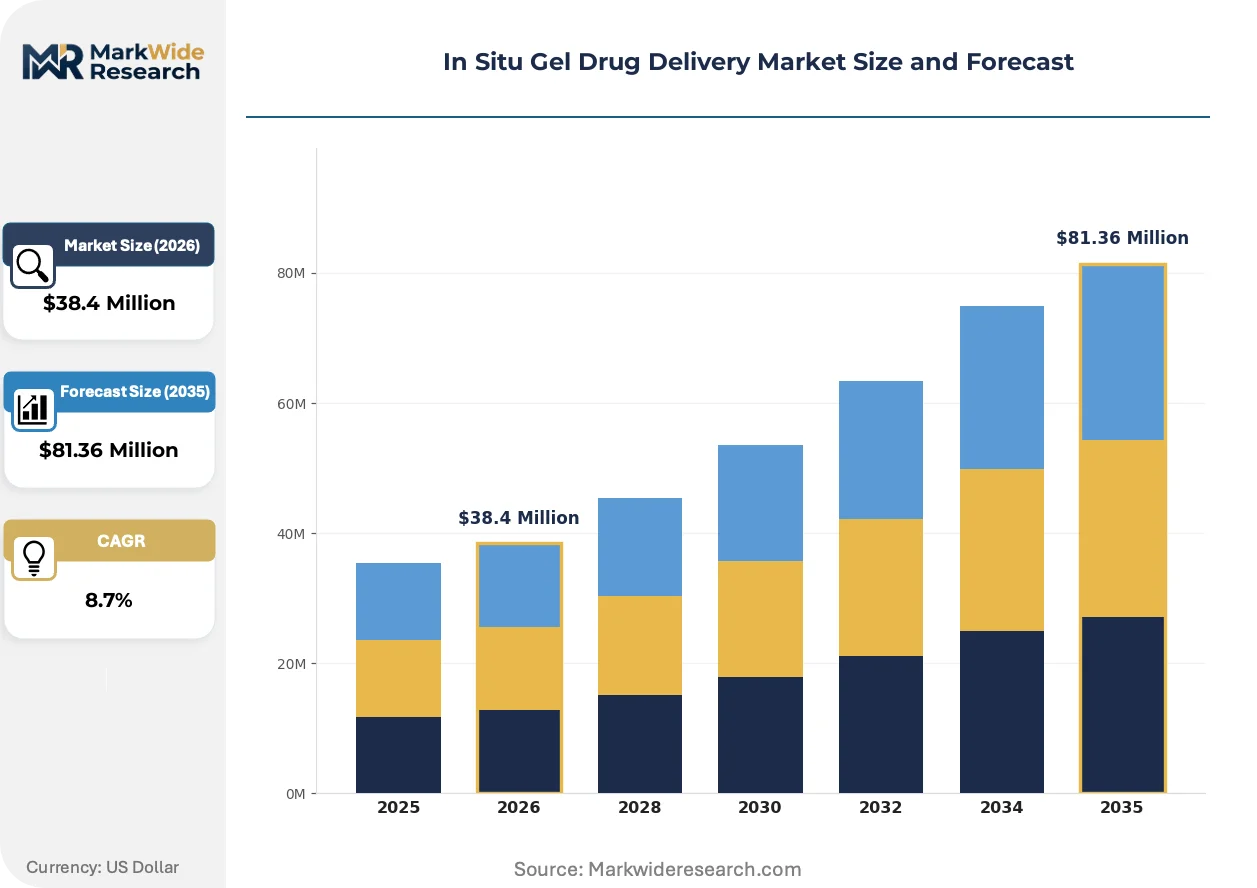
| Market Size in 2026 | $38.4 Million |
| Market Size in 2035 | $81.36 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Gels, Thermoresponsive Gels, Biodegradable Gels, Hydrogels Application: Ophthalmology, Oncology, Orthopedics, Cardiovascular Technology: Hydrogel Technology, Nanoparticle Technology, Polymeric Technology, Micelle Technology End User: Hospitals, Clinics, Home Care, Research Laboratories |
| Companies Covered | Merck KGaA, AstraZeneca PLC, Johnson & Johnson Services, Inc., Sanofi S.A., Baxter International Inc., Allergan plc, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Situ Gel Drug Delivery Market Strategic Shifts & Innovations
Formulation science is converging with precision medicine requirements, driving modular platform approaches that separate active pharmaceutical ingredient selection from depot engineering. This decoupling accelerates candidate progression across therapeutic areas.
Stimuli-responsive polymer chemistry is modularizing drug delivery architecture. pH-sensitive and ion-activated gel systems complement thermoresponsive platforms, enabling targeted deployment in specific tissue microenvironments. Oncology departments are piloting these systems for intratumoral injection, where local acidity triggers gelation. The technology is compressing development timelines by allowing platform reuse across multiple APIs.
EMA's MDR framework for class III implantable devices is tightening clinical evidence requirements for gel depots intended for extended residence. Manufacturers must now demonstrate biocompatibility and degradation kinetics through longitudinal studies. European sponsors are responding by front-loading characterization data in pre-submission meetings, extending development timelines but reducing regulatory risk.
Hospital procurement committees are consolidating supplier relationships around integrated formulation-manufacturing partners capable of end-to-end depot development. This concentration disadvantages pure-play polymer suppliers without clinical manufacturing capabilities. The shift is most pronounced in United States academic medical centers, where value analysis committees prioritize supply security and regulatory track record over unit cost.
In Situ Gel Drug Delivery Market Segmentation
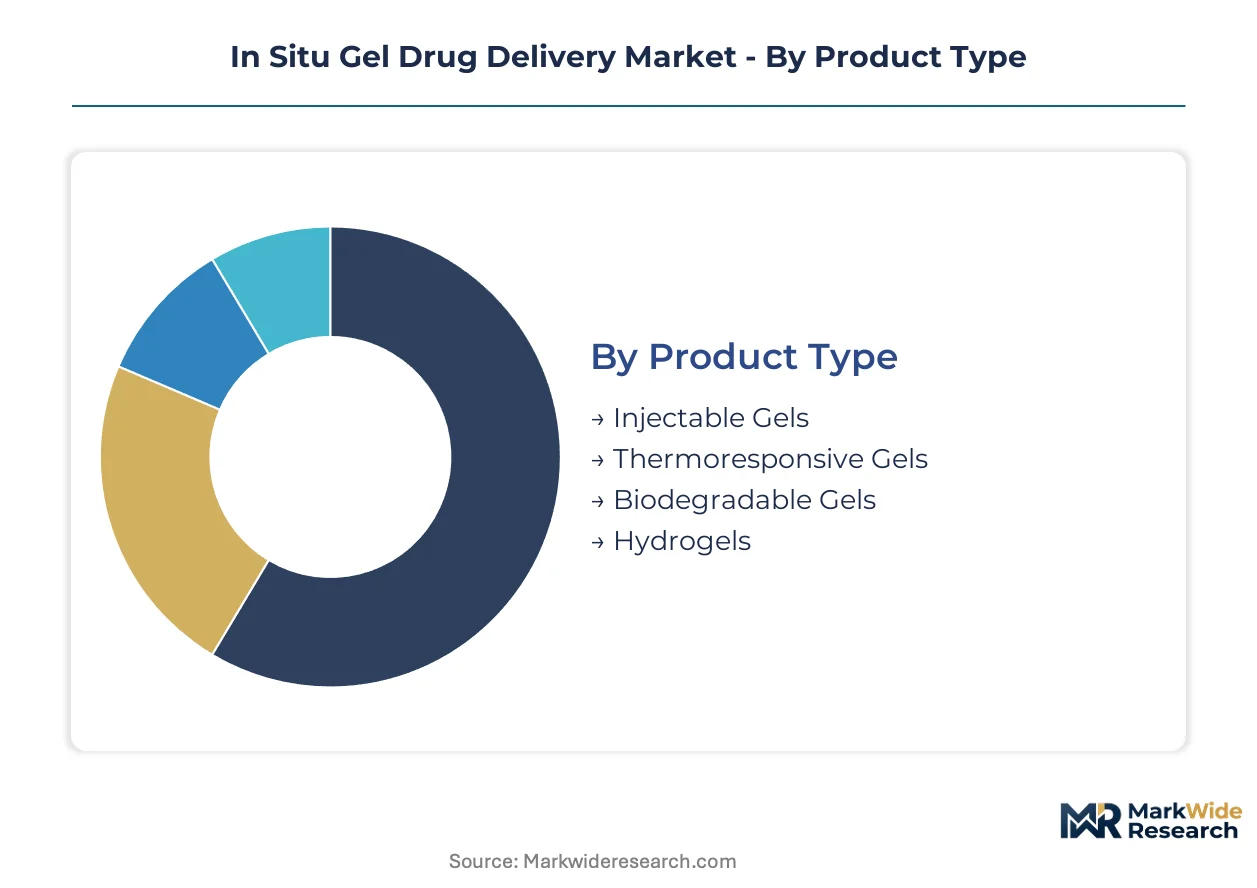
Segmentation in the in situ gel drug delivery market reflects divergent technical requirements across therapeutic areas. Formulation choices hinge on gelation kinetics, degradation profiles, and administration setting constraints rather than cost alone.
Product Type:
Clinicians prioritize syringeability and gelation reliability when selecting depot formulations for specific anatomical sites.
- Thermoresponsive Gels:Poloxamer-based matrices transition from liquid to semisolid between 25°C and 37°C, enabling room-temperature storage and body-temperature gelation. Hospital outpatient departments in the United States favor these systems for reduced nursing time and reproducible dosing intervals.
- Injectable Gels:Pre-formed viscous solutions require no phase transition, offering immediate mechanical stability upon deposition. Orthopedic surgeons deploy these for intra-articular applications where load-bearing capacity matters more than syringeability.
- Biodegradable Gels:Chitosan and PLGA platforms degrade through hydrolysis or enzymatic action, eliminating surgical retrieval.
- Hydrogels:Cross-linked hydrophilic polymer networks absorb physiological fluids to maintain depot integrity.
Thermoresponsive gels lead on scale; biodegradable gels lead on momentum.
Application:
Tissue-specific physiological conditions dictate gel architecture selection, with residence time requirements varying dramatically across anatomical compartments.
- Ophthalmology:Corneal and intravitreal applications demand precise gelation to avoid vision obstruction. Precorneal residence time extension drives thermoresponsive platform adoption in United States ophthalmology clinics seeking reduced dosing frequency for glaucoma and macular degeneration protocols.
- Oncology:Intratumoral and postsurgical cavity depots require sustained chemotherapy release over weeks. The FDA's streamlined bioequivalence pathways for modified-release parenterals accelerate development timelines for PLGA-based oncology depots.
- Orthopedics:Load-bearing joints necessitate mechanically robust gel matrices resistant to shear forces.
- Cardiovascular:Myocardial and perivascular applications require biocompatible degradation products.
Ophthalmology leads on scale; oncology leads on momentum.
Technology:
Platform maturity determines manufacturing scalability and regulatory pathway predictability for formulation sponsors.
- Hydrogel Technology:Cross-linked polymer networks dominate ophthalmic pipelines due to established safety profiles and tunable swelling kinetics.
- Polymeric Technology:Conventional synthetic polymer depots occupy the mature commercial margin pool with proven scale-up protocols.
- Nanoparticle Technology:Lipid and polymeric nanoparticles integrated within gel matrices enable dual-release kinetics for combination immuno-oncology therapies.
- Micelle Technology:Amphiphilic block copolymer assemblies enhance hydrophobic drug loading within aqueous gel vehicles.
Polymeric technology leads on scale; nanoparticle technology leads on momentum.
End User:
Administration setting determines sterility requirements, device format, and patient training needs for gel depot deployment.
- Hospitals:Inpatient and surgical settings handle complex aseptic processing for implantable gel depots with extended residence requirements.
- Clinics:Outpatient ophthalmology and oncology clinics drive thermoresponsive gel uptake through pre-filled syringe formats enabling rapid chairside administration.
- Home Care:Subcutaneous self-injection of thermoresponsive gels opens patient-administered depot therapy for chronic conditions.
- Research Laboratories:Academic and contract research organizations prototype next-generation stimuli-responsive gel architectures.
Hospitals lead on scale; home care leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation sponsors migrate manufacturing toward jurisdictions with predictable regulatory pathways and established polymer supply chains, exploiting cost-of-compliance gaps between mature and emerging pharmaceutical markets.
United States
FDA bioequivalence guidance for modified-release parenterals accelerates gel depot approvals, while hospital outpatient settings in the Northeast and California drive thermoresponsive formulation uptake. The 21st Century Cures Act provisions streamline breakthrough therapy designations for sustained-release platforms. Boston's Kendall Square biotech cluster anchors contract manufacturing for ophthalmic gel depots.
Germany
EMA's MDR framework for class III implantable devices tightens clinical evidence requirements, extending development timelines but reducing regulatory risk for compliant sponsors. The country's pharmaceutical-grade polymer heritage supports biodegradable gel platform scale-up. Heidelberg and Munich host formulation development centers serving European hospital networks.
Switzerland
Swissmedic's alignment with EMA standards enables parallel market access strategies across European Economic Area markets. The country's precision manufacturing base supports aseptic processing for heat-sensitive gel matrices. Basel's pharmaceutical corridor concentrates polymer engineering capabilities for oncology depot applications.
Japan
PMDA stability and sterility protocols for sustained-release parenterals determine market access timelines for multinational filings, with local partnership requirements for foreign sponsors. Aging demographics drive demand for reduced-dosing-frequency formulations in ophthalmology. The Kansai region's chemical industry supplies pharmaceutical-grade chitosan derivatives.
India
CDSCO's phased implementation of bioequivalence standards for complex generics creates regulatory arbitrage opportunities for contract research and manufacturing organizations. Pharmaceutical-grade chitosan production concentrates among domestic suppliers, exposing formulation houses to raw material qualification protocols. Hyderabad's bulk drug manufacturing cluster expands into gel depot contract manufacturing.
In Situ Gel Drug Delivery Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with consolidated control over polymer supply chains contrasting fragmented formulation development services. The vendor base organizes around three archetypes: diversified pharmaceutical conglomerates with captive polymer science capabilities, pure-play drug delivery technology licensors, and contract development and manufacturing organizations with aseptic processing expertise. M&A activity concentrates on polymer engineering assets, while capacity expansion focuses on multi-product aseptic filling lines for thermoresponsive gel formats.
Within the diversified pharmaceutical tier, Merck KGaA and Johnson & Johnson Services, Inc. occupy positions anchored by polymer science heritage and hospital network relationships respectively. Pfizer Inc. exemplifies R&D-intensive competition through nanoparticle-integrated gel architectures. These entities represent distinct strategic postures: European supply chain integration, North American manufacturing scale, and platform technology convergence.
| Leading Market Players |
|---|
| Merck KGaA |
| AstraZeneca PLC |
| Johnson & Johnson Services, Inc. |
| Sanofi S.A. |
| Baxter International Inc. |
| Allergan plc |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Others |
Cost & Logistics Intelligence
Formulation scientist concentration in the United States Northeast and Basel corridor compresses labor-cost differentials into premium-mid-economy pricing tiers for gel depot platforms.
Pricing Analysis
Hospital procurement committees extract direct-to-manufacturer discounts that compress distributor margins to single-digit percentages. Pricing stratifies across FDA-validated premium tiers, CE-marked standard tiers, and emerging-economy economy tiers based on bioequivalence documentation depth. Cost compression in the standard tier intensifies because CDSCO-aligned contract manufacturers arbitrage formulation development costs. Academic medical centers exhibit lowest price sensitivity due to bundled value-analysis scoring; outpatient ophthalmology clinics demonstrate highest sensitivity due to per-dose reimbursement constraints.
Supply Chain Analysis
Workforce availability for aseptic processing specialists concentrates in Switzerland, Germany, and the United States Massachusetts corridor. Pharmaceutical-grade chitosan production draws from Indian and Japanese chemical suppliers; poloxamer feedstocks rest on German and Belgian petrochemical complexes. Single-source vulnerability in high-purity chitosan qualification exposes formulation houses to six-month raw material approval delays. Distribution runs through integrated formulation-manufacturing partners capable of end-to-end depot development rather than pure-play polymer suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between FDA-validated United States manufacturing and CDSCO-aligned Indian contract research creates 40-60% development cost spreads for equivalent gel depot platforms.
For Market Incumbents: Deploy polymer engineering talent retention programs to defend against nanoparticle-integrated platform displacement. Consolidate supply security through captive chitosan derivative production or exclusive offtake agreements with qualified Asian suppliers. Capacity addition in Switzerland preserves EMA MDR compliance proximity while capturing precision manufacturing premiums.
For New Entrants and Emerging Players: Launch via pre-filled syringe thermoresponsive formats targeting United States home care channels underserved by hospital-centric incumbents. Pediatric oncology depots represent the most penetrable segment due to orphan drug incentive stacking and formulation scientist scarcity among established players. Pursue Health Canada-parallel FDA submission strategies to compress regulatory capital requirements.
For Investors and Strategic Acquirers: Contract development and manufacturing organizations with aseptic gel processing capabilities are the most active acquirer category in this space, consolidating polymer engineering assets ahead of platform modularization trends. Target acquisition archetypes include mid-scale formulation houses with validated PLGA depot platforms and existing FDA Type II drug master files. Watch for EMA MDR clinical evidence requirement tightening as inflection indicator for regulatory-capital barrier elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Engineering Talent Acquisition | Secures scarce sol-gel transition rheology expertise ahead of competitor pipeline expansion. |
| FDA Bioequivalence Pathway Navigation | Compresses clinical trial burden for modified-release parenteral gel depot approvals. |
| Chitosan Supply Chain Vertical Integration | Eliminates raw material qualification delays from concentrated Asian supplier base. |
| Nanoparticle-Gel Hybrid Platform Development | Enables dual-release kinetics for combination immuno-oncology therapies. |
| Pre-Filled Syringe Format Scale-Up | Opens outpatient and home administration channels previously restricted to clinical settings. |
Research Approach
Coverage spans the United States, Germany, Switzerland, Japan, and India, with primary inputs from each market cluster. The analysis combines structured interviews with formulation development executives, regulatory affairs leads at gel depot sponsors, hospital procurement managers, and polymer supply chain directors with secondary validation against FDA 510(k) filings, EMA MDR submission databases, ClinicalTrials.gov entries, and USP pharmacopeial monograph revisions. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates.
Rate-of-change decomposition separates volume expansion from pricing evolution across the projection horizon. Segmentation dimensions include product type, application, technology platform, and end-user setting, with regional regulatory cluster as an additional modeled variable. CAGRs derive from polynomial trend fitting against historical approval trajectories and polymer supply capacity expansion announcements. Forecast inputs incorporate FDA guidance document issuance patterns and EMA MDR implementation phase transitions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pharmacopeial standardization acceleration or chitosan supply disruption scenarios. Projections reflect documented assumptions regarding bioequivalence pathway stability and aseptic processing capacity expansion timelines. Material deviation in FDA orphan drug incentive continuity or EMA clinical evidence requirement enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
North America HIV Drugs Market
Biopharmaceuticals
Global Argatroban Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
North America and Europe Pegylated Drugs Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Ewing Sarcoma Drugs Market
Biopharmaceuticals
Primary Biliary Cholangitis (PBC) Therapeutics Market
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market
Biopharmaceuticals
Global Anti-Infective Drugs Market
Biopharmaceuticals
Peptide Antibiotics Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Bioequivalence Studies Market
Biopharmaceuticals
Atipamezole Market