
 Bioabsorbable Implant Market | 2026-2036
Bioabsorbable Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Bioabsorbable Implant Market Analytics
The EU Green Deal is realigning polymer sourcing priorities across European medical device supply chains. Medtronic leverages its integrated polymer research capabilities to sustain leadership in orthopedic resorbables. Stryker anchors its competitive position through specialized manufacturing scale in craniofacial screw systems. Johnson & Johnson competes via differentiated suture platforms that navigate diverse international regulatory pathways.
Bioabsorbable implants are medical devices fabricated from synthetic or natural polymers such as polylactic acid, polyglycolic acid, and lactic-glycolic copolymers that degrade through hydrolysis and metabolic absorption without requiring surgical removal. These devices serve primarily to provide temporary mechanical fixation, vascular scaffolding, or wound closure during tissue healing phases before dissolving completely. Screws and plates currently occupy the largest volume share within product categories, reflecting established orthopedic trauma applications. Stents represent the fastest-expanding segment as cardiovascular specialists adopt polymer-based alternatives to reduce long-term complications. Copolymer formulations command premium positioning due to tunable degradation rates that match specific tissue regeneration timelines.
The FDA enforces stringent biocompatibility and degradation profile documentation under its medical device quality system regulations, while the EMA's MDR framework mandates enhanced clinical evidence for resorbable implant longevity claims. ISO 10993 standards govern systematic biological evaluation of these polymer-based devices across both jurisdictions. Stakeholders must monitor evolving reimbursement policies for bioabsorbable alternatives versus permanent metal implants as hospital value analysis committees scrutinize total episode costs.
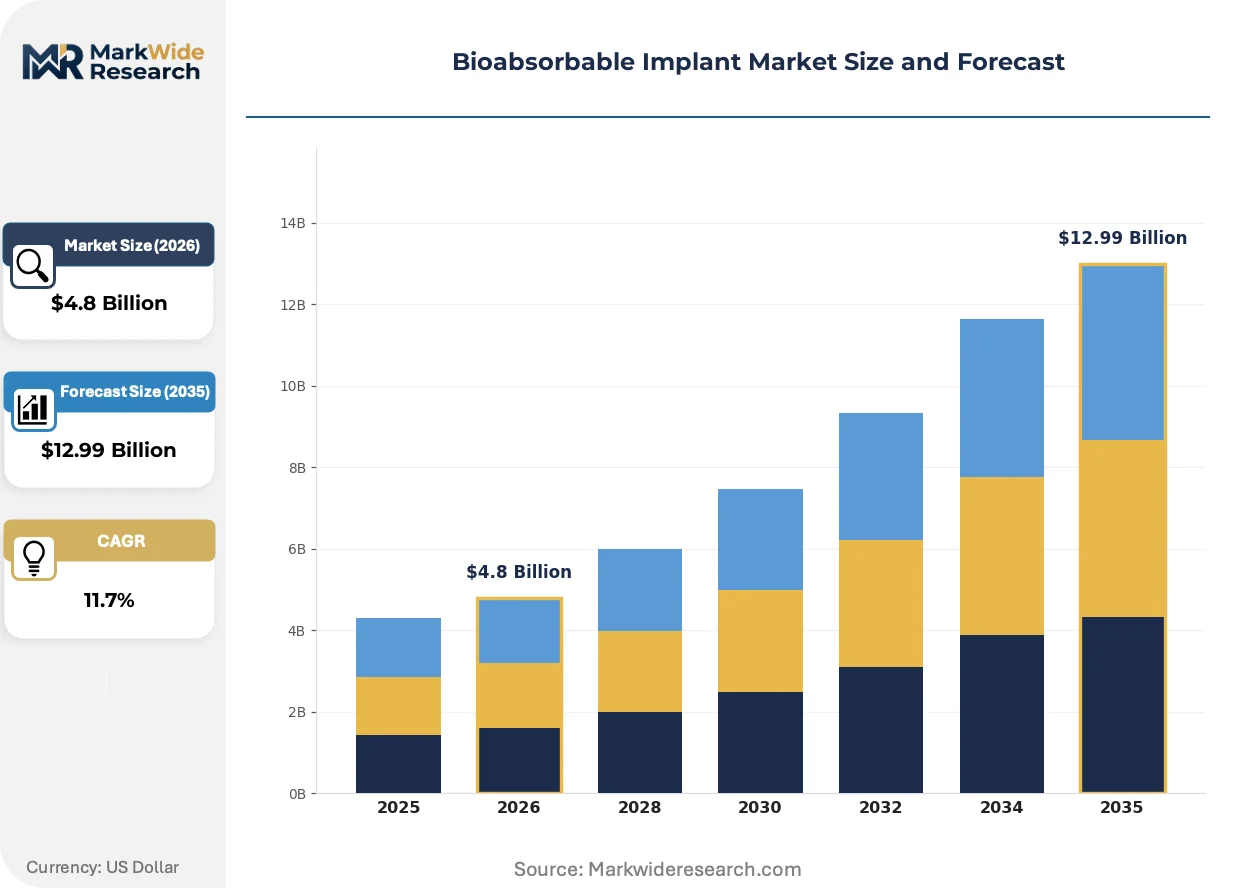
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product approval timelines while simultaneously elevating biocompatibility documentation burdens, forcing manufacturers to restructure clinical evidence strategies around polymer degradation profiles.
Growth Catalysts
- MDR Compliance Deadlines:The EU's Medical Device Regulation mandates enhanced clinical evidence for resorbable implant longevity claims, accelerating consolidation among prepared manufacturers.
- Hospital Purchasing Consortia:United States health systems increasingly favor suppliers with comprehensive bioabsorbable portfolios, concentrating procurement volume among integrated vendors.
- Polylactic Acid Formulations:Advances in PLLA and PLGA copolymer synthesis enable tunable degradation rates that match specific tissue regeneration timelines in orthopedic trauma.
Market Restraints
- Monomer Supply Concentration:Lactic acid and glycolic acid feedstock production clusters in China, exposing European and North American device makers to input cost volatility and trade friction.
- Degradation Rate Variability:Patient-specific metabolic differences create unpredictable mechanical failure windows, limiting adoption in load-bearing applications.
- Metal Implant Substitution Economics:Titanium and stainless steel hardware retain entrenched reimbursement codes and established supply chains in hospital value analysis frameworks.
Strategic Opportunities
- Pediatric Craniofacial Surgery:Avoidance of secondary removal surgeries in growing patients creates a defensible premium segment for resorbable plating systems.
- EU Green Deal Alignment:Biopolymer sourcing certifications and carbon footprint disclosures are becoming tender requirements in European public procurement.
- Drug-Eluting Stent Convergence:Combination products integrating antiproliferative agents with bioabsorbable scaffolds open cardiovascular applications beyond mechanical fixation.
Industry Challenges
- Polymer Processing Expertise Scarcity:Injection molding and extrusion technicians with medical-grade resorbable experience command premium wages in tight labor markets.
- ISO 10993-6 Testing Bottlenecks:Extended implantation study durations for local tissue response evaluation delay product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioabsorbable Implant Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screws, Plates, Stents, Sutures Material: Polylactic Acid, Polyglycolic Acid, Copolymers, Gelatin End User: Hospitals, Clinics, Research Institutes, Rehabilitation Centers Application: Orthopedics, Cardiovascular, Dentistry, Neurology |
| Companies Covered | Medtronic, Stryker, Zimmer Biomet, Smith & Nephew, Johnson & Johnson, Boston Scientific Corporation, B. Braun, Arthrex, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioabsorbable Implant Market Evolving Landscape
Polymer science advances and regulatory data requirements are converging to reshape how bioabsorbable devices demonstrate clinical value. Manufacturers now compete on degradation precision rather than material novelty alone.
Magnesium-based resorbable alloys are expanding into orthopedic trauma applications previously dominated by polymer screws and plates. Trauma surgeons in German and Swiss university hospitals are piloting these metallic alternatives for load-bearing fractures where polymer mechanical strength proves insufficient. The technology is expanding into mid-shaft long bone fixation, compressing the addressable market for high molecular weight polylactic acid implants in sports medicine.
REACH Annex XIV authorization requirements for polymerization catalysts are forcing reformulation of lactic-glycolic copolymer production pathways. European compounders must substitute tin-based catalysts with enzymatic or organometallic alternatives, adding process validation costs. Small-batch orthopedic screw manufacturers in Italy and Spain face disproportionate compliance burdens relative to scaled craniofacial plate producers.
Hospital value analysis committees now require total episode cost documentation comparing bioabsorbable against permanent metal alternatives. United States purchasing consortia in the Midwest and Southeast are standardizing these analyses across orthopedic service lines. Academic medical centers in Massachusetts and California have begun incorporating patient-reported outcome measures into implant selection algorithms.
Bioabsorbable Implant Market Segmentation
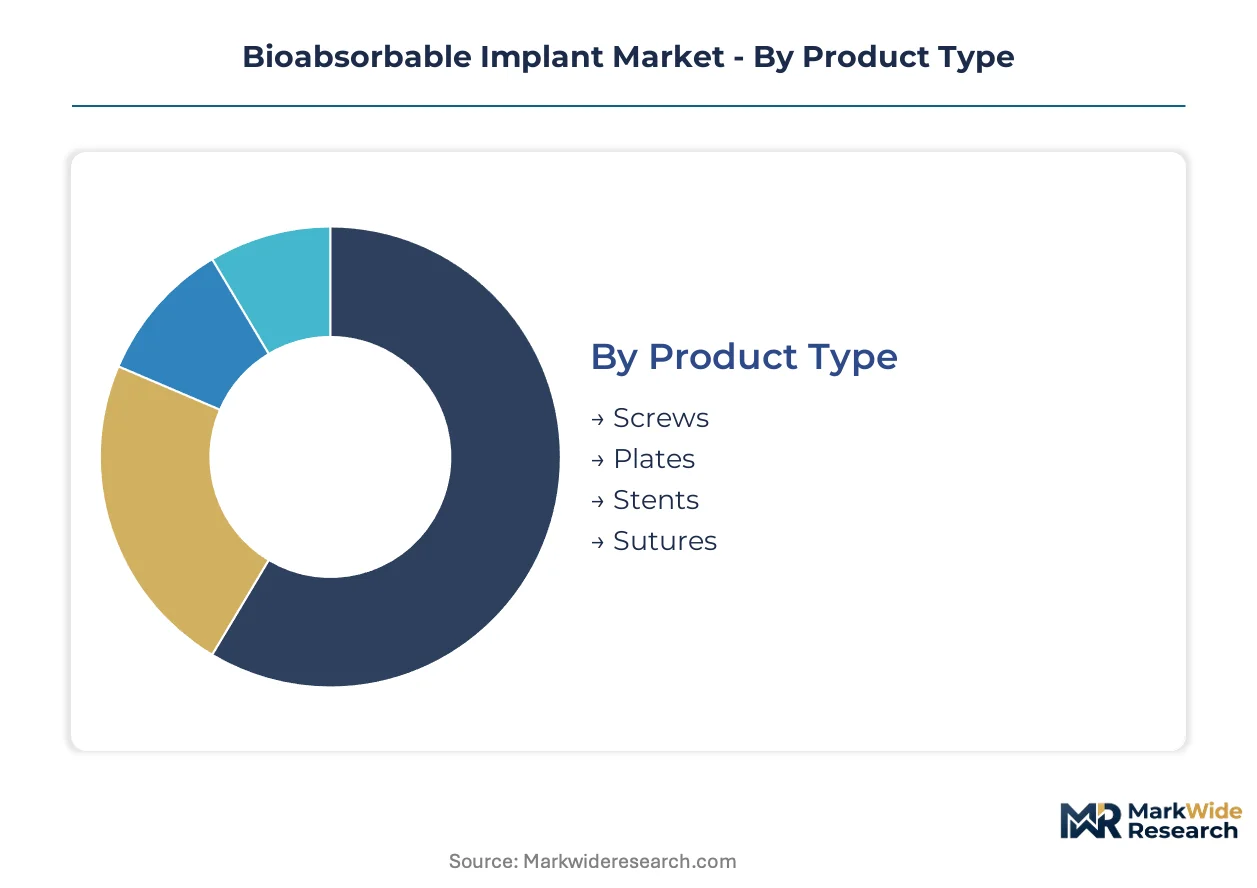
Degradation precision and mechanical performance requirements vary sharply across implant categories, forcing manufacturers to align polymer formulations with specific anatomical healing timelines. Segmentation reveals where formulation investments yield premium positioning versus commodity competition.
Product Type:
Replacement cycles differ fundamentally between permanent fixation hardware and temporary scaffolding devices, with upgrade pressures concentrated in trauma applications seeking reduced revision rates.
- Screws:Cylindrical fixation devices machined from high molecular weight polylactic acid provide temporary bone anchoring during fracture healing. German and Swiss trauma centers drive specification upgrades toward magnesium alloy alternatives in load-bearing applications. Orthopedic surgical suites in the United States Midwest favor comprehensive screw portfolios from integrated vendors.
- Plates:Flat or contoured polymer sheets with screw holes stabilize craniofacial and long bone fractures before hydrolytic absorption. Pediatric craniofacial applications command premium positioning through avoidance of secondary removal surgeries in growing patients. Massachusetts academic medical centers incorporate these into value analysis frameworks.
- Stents:Tubular scaffolds maintain vascular patency during endothelialization before dissolving completely.
- Sutures:Monofilament or braided threads fabricated from glycolide-lactide copolymers close soft tissue wounds without foreign body retention.
Volume placements concentrate in screws and plates; the faster expansion belongs to stents.
Material:
Cost tiers separate commodity lactic acid formulations from engineered copolymers commanding formulation premiums.
- Polylactic Acid:Semicrystalline thermoplastic derived from corn starch fermentation offers tunable degradation through molecular weight control. PLLA variants dominate orthopedic trauma fixation where mechanical strength must persist 12-18 months. California research institutes specify these for load-bearing applications.
- Copolymers:Lactic-glycolic acid combinations enable precise degradation rate matching to tissue regeneration timelines through monomer ratio adjustment. REACH Annex XIV catalyst substitution requirements force European compounders into enzymatic production pathways. Italian and Spanish manufacturers face disproportionate compliance burdens.
- Polyglycolic Acid:Rapidly hydrolyzing polymer suits short-term wound closure applications.
- Gelatin:Natural protein derived from collagen hydrolysis serves hemostatic and barrier functions.
Procurement volume clusters in polylactic acid; copolymers gain share fastest through degradation customization.
End User:
Customer type determines purchasing authority structure, with consolidated health systems wielding portfolio-based selection power.
- Hospitals:Integrated delivery networks with value analysis committees scrutinize total episode costs against permanent metal alternatives. Southeast United States purchasing consortia standardize bioabsorbable selection algorithms across orthopedic service lines. Midwestern systems favor suppliers with comprehensive resorbable portfolios.
- Clinics:Ambulatory surgical centers concentrate demand in sports medicine and minor trauma applications.
- Research Institutes:Massachusetts and California academic medical centers pilot patient-reported outcome integration into implant selection protocols.
- Rehabilitation Centers:Post-acute facilities influence long-term functional outcome documentation.
Procurement authority concentrates in hospitals; research institutes expand fastest through evidence generation mandates.
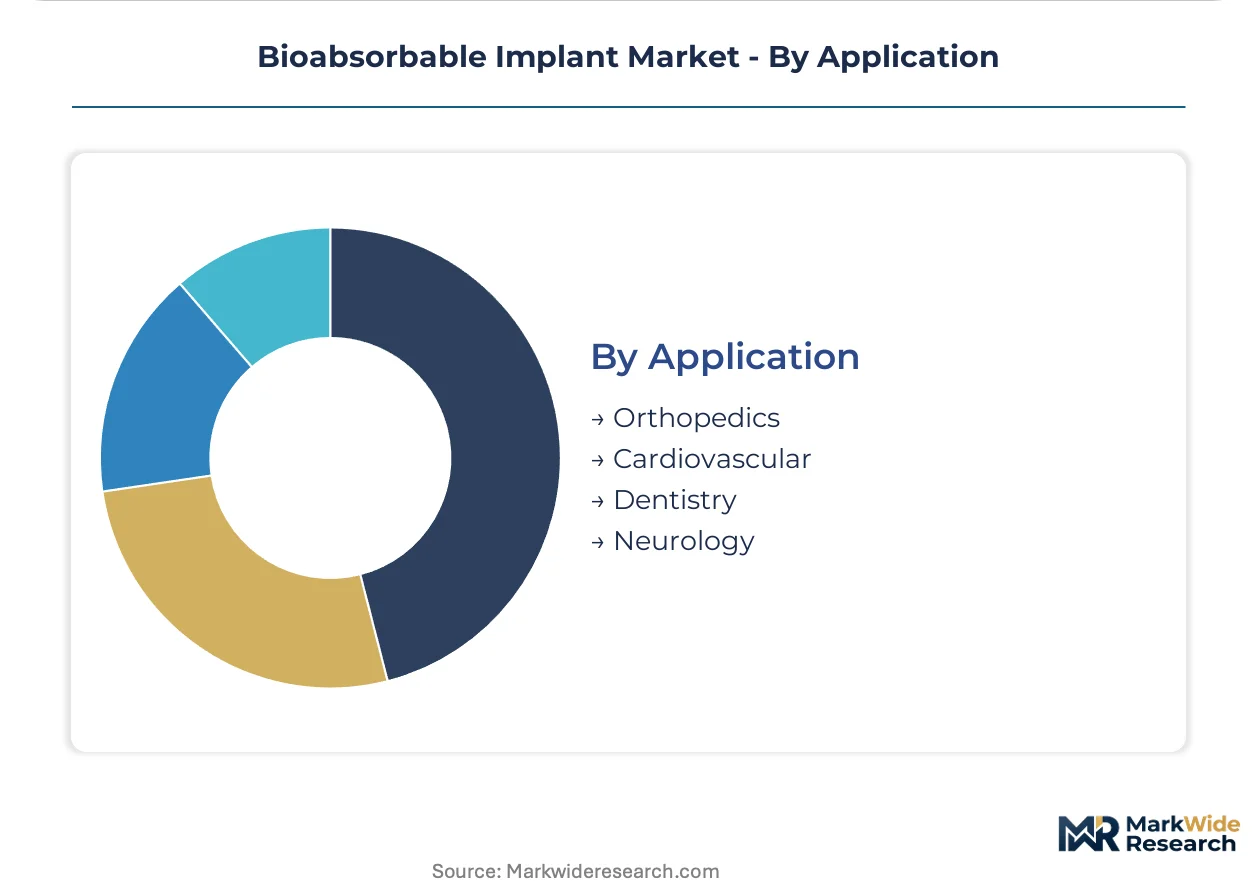
Application:
Maturity gradients separate established orthopedic fixation from emerging cardiovascular and neurological frontiers.
- Orthopedics:Trauma, sports medicine, and craniofacial reconstruction represent the dominant revenue base with established reimbursement pathways. Screws and plates in long bone and facial fracture fixation generate predictable placement volumes. German university hospitals pilot magnesium alternatives in mid-shaft fracture applications.
- Cardiovascular:Drug-eluting bioabsorbable scaffolds target coronary artery disease with antiproliferative agent integration.
- Dentistry:Guided bone regeneration membranes and orthodontic anchorage devices serve oral surgery applications.
- Neurology:Dural substitutes and nerve conduits represent nascent adoption with limited clinical evidence bases.
Revenue concentration sits with orthopedics; cardiovascular climbs fastest through stent technology convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American bioabsorbable implant innovation through Massachusetts General Hospital's clinical trial networks and the surrounding Cambridge-Waltham medical device corridor. Hospital purchasing consortia in this cluster drive standardization of value analysis frameworks across orthopedic service lines.
United States
Midwest hospital systems consolidate procurement around suppliers with comprehensive resorbable portfolios, while California academic medical centers integrate patient-reported outcomes into implant selection algorithms. FDA quality system regulations enforce stringent biocompatibility documentation for polymer degradation profiles. The Minneapolis-St. Paul corridor concentrates manufacturing scale for craniofacial screw systems.
Germany
University hospitals in Munich and Berlin pilot magnesium alloy alternatives to polymer implants in mid-shaft long bone fixation. EMA MDR frameworks mandate enhanced clinical evidence for resorbable implant longevity claims, compressing approval timelines for prepared manufacturers. The Rhine-Main industrial cluster hosts specialized compounders reformulating lactic-glycolic copolymers under REACH Annex XIV catalyst substitution requirements.
Switzerland
Swissmedic oversight aligns with stringent biocompatibility protocols that favor manufacturers with integrated polymer research capabilities. Zurich and Basel anchor precision machining clusters for high molecular weight polylactic acid orthopedic hardware. Trauma centers in these cities generate clinical evidence for tunable degradation rate applications.
China
NMPA medical device registration reforms accelerate domestic bioabsorbable stent approvals while tightening polymer sourcing documentation. Shanghai and Suzhou concentrate injection molding capacity for medical-grade resorbable devices. The Yangtze River Delta absorbs technology transfer from multinational joint ventures seeking localized production.
Japan
PMDA consultation procedures for combination products create specialized pathways for drug-eluting bioabsorbable scaffolds. Tokyo and Osaka medical centers adopt polymer-based cardiovascular alternatives to reduce long-term complication rates. The Kanto region maintains precision extrusion expertise for monofilament suture production.
Bioabsorbable Implant Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with captive polymer research capabilities. Hospital purchasing consolidation in the United States and European MDR compliance burdens favor scaled manufacturers with integrated clinical evidence generation. Three archetypes dominate: integrated orthopedic conglomerates with comprehensive resorbable portfolios, cardiovascular specialists leveraging stent technology convergence, and regional fabricators serving niche craniofacial applications. Competitive moves center on backward integration into polymer synthesis and strategic partnerships with academic medical centers for longitudinal outcome studies.
Among diversified orthopedic conglomerates, Medtronic and Stryker exemplify the integrated research-to-manufacturing archetype, while Johnson & Johnson occupies a position within the suture and wound closure specialization tier. These anchors represent contrasting strategic postures: one emphasizing polymer formulation control, another scaling specialized manufacturing systems, the third navigating diverse international regulatory pathways through differentiated platform architectures.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Zimmer Biomet |
| Smith & Nephew |
| Johnson & Johnson |
| Boston Scientific Corporation |
| B. Braun |
| Arthrex |
| Integra LifeSciences |
| Others |
Value Network & Pricing Analysis
The EU Green Deal biopolymer certification requirements now gate qualified supply access and premium-tier pricing eligibility for European public procurement contracts. Hospital value analysis committees in the United States Midwest simultaneously demand total episode cost documentation, compressing margins for manufacturers lacking backward integration into polymer synthesis.
Pricing Analysis
Value-based pricing anchored to avoidance of secondary removal surgeries commands premium positioning in pediatric craniofacial applications. Pricing stratifies across premium, standard, and economy tiers based on copolymer formulation complexity and ISO 10993-6 testing completion status. Cost compression in standard-grade polylactic acid screws is intensifying because magnesium alloy substitutes are gaining traction in German trauma centers. Ambulatory surgical centers exhibit highest price sensitivity, while Massachusetts academic medical centers prioritize patient-reported outcome integration over unit cost.
Supply Chain Analysis
Injection molding technicians with medical-grade resorbable experience command premium wages in tight labor markets across the Minneapolis-St. Paul corridor and Shanghai-Suzhou industrial clusters. Lactic acid and glycolic acid feedstock production concentrates in China, while high molecular weight polymer compounding localizes in Germany and Switzerland. Single-source vulnerability in tin-based catalyst supply chains is forcing European compounders into enzymatic production pathway validation. Distribution runs through integrated delivery networks with value analysis committee oversight in the United States and specialized orthopedic distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR enhanced clinical evidence mandates function as a cost-of-compliance moat, consolidating procurement volume among manufacturers with longitudinal outcome study capabilities and compressing margins for unprepared competitors.
For Market Incumbents: To counter magnesium alloy displacement in load-bearing trauma applications, anchor market position through captive supply of high molecular weight polylactic acid formulations and capacity expansion in precision extrusion capabilities for craniofacial plate systems. Prioritize backward integration into polymer synthesis to neutralize Chinese monomer supply volatility and secure REACH Annex XIV compliant catalyst pathways. For New Entrants and Emerging Players: Hospital purchasing consortia in the United States Southeast represent the most penetrable channel partner type for specialized suture platforms and drug-eluting stent combination products. Target ambulatory surgical center networks with sports medicine screw portfolios that navigate diverse international regulatory pathways through modular platform architectures. Emphasize pediatric craniofacial applications where avoidance of secondary surgeries creates defensible premium positioning. For Investors and Strategic Acquirers: FDA quality system enforcement actions against polymer degradation profile documentation gaps are the leading indicator that regulatory compliance capabilities will determine acquisition premiums across the analysis window. Focus on mid-cap manufacturers with integrated ISO 10993 testing infrastructure and established academic medical center partnerships for longitudinal evidence generation. Monitor EMA MDR approval timeline compression as the critical inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captive supply of lactic-glycolic copolymers neutralizes Chinese feedstock volatility and REACH catalyst substitution risks. |
| CE Marking Pathway Acceleration | Prepared manufacturers capture procurement volume as EMA MDR deadlines compress approval timelines for resorbable longevity claims. |
| Hospital System Partnership | United States Midwest purchasing consortia favor suppliers with comprehensive bioabsorbable portfolios across orthopedic service lines. |
| Software Companion Development | Patient-reported outcome integration into implant selection algorithms at Massachusetts academic medical centers differentiates premium positioning. |
| Reimbursement Strategy | Total episode cost documentation against permanent metal alternatives satisfies hospital value analysis committee scrutiny in Southeast consortia. |
Research Methodology
Document review covered FDA quality system regulations, EMA MDR framework guidance, ISO 10993 biological evaluation standards, and REACH Annex XIV authorization requirements, complemented by interviews with orthopedic trauma surgeons, hospital GPO contracts managers, biomedical engineers, and polymer compounder technical directors. Secondary validation drew from hospital procurement databases, CMS Medicare reimbursement schedules, customs trade data for lactic acid feedstocks, and SEC 10-K filings of diversified medical technology conglomerates. Bottom-up implant placement volume estimates triangulated against top-down market value reconstructions across product type, material formulation, and end-user segments.
Historical volume trajectories cross-referenced against expert panel input from German university hospital trauma centers and Massachusetts academic medical center purchasing committees shaped the analytical framework. Segmentation modeling incorporated product type, material chemistry, end-user purchasing authority structure, and application maturity gradients throughout the forecast period. CAGRs derived from polymer degradation rate customization trends and stent technology convergence patterns in cardiovascular applications.
Caveats apply where FDA enforcement priority shifts, EMA MDR implementation delays, or magnesium alloy clinical trial outcomes could materially shift the outlook for polymer implant addressable markets. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Bioartificial Renal Assist Devices Market
Biomedical Engineering
Medical Biomimetics Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Bioresorbable Scaffolds Market
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market
Biomedical Engineering
Tissue Engineered Skin Substitute Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
Large and Small-Scale Bioprocessing Market
Biomedical Engineering
Tissue Expansion Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Topical Bioadhesives Market
Biomedical Engineering
Biocompatible 3D Printing Market
Biomedical Engineering
Bioactive Coating Devices Market