
 Drinkable Yogurt Market | 2026-2036
Drinkable Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Drinkable Yogurt Market Intelligence
Multi-pack bundling is consolidating as the dominant packaging configuration, replacing single-serve impulse formats in mainstream retail. Danone S.A. leverages its refrigerated distribution network to anchor bundled offerings in European and North American supermarkets. Yakult Honsha Co., Ltd. sustains its daily-dose probiotic positioning through specialized small-bottle formats that resist standardization. Chobani LLC competes by extending its Greek yogurt brand equity into drinkable extensions with elevated protein claims.
Drinkable yogurt denotes a fermented dairy beverage manufactured through Lactobacillus and Streptococcus thermophilus culture fermentation of milk, typically yielding a viscosity between fluid milk and spoonable yogurt at 2,000–8,000 centipoise, designed for direct consumption without utensils. Probiotic variants command the deepest margin pools due to live-culture stability requirements and health-premium pricing power, while flavored formulations dominate unit volume through palatability-driven repeat purchase among children and retail consumers. Organic positioning captures disproportionate shelf-space growth in health stores and online platforms as ingredient-origin verification becomes a non-negotiable filter for health-conscious individuals.
The FDA enforces Grade A Pasteurized Milk Ordinance standards that dictate pathogen control and labeling for interstate dairy beverage commerce, while the EFSA evaluates probiotic health-claim substantiation under EU Regulation 1924/2006, directly constraining permissible marketing language. Japan's Ministry of Health, Labour and Welfare maintains Foods for Specified Health Uses designation requirements that Yakult and Meiji navigate for functional positioning. Stakeholders must monitor evolving live-culture count thresholds and sugar-content disclosure mandates as regulators tighten the boundary between conventional dairy and functional health products.
Market Dynamics
Clean-label formulation pressures and tightening dairy-labeling standards across multiple jurisdictions are redirecting R&D investment toward ingredient transparency and live-culture verification systems.
Growth Catalysts
- EU Regulation 1924/2006:EFSA probiotic health-claim substantiation requirements create defensible premium positioning for validated live-culture products in European retail channels.
- Refrigerated distribution density:Cold-chain infrastructure expansion in the United States enables extended shelf-life formats and premium multi-pack bundling in mainstream supermarkets.
- Functional beverage culture:Daily consumption rituals among health-conscious individuals normalize drinkable yogurt as a meal-replacement and digestive wellness staple.
Market Restraints
- Live-culture stability costs:Cold-chain maintenance and time-temperature monitoring throughout distribution compress margins on probiotic variants.
- Dairy input concentration:Milk supply volatility in major producing regions exposes processors to feed-cost fluctuations and seasonal volume constraints.
- Sugar-content disclosure mandates:Front-of-pack labeling requirements in multiple jurisdictions limit formulation flexibility for flavored children's segments.
Strategic Opportunities
- Japan's FOSHU designation:Foods for Specified Health Uses framework offers regulatory pathway for functional positioning and pharmacy-channel distribution.
- Plant-based fermentation convergence:Oat and coconut milk substrate adaptation opens allergen-free and vegan positioning in premium health stores.
- Direct-to-subscription channels:Recurring delivery models bypass retail slotting fees and build consumption habituation among urban professionals.
Industry Challenges
- Microbiologist talent scarcity:Live-culture strain selection and stability testing require specialized fermentation science expertise that outpaces academic pipeline output.
- Legacy ERP integration:Lot-level traceability requirements for organic and probiotic claims force costly upgrades to batch-tracking infrastructure.
- Cross-border formulation variance:Divergent live-culture count thresholds between FDA Grade A standards and EU dairy regulations complicate unified product architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drinkable Yogurt Market |
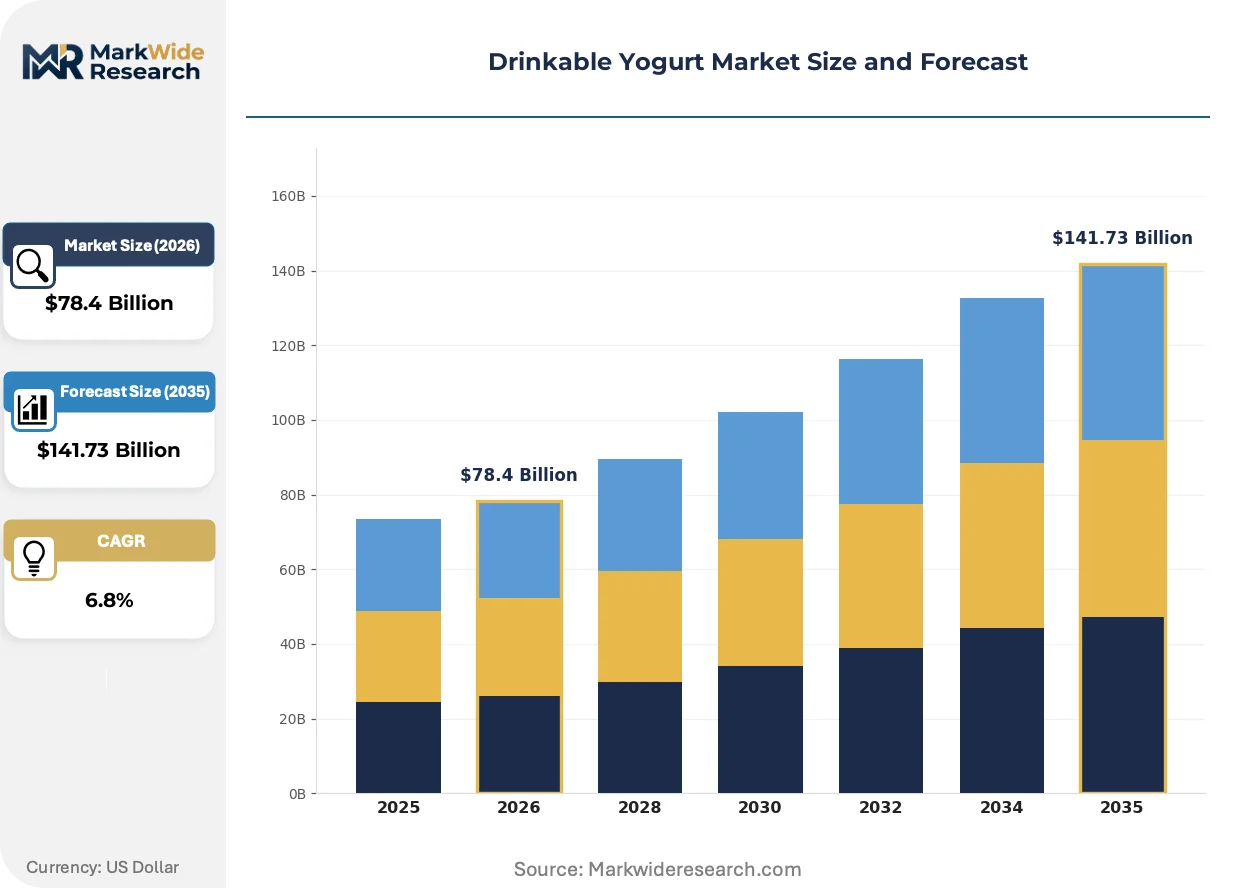
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotic, Flavored, Organic, Low-Fat End User: Retail Consumers, Fitness Enthusiasts, Health-Conscious Individuals, Children Distribution Channel: Supermarkets, Health Stores, Online Platforms, Convenience Stores Packaging Type: Bottles, Tetra Packs, Pouches, Cups |
| Companies Covered | Danone S.A., Yakult Honsha Co., Ltd., Chobani LLC, Nestlé S.A., Meiji Holdings Co., Ltd., General Mills Inc., Fonterra Co-operative Group Ltd., Arla Foods Amba, Lactalis Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drinkable Yogurt Market Strategic Shifts & Innovations
Active culture stabilization technologies and substrate diversification are compressing traditional formulation boundaries while regulatory verification systems reshape competitive differentiation.
High-pressure processing is rewriting shelf-life extension protocols without thermal degradation of probiotic viability. Mid-tier processors in the United States are adopting HPP lines at accelerating pace to bridge the gap between refrigerated distribution reach and live-culture potency claims. This technology is rewriting the geographic radius that premium probiotic brands can serve from single production facilities.
EFSA's evolving guidance on gut-health claim substantiation is tightening the evidentiary threshold for marketing language across European Union member states. Manufacturers must now fund clinical endpoint studies to retain functional positioning on packaging and promotional materials. Probiotic variants targeting digestive wellness claims face the steepest compliance burden and are consolidating substantiation investment among scale players.
Subscription-based replenishment models are displacing impulse single-serve purchases in household penetration strategies. Direct-to-consumer platforms and auto-replenishment algorithms lock in consumption frequency among time-constrained urban professionals. This behavioral shift concentrates most visibly in United States coastal metropolitan markets where refrigerated last-mile logistics have achieved critical density.
Drinkable Yogurt Market Segmentation
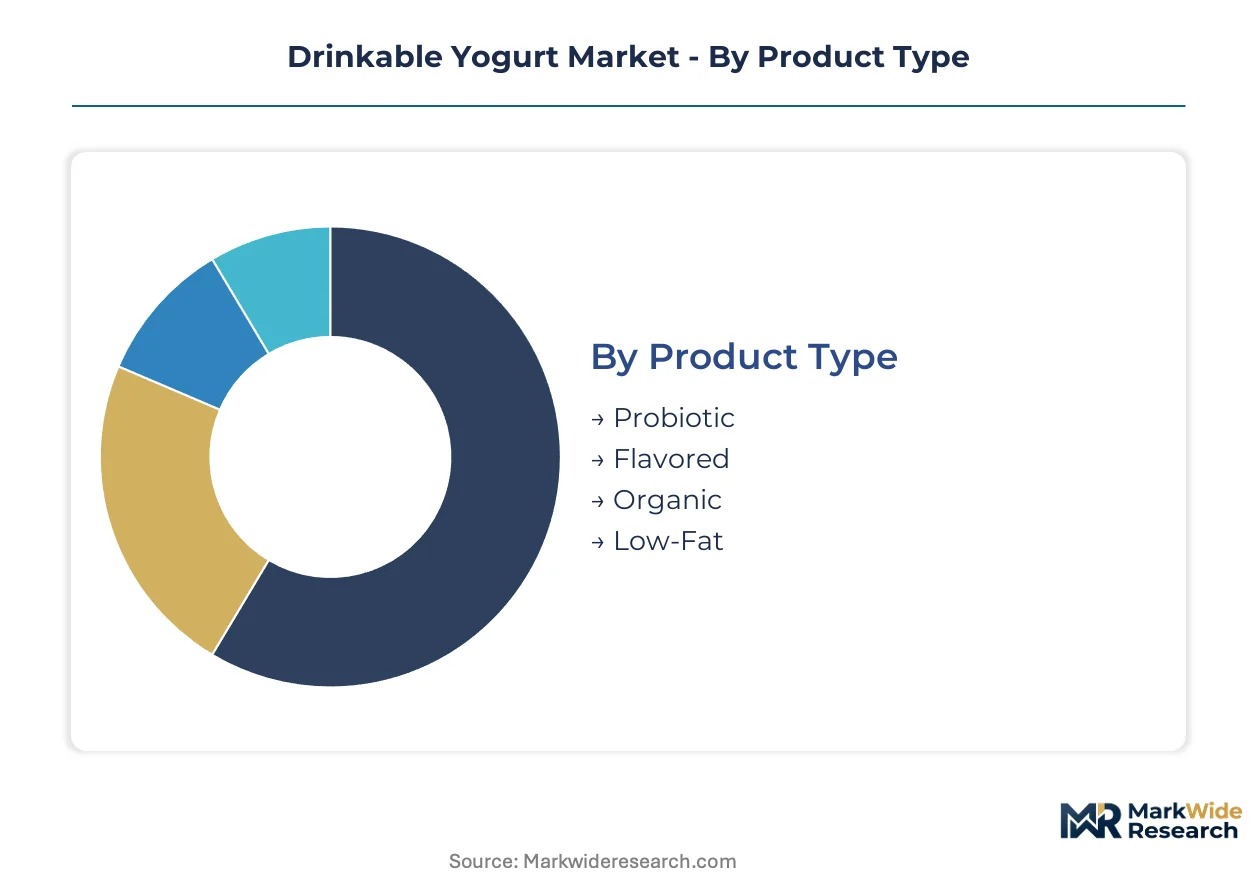
Drinkable yogurt segmentation reveals distinct margin architectures across product formulations and channel strategies. Manufacturers calibrate R&D allocation and cold-chain investment based on which segments command premium positioning versus volume throughput.
Product Type:
Integration depth varies sharply: probiotic and organic variants function as standalone wellness systems with live-culture verification requirements, while flavored and low-fat formats embed as commoditized refreshment options in broader beverage portfolios.
- Probiotic:Fermented dairy beverages containing verified live cultures of Lactobacillus and Bifidobacterium strains, typically requiring cold-chain maintenance from production through retail. Demand concentrates among health-conscious individuals in the United States where functional beverage culture supports daily consumption rituals and pharmacy-channel placement.
- Organic:Products certified to USDA or EU organic standards with full ingredient-origin traceability and prohibition of synthetic additives. Shelf-space allocation is accelerating in health stores and online platforms as ingredient-verification systems become non-negotiable filters for premium positioning.
- Flavored:Sweetened formulations targeting palatability-driven repeat purchase, dominant in children's segments and mainstream retail.
- Low-Fat:Reduced-fat variants competing in weight-management positioning, prevalent in fitness-oriented distribution channels.
Flavored formulations lead volumes today; organic certification is gaining share fastest.
End User:
Cost tier stratification separates premium wellness seekers from mass-market refreshment buyers, with fitness enthusiasts occupying a mid-tier hybrid position.
- Health-Conscious Individuals:Consumers prioritizing digestive wellness claims and clean-label verification, driving disproportionate margin capture. Demand concentrates in United States coastal metropolitan markets where subscription replenishment models and refrigerated last-mile density enable premium pricing.
- Children:Palatability-focused segment with parental gatekeepers, subject to tightening sugar-content disclosure mandates across multiple jurisdictions. Volume concentrates in supermarkets and convenience stores where multi-pack bundling and character licensing drive purchase frequency.
- Retail Consumers:Mainstream household purchasers seeking meal-replacement or snack occasions without specific wellness targeting.
- Fitness Enthusiasts:Protein-seeking consumers gravitating toward elevated protein claims and post-workout consumption timing.
Retail consumers anchor volume scale; health-conscious individuals command the steepest price premiums.
Distribution Channel:
Geographic concentration of refrigerated infrastructure determines which channels can support live-culture claims versus shelf-stable alternatives.
- Supermarkets:Primary volume channel with refrigerated section density enabling multi-pack bundling and promotional stacking. United States and European Union retailers anchor category management through private-label development and slotting fee structures.
- Online Platforms:Subscription-based auto-replenishment models bypass traditional retail economics, concentrating among urban professionals in United States metropolitan markets with same-day cold-chain delivery capability.
- Health Stores:Curated organic and probiotic assortments with educated staff recommendation driving premium conversion.
- Convenience Stores:Impulse-oriented single-serve formats with limited refrigerated facings, favoring shelf-stable or extended-shelf-life products.
Supermarkets dominate absolute volume; online platforms are expanding most quickly in subscription penetration.
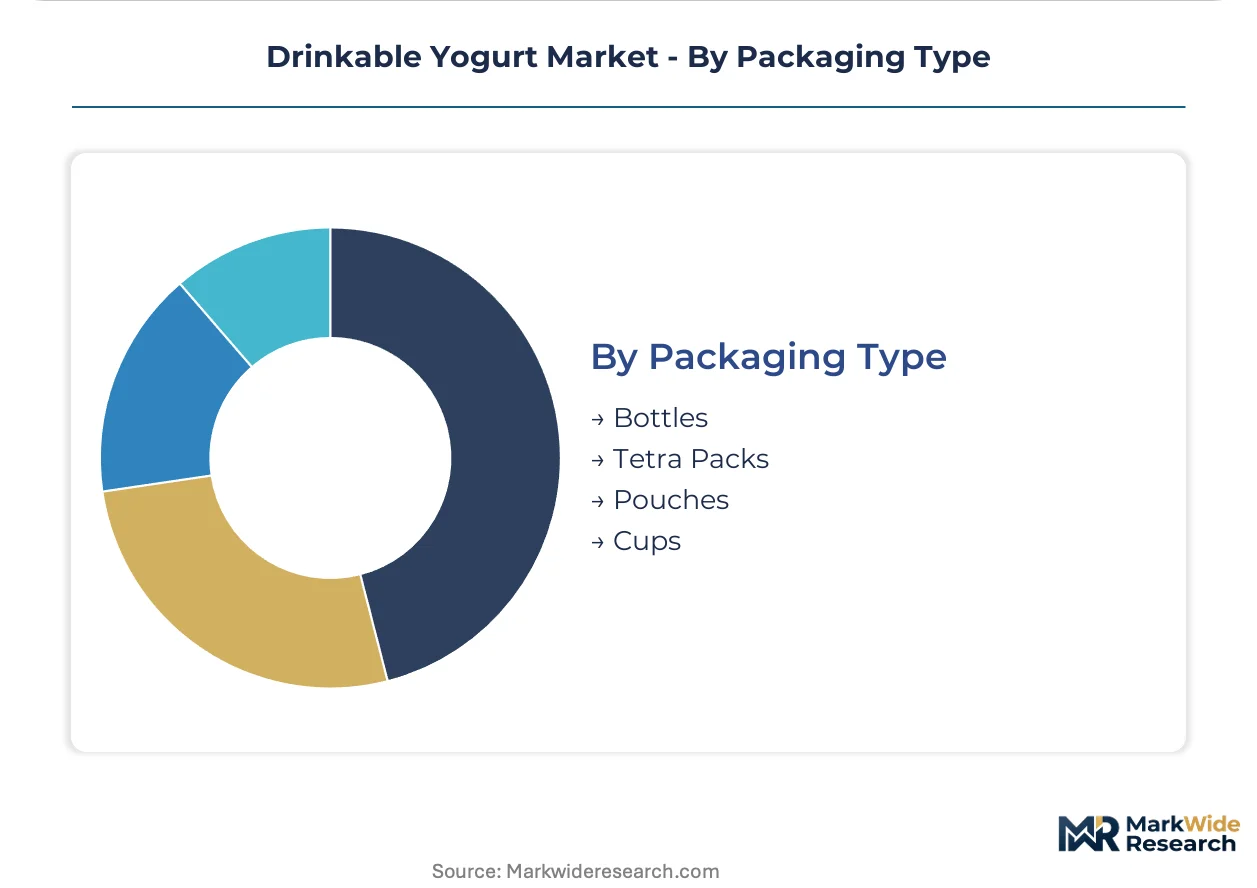
Packaging Type:
Supply concentration in blow-molding and aseptic filling equipment shapes which formats achieve cost parity at scale.
- Bottles:Dominant format for probiotic variants requiring resealability and transparent live-culture count labeling. PET and HDPE blow-molding capacity concentrates among United States and European Union converters with dairy-grade certification.
- Tetra Packs:Aseptic carton systems enabling ambient distribution for shelf-stable formulations, prevalent in markets with underdeveloped cold-chain infrastructure.
- Pouches:Flexible format gaining traction in children's segments and on-the-go consumption occasions.
- Cups:Limited application for drinkable yogurt, primarily in foodservice or sampling contexts.
Bottles lead manufacturing investment; Tetra Packs serve markets where refrigerated distribution remains constrained.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Drinkable yogurt originated in Japan during the 1930s with the development of fermented milk cultures for daily consumption, establishing the foundation for today's functional beverage category. The industry subsequently scaled through European dairy traditions and American refrigerated distribution networks. Geographic expansion now tracks cold-chain infrastructure density and probiotic health-claim regulatory pathways.
United States
Functional beverage culture and subscription replenishment models concentrate demand in coastal metropolitan markets. The FDA enforces Grade A Pasteurized Milk Ordinance standards governing interstate dairy commerce and live-culture labeling. Greater Boston anchors premium probiotic innovation with dense refrigerated last-mile logistics supporting direct-to-consumer delivery platforms.
Japan
Daily consumption rituals and pharmacy-channel distribution sustain the original functional positioning. The Ministry of Health, Labour and Welfare maintains Foods for Specified Health Uses designation requirements that validate gut-health marketing claims. Tokyo-Osaka corridor production facilities specialize in small-bottle fermentation systems optimized for live-culture stability.
Germany
Clean-label formulation pressures and organic certification demand reshape R&D allocation across dairy processors. EFSA probiotic health-claim substantiation under EU Regulation 1924/2006 constrains permissible marketing language. Bavaria hosts concentrated blow-molding capacity for PET bottle formats serving pan-European refrigerated distribution networks.
France
Traditional fermented dairy heritage supports premium positioning in domestic and export markets. EU dairy-labeling standards tighten ingredient transparency requirements for cross-border retail placement. Île-de-France logistics clusters coordinate multi-pack bundling strategies for supermarket channel penetration.
China
Rising health-conscious middle-class adoption drives refrigerated infrastructure investment in tier-one cities. SAMR dairy beverage standards govern probiotic count thresholds and shelf-life labeling for domestic commerce. Yangtze River Delta manufacturing bases scale aseptic filling capacity for ambient distribution to cold-chain constrained inland provinces.
Drinkable Yogurt Market Key Industry Players
The competitive structure tilts toward multinational dairy conglomerates with captive refrigerated distribution networks. Scale advantages concentrate in players commanding multi-regional cold-chain logistics and live-culture verification systems. Three archetypes dominate: legacy fermented dairy specialists, diversified nutrition multinationals, and Greek yogurt brand extenders. Capacity expansion and portfolio diversification constitute the primary competitive vectors as processors defend shelf-space allocation against plant-based alternatives.
Within the legacy specialist tier, Yakult Honsha Co., Ltd. exemplifies single-format fermentation expertise anchored in daily-dose positioning. Danone S.A. and Chobani LLC occupy differentiated positions across bundled multi-pack and elevated protein claim vectors respectively. These three entities represent contrasting pathways for live-culture product architecture—specialized small-format, diversified refrigerated network leverage, and brand equity extension into adjacent viscosity categories.
| Leading Market Players |
|---|
| Danone S.A. |
| Yakult Honsha Co., Ltd. |
| Chobani LLC |
| Nestlé S.A. |
| Meiji Holdings Co., Ltd. |
| General Mills Inc. |
| Fonterra Co-operative Group Ltd. |
| Arla Foods Amba |
| Lactalis Group |
| Others |
Cost & Logistics Intelligence
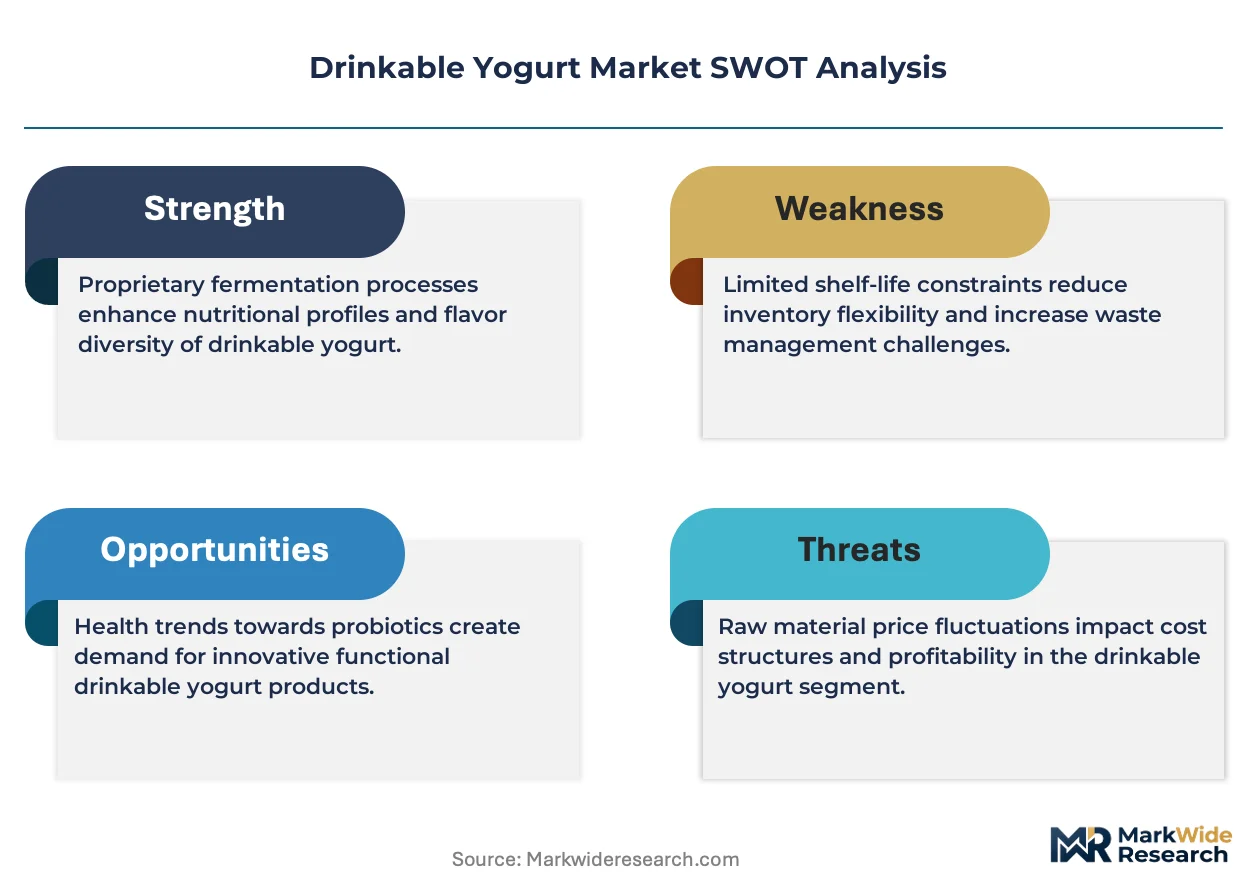
Global Dairy Trade price indices for skim milk powder and whey protein concentrate cascade through drinkable yogurt manufacturing, compressing margin pools at the standard tier while organic and probiotic variants capture insulation through live-culture verification premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the drinkable yogurt market, with organic certification and live-culture count thresholds as primary price differentiation drivers. Cost compression in the standard tier intensifies because private-label proliferation and retailer consolidation concentrate buying power. Health-conscious individuals exhibit the lowest price sensitivity, accepting per-unit premiums for verified strain counts and cold-chain integrity, while retail consumers in multi-pack formats demonstrate highest elasticity.
Supply Chain Analysis
Microbiologist talent scarcity in Bavaria, Île-de-France, and Wisconsin constrains fermentation science capacity expansion for live-culture strain development and stability testing. Raw material sourcing draws from concentrated milk supply regions in New Zealand, the European Union, and the United States, with probiotic culture banks anchored in Japan and Denmark. Single-source vulnerability in specialized Lactobacillus strain supply creates chokepoint exposure. Distribution runs through refrigerated third-party logistics networks with cold-chain monitoring from production through retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drinkable yogurt market functions as a stable compounder, with daily consumption habituation among health-conscious individuals generating predictable replenishment velocity and subscription retention.
For Market Incumbents: To counter plant-based fermentation convergence from oat and coconut milk entrants, deepen backward integration into captive probiotic culture banking and expand high-pressure processing capacity in United States coastal markets. Anchor multi-pack bundling through exclusive refrigerated distribution agreements with supermarket category managers. For New Entrants and Emerging Players: Direct-to-subscription auto-replenishment algorithms offer the most penetrable wedge for urban professional segments in United States metropolitan markets with same-day cold-chain delivery density. Target pharmacy-channel placement in Japan through FOSHU designation navigation. Build brand equity through clinical endpoint study investment that satisfies EFSA gut-health claim substantiation requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where live-culture verification systems and refrigerated distribution networks achieve overlapping geographic density. Over the medium-term horizon, vertically integrated processors with captive fermentation science talent and multi-regional cold-chain logistics present optimal acquisition profiles. Monitor EFSA guidance evolution on probiotic health-claim thresholds as inflection indicator for marketing language compliance burdens.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Line Deployment | HPP technology extends shelf-life without thermal degradation, enabling wider refrigerated distribution radius from single facilities. |
| FOSHU Designation Navigation | Japan's Foods for Specified Health Uses framework unlocks pharmacy-channel placement and functional positioning premium capture. |
| Direct-to-Subscription Platform Launch | Auto-replenishment algorithms bypass retail slotting fees and lock consumption frequency among time-constrained urban professionals. |
| Backward Integration into Culture Banking | Captive probiotic strain supply insulates against single-source fermentation science bottlenecks and accelerates R&D iteration. |
| Clinical Endpoint Study Investment | EFSA-compliant gut-health claim substantiation creates defensible premium positioning and marketing language exclusivity in EU retail. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with dairy processing executives, refrigerated logistics operators, supermarket category buyers, and fermentation science researchers. Secondary validation draws from FDA Grade A Pasteurized Milk Ordinance filings, EFSA health-claim substantiation databases, SAMR dairy beverage standards, and customs trade data on milk powder and culture imports. Bottom-up volume modeling triangulates against top-down value projections across product type, end user, and distribution channel dimensions.
Rate-of-change decomposition separates volume growth drivers from pricing dynamics across the analysis window. Segmentation modeling incorporates probiotic versus conventional formulation, organic certification status, packaging format, and regional regulatory cluster as core dimensions. CAGRs derive from historical trajectory analysis adjusted for live-culture stability technology adoption curves and refrigerated infrastructure expansion patterns. Forecast inputs include cold-chain density metrics, subscription platform penetration rates, and evolving sugar-content disclosure mandate timelines.
The model holds under steady regulatory enforcement of live-culture count thresholds and continued cold-chain investment in target metropolitan markets; deviation in milk supply volatility or accelerated plant-based substitution would shift volume trajectories. Practitioners should monitor EFSA guidance revisions and FDA labeling enforcement intensity for early signals of compliance burden evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Europe Dairy Based Beverages Market
Dairy Products
North America Cheese Market
Dairy Products
North America Milk Powder Market
Dairy Products
Low-Fat Cheese Nutrition Market
Dairy Products
Donkey Milk Market
Dairy Products
China Milk Protein Market
Dairy Products
United Kingdom Milk Protein Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Cheese Concentrate Market
Dairy Products
North America Dairy Desserts Market
Dairy Products
Organic Milk Powder Market
Dairy Products
Ultra High Temperature Milk Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Lactose Market
Dairy Products
United States Milk Protein Market
Dairy Products
Recombined Milk Market