
 Europe Yogurt Market | 2026-2036
Europe Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Yogurt Market Foresight
Multi-source dairy procurement across European cooperatives is recalibrating competitive dynamics in the yogurt sector. Danone SA leverages its fermentation technology leadership to maintain shelf-space dominance in French retail channels. Groupe Lactalis S.A. anchors its position through backward integration into milk collection networks spanning multiple member states. Arla Foods amba sustains cooperative-owned supply advantages that buffer margin pressure from volatile farm-gate prices.
Yogurt constitutes a fermented milk product manufactured through bacterial culture conversion of lactose into lactic acid, typically requiring Streptococcus thermophilus and Lactobacillus delbrueckii subsp. bulgaricus with live cultures exceeding 10^7 CFU per gram at production. Greek Yogurt commands disproportionate margin pools due to its protein concentration requiring triple milk volume inputs and extended straining processes. Non-Dairy Yogurt segments built on oat and almond bases attract capital allocation as plant-based alternatives displace conventional dairy in Scandinavian and Benelux retail sets. Distribution Channel dynamics reveal Online Retail as the fastest-expanding route, though Supermarkets retain volume supremacy through chilled-chain infrastructure investments.
EFSA evaluates all probiotic health claims under Regulation 1924/2006, rejecting unsubstantiated assertions and compressing permissible marketing language for live-culture products. The EU Green Deal's Packaging and Packaging Waste Directive accelerates transitions from conventional plastic cups toward recyclable or bio-based alternatives, with France's AGEC law imposing extended producer responsibility obligations ahead of bloc-wide harmonization. REACH compliance governs food-contact substances in packaging materials, adding testing burdens for imported packaging components. Stakeholders must monitor pending revisions to the EU Common Agricultural Policy's dairy quota mechanics and EFSA's evolving stance on novel fermentation-derived ingredients.
Market Dynamics
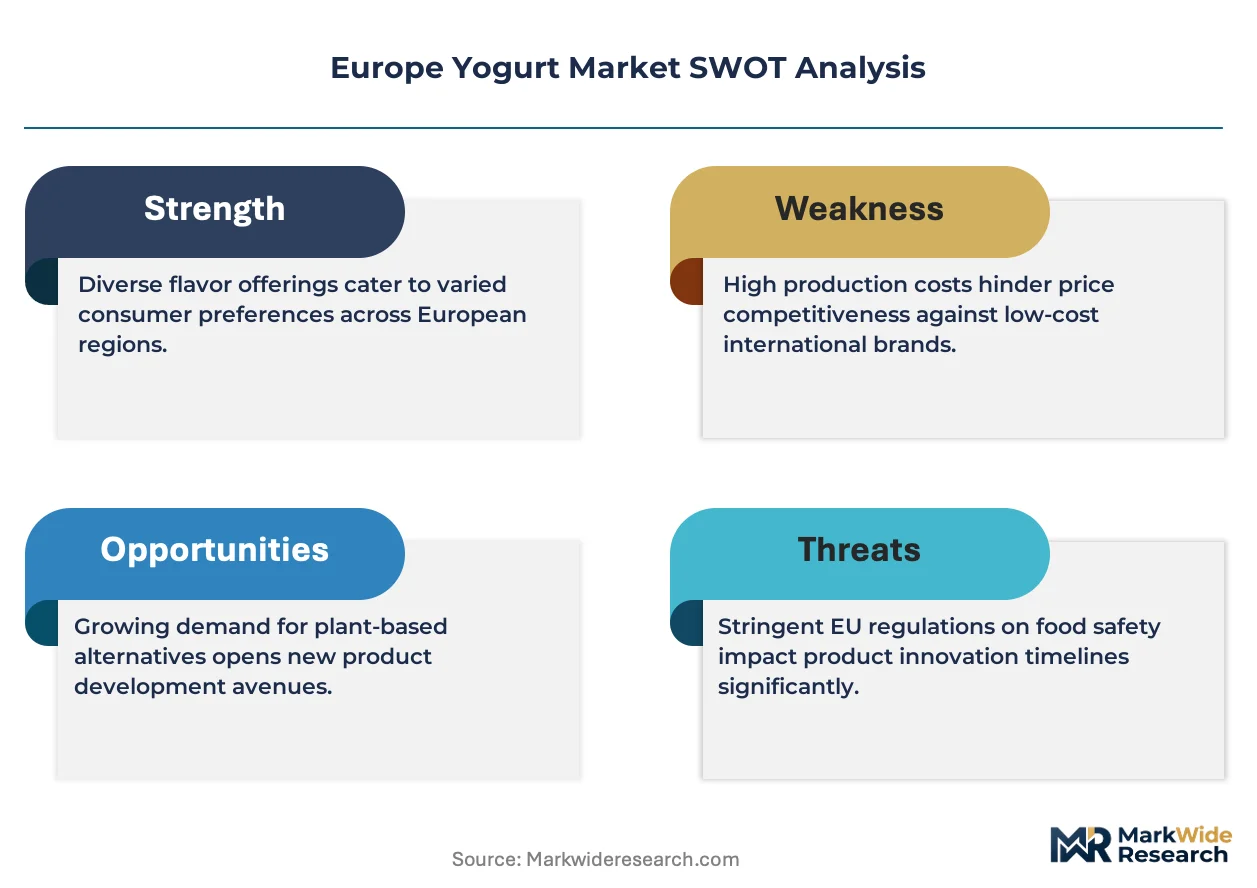
EFSA's stringent health claim evaluations under Regulation 1924/2006 are compressing permissible marketing language for probiotic-enriched yogurts, forcing manufacturers to reformulate around substantiated functional benefits rather than generic wellness positioning.
Growth Catalysts
- EU Green Deal Packaging Mandates:The Packaging and Packaging Waste Directive accelerates transitions toward recyclable and bio-based cup materials, creating first-mover advantages for suppliers with certified sustainable packaging portfolios.
- Probiotic Culture Innovation:Advanced fermentation techniques enabling higher live culture retention through shelf life are expanding permissible health positioning in German and French retail channels.
- Greek Yogurt Premiumization:Protein concentration requirements driving triple milk volume inputs are anchoring margin expansion in Western European chilled dairy sets.
Market Restraints
- Farm-Gate Milk Price Volatility:Input cost fluctuations across European cooperative procurement networks compress margins for non-vertically integrated processors lacking captive milk supply.
- EFSA Substantiation Requirements:The rejection of unsubstantiated probiotic claims under Regulation 1924/2006 limits marketing differentiation and increases R&D expenditure for clinical validation.
- Plant-Based Substitution:Oat and almond-based alternatives are displacing conventional dairy yogurt volumes in Scandinavian and Benelux retail environments.
Strategic Opportunities
- Online Retail Channel Expansion:Direct-to-consumer chilled delivery infrastructure investments unlock geographic penetration beyond traditional supermarket catchment areas in secondary French and German urban markets.
- Novel Fermentation Ingredients:EFSA's evolving stance on fermentation-derived functional ingredients creates regulatory white space for next-generation probiotic strains with documented clinical outcomes.
- France AGEC Law Alignment:Extended producer responsibility obligations imposed ahead of EU-wide harmonization reward early compliance investments with preferred retail listing terms.
Industry Challenges
- REACH Compliance Burden:Food-contact substance testing requirements for imported packaging components extend procurement timelines and increase supplier qualification costs.
- Chilled-Chain Infrastructure:Capital intensity of temperature-controlled distribution networks limits online retail scalability for perishable fermented products with short shelf lives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Yogurt Market |
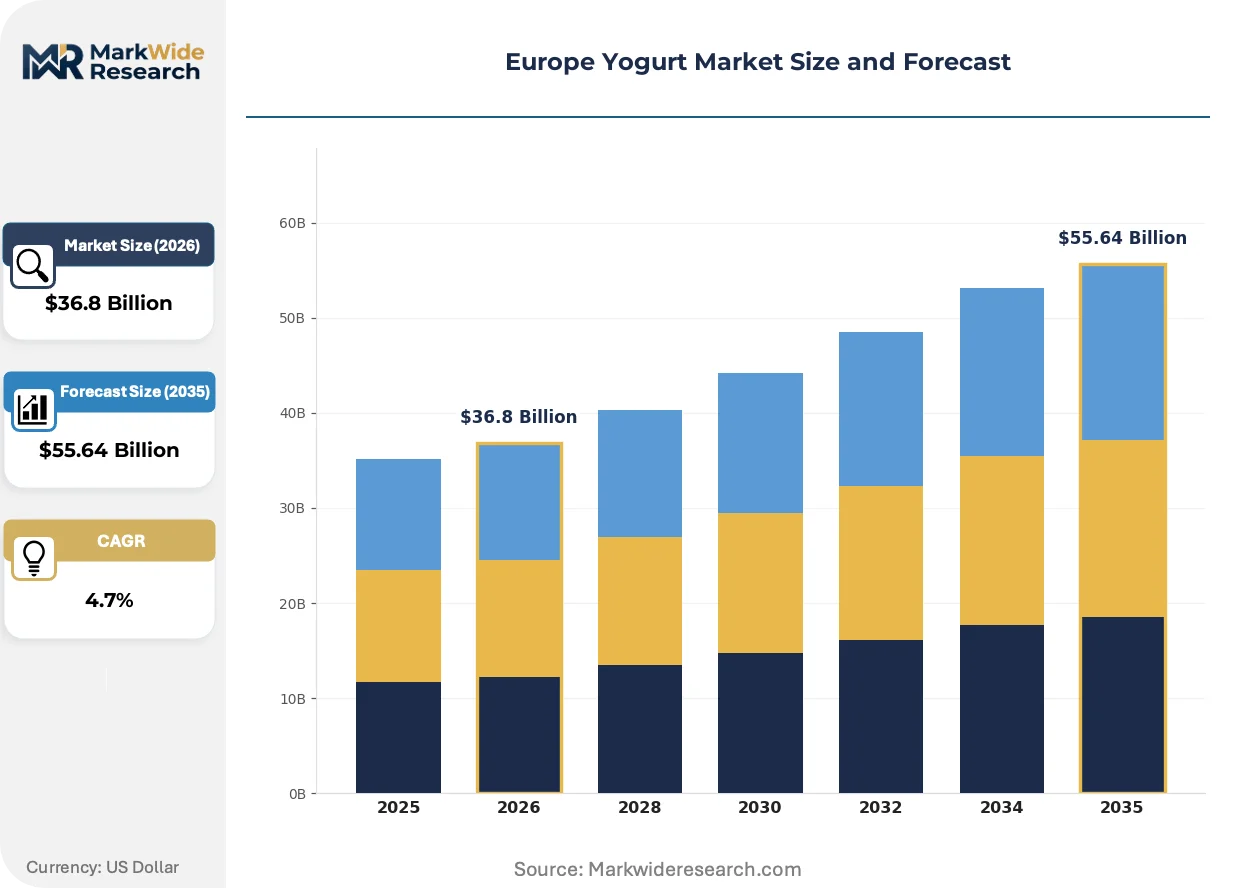
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $55.64 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Yogurt, Greek Yogurt, Non-Dairy Yogurt, Flavored Yogurt Packaging Type: Plastic Cups, Glass Jars, Tetra Packs, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Food Stores End User: Households, Restaurants, Cafés, Retail Outlets |
| Companies Covered | Danone SA, Groupe Lactalis S.A., Arla Foods amba, Theo Müller Group, Nestlé SA, FrieslandCampina, Emmi Group, Fage International SA, Yoplait, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Yogurt Market Shifts & Advancements
Fermentation technology advances and packaging material transitions are reshaping product formulation priorities across European dairy processing facilities.
Precision fermentation systems are integrating culture optimization protocols that enhance live probiotic survival rates through distribution temperature fluctuations. Mid-tier processors in the Netherlands and Belgium are adopting these platforms to meet EFSA substantiation thresholds without multinational R&D budgets. This convergence is compressing the competitive gap between cooperative-owned and privately held manufacturing operations.
France's AGEC law is accelerating extended producer responsibility implementation for single-use dairy packaging ahead of bloc-wide harmonization. Manufacturers must now finance end-of-life collection and recycling infrastructure for conventional plastic cups. Premium and organic yogurt segments are absorbing compliance costs through packaging material upgrades, while standard-tier products face margin compression from unrecoverable regulatory expenditure.
Health-conscious households are rotating procurement toward functional yogurt subcategories with documented digestive and immune benefits. Supermarket chilled aisles in Germany and France are reallocating shelf space from conventional stirred yogurt to probiotic-enriched and high-protein Greek varieties. This behavioral shift concentrates volume growth in Western European markets where premium positioning commands sustained consumer loyalty and repeat purchase rates.
Europe Yogurt Market Segmentation
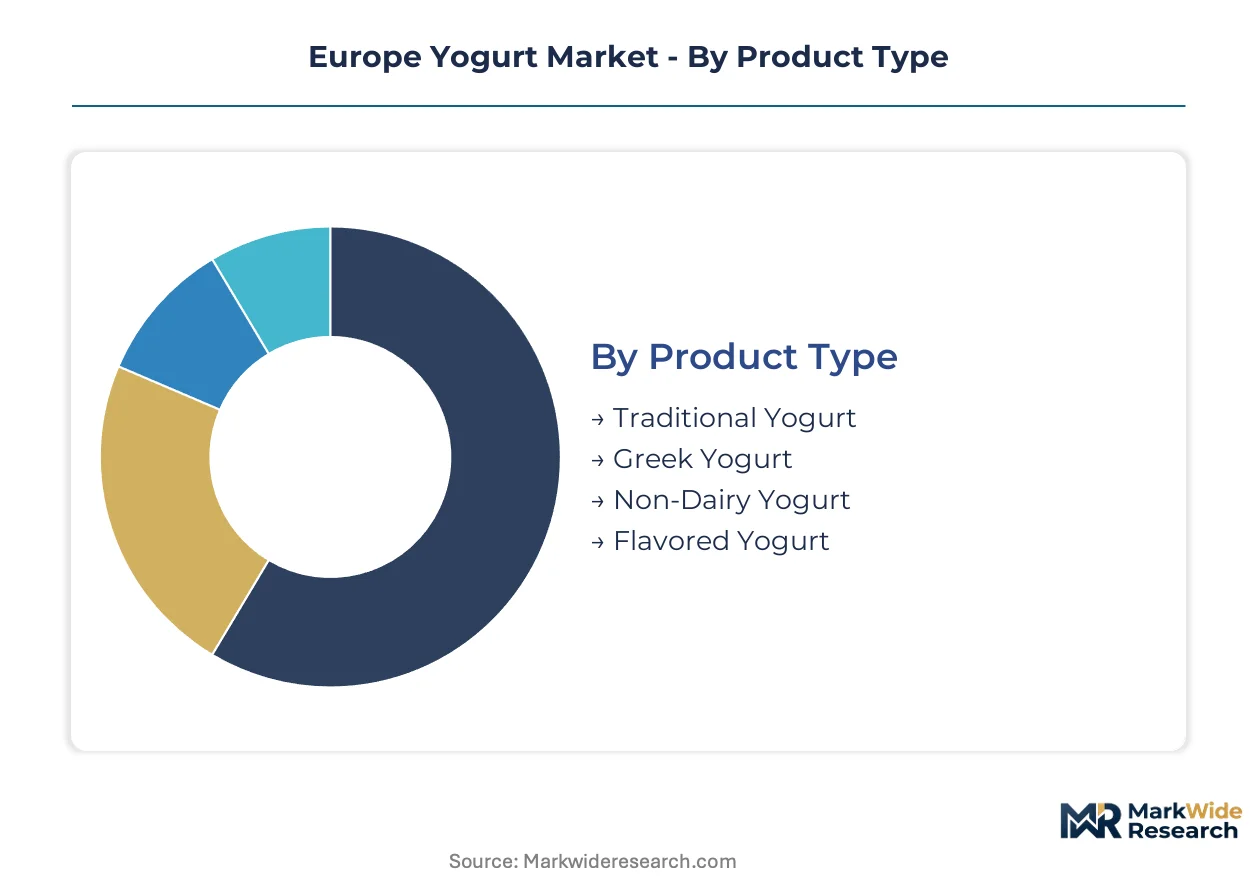
Yogurt segmentation in Europe reflects divergent consumer priorities across health positioning, sustainability credentials, and channel accessibility. Manufacturers configure production assets and packaging investments around these category boundaries to capture margin pools in premium functional segments while defending volume positions in conventional offerings.
Product Type:
Buyers differentiate primarily by protein density, live culture specifications, and base material sourcing when selecting yogurt formats.
- Traditional Yogurt:Fermented milk product manufactured with Streptococcus thermophilus and Lactobacillus delbrueckii subsp. bulgaricus, requiring live cultures exceeding 10^7 CFU per gram at production. German and French households sustain the largest consumption bases, though volume growth is flattening as consumers rotate toward functional alternatives.
- Greek Yogurt:Triple milk volume inputs and extended straining processes concentrate protein content, anchoring disproportionate margin pools in Western European chilled dairy sets. Premium positioning commands sustained loyalty in urban French retail channels where protein-forward nutrition claims drive repeat purchase.
- Non-Dairy Yogurt:Oat and almond-based formulations displace conventional dairy volumes in Scandinavian and Benelux retail environments.
- Flavored Yogurt:Added fruit preparations and sweetener systems target younger demographics and convenience-oriented consumption occasions.
Traditional yogurt leads volumes today; Greek yogurt is gaining share fastest.
Packaging Type:
Material selection hinges on chilled-chain compatibility, recyclability mandates under France's AGEC law, and shelf-space economics in competing retail formats.
- Plastic Cups:Conventional polystyrene and polypropylene formats dominate unit economics but face accelerated displacement under EU Green Deal packaging directives. Extended producer responsibility obligations are compressing margins for standard-tier products lacking material upgrade pathways.
- Glass Jars:Premium and organic segments absorb higher per-unit costs to signal sustainability credentials and command price premiums in German health food retail.
- Tetra Packs:Aseptic carton formats enable ambient distribution with reduced chilled-chain dependency, expanding geographic penetration in secondary markets.
- Pouches:Flexible formats reduce material weight and transportation costs for single-serve portions targeting on-the-go consumption.
Plastic cups retain volume dominance; glass jars are climbing the fastest as sustainability premiums justify cost absorption.
Distribution Channel:
Route selection determines temperature control requirements, delivery frequency, and direct consumer relationship depth.
- Supermarkets:Chilled-chain infrastructure investments sustain volume supremacy through dedicated dairy aisle placement and promotional scale in French and German retail networks.
- Online Retail:Direct-to-consumer chilled delivery unlocks geographic penetration beyond traditional catchment areas, expanding most quickly in secondary urban markets.
- Convenience Stores:Limited chilled capacity restricts assortment to high-velocity SKUs with extended shelf stability.
- Health Food Stores:Curated probiotic and organic assortments align with EFSA-compliant health positioning for educated consumer segments.
Supermarkets anchor current volumes; online retail shows the steepest expansion trajectory.
End User:
Final demand concentrates in at-home consumption, though foodservice channels present specialized formulation and portioning requirements.
- Households:Health-conscious procurement patterns in Germany and France are expanding purchases of probiotic-enriched and high-protein varieties for daily consumption.
- Restaurants:Foodservice operators require bulk formats and consistent viscosity profiles for menu integration across Mediterranean and Northern European culinary traditions.
- Cafés:Breakfast and snack-oriented positioning drives demand for single-serve Greek and flavored yogurt parfaits.
- Retail Outlets:Independent grocers and specialty stores curate premium assortments with documented live culture specifications.
Households dominate consumption today; restaurants are expanding procurement most rapidly as menu yogurt integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris and the Île-de-France cluster anchor European yogurt innovation through Danone's fermentation R&D facilities and premium retail channel density. The region's regulatory environment shapes formulation standards that propagate across the continent.
Germany
Health-conscious households in Bavaria and North Rhine-Westphalia are expanding probiotic-enriched purchases, with Munich-based cooperatives driving multi-source dairy procurement. EFSA's Regulation 1924/2006 substantiation requirements compress marketing language for functional claims. The Stuttgart industrial corridor concentrates precision fermentation technology adoption among mid-tier processors seeking live culture retention improvements.
France
Protein-forward nutrition claims in urban retail channels sustain Greek yogurt loyalty, while Île-de-France households absorb premium pricing for organic varieties. France's AGEC law imposes extended producer responsibility obligations for single-use dairy packaging ahead of EU-wide harmonization. Lactalis anchors backward integration into milk collection networks spanning Normandy and Brittany cooperative systems.
Netherlands
Oat and almond-based alternatives displace conventional dairy volumes in Amsterdam and Rotterdam retail environments, attracting capital allocation toward plant-based production assets. REACH compliance governs food-contact substance testing for imported packaging components. Wageningen University's food science cluster accelerates novel fermentation ingredient development for EFSA pre-submission validation.
United Kingdom
Online retail chilled delivery infrastructure unlocks geographic penetration beyond London supermarket catchment areas into secondary urban markets. The country's national food standards regulator evaluates probiotic health claims with reference to EFSA precedent. Yorkshire and Lancashire dairy processing facilities are recalibrating toward Greek yogurt protein concentration requirements to capture margin expansion.
Italy
Traditional stirred yogurt consumption in Lombardy and Emilia-Romagna faces flattening volume growth as consumers rotate toward functional alternatives. EU Green Deal packaging directives accelerate transitions from conventional plastic cups toward recyclable alternatives. Parmalat's historical presence in the Po Valley dairy belt exemplifies cooperative-owned supply advantages buffering margin pressure from volatile farm-gate prices.
Europe Yogurt Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue plant-based and precision fermentation niches. The sector exhibits cooperative-owned supply structures alongside multinational processing networks. Three archetypes dominate: vertically integrated dairy cooperatives with captive milk supply, multinational CPG conglomerates with fermentation technology leadership, and specialist Greek yogurt processors with protein concentration expertise. Competitive moves concentrate on packaging sustainability upgrades and direct-to-consumer channel expansion.
Within the cooperative tier, Arla Foods amba exemplifies member-owned supply advantages that buffer input cost volatility. Danone SA occupies a position representing multinational fermentation technology leadership and retail channel dominance. Groupe Lactalis S.A. anchors the vertically integrated archetype through milk collection network control. These three entities collectively illustrate the competitive tension between cooperative governance structures and corporate R&D scale in European dairy processing.
| Leading Market Players |
|---|
| Danone SA |
| Groupe Lactalis S.A. |
| Arla Foods amba |
| Theo Müller Group |
| Nestlé SA |
| FrieslandCampina |
| Emmi Group |
| Fage International SA |
| Yoplait |
| Others |
Supply & Pricing Matrix
Cooperative-owned dairy networks across Germany, France, and the Netherlands anchor supply-side governance and enforce pricing discipline through captive milk collection. This ownership structure buffers margin volatility from farm-gate price swings while compressing pricing power for non-integrated processors competing on procurement spot markets.
Pricing Analysis
Input-cost pass-through from volatile farm-gate milk prices drives pricing dynamics across the European yogurt sector. Three-tier pricing structure across premium, standard, and economy levels separates Greek yogurt protein concentration from conventional stirred formats from private-label economy tiers. Price differentiation rests on live culture certification under EFSA Regulation 1924/2006 and organic accreditation. Cost compression in standard-tier plastic cup formats is intensifying because France's AGEC law imposes unrecoverable extended producer responsibility fees. Price-sensitive buyers concentrate in discount retail channels, while premium organic segments exhibit inelastic demand.
Supply Chain Analysis
Certification and qualification gating through EFSA health claim substantiation and REACH food-contact compliance shapes supplier准入 across European dairy processing. Milk supply concentrates in Germany, France, and the Netherlands through cooperative collection networks. Raw material dependencies include farm-gate milk, probiotic culture strains, and bio-based packaging resins. Single-source vulnerability runs through specialized fermentation equipment suppliers serving precision culture optimization. Distribution runs through temperature-controlled chilled chains anchored by supermarket retail infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the European yogurt sector is accelerating through protein premiumization in Greek formats and packaging cost-down shifts from plastic to recyclable alternatives. These drivers reward early movers with certified sustainable portfolios and EFSA-compliant health positioning.
For Market Incumbents: Hedge against plant-based substitution by securing oat and almond protein supply agreements in Scandinavian procurement zones. Deepen backward integration into bio-based packaging resin production to capture France AGEC compliance premiums before EU-wide harmonization. Anchor fermentation R&D scale against mid-tier processor technology convergence in the Netherlands and Belgium.
For New Entrants and Emerging Players: Capture white-space in online retail chilled delivery infrastructure for secondary German and French urban markets underserved by supermarket catchment areas. Target precision fermentation ingredient niches awaiting EFSA pre-submission validation through Wageningen University research partnerships. Pursue direct-to-consumer subscription models with documented live culture retention guarantees.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier cooperative processors lacking brand equity but holding captive milk supply in Normandy and Brittany networks. Long-term viability across the analysis window favors entities with EFSA-substantiated probiotic strain libraries and AGEC-compliant packaging upgrade pathways. Watch EFSA's evolving stance on novel fermentation-derived ingredients as the signal for regulatory white-space inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | EFSA-substantiated live culture retention commands shelf-space premiums in German retail. |
| Bio-Based Packaging Transition | France's AGEC law rewards early compliance with preferred retail listing terms. |
| Direct-to-Consumer Channel Expansion | Chilled delivery infrastructure unlocks geographic penetration beyond Paris and Munich catchments. |
| Plant-Based Production Asset Allocation | Oat and almond formulations displace conventional dairy in Amsterdam and Rotterdam retail sets. |
| Cooperative Milk Supply Consolidation | Backward integration into Normandy and Brittany networks buffers farm-gate price volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture supply-side and demand-side dynamics across European dairy processing. Primary fieldwork engaged fermentation technology directors, supermarket category buyers, cooperative procurement managers, and EFSA regulatory affairs specialists. Secondary validation drew from EU dairy market databases, EFSA health claim registers, customs trade records, and EU Green Deal implementation tracking. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Segment-weighting across product type, packaging material, distribution channel, and end-user categories structured the analytical framework. Growth trajectories derived from historical volume elasticities, price-premium absorption rates, and channel shift velocities. Forecast inputs incorporated farm-gate milk price volatility indices, EFSA substantiation pipeline status, and France AGEC compliance cost curves across the projection horizon.
Farm-gate price volatility, EFSA regulatory revision, and packaging mandate acceleration are the dominant revision risks for European yogurt market projections. Forecasts reflect assumptions on probiotic health claim permissibility and cooperative supply stability. A model refresh is warranted upon material change in EFSA's stance on novel fermentation-derived ingredients.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Textured Butter Market
Dairy Products
Sheep Milk Market
Dairy Products
United States Yogurt Market
Dairy Products
Organic Milk Protein Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Cheese Concentrate Market
Dairy Products
Drinkable Yogurt Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
Ultra High Temperature Milk Market
Dairy Products
Low Temperature Yogurt Market
Dairy Products
Butter and Margarine Market
Dairy Products
Flavoured Milk Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
Colombia Dairy Market
Dairy Products
Organic Cheese Powder Market