
 Dairy Free Yogurt Market | 2026-2036
Dairy Free Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Free Yogurt Market Analysis
Asset-light contract manufacturing and third-party co-packing is fragmenting competitive dynamics in dairy-free yogurt, allowing niche brands to scale without capital-intensive plant investments. Danone SA leverages its existing chilled-distribution infrastructure to secure retail placement across multiple continents. Forager Project LLC specializes in cashew-based formulations that command premium positioning in natural-channel sets. Oatly AB extends its oat-milk brand equity into adjacent cultured categories through controlled retail expansion.
Dairy free yogurt denotes a fermented, spoonable product manufactured from plant-derived substrates—typically coconut, almond, cashew, or oat bases—using live bacterial cultures at controlled temperatures to achieve target pH and viscosity. The product serves consumers seeking functional gut-health benefits without mammalian milk proteins or lactose. Coconut yogurt and almond yogurt together anchor the bulk of current retail velocity, though oat-based lines are gaining fastest as ingredient technology improves mouthfeel. Supermarkets dominate distribution-channel volume, while online retail captures the highest margin per unit through subscription and direct-to-consumer models.
The FDA governs allergen labeling and nutrient-content claims for U.S.-sold products, while the EU Green Deal shapes agricultural-input sourcing standards for European manufacturers. Health Canada and EFSA both scrutinize probiotic-strain substantiation, creating compliance friction for brands making digestive-health assertions. Stakeholders must monitor evolving protein-fortification standards and fermentation-process certifications as regulators tighten the boundary between conventional yogurt and plant-based alternatives.
Market Dynamics
Contract manufacturing networks are redistributing production capacity across the dairy-free yogurt sector, enabling niche brands to achieve national distribution without building captive fermentation facilities. This asset-light model compresses capital barriers while fragmenting competitive control over formulation IP.
Growth Catalysts
- EU Green Deal agricultural standards:The framework mandates deforestation-free supply chains for coconut and almond sourcing, accelerating certified ingredient procurement among European manufacturers seeking retail placement.
- Functional gut-health positioning:Live culture substantiation under EFSA and Health Canada guidelines drives probiotic strain investment, differentiating products in natural-channel sets where health claims command shelf space.
- Germany's retail density:Discounter and organic supermarket concentration creates concentrated demand pull for private-label and branded oat-based lines with clean-label positioning.
Market Restraints
- Coconut cream input volatility:Philippine and Indonesian harvest fluctuations expose margin structures to raw material cost swings without long-term contracting mechanisms.
- Almond water intensity:California aquifer stress and irrigation restrictions constrain supply scalability for almond-milk base formulations during drought cycles.
- FDA allergen-labeling friction:Tree nut and coconut disclosure requirements complicate cross-category branding strategies for multi-base portfolios.
Strategic Opportunities
- Australian foodservice penetration:Cafe and QSR chains in Sydney and Melbourne present underdeveloped channels for single-serve cultured oat products with barista-compatible texture profiles.
- Precision fermentation convergence:Dairy-identical protein synthesis via microbial hosts enables texture replication without allergen labeling, opening formulation white space.
- Subscription channel infrastructure:Direct-to-consumer cold-chain logistics investments by third-party platforms reduce customer acquisition costs for regional brands.
Industry Challenges
- Live culture stability expertise:Shelf-life extension without refrigeration requires specialized fermentation science talent scarce outside traditional dairy R&D centers.
- Organic certification timelines:Three-year land conversion periods for coconut and oat sourcing delay clean-label product launches and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Free Yogurt Market |
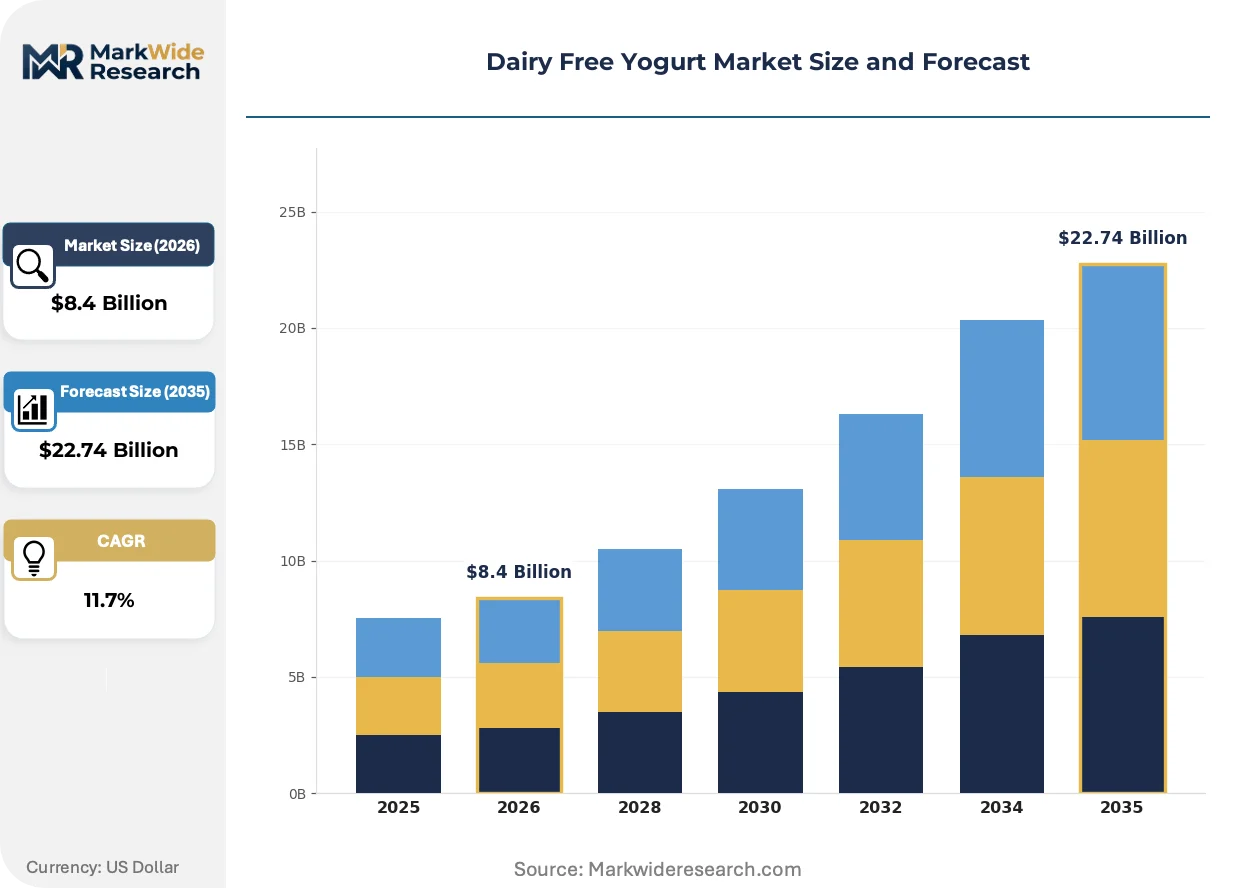
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Yogurt, Almond Yogurt, Cashew Yogurt, Soy Yogurt Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores Customer Type: Health Conscious Consumers, Vegans, Lactose Intolerant Individuals, Fitness Enthusiasts Flavor: Vanilla, Strawberry, Blueberry, Plain |
| Companies Covered | Chobani LLC, Kite Hill Inc., Danone SA, Good Karma Foods Inc., Forager Project LLC, The Hain Celestial Group, Nestlé SA, Oatly AB, General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Free Yogurt Market Emerging Trajectories
Texture engineering and culture stabilization protocols are converging to close the sensory gap between plant-based and conventional yogurt, reshaping where and how these products compete for refrigerated case space.
High-pressure processing of oat bases is rendering obsolete the starch-heavy, gummy mouthfeel that previously limited oat yogurt acceptance in mainstream retail sets. Natural-channel buyers in Germany and the United States are adopting these reformulated lines at rates that justify dedicated production runs. The technology is rendering obsolete first-generation oat yogurts that relied on viscosity modifiers rather than protein network development.
The FDA's updated nutrition-labeling rules for added sugars disclosure are forcing reformulation of sweetened coconut and almond bases previously dependent on cane sugar for flavor masking. Manufacturers must rebalance sweetness profiles using monk fruit, allulose, or fermentation-derived alternatives to maintain clean-label positioning. Children's and dessert-positioned segments face the steepest compliance costs and shortest reformulation timelines.
Buyers in the United States are consolidating purchases through retail subscription platforms that bypass traditional distributor markups and capture consumption data for personalized flavor recommendations. Natural-channel independents and direct-to-consumer startups are displacing conventional supermarket velocity as the primary growth engine. This channel rotation is most visible in coastal metropolitan clusters where cold-chain logistics density supports reliable home delivery.
Dairy Free Yogurt Market Segmentation
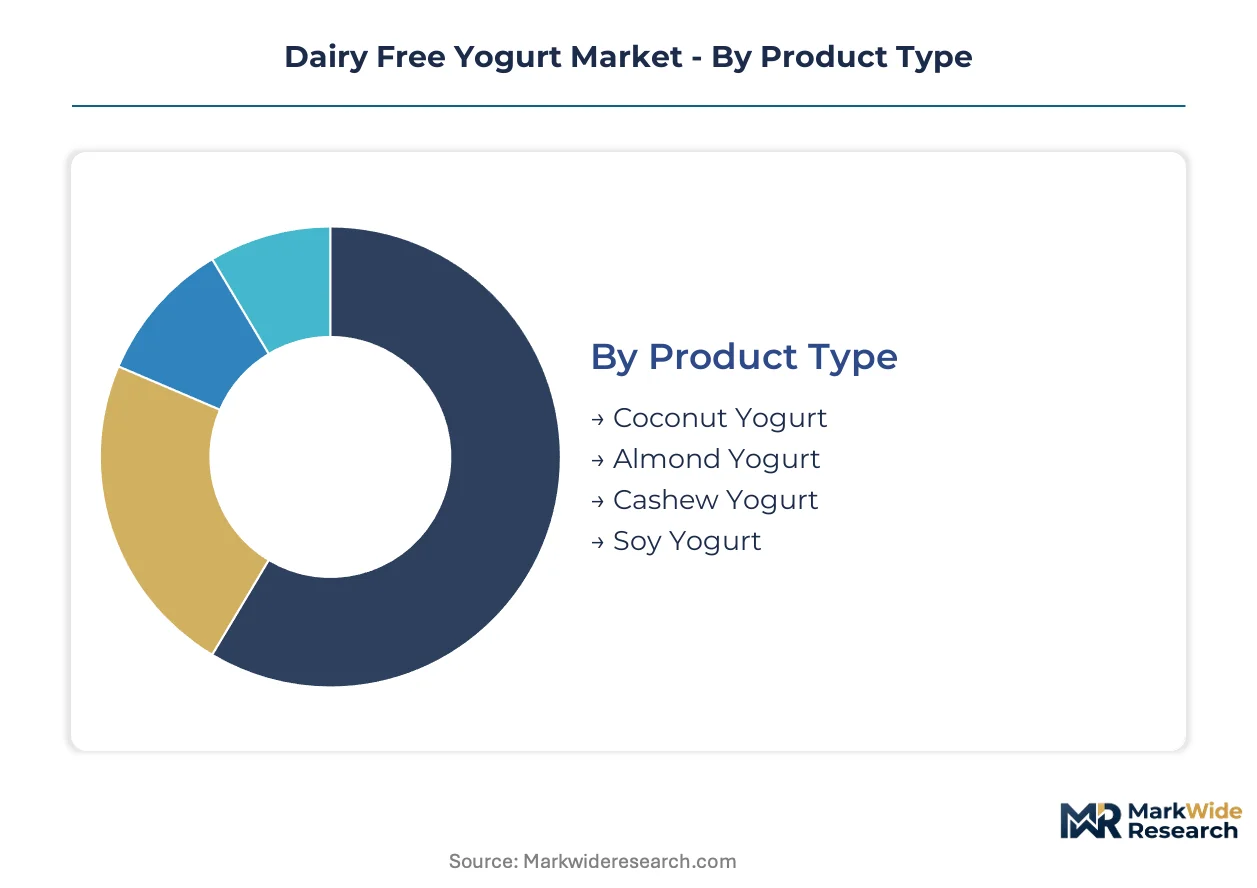
Plant-based yogurt manufacturers calibrate formulation investments and shelf-space negotiations around four distinct segmentation axes. Each dimension reveals divergent margin structures, regulatory exposure, and channel access requirements that shape portfolio prioritization.
Product Type:
Cost tier differentiation separates commodity substrates from premium-positioned bases requiring specialized fermentation science and ingredient sourcing.
- Coconut Yogurt:High-fat coconut cream substrates deliver the richest mouthfeel among plant-based alternatives, with Philippine and Indonesian supply chains dominating raw material procurement. German discounters and U.S. natural-channel sets concentrate demand for this established base, though EU Green Deal deforestation-free mandates are tightening supplier certification requirements.
- Oat Yogurt:High-pressure processing of oat bases eliminates the starch-heavy viscosity modifiers that previously limited mainstream acceptance, enabling protein network development that rivals conventional yogurt texture. Australian foodservice operators and U.S. coastal metropolitan buyers are adopting reformulated lines fastest as cold-chain subscription infrastructure matures.
- Almond Yogurt:California-sourced almond milk bases face irrigation constraint exposure during drought cycles, compressing margin stability for manufacturers without long-term contracting mechanisms.
- Cashew Yogurt:Premium cashew cream formulations command natural-channel positioning through superior fat-protein emulsion stability, though Vietnamese and Indian supply concentration creates procurement risk.
- Soy Yogurt:Mature soy protein isolate technology offers the lowest unit economics but carries allergen-labeling friction and clean-label headwinds in Western European markets.
Coconut yogurt commands the established base. The steepest expansion runs through oat yogurt.
Distribution Channel:
Application context determines refrigeration requirements, margin capture, and consumer data access across retail and foodservice touchpoints.
- Supermarkets:Chilled dairy case placement generates the highest absolute volume velocity, with slotting fees and promotional calendars dictating working capital intensity for emerging brands.
- Online Retail:Direct-to-consumer and third-party subscription platforms bypass traditional distributor markups while capturing consumption pattern data for personalized flavor recommendations.
- Health Food Stores:Natural-channel independents prioritize live culture substantiation and organic certification, filtering for probiotic strain investment and three-year land conversion compliance.
- Convenience Stores:Single-serve portability and ambient-stable formulations remain underdeveloped, with shelf-life extension science scarce outside traditional dairy R&D centers.
Supermarket velocity anchors current revenue. Online retail climbs the fastest as cold-chain logistics density improves.
Customer Type:
Volume concentration varies sharply across demographic segments with divergent price sensitivity and functional claim requirements.
- Health Conscious Consumers:Gut-health positioning and clean-label ingredient disclosure drive repeat purchase, with EFSA and Health Canada probiotic substantiation standards filtering product eligibility.
- Vegans:Ethical positioning demands extend to packaging sustainability and supply chain transparency, compressing margins through certification overhead.
- Lactose Intolerant Individuals:Medical necessity creates price-inelastic demand, though FDA allergen-labeling requirements complicate cross-category branding for multi-base portfolios.
- Fitness Enthusiasts:Protein-fortification standards and macronutrient transparency requirements are tightening as regulators distinguish conventional yogurt from plant-based alternatives.
Lactose-intolerant buyers provide the most stable demand base. Health-conscious consumers are gaining share fastest through subscription channel adoption.
Flavor:
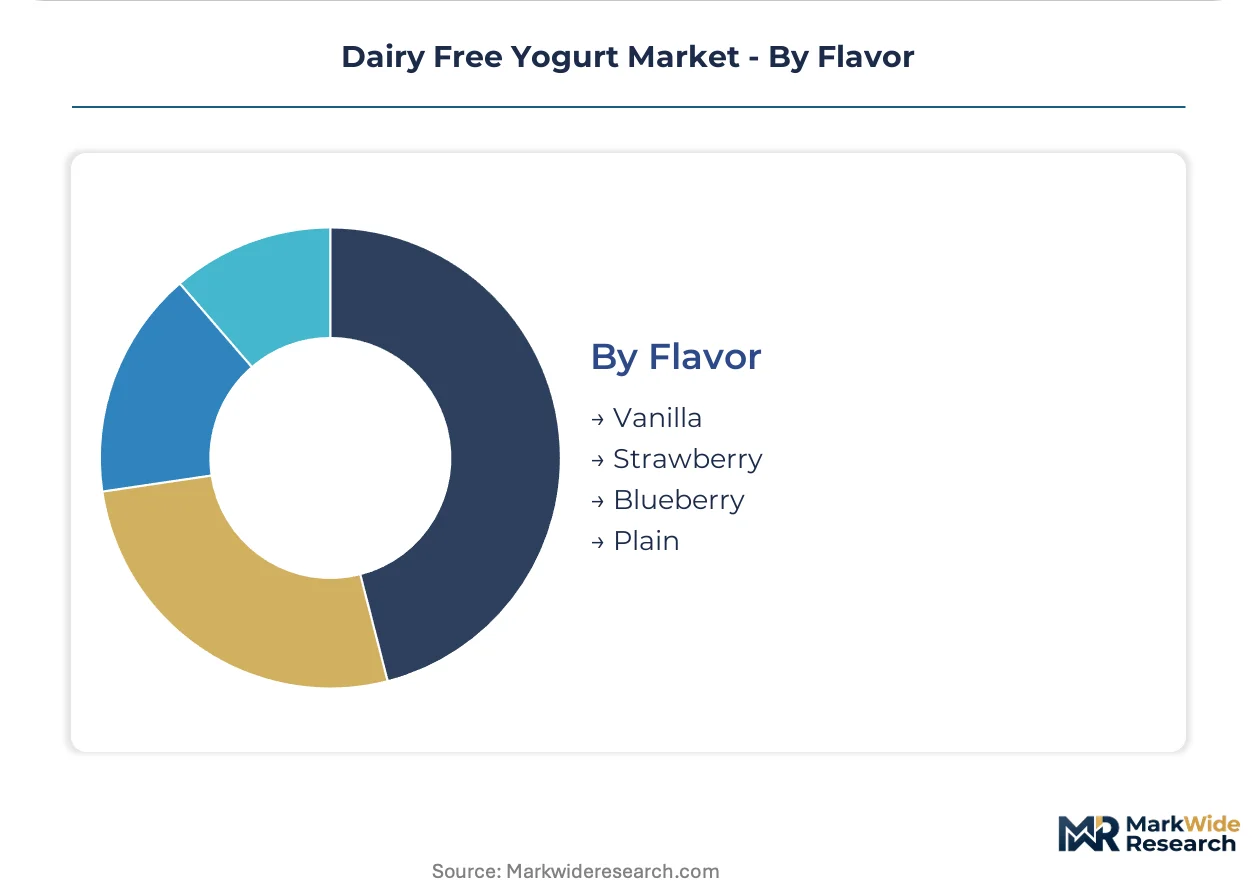
Maturity curves separate established varieties from emerging formulations facing reformulation pressure under evolving sugar disclosure rules.
- Plain:Unsweetened bases serve cooking applications and custom flavoring, with minimal regulatory exposure to added sugar disclosure requirements.
- Vanilla:Classic positioning faces steep FDA compliance costs as manufacturers rebalance sweetness profiles using monk fruit, allulose, or fermentation-derived alternatives to replace cane sugar masking.
- Strawberry:Children's segment concentration intensifies reformulation timeline pressure under updated nutrition-labeling rules.
- Blueberry:Dessert-positioned applications carry the highest sweetener dependency, with shortest runway for clean-label transition.
Plain varieties command the established base. Vanilla faces the steepest formulation transition as sugar disclosure tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German retail channels where discounter density compresses margins, while Australian foodservice operators capture premium positioning through cafe-chain partnerships. This asymmetry shapes where manufacturers allocate fermentation capacity and cold-chain investments.
Germany
Discounter concentration and organic supermarket penetration drive volume demand for oat-based private-label lines. The EU Green Deal mandates deforestation-free coconut and almond sourcing, accelerating certified supply chain audits. Berlin and Hamburg anchor reformulation R&D clusters where high-pressure processing adoption is fastest.
United States
Coastal metropolitan subscription adoption and natural-channel consolidation pull refrigerated case innovation. FDA updated nutrition-labeling rules for added sugars disclosure force monk fruit and allulose reformulation across sweetened vanilla and strawberry SKUs. California almond growers face irrigation constraints that compress base material scalability during drought cycles.
Australia
Sydney and Melbourne cafe chains present underdeveloped foodservice channels for barista-compatible oat yogurt textures. Health Canada-aligned probiotic substantiation standards filter product eligibility for gut-health claims in cross-border retail. Queensland cold-chain infrastructure investments enable direct-to-consumer subscription penetration into regional markets.
Canada
Lactose-intolerant consumer density in Ontario and Quebec sustains price-inelastic demand for coconut and almond bases. Health Canada scrutinizes live culture stability claims, creating compliance friction for brands without traditional dairy R&D heritage. Vancouver natural-channel independents prioritize organic certification and three-year land conversion compliance.
United Kingdom
Clean-label positioning and packaging sustainability demands compress margins through certification overhead in London and Southeast retail clusters. EFSA probiotic strain substantiation requirements differentiate shelf space in health food channels. Midlands distribution hubs handle EU-imported coconut cream substrates facing post-Brexit customs documentation.
Dairy Free Yogurt Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The dairy-free yogurt sector exhibits moderate consolidation where multinational food conglomerates leverage chilled-distribution infrastructure against asset-light contract manufacturers. Two strategic archetypes dominate: legacy dairy diversifiers extending brand equity into plant-based adjacencies, and venture-backed challengers scaling through co-packing networks without captive fermentation facilities. Competitive moves concentrate on retail slotting fee negotiations and precision fermentation technology licensing.
Within the legacy diversification tier, Danone SA and Nestlé SA exemplify multinational platform operators. Among challenger specialists, Forager Project LLC and Oatly AB occupy positions where cashew and oat base expertise anchors premium natural-channel placement. Chobani LLC sits within the mid-scale integrator archetype, bridging conventional yogurt manufacturing heritage with plant-based line extensions.
| Leading Market Players |
|---|
| Chobani LLC |
| Kite Hill Inc. |
| Danone SA |
| Good Karma Foods Inc. |
| Forager Project LLC |
| The Hain Celestial Group |
| Nestlé SA |
| Oatly AB |
| General Mills Inc. |
| Others |
Supply Flow & Price Mechanics
Philippine coconut cream harvest volatility determines both margin compression in premium tiers and the geographic diversification of fermentation capacity investments. Manufacturers without long-term contracting mechanisms face asymmetric exposure to raw material cost swings that reshape procurement priorities across oat and almond alternatives.
Pricing Analysis
Natural-channel buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the dairy-free yogurt sector. Price differentiation centers on organic certification status and live culture substantiation investment, with EFSA-compliant probiotic tiers commanding shelf-space premiums. Pricing pressure stems from California almond irrigation constraints compressing base material scalability during drought cycles. Discounter penetration in Germany represents the most price-sensitive segment, while Australian foodservice operators show the least sensitivity due to barista-compatible texture requirements.
Supply Chain Analysis
Extended payment terms from Philippine and Indonesian coconut processors strain working capital for manufacturers scaling oat-based lines. Raw material procurement draws from Vietnamese cashew concentrate, California almond milk solids, and Nordic oat protein isolates. Single-source vulnerability concentrates in Southeast Asian coconut cream supply chains facing EU Green Deal deforestation-free audit requirements. Distribution runs through chilled third-party logistics networks anchored in Berlin, Los Angeles, and Melbourne metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
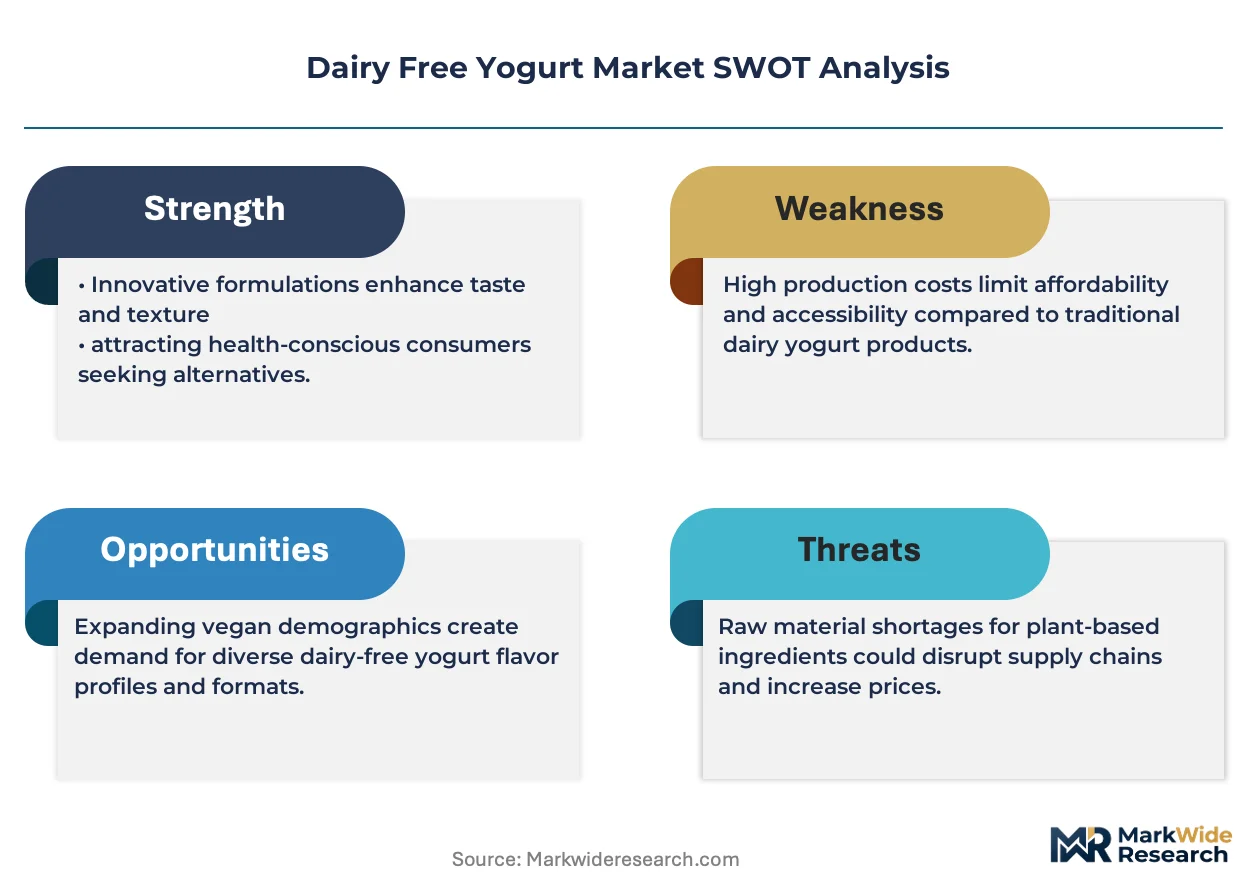
The dairy-free yogurt market sits in early-cycle expansion driven by precision fermentation convergence disrupting conventional texture replication economics. Australian foodservice penetration and subscription channel infrastructure investments signal sustained adoption tailwinds.
For Market Incumbents: Insulate formulation IP through captive precision fermentation licensing agreements before microbial-derived dairy proteins commoditize texture advantages. Secure long-term coconut cream offtake contracts in the Philippines to hedge against EU Green Deal supply chain audit disruptions. Channel control through direct-to-consumer cold-chain investments represents the critical defensive lever against subscription platform disintermediation. For New Entrants and Emerging Players: Mid-market oat yogurt SKUs in Australian cafe chains represent the most penetrable entry point given underdeveloped barista-compatible texture supply. Precision fermentation partnerships enabling dairy-identical protein synthesis without allergen labeling open formulation white space unavailable to legacy cashew and coconut specialists. A co-packing-first go-to-market model bypasses capital-intensive fermentation facility requirements while testing product-market fit. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors precision fermentation platform specialists over established base-material processors. Long-term viability across the next decade hinges on microbial protein synthesis capabilities that transcend agricultural input constraints. The signal to watch is Health Canada and FDA probiotic strain substantiation rulings that will filter eligible acquisition targets by compliance infrastructure depth.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Licensing | Microbial-derived dairy proteins enable texture replication without coconut or almond supply exposure. |
| Direct-to-Consumer Cold-Chain Buildout | Subscription platform investments capture margin bypassed by traditional distributor markups in coastal metros. |
| EU Green Deal Supply Certification | Deforestation-free coconut sourcing audits secure retail placement in German discounter and organic channels. |
| High-Pressure Processing Adoption | Oat base texture engineering eliminates starch-heavy viscosity modifiers previously limiting mainstream acceptance. |
| Probiotic Strain Patent Portfolio | Live culture substantiation under EFSA and Health Canada guidelines differentiates shelf space in natural-channel sets. |
Methodological Framework
Operator-level perspectives from fermentation scientists, chilled-distribution logistics directors, natural-channel category buyers, and contract manufacturing executives anchored the qualitative base. Secondary validation drew from FDA nutrition-labeling filings, EU Green Deal agricultural standard updates, Health Canada probiotic substantiation guidelines, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category spend analysis across the projection horizon.
Scenario-bracketing around coconut cream input volatility, precision fermentation technology maturation, and subscription channel penetration rates shaped the analytical framework. Segmentation dimensions spanned substrate type, distribution channel, customer archetype, and flavor positioning across the modeling period. CAGRs derived from iterative reconciliation of manufacturer capacity announcements, retail shelf-space expansion signals, and ingredient technology adoption curves. Forecast inputs incorporated EU Green Deal compliance timelines and high-pressure processing equipment deployment trajectories.
Practitioners should monitor Philippine harvest fluctuations, FDA added-sugar disclosure enforcement, and precision fermentation regulatory classification for early signals. Forecasts reflect assumptions around cold-chain logistics density improvements and probiotic strain stability science advancement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Dairy-Free Ice Creams Market
Dairy Alternatives
United Kingdom Dairy Alternatives Market
Dairy Alternatives
North America Non-Dairy Milk Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
Dairy-Free Chocolate Market
Dairy Alternatives
Walnut Milk Market
Dairy Alternatives
Legumes Plant-Based Milk Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
United States Non-Dairy Milk Market