
 Cheese Alternative Market | 2026-2036
Cheese Alternative Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Alternative Market Outlook
Coconut oil is consolidating its position as the dominant fat base in cheese alternative formulations, displacing partially hydrogenated oils across premium and mid-tier product lines. Daiya Foods Inc. leverages large-scale manufacturing in North America to anchor supply for retail and foodservice channels. Violife Foods competes through specialized allergen-free formulations that dominate European shelf space. Miyoko's Creamery differentiates via cultured cashew processes that extend product complexity beyond basic analogs.
Cheese alternatives comprise formulated food products designed to replicate the functional properties—meltability, stretch, and mouthfeel—of dairy cheese using plant-derived proteins, oils, and fermentation-derived flavor compounds, typically containing 15-30% fat content and protein bases from nuts, legumes, or starches. These products serve lactose-intolerant consumers, vegan populations, and flexitarian households seeking sensory parity with conventional cheese. Cream cheese alternatives lead residential adoption due to spreadable convenience and breakfast application breadth, while mozzarella analogs capture the fastest growth within foodservice as pizza chains expand plant-based menus. Shreddable textures command margin concentration in retail given processing complexity and consumer willingness to pay for performance in hot applications.
The FDA governs allergen disclosure and identity standards for cheese alternatives sold in the United States, while EFSA and EU Green Deal frameworks shape ingredient sustainability claims and packaging requirements across Europe. REACH compliance for flavor additives and FDA enforcement on dairy terminology restrictions directly constrain labeling freedom and reformulation costs for manufacturers. Stakeholders must monitor evolving precision fermentation regulations and cultured protein approval timelines, as these technologies threaten to bypass conventional plant-based processing entirely.
Market Dynamics
Coconut oil's displacement of partially hydrogenated oils across cheese alternative formulations is compressing reformulation timelines and redrawing supplier hierarchies in fat base procurement.
Growth Catalysts
- EFSA allergen-labeling mandates:Tightened disclosure requirements across the EU are forcing foodservice operators to expand plant-based menu placements, directly expanding distribution channels for cheese alternatives.
- Cashew protein processing:Advances in enzymatic hydrolysis of cashew proteins are improving meltability profiles, enabling premium positioning in shredded and sliced formats.
- German retail concentration:Clean-label preferences in German supermarkets are consolidating shelf space for coconut oil-based formulations with minimal ingredient lists.
Market Restraints
- Cashew supply concentration:Vietnam and India control over 80% of raw cashew processing, exposing European and North American manufacturers to price volatility and geopolitical disruption.
- FDA dairy terminology restrictions:Enforcement actions against "cheese" labeling limit consumer recognition and force costly rebranding campaigns for established products.
- Protein functionality gaps:Current legume and starch bases fail to replicate casein's stretch properties in high-heat applications, constraining pizza and grilling segments.
Strategic Opportunities
- United States foodservice expansion:Pizza chain plant-based menu rollouts are creating dedicated mozzarella analog demand that exceeds current shred-capacity supply.
- Precision fermentation regulatory clarity:EFSA and FDA approval timelines for animal-free casein proteins threaten to bypass conventional plant-based processing entirely.
- Direct-to-foodservice distribution:Bypassing retail brokerage fees through specialized foodservice distributors is capturing margin in institutional and QSR channels.
Industry Challenges
- Fermentation scale-up expertise:Cultured cashew and precision dairy protein processes require specialized bioprocess engineers scarce in conventional food manufacturing.
- REACH flavor additive compliance:Novel fermentation-derived flavor compounds face 12-18 month safety assessment timelines, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Alternative Market |
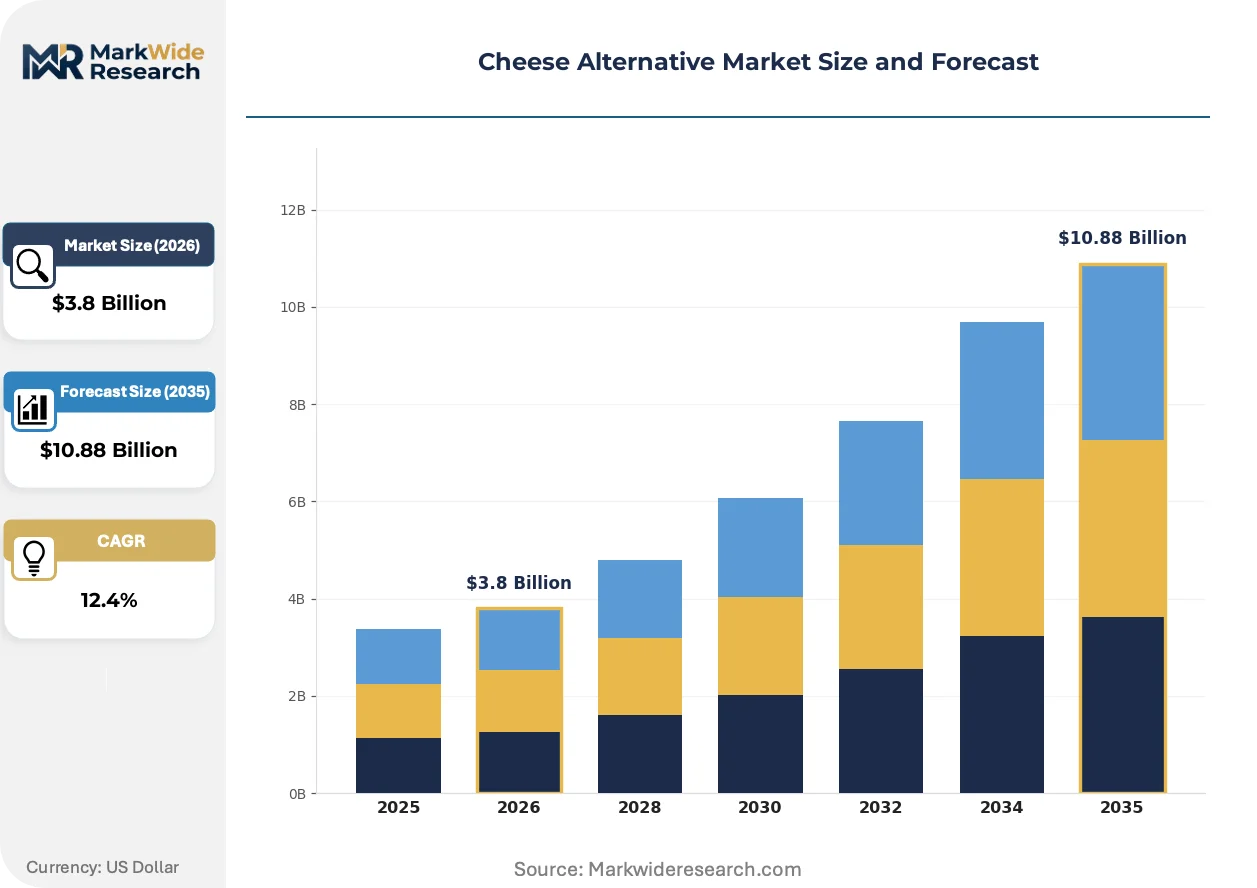
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream Cheese, Cheddar, Mozzarella, Parmesan Ingredient Source: Coconut Oil, Almonds, Cashews, Soy End User: Residential, Foodservice, Retail, Industrial Texture: Spreadable, Shreddable, Sliced, Block |
| Companies Covered | Daiya Foods Inc., Violife Foods, Kite Hill, Follow Your Heart, Miyoko's Creamery, Treeline Cheese, Tofutti Brands Inc., Parmela Creamery, Good Planet Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Alternative Market Strategic Shifts
Bioprocess engineering is converging with traditional food manufacturing, blurring boundaries between dairy, plant-based, and fermentation-derived production systems.
Precision fermentation for animal-free casein and whey proteins is converging with conventional extrusion technologies to enable stretch and melt properties previously unattainable in plant-based formats. Specialty cheese alternative manufacturers in the Netherlands and California are piloting hybrid processes that combine microbial proteins with coconut fat matrices. This convergence is compressing the performance gap between dairy and plant-based cheese, threatening to obsolete basic analog formulations within premium segments.
REACH compliance requirements for novel flavor additives are extending development timelines and consolidating reformulation capabilities among larger manufacturers with dedicated regulatory affairs teams. The European Chemicals Agency's expanded safety data requirements for enzymatically modified lipids are disproportionately affecting mid-tier producers dependent on external flavor houses. German and French manufacturers are responding by vertically integrating fermentation-derived flavor production to control disclosure documentation.
Flexitarian households are compressing purchase cycles for cheese alternatives, treating plant-based options as rotational rather than replacement purchases. Retailers in the United Kingdom and United States are responding with smaller-format, multi-SKU variety packs that reduce trial risk. This pattern is most visible in cream cheese alternatives, where breakfast application breadth supports higher purchase frequency than block or shred formats.
Cheese Alternative Market Segmentation
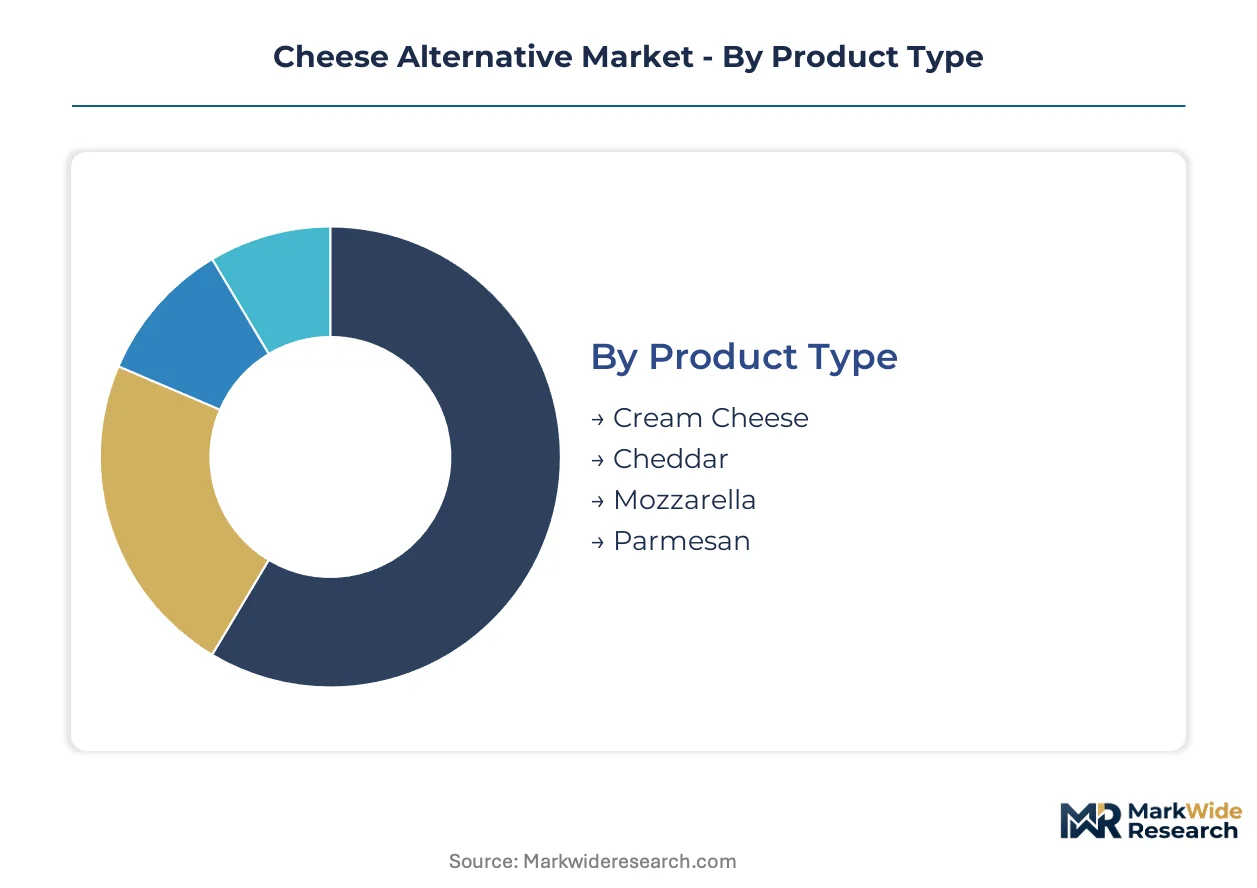
Cheese alternative manufacturers configure product portfolios across four intersecting dimensions that determine margin capture and channel access. Each segmentation axis carries distinct technical requirements, regulatory exposure, and pricing power that shape competitive positioning.
Product Type:
Cream cheese alternatives function as standalone spreads with minimal processing complexity, while shred and slice formats embed into complex foodservice workflows demanding performance parity.
- Cream Cheese:Formulated with 15-25% coconut oil fat content and stabilizer systems for cold spreadability. Residential breakfast applications in the United States and Germany concentrate demand, with flexitarian households treating these as rotational dairy substitutes. Clean-label ingredient lists under ten components command shelf space premiums.
- Mozzarella:Engineered for meltability and stretch in high-heat applications using modified starch and protein blends. Pizza chain rollouts across North American foodservice are outpacing shred-capacity supply, creating dedicated production line investments. Stretch property gaps versus dairy casein remain the primary technical constraint.
- Cheddar:Sharp flavor profiles rely on fermentation-derived compounds and annatto coloring for visual authenticity. Block formats dominate retail deli sections.
- Parmesan:Grated and shaved textures target pasta finishing applications with lower volume throughput than melt formats.
Cream cheese leads volumes today; mozzarella is gaining share fastest.
Ingredient Source:
Cost tier stratification separates premium nut-based formulations from commodity oil and legume alternatives, with fat base selection directly determining flavor profile and regulatory complexity.
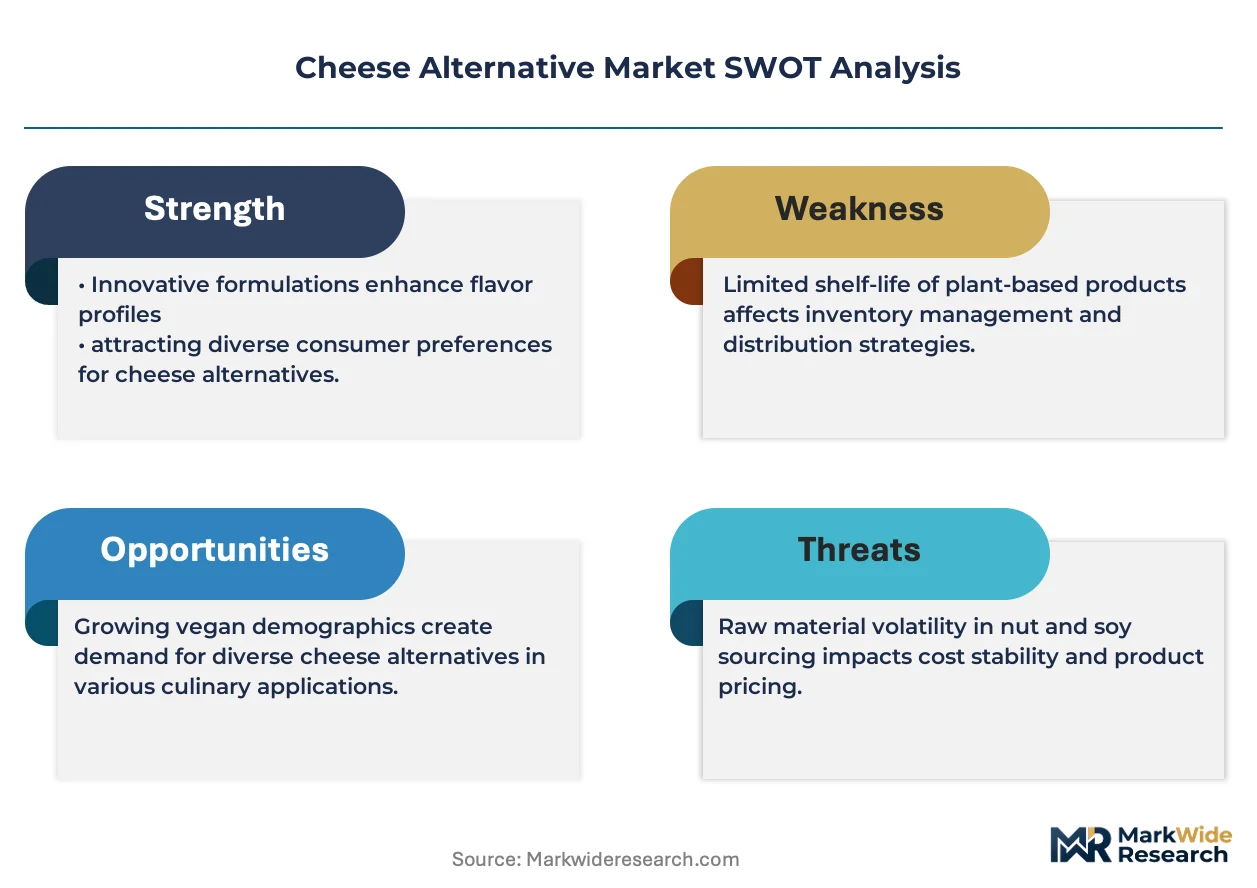
- Coconut Oil:Saturated fat content above 80% provides solid fat functionality without hydrogenation, displacing partially hydrogenated oils across mid-tier and premium lines. REACH compliance for refined coconut derivatives adds documentation burden for European manufacturers.
- Cashews:Enzymatic hydrolysis advances are improving protein functionality for shred and slice applications. Vietnam and India processing concentration exposes supply chains to price volatility and geopolitical disruption.
- Almonds:California cultivation bases support North American manufacturing with water-usage sustainability scrutiny.
- Soy:Lowest-cost protein base with established allergen labeling requirements under FDA and EFSA frameworks limiting foodservice placement flexibility.
Coconut oil anchors the largest volume position; cashew formulations are climbing the fastest.
End User:
Customer type determines packaging format, order minimums, and technical service intensity, with foodservice requiring specialized distributor relationships and residential favoring retail brokerage channels.
- Foodservice:Institutional and QSR channels demand case quantities with consistent melt performance specifications. Direct-to-foodservice distribution bypasses retail brokerage fees, capturing margin in pizza and sandwich chain supply agreements. Allergen disclosure mandates under EFSA are accelerating menu placement expansion.
- Residential:Supermarket and e-commerce channels favor smaller-format SKUs with variety pack configurations that reduce trial risk for flexitarian purchasers.
- Retail:Deli counter and specialty cheese case placement requires refrigerated supply chain investment and slotting fee negotiations.
- Industrial:Ingredient supply to processed food manufacturers demands bulk pricing and customized functional specifications.
Foodservice channels are expanding most quickly; residential maintains the volume base.
Texture:
Processing complexity and equipment capital requirements stratify margin capture, with shreddable formats demanding extrusion and cooling tunnel investments that block mid-tier entrants.
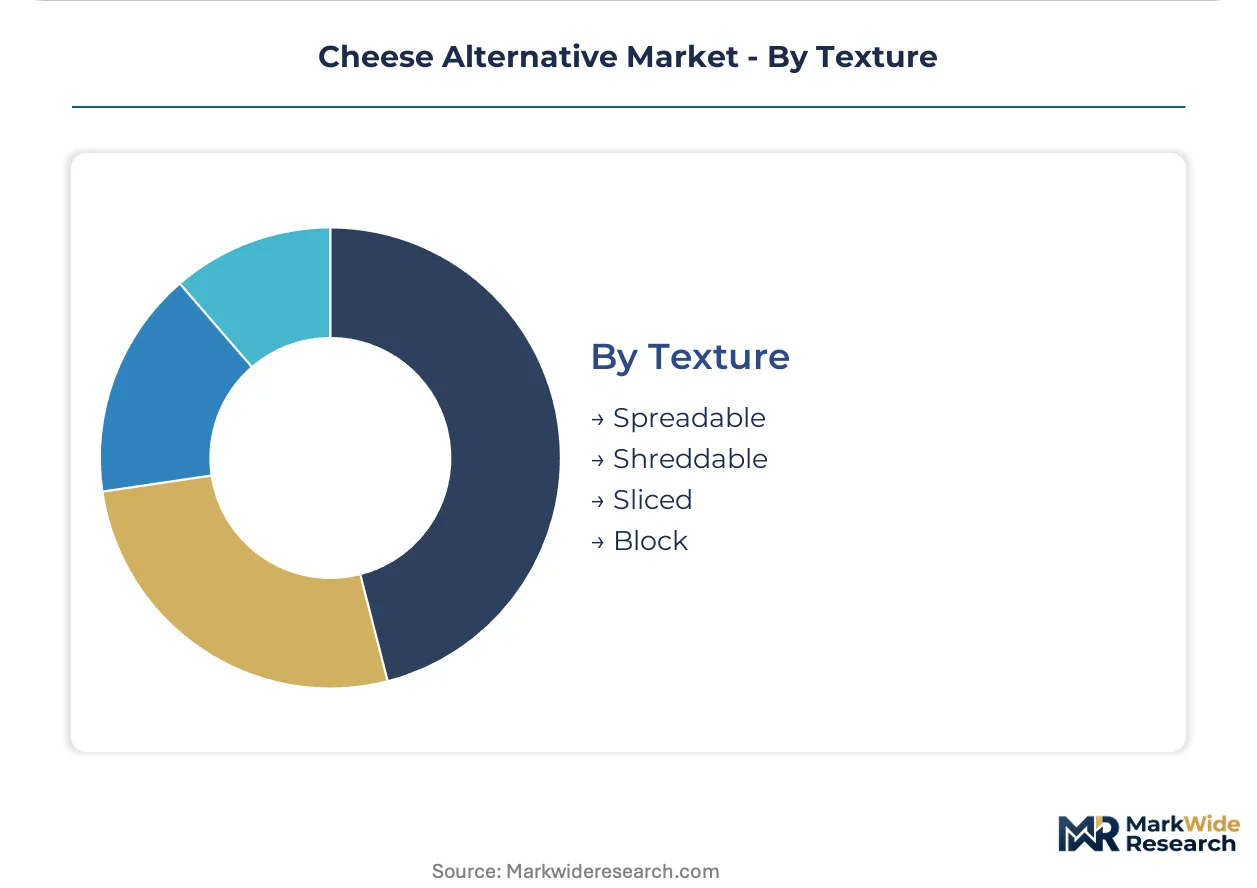
- Shreddable:Extruded strand formation with modified tapioca or potato starch binding systems enables hot-application performance. Shred-capacity supply constraints in North American foodservice are supporting price premiums above block and spread formats.
- Spreadable:Cold-process emulsification with hydrocolloid stabilization requires lower capital investment, enabling private-label proliferation.
- Sliced:Precision cutting and interleaving equipment for sandwich applications with specific thickness tolerances.
- Block:Molded and pressed formats for deli slicing and consumer portioning with minimal processing differentiation.
Spreadable textures dominate current volume; shreddable formats show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retail concentration anchors cheese alternative demand through clean-label supermarket chains and specialized organic distributors. Regulatory frameworks in five countries reshape ingredient sourcing and product positioning across distinct consumer bases.
United States
Pizza chain plant-based menu rollouts drive mozzarella analog demand beyond current shred-capacity supply. FDA enforcement on dairy terminology restrictions forces costly rebranding for established products. California-based precision fermentation startups pilot hybrid processes combining microbial proteins with coconut fat matrices.
Germany
Clean-label preferences concentrate demand for coconut oil-based formulations with minimal ingredient lists under EFSA allergen-labeling mandates. REACH compliance requirements for refined coconut derivatives add documentation burden for domestic manufacturers. Berlin and Hamburg host specialized distributors expanding direct-to-foodservice channels for institutional clients.
United Kingdom
Flexitarian households compress purchase cycles through smaller-format variety packs reducing trial risk. EFSA frameworks shape ingredient sustainability claims and packaging requirements across retail channels. London-based retailers anchor multi-SKU breakfast application placements for cream cheese alternatives.
Netherlands
Specialty manufacturers pilot bioprocess engineering convergence between dairy, plant-based, and fermentation-derived production systems. ECHA expanded safety data requirements for enzymatically modified lipids affect mid-tier producers. Dutch clusters near Wageningen develop vertically integrated fermentation-derived flavor production.
Canada
Health Canada allergen disclosure standards tighten foodservice operator procurement specifications. Pacific Northwest supply chain linkages connect Vancouver distributors to California precision fermentation feedstocks. Toronto and Montreal retail consolidation favors premium nut-based formulations with established cold-chain infrastructure.
Cheese Alternative Market Competitive Environment
Global majors compete with regional champions across formulation complexity and channel access. The vendor base stratifies between scale-driven manufacturers with dedicated foodservice supply agreements and specialized allergen-free formulators capturing premium retail positioning. Three archetypes dominate: coconut oil-based mass-market suppliers, cultured cashew premium specialists, and precision fermentation technology developers. Capacity expansion in shred-format production lines and backward integration into flavor compound manufacturing represent the dominant competitive moves reshaping supplier hierarchies.
Within the North American scale-driven tier, Daiya Foods Inc. anchors large-scale manufacturing supply for retail and foodservice channels. Violife Foods exemplifies the European allergen-free specialist archetype dominating continental shelf space. Miyoko's Creamery occupies a position within the cultured process premium segment extending product complexity beyond basic analogs.
| Leading Market Players |
|---|
| Daiya Foods Inc. |
| Violife Foods |
| Kite Hill |
| Follow Your Heart |
| Miyoko's Creamery |
| Treeline Cheese |
| Tofutti Brands Inc. |
| Parmela Creamery |
| Good Planet Foods |
| Others |
Value Chain & Pricing Dynamics
Captive supply of coconut oil refining anchors both procurement security and margin capture for cheese alternative manufacturers, with backward integration into fat base processing insulating premium tier producers from Vietnamese and Indian cashew price swings that compress mid-tier economics.
Pricing Analysis
Input-cost pass-through from coconut oil and cashew protein bases shapes contract structures across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates cultured cashew formulations with fermentation-derived complexity from commodity oil-starch blends. Price differentiation hinges on clean-label ingredient counts and EFSA allergen compliance certification. Cost compression in economy tiers is intensifying because soy-based alternatives face FDA dairy terminology enforcement that forces costly rebranding. Foodservice buyers exhibit highest price sensitivity due to volume scale procurement, while specialty retail channels absorb premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with Vietnam and India for raw cashew processing, where over 80% concentration exposes European and North American formulators to geopolitical disruption and harvest volatility. Coconut oil supply draws from Philippines and Indonesia plantation networks, with refined derivative production clustering in Malaysia and Thailand. REACH compliance documentation for enzymatically modified lipids creates regulatory friction that lengthens European procurement cycles. Distribution runs through specialized foodservice distributors bypassing retail brokerage, with direct-to-institutional channels capturing margin in pizza chain and QSR supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cheese alternative manufacturing operates as a geographic-arbitrage play between German clean-label retail premiums and United States foodservice volume scale, with EFSA allergen mandates tightening faster than FDA enforcement to create regulatory cost differentials.
For Market Incumbents: Deepen backward integration into fermentation-derived flavor compound production to control REACH documentation timelines that delay mid-tier competitors. Expand shred-capacity production lines in North American manufacturing clusters to capture dedicated mozzarella analog demand from pizza chain rollouts. Precision fermentation startups threaten to bypass conventional plant-based processing entirely as EFSA and FDA approval timelines clarify. For New Entrants and Emerging Players: The 40-60% price-point gap between premium cultured cashew formulations and economy oil-starch blends opens white-space targeting at the mid-tier intersection of clean-label positioning and accessible pricing. German supermarket chains and United Kingdom flexitarian households represent the most penetrable demand clusters. Direct-to-foodservice distribution bypassing retail slotting fees offers the strongest go-to-market angle for shred-format specialization. For Investors and Strategic Acquirers: Roll-up economics work for regional coconut oil-based manufacturers with established foodservice supply agreements because EFSA allergen-labeling mandates are accelerating menu placement expansion that outpaces organic growth capacity. Five-to-ten year viability hinges on positioning ahead of precision fermentation scale-up. The signal to watch is EFSA and FDA animal-free casein approval timelines that would obsolete basic plant-based analogs in premium segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flavor Production | REACH compliance control accelerates European product launches versus external flavor house dependencies. |
| Shred-Capacity Production Expansion | Pizza chain plant-based menu rollouts in North America outpace current supply, supporting price premiums. |
| Direct-to-Foodservice Distribution Buildout | Bypassing retail brokerage fees captures margin in institutional and QSR channel supply agreements. |
| Precision Fermentation Partnership | Hybrid microbial protein-coconut fat processes threaten to obsolete basic analog formulations in premium tiers. |
| Clean-Label Certification Investment | EFSA allergen-labeling mandates tighten disclosure requirements that favor minimal-ingredient list positioning. |
Study Parameters
Multiple input streams — primary interviews with plant-based R&D directors, foodservice procurement managers, and specialty distributor executives; secondary validation through FDA enforcement actions, EFSA guidance documents, and REACH compliance databases; customs and trade flow data for coconut oil and cashew kernel movements — were reconciled through bottom-up volume modeling and top-down value triangulation.
Cross-referencing historical shipment patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, ingredient source, end-user channel, and texture format, with CAGRs derived from elasticity-adjusted demand curves and capacity expansion timelines. Forecast inputs incorporated pizza chain menu rollout schedules and precision fermentation regulatory approval pathway monitoring.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation-derived casein proteins would alter the outlook if EFSA and FDA approvals accelerate beyond baseline assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Europe Non-Dairy Cheese Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Cashew Milk Market
Dairy Alternatives
Dairy-Free Creams Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Legumes Plant-Based Milk Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
Almond Milk Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market