
 Europe Non-Dairy Yogurt Market | 2026-2036
Europe Non-Dairy Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Non-Dairy Yogurt Market Insights
Supermarket dairy aisles across Europe is tilting toward dedicated plant-based refrigerated sections, forcing traditional yogurt brands to defend shelf space. Danone S.A. leverages its European cold-chain infrastructure to anchor distribution in France and Germany. Oatly Group AB competes through barista-grade brand recognition that extends into yogurt adjacent categories. Valio Ltd. differentiates via fermented oat expertise developed through Nordic dairy heritage.
Europe non-dairy yogurt comprises fermented plant-based milk preparations, typically containing live bacterial cultures and achieving protein contents between 1.5 and 5 grams per 100 grams depending on base ingredient. Manufacturers employ enzymatic treatment and controlled fermentation at 40 to 45 degrees Celsius to develop texture and acidity profiles mimicking conventional yogurt for commercial foodservice and retail applications. Almond and coconut bases lead volume due to established consumer familiarity, while cashew formulations capture premium margin pools through creamier mouthfeel positioning. Soy-derived variants sustain mature demand among allergen-aware buyers despite taste limitations relative to newer alternatives.
EFSA nutritional labeling requirements and EU Green Deal sustainability frameworks shape ingredient transparency mandates across member states, while REACH chemical safety standards govern additive approvals in plant-based formulations. Germany's BfR and France's DGCCRF enforce divergent national interpretation layers atop harmonized EU rules, complicating cross-border formulation strategies. Stakeholders must monitor evolving protein content claim thresholds and carbon footprint disclosure obligations that will determine which formulations retain shelf access.
Market Dynamics
EFSA protein content claim thresholds and EU Green Deal carbon disclosure mandates are forcing manufacturers to reformulate across multiple base ingredients simultaneously, compressing R&D timelines and raising compliance costs for mid-tier producers.
Growth Catalysts
- EU Green Deal sustainability frameworks:Mandatory carbon footprint disclosure obligations are accelerating clean-label investments and favoring domestically sourced oat supply chains over imported coconut bases.
- Germany's BfR enzymatic approval pathways:Streamlined additive safety assessments for fermented oat textures are reducing time-to-market for novel mouthfeel formulations targeting foodservice channels.
- Almond and coconut base familiarity:Established consumer recognition in France and the United Kingdom is sustaining repeat purchase rates while newer entrants build trial.
Market Restraints
- Input cost volatility:Almond water intensity and Spanish drought exposure are compressing margin stability for producers dependent on Mediterranean sourcing.
- Supply concentration risk:Nordic oat processing infrastructure dominates enzymatic treatment capacity, creating single-point vulnerability for texture-critical formulations.
- REACH additive friction:Divergent national interpretations of chemical safety standards between Germany's BfR and France's DGCCRF are forcing redundant testing protocols.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland and Romania show nascent refrigerated plant-based section development with limited local production capacity.
- CSRD supply chain disclosure mandates:Early compliance with corporate sustainability reporting requirements positions premium brands for institutional procurement contracts.
- Precision fermentation convergence:Integration of biomass fermentation with traditional enzymatic treatment is enabling protein content claims that meet EFSA thresholds without soy bases.
Industry Challenges
- Fermentation microbiology talent scarcity:Cross-training dairy culture specialists for plant-based substrate management requires 18-24 month capability development cycles.
- Cold-chain capex intensity:Dedicated refrigerated distribution for live culture products demands infrastructure investment that disadvantages smaller regional entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Non-Dairy Yogurt Market |
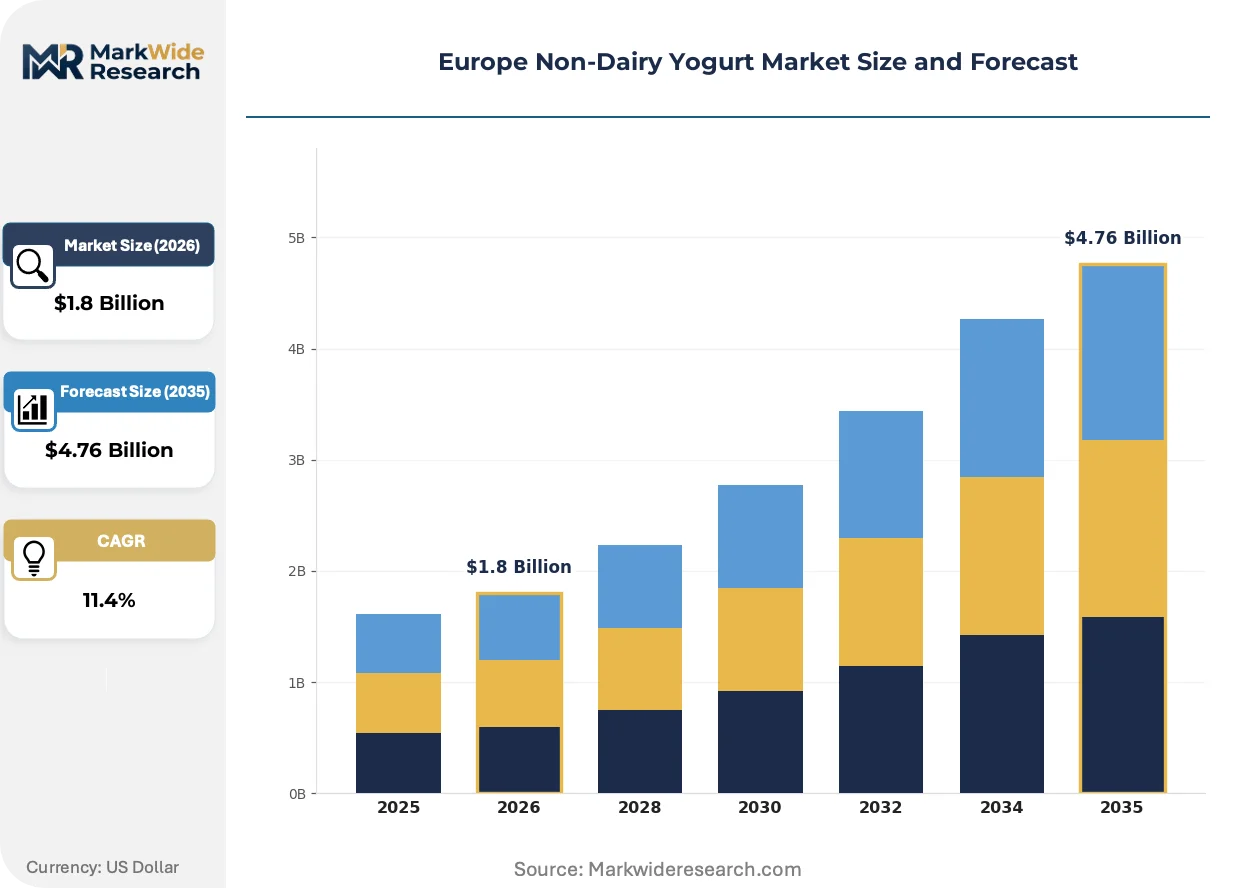
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut, Almond, Soy, Cashew End User: Health-Conscious Consumers, Vegans, Lactose Intolerant Individuals, Athletes Packaging Type: Plastic Cups, Glass Jars, Pouches, Family Size Containers Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Restaurants |
| Companies Covered | Danone S.A., Oatly Group AB, The Hain Celestial Group Inc., Valio Ltd., Valsoia SpA, Blue Diamond Growers, Triballat Noyal, Andros Group, Nestlé S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Non-Dairy Yogurt Market Trends and Innovations
Texture engineering and regulatory disclosure requirements are converging to reshape competitive positioning, with protein claim legitimacy and carbon transparency emerging as the primary axes of differentiation.
High-pressure processing is collapsing the traditional trade-off between extended shelf stability and live culture viability. German and French retail buyers are adopting HPP-treated skyr-style oat formulations at twice the rate of conventional pasteurized alternatives. This technology is collapsing distribution radius limitations that previously constrained regional brands to local markets.
EFSA nutritional labeling requirements are tightening protein content claim thresholds across member states. Manufacturers must now substantiate gram-per-serving declarations with validated amino acid profiles rather than crude nitrogen measurements. Soy-derived variants in allergen-aware segments face the steepest reformulation pressure as they attempt to maintain claim eligibility against rising analytical standards.
Buyer concentration in German and French supermarket chains is compressing supplier negotiation cycles and unbundling traditional slotting fee structures. Discounters Aldi and Lidl are demanding direct sourcing relationships that bypass established dairy distributor networks. This pattern is most visible in the United Kingdom, where Tesco and Sainsbury's private-label plant-based lines now capture one-third of refrigerated shelf space.
Europe Non-Dairy Yogurt Market Segmentation
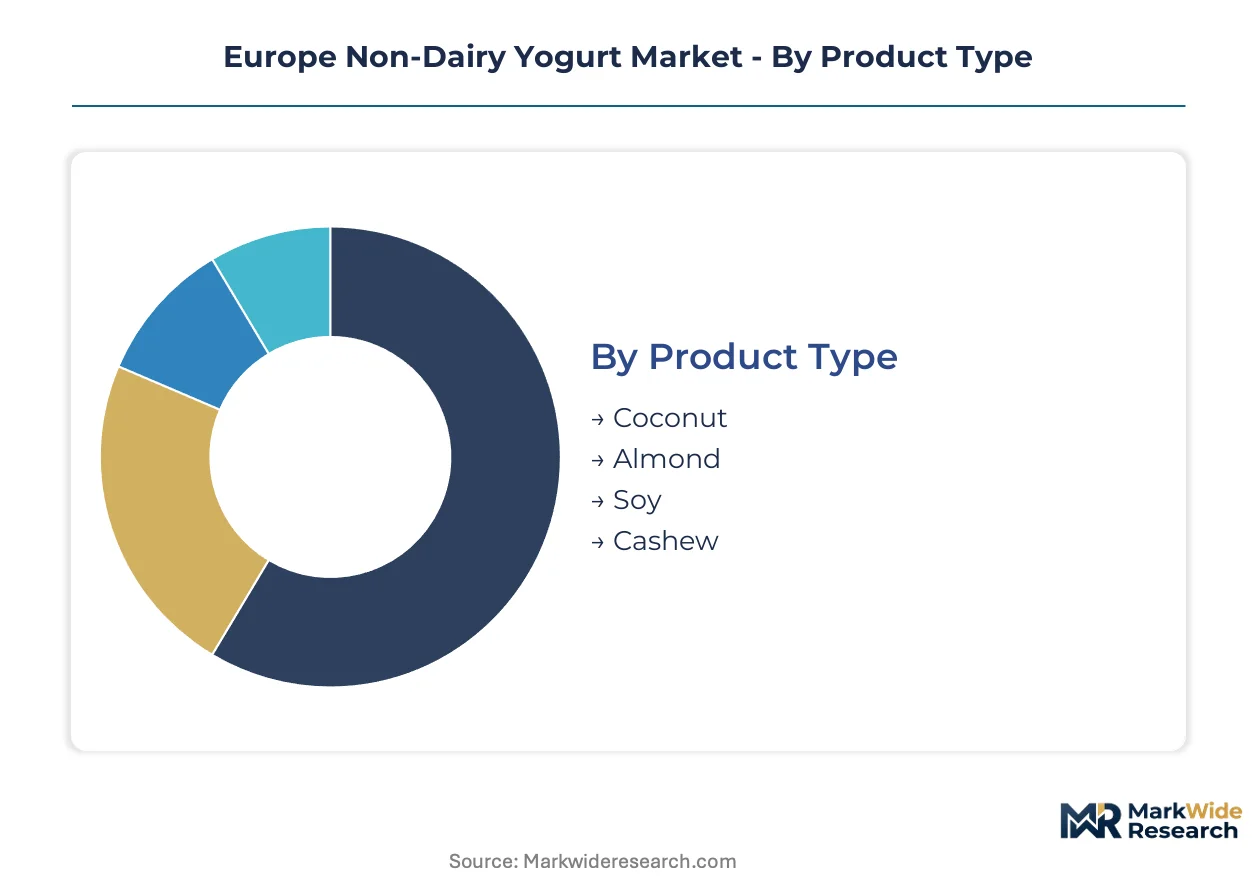
Segmentation in the Europe non-dairy yogurt market reveals how texture engineering, protein claim thresholds, and cold-chain requirements create divergent margin structures across product formats and buyer profiles. Manufacturers must align formulation investments with specific channel access rules and end-user willingness to pay for clean-label positioning.
Product Type:
After-sales service intensity varies sharply by base ingredient, as enzymatic treatment failures and fermentation inconsistency drive disproportionate customer support demands for novel formulations versus established alternatives.
- Almond:Formulations achieve protein contents between 1.5 and 3 grams per 100 grams through controlled enzymatic treatment of blanched nut bases. German and French retail buyers favor almond-derived lines for their established consumer familiarity, though Spanish drought exposure compresses margin stability for Mediterranean-dependent sourcing.
- Coconut:Coconut bases deliver creamy mouthfeel through higher fat content and require less texture modification, reducing enzymatic intervention complexity. United Kingdom supermarkets allocate premium refrigerated positioning to coconut variants, yet imported supply chains face carbon disclosure pressure under EU Green Deal frameworks.
- Soy:Soy-derived variants sustain mature demand among allergen-aware buyers despite taste limitations and EFSA protein claim threshold challenges.
- Cashew:Cashew formulations capture premium margin pools through superior creaminess and minimal astringency, commanding price multiples in French foodservice channels.
Almond holds the largest share; momentum sits with cashew as creamier mouthfeel positioning displaces basic nutrition claims.
End User:
Cost tier stratification separates mass-market penetration from premium positioning, with formulation complexity and certification requirements determining which user segments justify dedicated SKUs.
- Health-Conscious Consumers:This segment drives clean-label demand and tolerates price premiums for live culture viability, HPP-treated stability, and transparent carbon footprint disclosure.
- Vegans:Vegans require absolute dairy-free certification and scrutinize cross-contamination protocols, creating compliance costs that restrict supplier eligibility.
- Lactose Intolerant Individuals:Lactose-intolerant buyers prioritize digestive comfort over taste optimization, sustaining demand for simpler oat and soy bases with minimal additive profiles.
- Athletes:Athletes represent the fastest-expanding trajectory as EFSA protein claim thresholds and precision fermentation integration enable performance-oriented positioning previously unattainable in plant-based formats.
Health-conscious consumers dominate volume; athletes are climbing the fastest as protein claim legitimacy reshapes competitive targeting.
Packaging Type:
Application-driven format selection reflects the tension between live culture viability requirements, cold-chain capex constraints, and retail shelf-space economics.
- Plastic Cups:Single-serve plastic cups dominate German and French supermarket refrigerated sections, optimized for automated filling lines and standard shelf depths.
- Glass Jars:Glass jars command premium positioning in United Kingdom health food stores and support extended fermentation visibility marketing.
- Pouches:Pouch formats reduce packaging weight for online retail logistics but face EFSA additive scrutiny for multilayer barrier films.
- Family Size Containers:Family-size containers concentrate in Aldi and Lidl discounter channels where unit economics favor volume throughput over margin extraction.
Plastic cups retain the largest share; pouches are gaining share fastest as direct-to-home delivery expands beyond urban cores.
Distribution Channel:
Supply concentration by channel determines which manufacturers can absorb slotting fee structures and cold-chain infrastructure demands.
- Supermarkets:Supermarkets anchor volume through dedicated plant-based refrigerated sections in Germany, France, and the United Kingdom, though buyer concentration compresses supplier negotiation cycles.
- Online Retailers:Online retailers enable subscription models and direct sourcing relationships that bypass traditional dairy distributor networks.
- Health Food Stores:Health food stores sustain premium positioning for certified organic and precision fermentation variants with higher service intensity.
- Restaurants:Restaurants demand barista-grade texture stability and foodservice-format packaging, with HPP-treated skyr-style oat formulations expanding at twice the rate of conventional alternatives.
Supermarkets hold the largest share; restaurants are expanding most quickly as foodservice channels recover and adopt plant-based menu integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites distribution reach across northwestern Europe, enabling live culture products to maintain viability through multimodal transit into German and French retail networks.
Germany
Health-conscious consumers in Berlin and Munich drive refrigerated plant-based section expansion across Edeka and Rewe supermarket chains. BfR enzymatic approval pathways streamline additive safety assessments for fermented oat textures. Bavaria's dairy processing heritage clusters around Munich, where traditional fermentation expertise migrates into plant-based substrate development.
France
French supermarkets allocate premium positioning to coconut and cashew formulations as Parisian consumers prioritize creamy mouthfeel over basic nutrition claims. DGCCRF enforces national interpretation layers atop harmonized EU rules, complicating cross-border formulation strategies. The Île-de-France region concentrates foodservice demand where HPP-treated skyr-style oat formulations expand at twice conventional rates.
United Kingdom
Tesco and Sainsbury's private-label plant-based lines capture one-third of refrigerated shelf space, compressing supplier negotiation cycles. EFSA protein content claim thresholds force reformulation of soy-derived variants as analytical standards tighten. Greater London's direct-to-home delivery networks accelerate pouch format adoption beyond urban cores.
Netherlands
Rotterdam's port infrastructure anchors oat import flows from Nordic processing facilities, creating supply concentration risk for texture-critical formulations. CSRD supply chain disclosure mandates position early compliance brands for institutional procurement contracts. The Randstad cluster hosts precision fermentation startups integrating biomass methods with traditional enzymatic treatment.
Spain
Spanish drought exposure compresses margin stability for almond-dependent producers sourcing from Mediterranean growing regions. EU Green Deal carbon disclosure frameworks favor domestically sourced oat supply chains over imported coconut bases. Andalusia's almond orchards face water intensity pressures that reshape ingredient sourcing strategies for Barcelona and Madrid processors.
Europe Non-Dairy Yogurt Market Competitive Landscape
On the supply side, the industry is consolidating around cold-chain infrastructure owners and enzymatic texture specialists, with mid-tier producers facing compressed R&D timelines from simultaneous reformulation demands. Three archetypes dominate: legacy dairy converters leveraging fermentation heritage, oat-native challengers with barista-grade brand recognition, and precision fermentation integrators pursuing protein claim legitimacy. Competitive moves center on M&A for Nordic oat processing capacity and strategic partnerships for HPP technology licensing.
Within the legacy converter archetype, Danone S.A. and Valio Ltd. anchor European distribution through cold-chain infrastructure ownership and Nordic dairy heritage respectively. Among oat-native challengers, Oatly Group AB exemplifies brand recognition extension from adjacent beverage categories into yogurt formats. These three companies occupy positions spanning infrastructure control, regional heritage leverage, and cross-category brand equity deployment.
| Leading Market Players |
|---|
| Danone S.A. |
| Oatly Group AB |
| The Hain Celestial Group Inc. |
| Valio Ltd. |
| Valsoia SpA |
| Blue Diamond Growers |
| Triballat Noyal |
| Andros Group |
| Nestlé S.A. |
| Others |
Pricing and Supply Chain Analysis
Spanish drought exposure determines both pricing tier spreads and supply chain shape for almond-dependent formulations, compressing margin stability for Mediterranean-sourced bases while accelerating oat supply chain investments across Nordic and domestic European channels.
Pricing Analysis
Volume-discount tiering structures separate family-size containers in Aldi and Lidl channels from premium glass jar positioning in United Kingdom health food stores. Price differentiation rests on certification grade and live culture viability claims, with HPP-treated formulations commanding sustained premiums. Pricing pressure stems from input cost volatility in almond and coconut bases, squeezing mid-tier producers most acutely. Discounter buyers exhibit highest price sensitivity, while health-conscious consumers in Berlin and Munich tolerate premiums for transparent carbon footprint disclosure.
Supply Chain Analysis
Extended payment terms from German and French supermarket chains concentrate working capital demands on mid-tier producers, favoring cold-chain infrastructure owners with balance sheet depth. Geographic supply concentrates in Sweden, Finland, and Germany for enzymatic oat processing, while coconut bases draw from Southeast Asian import flows. Raw material dependencies span Nordic oat starch, Mediterranean almond protein, and enzymatic texture modifiers. Single-source vulnerability in Nordic enzymatic treatment capacity threatens texture-critical formulations. Distribution runs through Rotterdam's port infrastructure into multimodal cold-chain networks serving Edeka, Rewe, and Tesco retail systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection arrives through CSRD supply chain disclosure mandates, which transform carbon transparency into an interoperability standard that determines institutional procurement access across European foodservice and retail ecosystems.
For Market Incumbents: Build cold-chain infrastructure moats through captive Nordic oat processing capacity additions, defending against precision fermentation entrants. Acquire enzymatic texture specialists to compress R&D timelines for EFSA protein claim compliance. Channel control through direct sourcing relationships with Aldi and Lidl bypasses traditional dairy distributor networks.
For New Entrants and Emerging Players: Build out white-space presence in Poland and Romania's nascent refrigerated plant-based sections, where limited local production capacity creates entry windows. Target athlete segments with precision fermentation-enabled protein claims that legacy converters cannot match. Foodservice channel partnerships with HPP-treated skyr-style formulations offer fastest traction.
For Investors and Strategic Acquirers: EU Green Deal carbon disclosure mandates reshape the acquisition landscape toward early CSRD compliance brands with institutional procurement positioning. Five-to-ten-year viability favors precision fermentation integrators over commodity base importers. Acquisition target archetype: enzymatic texture specialists with BfR approval pathways. Signal to watch: EFSA protein content threshold enforcement timing.
| Strategic Initiative | Industry Significance |
|---|---|
| HPP Technology Licensing | Collapses shelf stability and live culture viability trade-offs for German retail buyers. |
| Nordic Oat Processing Acquisition | Secures enzymatic treatment capacity against single-point supply vulnerability. |
| CSRD Early Compliance Program | Positions premium brands for institutional procurement contracts under EU frameworks. |
| Precision Fermentation Integration | Enables EFSA protein claim eligibility without soy base dependency. |
| Direct-to-Home Pouch Expansion | Captures subscription demand beyond Greater London's urban core delivery networks. |
Research Methodology
Operator-level perspectives from fermentation microbiologists, enzymatic texture specialists, supermarket category buyers, and cold-chain logistics managers anchored the qualitative base. Primary interviews combined with secondary validation from EFSA guidance documents, EU Green Deal implementation frameworks, BfR additive safety assessments, and Nielsen retail audit data. Bottom-up formulation modeling and top-down channel volume estimates were triangulated against customs records for oat and almond base imports.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning base ingredient type, protein content tier, packaging format, and distribution channel. CAGRs derived from elasticity-adjusted demand curves incorporating EFSA regulatory timing and CSRD disclosure phase-in schedules. Forecast inputs included enzymatic treatment capacity expansion timelines and HPP technology adoption rates in German and French retail networks.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation entrants or accelerated EFSA enforcement would shift outcomes. Macroeconomic deviation, regulatory timing changes, or breakthroughs in biomass fermentation economics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
Dairy Free Shortening Market
Dairy Alternatives
Oat Milk Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
Fat Free Yogurt Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
North America Non-Dairy Cheese Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
Yogurt Alternative Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Vegan Butter Market
Dairy Alternatives
Non-Dairy Cheese Market