
 Buttermilk Market | 2026-2036
Buttermilk Market Size, Share, and Industry Trends Forecast 2026-2036
Buttermilk Market Analytics
Premium cultured buttermilk with live probiotic counts and extended shelf-life specifications is bifurcating the competitive landscape between commodity fluid suppliers and value-added processors. Amul leverages its Gujarat cooperative network to dominate India's branded buttermilk segment with ambient-stable pouches. Arla Foods sustains European market presence through organic and pasture-milk certified lines that command shelf space in Scandinavian and German retail. Fonterra anchors Oceania supply through its dairy ingredient export platform, shipping powdered buttermilk to Southeast Asian bakery manufacturers.
Buttermilk comprises the low-fat liquid remaining after butter churning, or fermented milk cultured with Lactococcus lactis to achieve tart flavor and viscosity around 8-10% milk solids-not-fat; it functions primarily as an acidulant and tenderizer in baked goods, a base for emulsified dressings, and a cultured beverage. Liquid buttermilk leads volume in food service channels where batch consistency matters, while powdered buttermilk captures margin in industrial baking and export markets where logistics costs constrain fluid alternatives. Non-dairy buttermilk, formulated from oat or soy with lactic acid and lecithin, is expanding fastest among North American plant-based bakeries and vegan sauce producers seeking functional parity.
FDA standards of identity for cultured dairy products and the EU's Dairy Regulations enforce compositional thresholds that shape formulation investments and cross-border trade eligibility for buttermilk exporters. India's FSSAI packaged food labeling rules and BIS dairy product standards are tightening microbial specifications, forcing domestic processors to upgrade cold chain infrastructure or shift toward UHT and powdered formats. Stakeholders must monitor how diverging probiotic health claims regulations across the United States, Europe, and India will determine which product tiers can command premium positioning without triggering pharmaceutical classification.
Market Dynamics
Clean-label dairy regulations in the European Union and North America are forcing processors to reformulate toward cultured and fermented derivatives, bifurcating supply chains between commodity fluid handlers and value-added probiotic processors.
Growth Catalysts
- EU Dairy Regulations:Compositional thresholds for cultured products are accelerating investment in certified organic pasture-milk lines across Scandinavian and German retail channels.
- Industrial baking automation:Powdered buttermilk demand is concentrating in Southeast Asian bakery manufacturing hubs where batch consistency and extended shelf-life reduce logistics costs.
- India's organized retail expansion:Cold chain infrastructure upgrades and UHT format adoption are lifting per-capita buttermilk volumes in Gujarat and Maharashtra cooperative networks.
Market Restraints
- Butter price volatility:Cream input costs fluctuate with global dairy commodity cycles, compressing margins for traditional churn-based buttermilk processors.
- FDA standards of identity:Cross-border trade eligibility constraints limit fluid buttermilk exports from Oceania to North American food service channels.
- Oat and soy emulsion technology:Plant-based acidulant-lecithin formulations are capturing functional parity in vegan bakery and sauce applications.
Strategic Opportunities
- FSSAI microbial specification tightening:India's packaged food labeling rules are creating first-mover advantage for domestic processors investing in ambient-stable pouch formats.
- Probiotic health claims convergence:Diverging pharmaceutical classification thresholds across the United States, Europe, and India present white space for live-count premium tier positioning.
- Direct-to-food-service distribution:Bypassing traditional dairy wholesale channels is enabling margin capture for regional processors serving artisanal bakery clusters.
Industry Challenges
- Live culture stability expertise:Maintaining viable Lactococcus lactis counts through UHT and extended shelf-life processing requires specialized fermentation engineering talent scarce outside established dairy cooperatives.
- Clean-label certification timelines:Organic and pasture-milk audit cycles stretch 18-24 months, delaying market entry for reformulated product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buttermilk Market |
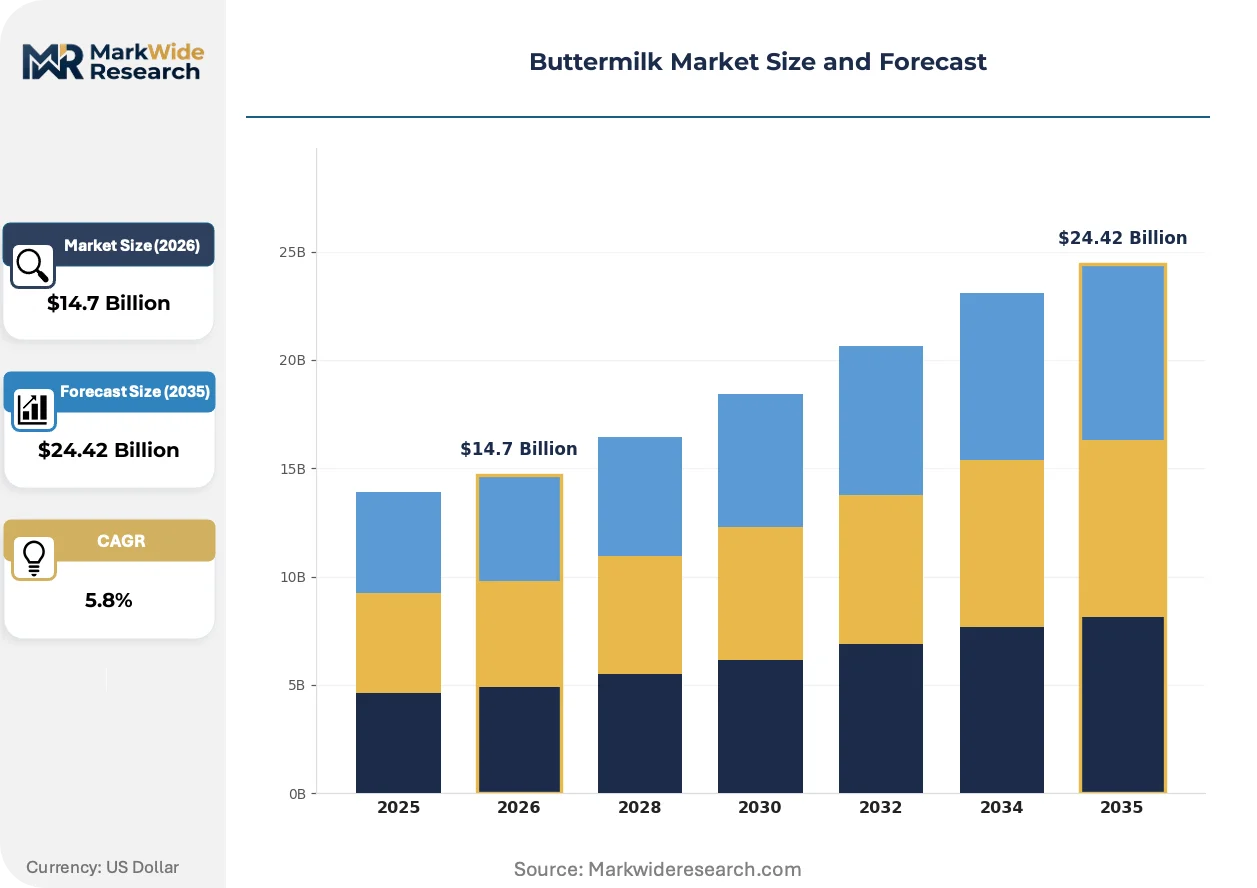
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Buttermilk, Powdered Buttermilk, Cultured Buttermilk, Non-Dairy Buttermilk End Use: Baking, Beverage, Salad Dressing, Sauces Packaging Type: Bottles, Tetra Packs, Pouches, Cartons Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service |
| Companies Covered | Amul, Arla Foods, DairyAmerica, Sodiaal Group, Fonterra, Dairy Farmers of America, Glanbia, Valley Milk, Associated Milk Producers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buttermilk Market Evolving Landscape
Functional ingredient technology and regulatory divergence are fragmenting buttermilk supply chains into three distinct competitive arenas: live-probiotic premium tiers, extended shelf-life convenience formats, and plant-based functional alternatives.
Precision fermentation for dairy protein synthesis is decomposing the traditional butter-churning value chain by enabling buttermilk solid production without cream separation. Synthetic biology startups and ingredient multinationals are piloting microbial-derived milk fat globule membranes for bakery applications. This technology is compressing the cost structure for industrial-scale acidulant supply while threatening commodity fluid processor margins.
REACH chemical safety assessments and the EU Green Deal's farm-to-fork sustainability mandates are reshaping dairy ingredient sourcing requirements. Processors must now document pasture-milk provenance and methane reduction metrics to maintain retail shelf access. German and Danish organic lines are responding with blockchain-tracked cooperative supply networks that satisfy EFSA audit standards.
Food service procurement is consolidating around specification-driven vendor qualification programs that unbundle fluid delivery from technical support. Large bakery chains are replacing spot-market dairy purchasing with annual contracts tying volume commitments to microbiological consistency guarantees. This pattern is most visible in India's quick-service restaurant expansion, where centralized commissaries demand ambient-stable buttermilk with documented probiotic viability through distribution.
Buttermilk Market Segmentation
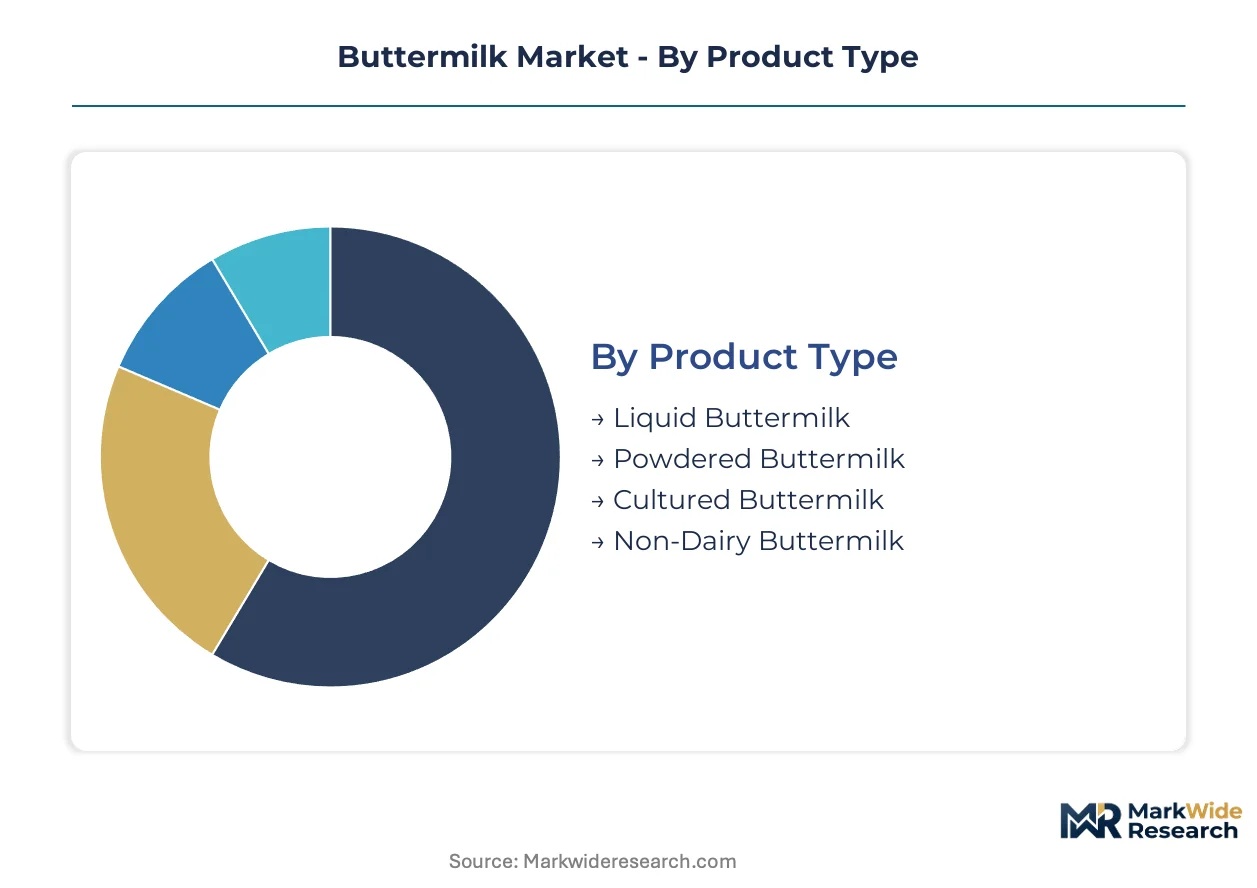
Buttermilk's functional versatility across acidulant, tenderizer, and cultured beverage roles creates distinct demand profiles by product form and application. Segmentation reveals where plant-based substitutes exert pressure versus where dairy-derived specifications remain non-negotiable.
Product Type:
Non-dairy formulations face the most acute substitution pressure as oat and soy emulsion technology achieves functional parity in bakery and sauce applications.
- Liquid Buttermilk:Fluid format retains 8-10% milk solids-not-fat with native Lactococcus lactis cultures, delivering batch consistency critical to artisanal bakeries in India and North American food service channels where live culture viability determines specification compliance.
- Powdered Buttermilk:Spray-dried format concentrates milk solids to 95%+ for extended shelf-life logistics, capturing industrial baking demand in Southeast Asian manufacturing hubs where ambient storage reduces cold chain capital requirements.
- Cultured Buttermilk:Fermented dairy with controlled acidity and viscosity specifications serves clean-label reformulation needs under EU Dairy Regulations and FDA standards of identity.
- Non-Dairy Buttermilk:Acidulant-lecithin emulsions from oat or soy substrates target vegan bakery and plant-based sauce producers seeking functional equivalence without dairy allergen declarations.
Liquid buttermilk anchors the volume base while non-dairy alternatives gain share at the steepest rate.
End Use:
Cost tier stratification separates commodity acidulant supply from premium probiotic beverage positioning.
- Baking:Industrial and artisanal applications demand precise acidulant function for gluten protein modification and crumb tenderization, with powdered formats preferred for automated dosing systems in high-volume operations.
- Beverage:Cultured buttermilk as a standalone drink concentrates in Indian organized retail through ambient-stable pouches, while probiotic health claims face divergent pharmaceutical classification thresholds across the United States, Europe, and India.
- Salad Dressing:Emulsified buttermilk bases require specific fat-protein ratios for stability, driving specification-driven procurement from dairy ingredient suppliers.
- Sauces:Acidulant and flavor base functions support cream-style and cheese sauce formulations where cultured dairy notes provide signature taste profiles.
Baking anchors the volume base while beverage applications expand most quickly.
Packaging Type:
Supply concentration in ambient-stable formats reflects cold chain infrastructure gaps in emerging demand centers.
- Bottles:HDPE and PET containers serve fluid buttermilk in refrigerated retail channels where turnover velocity supports shorter shelf-life logistics.
- Tetra Packs:Aseptic carton technology enables UHT treatment and ambient distribution, critical to India's cooperative network expansion in Gujarat and Maharashtra.
- Pouches:Flexible laminate formats dominate Indian branded buttermilk through Amul's cooperative distribution, combining cost efficiency with shelf stability.
- Cartons:Gable-top refrigerated cartons maintain presence in European and North American retail dairy cases.
Tetra packs anchor the volume base while pouches gain share at the steepest rate.
Distribution Channel:
Customer type fragmentation separates specification-driven food service procurement from price-sensitive retail purchasing.
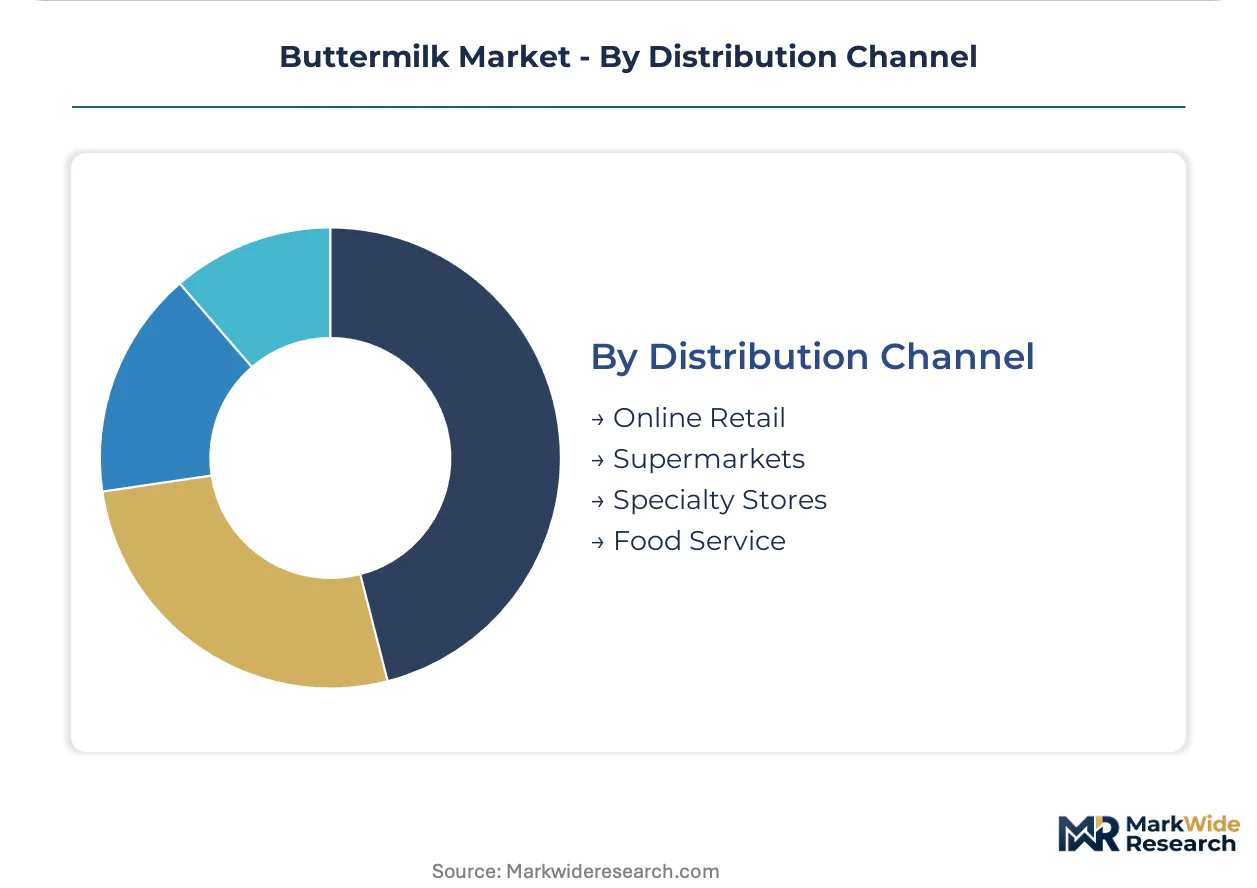
- Online Retail:E-commerce platforms aggregate niche and premium cultured products, though fluid formats face last-mile cold chain constraints outside metropolitan zones.
- Supermarkets:Multi-format retail in India and organized chains in Germany and Denmark drive volume through private-label and branded cultured lines.
- Specialty Stores:Organic and pasture-milk certified buttermilk concentrates in natural food channels where blockchain-tracked provenance commands shelf space.
- Food Service:Direct-to-commissary contracts with microbiological consistency guarantees are replacing spot-market purchasing among Indian quick-service restaurant chains and large bakery operations.
Supermarkets anchor the volume base while food service channels expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in dairy cooperative networks across India, Europe, and Oceania, with each region developing distinct format preferences shaped by cold chain maturity and regulatory frameworks governing cultured dairy classification.
India
Gujarat and Maharashtra cooperative networks drive ambient-stable pouch adoption through Amul's distribution infrastructure. FSSAI packaged food labeling rules and BIS dairy product standards are tightening microbial specifications, forcing upgrades toward UHT formats. Organized retail expansion in Mumbai and Pune accelerates per-capita buttermilk consumption through branded cultured beverages.
United States
Industrial baking automation and food service procurement consolidation concentrate powdered buttermilk demand in Midwest manufacturing corridors. FDA standards of identity for cultured dairy products constrain cross-border fluid imports while enabling domestic probiotic health claim differentiation. Artisanal bakery clusters in California and New York Metro sustain refrigerated liquid format volumes through direct-to-commissary contracts.
Germany
Organic and pasture-milk certified lines command shelf space in Scandinavian and German retail through Arla Foods' cooperative sourcing. REACH chemical safety assessments and the EU Green Deal's farm-to-fork mandates require documented methane reduction metrics and blockchain-tracked provenance. Dairy processing concentration in Bavaria and North Rhine-Westphalia anchors reformulation investment toward clean-label fermented derivatives.
New Zealand
Fonterra's dairy ingredient export platform ships powdered buttermilk to Southeast Asian bakery manufacturers seeking batch consistency and extended shelf-life logistics. The country's pasture-based production model satisfies EU Dairy Regulations for organic certification eligibility. Auckland and Canterbury processing hubs concentrate spray-dried format capacity serving industrial baking automation in Singapore and Malaysia.
France
Sodiaal Group's cooperative structure sustains cultured buttermilk supply for emulsified dressing and sauce applications requiring specific fat-protein stability ratios. EFSA audit standards and EU Dairy Regulations enforce compositional thresholds that shape formulation investments for cross-border retail access. Dairy processing clusters in Brittany and Normandy specialize in fermented derivatives for European food service channels.
Buttermilk Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the buttermilk value chain. The market exhibits tiered concentration with dairy cooperatives dominating branded beverage segments and ingredient multinationals controlling industrial powder supply. Three archetypes prevail: cooperative-owned processors with captive milk supply, specialty dairy ingredient exporters with spray-drying scale, and plant-based emulsion technology developers. Competitive moves center on backward integration into fermentation engineering talent and strategic partnerships with quick-service restaurant chains for direct-to-commissary distribution.
Within the cooperative processor archetype, Amul and Arla Foods exemplify region-anchored market presence through membership-based milk sourcing structures. Fonterra occupies a position bridging Oceania production gravity and Southeast Asian demand concentration through its ingredient export platform. These three entities represent distinct geographic supply bases—Indian subcontinent, Northern Europe, and Australasia—each shaped by divergent regulatory frameworks for cultured dairy classification and probiotic health claim authorization.
| Leading Market Players |
|---|
| Amul |
| Arla Foods |
| DairyAmerica |
| Sodiaal Group |
| Fonterra |
| Dairy Farmers of America |
| Glanbia |
| Valley Milk |
| Associated Milk Producers |
| Others |
Value Network & Pricing Analysis
FDA standards of identity for cultured dairy products gate both supply qualification and price differentiation simultaneously, enforcing compositional thresholds that separate premium probiotic tiers from commodity fluid handlers while cross-border eligibility constraints reshape import economics for regional processors.
Pricing Analysis
FDA standards of identity dictate the pricing tier structure by enforcing compositional thresholds that separate certified organic pasture-milk lines from conventional fluid supply. Three-tier pricing structure across premium probiotic, standard cultured, and economy commodity levels tracks certification grade and live culture viability specifications. Cost compression in the commodity tier is intensifying because butter price volatility feeds directly into cream input economics. Industrial baking manufacturers exhibit the highest price sensitivity due to automated dosing scale, while specialty organic retailers show minimal elasticity for blockchain-tracked provenance claims.
Supply Chain Analysis
India and New Zealand anchor global buttermilk supply through divergent production architectures—Gujarat cooperative networks for ambient-stable pouches and Canterbury spray-drying hubs for industrial powder export. Raw material flows draw from pasture-milk cooperatives, cream separation byproducts, and microbial culture propagation facilities. Single-source vulnerability concentrates in Lactococcus lactis strain supply for live-probiotic tier maintenance. Distribution runs through dairy cooperative wholesale channels in India, direct-to-commissary contracts in North American food service, and ingredient export platforms serving Southeast Asian bakery manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The buttermilk market sits at a platform-economics inflection where precision fermentation technology threatens to decompose traditional butter-churning value chains by enabling dairy protein synthesis without cream separation infrastructure.
For Market Incumbents: Consolidate backward integration into captive fermentation engineering talent pools to defend live culture stability expertise against synthetic biology startup disruption. Expand spray-dried capacity in Canterbury and Bavaria processing clusters to capture industrial baking automation demand in Southeast Asia. Lock in multi-year direct-to-commissary contracts with Indian quick-service restaurant chains before ambient-stable pouch formats commoditize.
For New Entrants and Emerging Players: Lead with oat and soy emulsion technology targeting vegan bakery clusters in California and New York Metro where functional parity commands price premiums absent dairy allergen declarations. Penetrate the North American plant-based sauce producer segment through acidulant-lecithin formulations that bypass FDA standards of identity constraints entirely. Pursue white-label manufacturing partnerships with established dairy cooperatives to bypass 18-24 month organic certification audit cycles.
For Investors and Strategic Acquirers: FSSAI microbial specification tightening reshapes the acquisition landscape by forcing domestic Indian processors toward UHT and powdered format investments that favor scaled operators over fragmented regional players. Position for five-to-ten year horizon consolidation in Indian organized retail buttermilk distribution. Target spray-drying specialists with established Southeast Asian export relationships and documented probiotic viability through extended shelf-life processing. Watch for divergence convergence in pharmaceutical classification thresholds across the United States, Europe, and India as the signal for premium tier repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Decomposes traditional cream-separation economics by enabling microbial-derived milk fat globule membrane production for bakery acidulant supply. |
| Blockchain-Tracked Provenance Integration | Satisfies EU Green Deal farm-to-fork mandates and EFSA audit standards for German and Danish organic retail shelf access. |
| Direct-to-Commissary Distribution Bypass | Captures margin from Indian quick-service restaurant expansion through centralized procurement with microbiological consistency guarantees. |
| UHT Format Infrastructure Investment | Addresses FSSAI microbial specification tightening by extending shelf life for Gujarat and Maharashtra cooperative network distribution. |
| Plant-Based Emulsion R&D Partnership | Secures functional parity in vegan bakery applications through oat and soy acidulant-lecithin formulations targeting North American allergen-free demand. |
Research Methodology
Two parallel data streams informed the analysis: structured primary engagement with dairy cooperative executives, fermentation engineering specialists, food service procurement managers, and bakery manufacturing operations leads; and secondary validation through FDA standards of identity filings, EU Dairy Regulations documentation, FSSAI packaged food labeling directives, Fonterra export platform disclosures, and Amul cooperative network distribution data. Bottom-up volume triangulation across product type, end use, packaging format, and distribution channel segments converged with top-down macroeconomic boundary conditions.
Across the analysis window, the analytical framework modeled volume and value outputs through segmentation across liquid, powdered, cultured, and non-dairy product types; baking, beverage, salad dressing, and sauce end uses; and supermarket, food service, online retail, and specialty store channels. CAGRs were derived from trend extrapolation anchored in butter price volatility cycles, clean-label regulatory enforcement trajectories, and precision fermentation technology adoption curves. Forecast inputs incorporated cold chain infrastructure investment rates in Indian organized retail and industrial baking automation penetration in Southeast Asian manufacturing hubs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement, stable FSSAI regulatory trajectory, or contained precision fermentation cost compression would require recalibration. Forecasts reflect documented assumptions about probiotic health claim authorization convergence and plant-based emulsion technology maturation. Recalibration cycles align with material shifts in dairy commodity pricing, regulatory classification thresholds, and synthetic biology platform economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
Savory Yogurt Market
Dairy Alternatives
Canada Dairy Alternatives Market
Dairy Alternatives
Europe Non-Dairy Cheese Market
Dairy Alternatives
A2 Ice Cream Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Vegan Butter Market
Dairy Alternatives
Dairy-Free Chocolate Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Vegan Ice Cream Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Non-Dairy Creamer Powder Market