
 Yellow Pea Protein Market | 2026-2036
Yellow Pea Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Yellow Pea Protein Market Intelligence
The capital investment divide in advanced dry fractionation technology is collapsing the distinction between diversified ingredient giants and specialized protein producers. Roquette Freres leverages its extensive manufacturing scale to serve high-volume food manufacturers. In contrast, Puris differentiates through its focus on non-GMO, domestically sourced pea supply chains. Ingredion Incorporated competes by offering a broad portfolio of plant-based ingredients, including isolates and concentrates.
Yellow pea protein is a plant-based protein derived from the yellow split pea, Pisum sativum, through either wet or dry processing methods. Its primary function in food manufacturing is to provide texture, emulsification, and nutritional fortification, especially in products for vegan and allergen-free consumers. Isolates, which contain over 80% protein content, command higher prices than the less-refined concentrates. Demand from the meat alternatives and nutritional supplements applications continues to drive innovation and volume growth across product types.
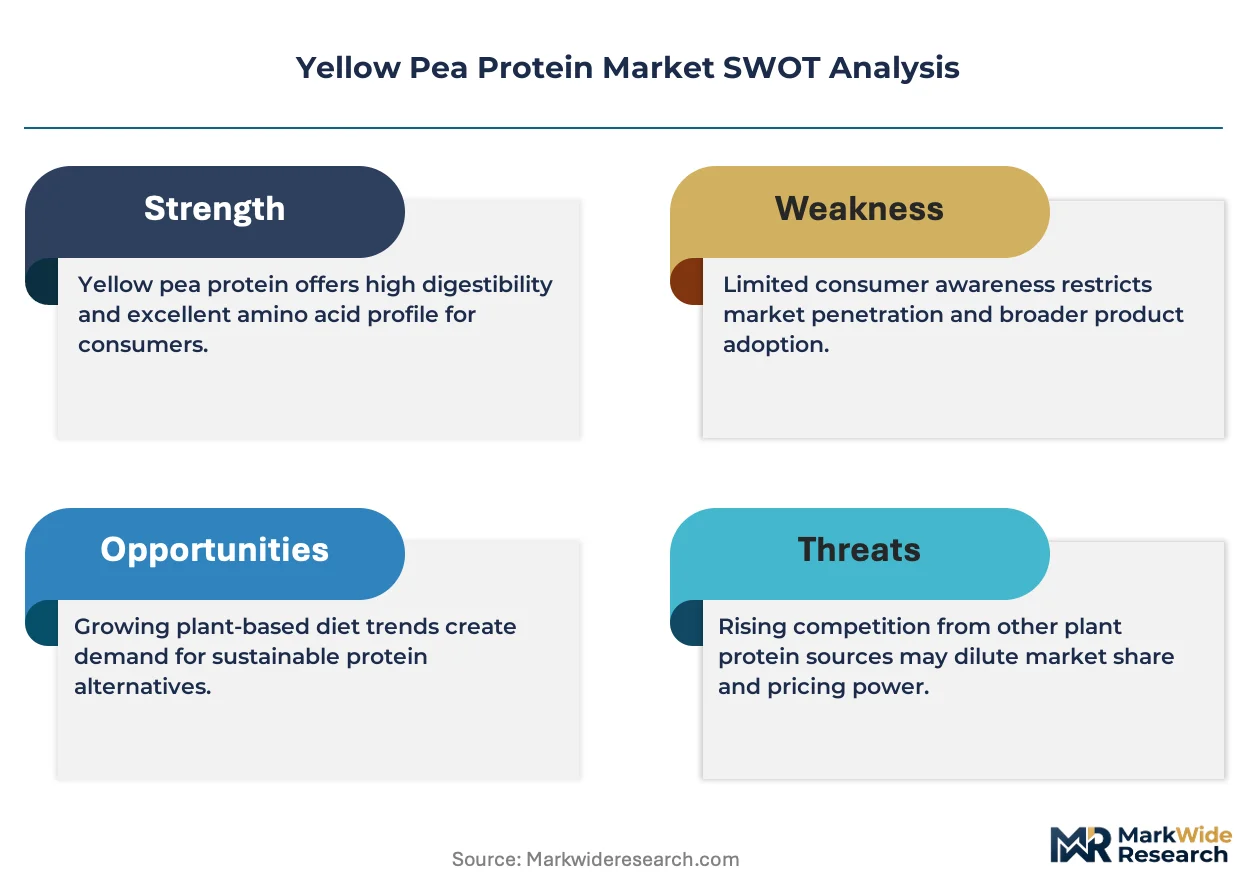
Regulations from bodies like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern ingredient safety and labeling. These frameworks mandate clear allergen declarations and influence how "plant-based" or "high-protein" claims are marketed to consumers. Navigating evolving standards for clean label ingredients and securing consistent, non-GMO yellow pea supply chains remain critical strategic priorities for all processors.
Market Dynamics
The bifurcation of supply chains, driven by divergent demands for mass-market functionality and certified clean-label attributes, represents the central structural force. Processors must navigate the technical and sourcing requirements of both high-volume and premium market segments.
Growth Catalysts
- Consumer Health Trends:Rising preference for plant-based diets and allergen-free products in economies like the United States and Germany fuels demand from the nutritional supplements and meat alternatives sectors.
- Processing Innovations:Advances in dry fractionation technology lower water and energy consumption, improving the sustainability profile and cost-competitiveness against other plant proteins like soy.
- Favorable Labeling Regulations:Clear "plant-based" and "high-protein" marketing claims, guided by frameworks from the FDA and EFSA, build consumer trust and facilitate market entry for new food products.
Market Restraints
- Supply Chain Volatility:Dependence on yellow pea harvests concentrated in regions like Canada and parts of Europe creates vulnerability to climate-related disruptions and price fluctuations for the raw agricultural input.
- Flavor and Functionality Hurdles:Unpleasant "beany" off-notes and challenges with solubility in certain food matrices require additional masking agents or processing steps, increasing formulation complexity and cost for food manufacturers.
- Competition from Other Plant Proteins:Intense competition from established proteins like soy and emerging alternatives such as fava bean or chickpea protein limits market penetration by offering different functional or cost advantages.
Strategic Opportunities
- Expansion in Asia-Pacific:Targeting growing middle-class populations in countries like China and India with fortified foods and meat analogues represents a significant growth vector beyond saturated Western markets.
- Pet Food Fortification:The humanization of pets trend creates an opportunity for high-protein, grain-free pet food formulations, an application where yellow pea protein's hypoallergenic properties are a key advantage.
- Hybrid Product Development:Blending yellow pea protein with other plant proteins, such as rice or potato, to create complete amino acid profiles and superior textures opens new possibilities in sports nutrition and dairy alternatives.
Industry Challenges
- High Capital Investment:Scaling production of high-purity isolates requires significant capital expenditure in advanced fractionation facilities, creating a high barrier to entry for smaller processors.
- Navigating GMO Labeling Complexity:Maintaining and certifying non-GMO supply chains across multiple countries with differing regulations, such as those in the European Union versus the United States, poses a significant logistical burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yellow Pea Protein Market |
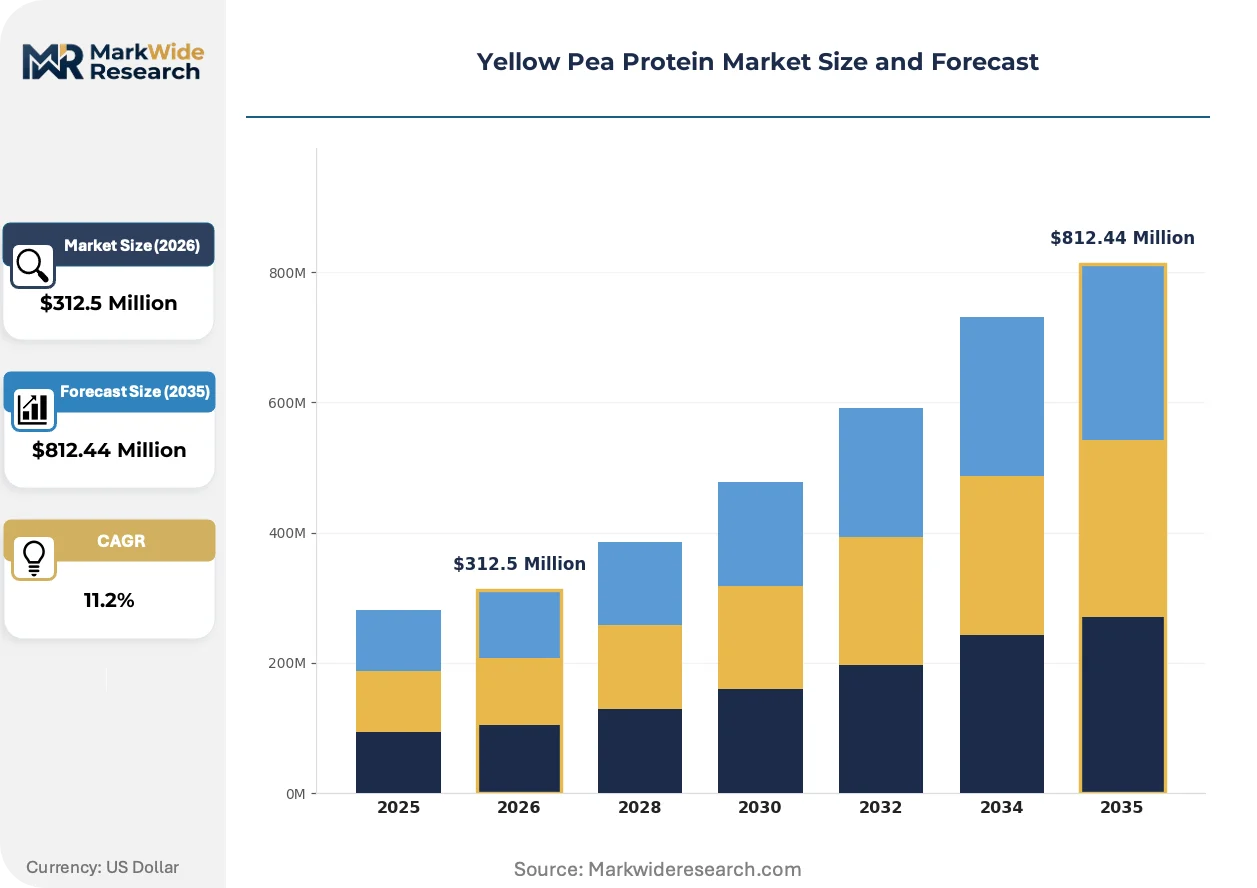
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $812.44 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolates, Concentrates, Textured Protein, Hydrolysates Application: Plant-Based Beverages, Meat Alternatives, Bakery Products, Nutritional Supplements End User: Food Manufacturers, Beverage Producers, Nutraceutical Companies, Animal Feeders Distribution Channel: Supermarkets & Hypermarkets, Specialty Stores, Online Retailers, Direct Sales |
| Companies Covered | Roquette Freres, Puris, Ingredion Incorporated, COSUCRA Groupe Warcoing S.A., The Scoular Company, Burcon NutraScience Corporation, Cargill, Axiom Foods, Inc., DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yellow Pea Protein Market Strategic Shifts & Innovations
Market evolution is defined by a shift from commodity ingredients to functionally optimized protein systems. Technological advancements in fractionation and texturization enable processors to meet precise formulation demands in high-value food and beverage applications.
Texturized vegetable protein (TVP) extrusion uses heat and pressure to transform pea protein flour into fibrous structures mimicking meat. Food manufacturers in the meat alternatives sector are adopting TVP for plant-based burgers and sausages. This technology is decomposing the boundary between plant-based ingredients and finished meat products, allowing direct competition on texture.
European Food Safety Authority (EFSA) regulations on allergen labeling require clear declarations on food packaging. This framework creates an advantage for inherently hypoallergenic ingredients like yellow pea protein over alternatives such as soy. The nutritional beverage segment in the European Union shows a preference for pea protein to simplify compliance.
A notable procurement shift involves large food manufacturers co-developing customized protein systems with suppliers instead of buying basic isolates. This displaces transactional purchasing with a partnership approach focused on achieving specific textural or nutritional outcomes. The trend is prominent in the North American dairy alternatives market for creating unique yogurt and beverage textures.
Yellow Pea Protein Market Segmentation
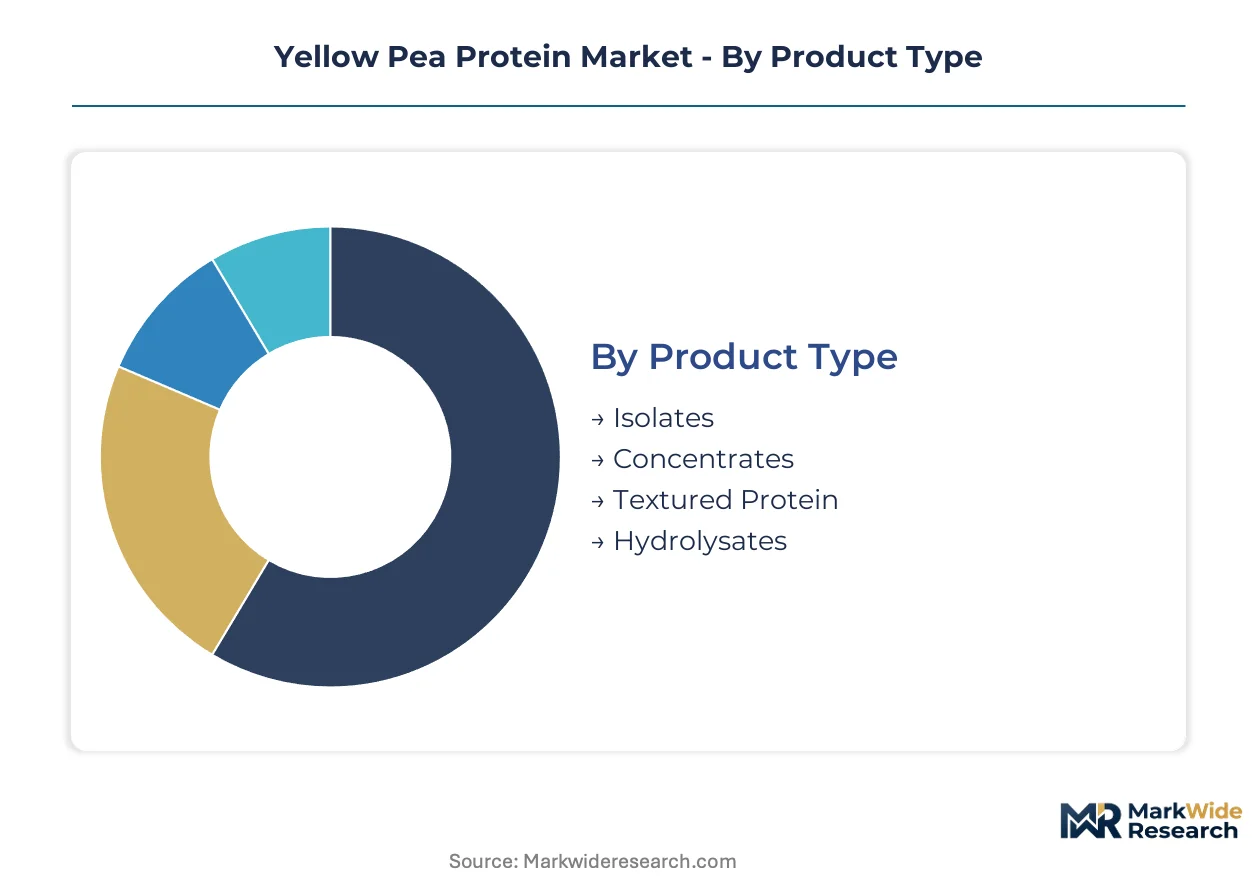
The segmentation of the yellow pea protein market illuminates distinct value propositions and competitive landscapes across different product forms, applications, and consumer touchpoints. Understanding these divisions helps processors and food manufacturers tailor their offerings to specific market needs and regulatory environments.
Product Type:
Regulatory frameworks from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) significantly differentiate product types based on purity and processing methods.
- Isolates:These highly refined products contain over 80% protein, offering superior functional properties like emulsification and solubility for high-value applications. Demand is concentrating in Europe for dairy alternatives, driven by consumer preference for clean label ingredients.
- Textured Protein:Produced through extrusion, this category transforms pea protein flour into fibrous structures that mimic meat, making it essential for plant-based burgers and sausages. North American meat alternative producers are adopting TVP for its textural capabilities, competing directly with traditional meat products.
- Concentrates:Containing 50-80% protein, concentrates offer a cost-effective protein source for various food formulations.
- Hydrolysates:These proteins are enzymatically broken down into smaller peptides, improving digestibility and solubility, often used in specialized nutritional products.
Textured Protein handles the majority of throughput; Isolates are the fastest mover on share.
Application:
Volume dynamics across applications are heavily influenced by evolving consumer dietary preferences and product innovation cycles.
- Meat Alternatives:This segment represents a substantial volume driver, utilizing yellow pea protein for its textural properties and nutritional profile in plant-based burgers, sausages, and ground meat substitutes. Innovation here is rapid, particularly in the United States and Germany.
- Nutritional Supplements:Pea protein is a favored ingredient in protein powders, bars, and ready-to-drink shakes due to its hypoallergenic nature and amino acid profile. European consumers increasingly seek plant-based options for sports nutrition.
- Plant-Based Beverages:Pea protein provides emulsion stability and nutritional fortification in milk alternatives, smoothies, and functional drinks.
- Bakery Products:Used to enhance protein content and improve texture in gluten-free breads, cookies, and pastries.
Demand for Meat Alternatives dominates volume while Nutritional Supplements demonstrates the steepest expansion trajectory.
End User:
Customer type segmentation reveals varied procurement strategies and formulation requirements across the industry value chain.
- Food Manufacturers:These large-scale entities integrate yellow pea protein into a wide range of finished products, including meat alternatives, snacks, and ready meals. They often engage in co-development partnerships with ingredient suppliers for customized protein systems.
- Nutraceutical Companies:Specialized in health and wellness products, these companies value pea protein for its clean label appeal and functional benefits in dietary supplements and functional foods. Compliance with FDA and EFSA guidelines is paramount for these formulations.
- Beverage Producers:They incorporate pea protein into plant-based milks, protein shakes, and functional drinks, focusing on solubility and taste neutrality.
- Animal Feeders:This segment uses pea protein as a protein source in pet food and livestock feed, leveraging its nutritional value.
Industrial scale procurement from Food Manufacturers underpins the market; Nutraceutical Companies exhibit strong growth in specialized formulations.
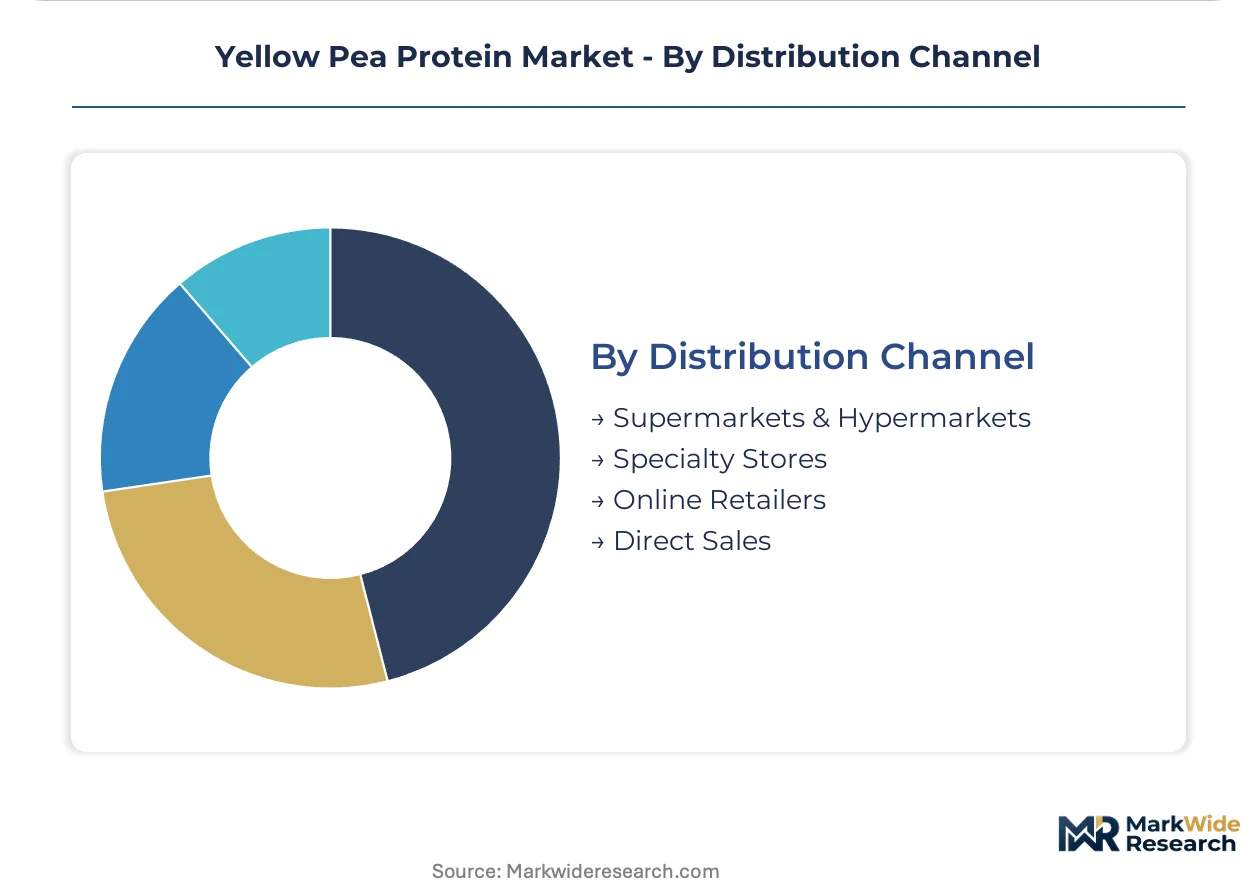
Distribution Channel:
The maturity of distribution channels dictates market reach and consumer accessibility for yellow pea protein products.
- Online Retailers:E-commerce platforms offer broad consumer access and are expanding rapidly, especially for niche nutritional supplements and specialty plant-based foods. This channel allows direct-to-consumer sales and personalized marketing.
- Supermarkets & Hypermarkets:These traditional retail outlets provide the largest volume sales for finished products containing yellow pea protein, including meat alternatives and plant-based beverages. Their extensive reach makes them critical for mass-market penetration.
- Specialty Stores:Health food stores and organic markets cater to consumers seeking premium, clean-label, and allergen-free products.
- Direct Sales:Some ingredient suppliers engage in direct sales to industrial clients, fostering long-term relationships for bulk orders.
Traditional retail channels like Supermarkets & Hypermarkets secure broad consumer access, while Online Retailers channels are expanding rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for yellow pea protein varies significantly, with premium, clean-label applications in Europe exhibiting less price sensitivity compared to high-volume, cost-driven segments in North America. Processors must align their offerings with these regional economic dynamics. This bifurcation influences investment decisions and supply chain configurations across diverse markets.
United States
Strong consumer health trends and the expanding meat alternatives sector drive significant demand for yellow pea protein. The U.S. Food and Drug Administration (FDA) regulates ingredient safety and labeling, influencing product development. Food manufacturers in the Midwest are actively innovating new plant-based burger and sausage formulations.
Germany
European consumers, particularly in Germany, show a high preference for plant-based diets and allergen-free products, fueling demand in nutritional supplements. The European Food Safety Authority (EFSA) mandates clear allergen declarations, which benefits hypoallergenic pea protein. Berlin's vibrant food tech scene fosters new product development in plant-based dairy alternatives.
China
Growing middle-class populations in China seek fortified foods and meat analogues, creating a substantial growth vector for pea protein. Regulations from the State Administration for Market Regulation (SAMR) govern food safety and ingredient approvals. Shanghai's food processing hubs are integrating pea protein into a variety of functional beverages and snacks.
India
Rising health consciousness and a large vegetarian population contribute to the demand for plant-based protein in India. The Food Safety and Standards Authority of India (FSSAI) oversees food product standards and labeling requirements. Bangalore's burgeoning nutraceutical industry incorporates pea protein into health supplements and protein powders.
Canada
Canada's robust agricultural sector provides a strong supply base for yellow peas, supporting both domestic and export markets. Health Canada sets guidelines for natural health products and food ingredients, ensuring product safety. Saskatchewan's agricultural processing facilities are expanding capacity for pea protein extraction, serving global demand.
Yellow Pea Protein Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the yellow pea protein market. These leaders often possess extensive manufacturing scale and diversified ingredient portfolios. Strategic archetypes include large-scale ingredient producers, specialized non-GMO protein providers, and broad plant-based ingredient suppliers. Competitive moves frequently involve capacity expansion and strategic partnerships with food manufacturers.
At the scale-driven end, Roquette Freres, a French-based company, represents a major ingredient producer leveraging extensive manufacturing capabilities for high-volume food manufacturers. Puris, an American-based company, exemplifies specialized protein producers focusing on non-GMO and domestically sourced pea supply chains, differentiating through its supply chain control. Ingredion Incorporated, another American-based entity, occupies a position as a broad plant-based ingredient supplier, offering a wide range of isolates and concentrates to diverse application segments.
| Leading Market Players |
|---|
| Roquette Freres |
| Puris |
| Ingredion Incorporated |
| COSUCRA Groupe Warcoing S.A. |
| The Scoular Company |
| Burcon NutraScience Corporation |
| Cargill |
| Axiom Foods, Inc. |
| DuPont de Nemours, Inc. |
| Others |
Cost & Logistics Intelligence
Seasonal raw material inventory fluctuations directly influence yellow pea protein market pricing power and supply chain configuration. This dynamic creates challenges for processors in managing costs and ensuring consistent product availability for diverse end-use applications.
Pricing Analysis
Value-added formulation services drive lifetime value for specialized yellow pea protein suppliers. The market operates on a hybrid pricing model, blending long-term contract-based agreements for high-volume food manufacturers with commodity spot pricing for less refined products. Price differentiation stems from protein purity (isolates versus concentrates) and non-GMO certification, which commands a premium. Pricing softness arises from intense competition from other plant proteins like soy and fava bean. High-volume, cost-driven segments in North America exhibit greater price sensitivity than premium, clean-label applications in Europe.
Supply Chain Analysis
Dependence on yellow pea harvests concentrated in Canada and parts of Europe underwrites significant supply chain volatility. The market relies heavily on yellow split peas as its primary agricultural input. This concentration creates a structural risk to climate-related disruptions and raw material price fluctuations. Maintaining certified non-GMO supply chains across diverse regulatory environments also poses logistical burdens. Distribution runs through direct sales to large food manufacturers for customized systems and bulk orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The yellow pea protein market presents a significant service-attach opportunity, with co-development partnerships for customized protein systems expanding faster than basic commodity sales. This trend allows suppliers to embed deeper into customer value chains and secure recurring revenue streams.
For Market Incumbents: Compound existing manufacturing scale by investing in advanced dry fractionation facilities to produce high-purity isolates. Roquette Freres can strengthen its position against emerging protein alternatives by deepening co-development partnerships with large food manufacturers for customized solutions. Prioritize R&D in flavor masking technologies to overcome the "beany" off-notes, a persistent formulation hurdle. Secure long-term, non-GMO yellow pea supply contracts to mitigate raw material volatility and maintain clean-label integrity.
For New Entrants and Emerging Players: Anchor in niche, high-growth applications like pet food fortification or specialized nutritional supplements, leveraging yellow pea protein's hypoallergenic properties. Target the burgeoning Asia-Pacific market, particularly China and India, with fortified food products designed for middle-class consumers. Differentiate through proprietary processing innovations that deliver superior texture or eliminate off-notes, enabling premium positioning. Develop hybrid protein blends for sports nutrition and dairy alternatives to offer complete amino acid profiles.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified ingredient giants seeking to divest non-core protein assets, or from specialized protein producers with unique technological advantages. The long-term viability of the yellow pea protein market remains strong, driven by sustained consumer shifts towards plant-based and clean-label diets. Seek acquisition opportunities in companies controlling proprietary dry fractionation technologies or possessing robust, non-GMO pea supply chains. The increasing market share of isolates and textured protein indicates an inflection point towards higher-value applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Dry Fractionation | Scaling advanced fractionation facilities allows producers to meet demand for high-purity isolates in Europe. |
| Investment in Flavor Masking R&D | Addressing "beany" off-notes improves yellow pea protein's applicability across diverse food matrices. |
| Secure Non-GMO Supply Chain Partnerships | Ensuring consistent, certified non-GMO pea supply is critical for clean-label product positioning in the United States. |
| Co-development of Customized Protein Systems | Partnerships with food manufacturers drive innovation in functionally optimized protein solutions for dairy alternatives. |
| Expansion into Asia-Pacific Markets | Targeting growing middle-class populations in China and India unlocks new growth vectors for fortified foods. |
Research Approach
Initial hypotheses were tested against primary input from food manufacturing R&D heads, ingredient procurement managers, and nutraceutical product developers, then refined through iterative analysis. This involved combining insights from in-depth interviews with secondary validation from FDA filings, EFSA guidance documents, and customs trade data. A rigorous triangulation process, integrating both bottom-up market sizing and top-down validation, ensured data accuracy.
Variance decomposition attributed market growth to shifts in product type, application, end-user segments, and regional regulatory frameworks across the analysis window. Compound annual growth rates were derived by extrapolating historical trends and projecting future demand drivers. The analytical framework integrated inputs such as raw material price stability and evolving consumer preference shifts for plant-based diets.
Material uncertainties — including climate change impacts on pea harvests and sudden shifts in global trade policies — sit outside the modeled envelope. Forecasts reflect assumptions based on current market dynamics and regulatory landscapes. Practitioners should keep alternative scenarios live as agricultural yields and clean-label standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
India Plant Based Meat Alternatives Market
Plant Based Food
Fava Bean Protein Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
New Jersey Vegan Products Market
Plant Based Food
Global Plant Protein Market
Plant Based Food
Plant-Based Frozen Dessert Market
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Soy Food Products Market
Plant Based Food
Global Organic Soy Protein Market
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Organic Rice Protein Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
Soy Protein Market
Plant Based Food
Tempeh Market
Plant Based Food
Targeting Pod Market