
 India Plant Based Meat Alternatives Market | 2026-2036
India Plant Based Meat Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
India Plant Based Meat Alternatives Market Insights
Quick-service restaurant procurement is shifting toward plant-based patties and nuggets as chains seek to diversify protein menus. GoodDot leverages its Rajasthan manufacturing base to supply foodservice operators across North India. Blue Tribe anchors its position through specialized burger and sausage formulations targeting premium urban outlets. Imagine Meats competes via Bollywood-backed brand recognition and direct-to-consumer channel control in metro markets.
India plant based meat alternatives comprise protein-isolate matrices extruded into fibrous textures mimicking animal muscle structure, typically formulated with soy or pea protein isolates, binding hydrocolloids, and lipid fractions to achieve chew profiles and moisture retention comparable to conventional meat. The primary commercial purpose is to serve as drop-in replacements in existing cooking workflows across foodservice and retail channels. Burgers dominate current volume due to familiar format and grilling compatibility, while sausages capture expanding quick-service breakfast and snacking occasions. Pea protein isolates are gaining fastest among source categories as manufacturers seek to differentiate from legacy soy offerings and address allergen-labeling preferences.
FSSAI standards for novel plant protein labeling and safety testing shape product approval timelines and interstate distribution eligibility for domestic manufacturers. BIS nutritional fortification guidelines and state-level food safety commissioner enforcement in Maharashtra and Gujarat further segment compliance burdens across production clusters. Stakeholders must monitor evolving PLI scheme eligibility for alternative protein infrastructure and anticipate how state-level organic and clean-label certifications will reshape consumer trust thresholds.
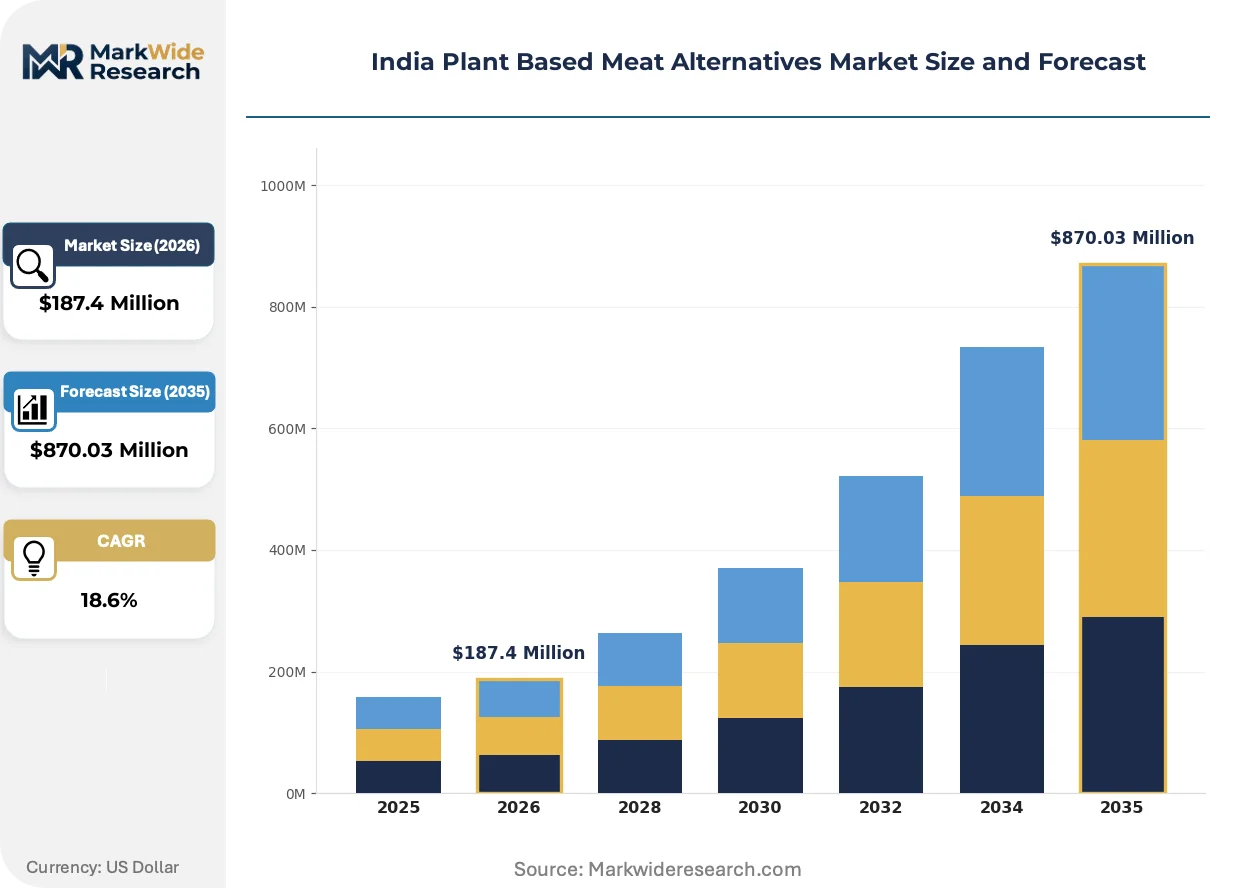
Market Dynamics
Quick-service restaurant chains in Mumbai and Delhi are expanding plant-based menu options, creating procurement pull that concentrates demand among flexitarian consumers in Maharashtra and Karnataka while compressing product certification timelines under FSSAI's evolving novel protein standards.
Growth Catalysts
- Pea protein isolate adoption:Manufacturers differentiate from legacy soy formulations to address allergen-labeling preferences and expand foodservice compatibility.
- FSSAI novel protein framework:Accelerating product approval timelines enables faster interstate distribution eligibility for domestic producers.
- Quick-service restaurant procurement:Chains seek drop-in protein replacements for existing grilling workflows, driving volume concentration in burger and sausage formats.
Market Restraints
- Binding hydrocolloid cost volatility:Input price swings for texturizing agents compress margin predictability for extruded protein manufacturers.
- Rajasthan production cluster concentration:Geographic dependence on North Indian manufacturing bases creates logistics vulnerability for pan-India distribution.
- Sensory fidelity ceiling:Current extrusion technology cannot replicate the fibrous chew of whole-muscle cuts, limiting premium positioning.
Strategic Opportunities
- Karnataka flexitarian penetration:Bangalore's urban consumer base remains underdeveloped relative to Maharashtra, offering white-space expansion.
- Direct-to-consumer channel control:Metro markets enable brand-owned distribution bypassing traditional retail slotting fees.
- PLI scheme infrastructure eligibility:Alternative protein manufacturing investments may qualify for production-linked incentive support.
Industry Challenges
- FSSAI-BIS compliance layering:Manufacturers navigate overlapping national labeling standards and state-level food safety commissioner enforcement in Gujarat and Maharashtra.
- Food technologist talent scarcity:Protein extrusion and lipid fraction formulation expertise concentrates with legacy ingredient suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Plant Based Meat Alternatives Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Burgers, Sausages, Nuggets, Meatballs Source: Soy, Pea, Wheat, Rice Distribution Channel: Supermarkets, Online Retail, Health Stores, Restaurants End User: Vegetarians, Flexitarians, Vegans, Meat Reducers |
| Companies Covered | GoodDot, Greenest Foods, Vezlay Foods, Blue Tribe, Wakao Foods, Imagine Meats, Evo Foods, Ahimsa Foods, Vegolution, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Plant Based Meat Alternatives Market Trends and Innovations
Extrusion technology advancement and regulatory clarity are compressing the gap between plant protein functionality and animal meat performance, while procurement patterns shift toward specialized burger and sausage formulations.
High-moisture extrusion is unifying protein-isolate matrices into fibrous textures that replicate animal muscle structure. Foodservice operators in Delhi and Mumbai are adopting these formulations for grilling compatibility. This convergence is unifying previously separate equipment lines and shortening kitchen retraining requirements.
FSSAI's evolving food safety standards for novel proteins are mandating specific safety testing protocols and label disclosure requirements. Domestic manufacturers face compressed approval timelines but expanded interstate distribution eligibility. Maharashtra and Gujarat state-level enforcement creates segmented compliance burdens across production clusters.
Flexitarian consumers in urban Maharashtra are rotating toward premium urban outlets that offer specialized burger and sausage formats. Quick-service breakfast and snacking occasions are displacing traditional retail frozen formats. This behavioral shift concentrates most visibly in Mumbai's quick-service restaurant chains.
India Plant Based Meat Alternatives Market Segmentation
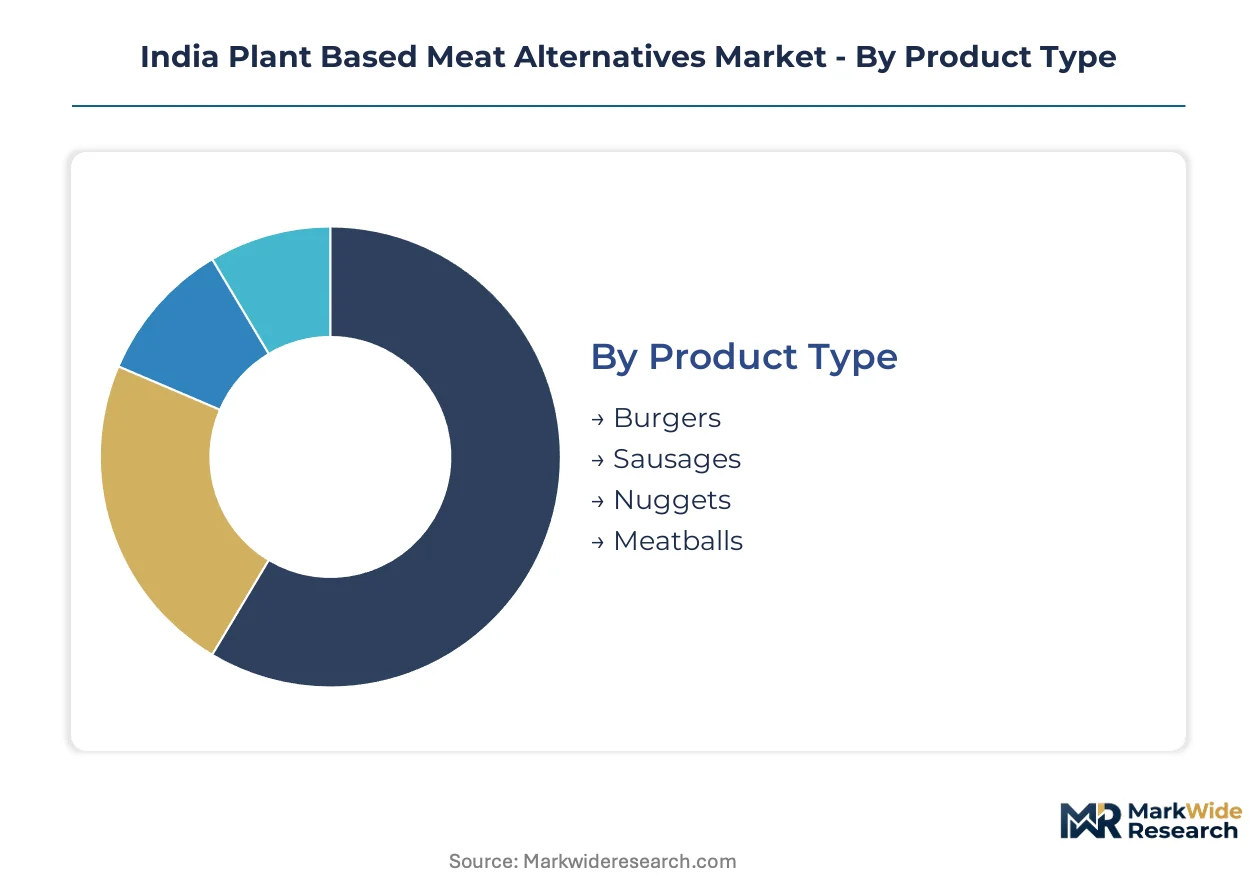
Segmentation in India's plant-based meat alternatives market reveals distinct procurement patterns across product formats and protein sources. Understanding these divisions exposes where volume concentrates versus where premium pricing power develops.
Product Type:
Burgers dominate volume through quick-service restaurant compatibility, while sausages command premium positioning in breakfast and snacking channels.
- Burgers:Extruded soy or pea protein patties formulated for direct grilling substitution. Demand concentrates in Mumbai and Delhi quick-service chains where drop-in workflow compatibility drives procurement contracts.
- Sausages:Cased protein emulsions requiring specialized hydrocolloid binding for snap and juiciness retention. Premium urban outlets in Bangalore and Pune are expanding breakfast menu placements, though volume trails burgers significantly.
- Nuggets:Battered and breaded bite-sized formats targeting children's menus and snacking occasions in metro foodservice.
- Meatballs:Spherical extruded products finding traction in casual dining curry and pasta applications across Maharashtra.
Today's leader: Burgers. Tomorrow's challenger: Sausages.
Source:
Protein isolate selection determines allergen labeling, extrusion behavior, and differentiation from legacy offerings in domestic manufacturing.
- Pea:Hypoallergenic isolate gaining fastest among manufacturers seeking soy differentiation. Rajasthan production clusters favor pea for its cleaner label appeal in export-oriented and premium domestic channels.
- Soy:Mature isolate infrastructure with established supply chains and cost advantages. Volume concentrates in mass-market retail and institutional foodservice where price sensitivity dominates procurement.
- Wheat:Gluten-based texturizing protein used in hybrid formulations to reduce isolate costs and modify chew profiles.
- Rice:Emerging isolate category addressing combined soy and pea allergen concerns in niche premium positioning.
Pea protein is climbing the fastest as FSSAI labeling requirements harden and export eligibility expands.
Distribution Channel:
Channel selection dictates margin structure, brand control, and consumer education requirements for plant-based meat alternatives.
- Supermarkets:Frozen and chilled retail formats requiring slotting fees and cold chain integrity. Volume concentrates in Mumbai and Delhi modern trade outlets where flexitarian trial occurs.
- Restaurants:Foodservice direct procurement bypassing retail markup, enabling formulation customization for specific kitchen workflows.
- Online Retail:Direct-to-consumer platforms allowing subscription models and controlled brand narrative in metro markets.
- Health Stores:Premium positioning in organic and wellness-focused retail formats with educated staff driving conversion.
Restaurants capture volume leadership. Online retail offers the steepest expansion trajectory for emerging brands.
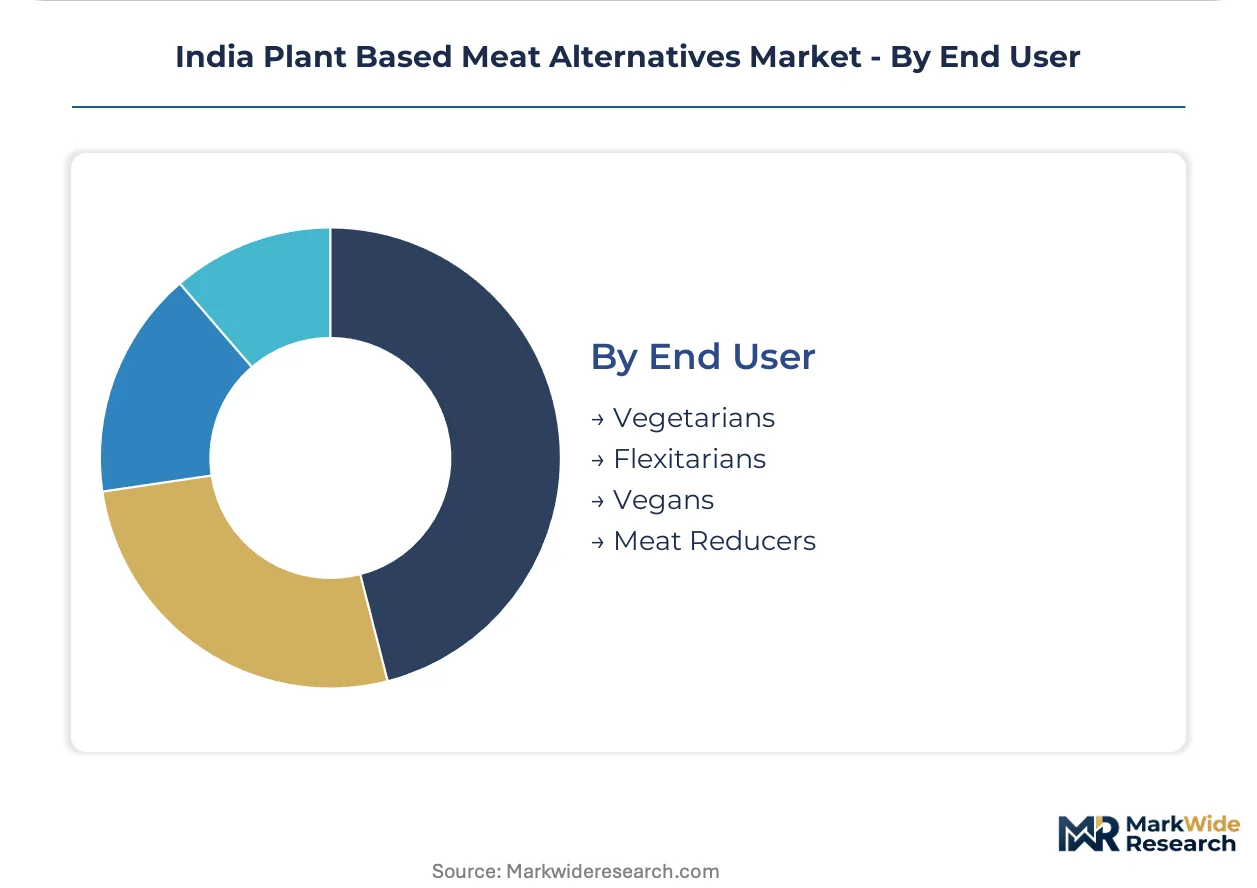
End User:
Consumer motivation segmentation separates price-driven substitution from values-driven premium purchasing in urban India.
- Flexitarians:Meat-reducing consumers seeking occasional plant-based alternatives without dietary commitment. This segment dominates Maharashtra and Karnataka urban demand, rotating between animal and plant proteins based on occasion and availability.
- Meat Reducers:Health-motivated consumers actively limiting animal protein intake for cardiovascular or environmental reasons, showing higher willingness to pay for sensory fidelity.
- Vegetarians:Long-term abstainers from animal meat seeking expanded protein variety rather than meat mimicry, often preferring traditional Indian formats over Western-style burgers.
- Vegans:Strictest dietary segment demanding complete animal product elimination, including scrutiny of binding hydrocolloids and lipid sources for hidden animal derivatives.
Flexitarians anchor current volume. Meat reducers represent the fastest-expanding trajectory as health consciousness penetrates tier-1 cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's Mumbai-Pune corridor anchors India's plant-based meat demand through quick-service restaurant procurement concentration and flexitarian consumer density.
Maharashtra
Mumbai quick-service chains drive burger and sausage procurement volumes for drop-in grilling workflows. FSSAI's evolving novel protein standards compress interstate distribution timelines for Maharashtra-based manufacturers. Pune's foodservice operators expand breakfast menu placements, creating secondary demand concentration beyond Mumbai's retail dominance.
Karnataka
Bangalore's urban flexitarian base remains underdeveloped relative to Maharashtra, offering white-space expansion for direct-to-consumer channels. State-level food safety commissioner enforcement aligns with national FSSAI frameworks but adds compliance layering for interstate shipments. Premium urban outlets in Whitefield and Koramangala test specialized sausage formats for breakfast occasions.
Gujarat
Ahmedabad and Surat manufacturing clusters supply hydrocolloid binding agents and lipid fractions to extruded protein producers across North India. BIS nutritional fortification guidelines intersect with state-level enforcement, segmenting compliance burdens for Gujarat-based ingredient suppliers. The state's chemical processing infrastructure supports texturizing agent production for pan-India distribution.
Delhi-NCR
National capital region quick-service restaurants pilot plant-based menu expansions, creating procurement pull from nearby Rajasthan production bases. FSSAI headquarters proximity accelerates product certification feedback loops for domestic manufacturers seeking interstate eligibility. Gurugram and Noida foodservice operators concentrate demand for nugget and patty formats in children's menu channels.
Rajasthan
Udaipur and Jaipur production facilities leverage North Indian geographic positioning for pan-India distribution logistics. PLI scheme infrastructure eligibility for alternative protein manufacturing attracts capital deployment to Rajasthan extrusion facilities. The state's manufacturing concentration creates vulnerability for supply chain resilience during logistics disruptions.
India Plant Based Meat Alternatives Market Competitive Landscape
Capacity expansion dominates the current landscape as domestic manufacturers scale extrusion infrastructure to meet quick-service procurement volumes. The vendor base clusters around three strategic archetypes: Bollywood-backed consumer brands controlling metro direct-to-consumer channels, Rajasthan-based foodservice suppliers leveraging manufacturing scale, and specialized formulation developers targeting premium burger and sausage textures. M&A activity remains limited given early-stage market development, while strategic partnerships between ingredient suppliers and restaurant chains accelerate product placement velocity.
Within the celebrity-backed brand tier, Imagine Meats occupies a position exemplifying direct-to-consumer channel control in Mumbai and Delhi metro markets. GoodDot and Blue Tribe represent contrasting archetypes: GoodDot anchors foodservice supply from its Rajasthan manufacturing base, while Blue Tribe exemplifies premium urban outlet specialization through burger and sausage formulation focus. Wakao Foods and Evo Foods sit within the emerging tier of challengers testing Karnataka and Gujarat expansion corridors.
| Leading Market Players |
|---|
| GoodDot |
| Greenest Foods |
| Vezlay Foods |
| Blue Tribe |
| Wakao Foods |
| Imagine Meats |
| Evo Foods |
| Ahimsa Foods |
| Vegolution |
| Others |
Pricing and Supply Chain Analysis
Bollywood-backed consumer brands and family-owned Rajasthan manufacturers anchor India's plant-based meat pricing discipline through divergent channel strategies. Direct-to-consumer operators command premium positioning via controlled metro distribution, while foodservice suppliers compete on volume scale through quick-service procurement contracts.
Pricing Analysis
Retailer markup layers dominate mass-market frozen formats, compressing manufacturer margins in supermarket channels. Three-tier pricing structure across premium, standard, and economy levels separates Bollywood-backed brands from Rajasthan foodservice suppliers and private-label retail offerings. Price differentiation hinges on FSSAI certification tier and cold-chain delivery infrastructure investment. Pricing pressure stems from hydrocolloid binding agent cost volatility, squeezing extruded protein producers. Quick-service restaurant procurement teams exhibit highest price sensitivity, while premium urban outlets absorb formulation premiums for sensory fidelity.
Supply Chain Analysis
Food technologist scarcity in Udaipur and Jaipur extrusion facilities limits Rajasthan production cluster expansion. Geographic supply concentration centers on India for pea protein isolate processing, with hydrocolloid texturizing agents sourcing from Gujarat chemical infrastructure. Raw material dependencies include imported pea protein concentrate, domestic soy isolate, and specialized lipid fractions for moisture retention. Single-source vulnerability runs through Rajasthan manufacturing concentration, creating logistics exposure during interstate distribution disruptions. Distribution runs through temperature-controlled trucking networks to Mumbai and Delhi quick-service hubs, with direct-to-consumer platforms bypassing traditional retail markup layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's plant-based meat alternatives market offers margin expansion through pea protein isolate adoption and premium urban outlet penetration. Cost compression in binding hydrocolloid sourcing and high-moisture extrusion scale-up enables tier-up pricing capture.
For Market Incumbents: Lock in quick-service procurement contracts through specialized burger and sausage formulation partnerships before emerging entrants secure Karnataka white-space. Secure backward integration into pea protein isolate processing to hedge against import cost volatility and FSSAI labeling compliance acceleration. For New Entrants and Emerging Players: Enter via direct-to-consumer subscription models in Bangalore's underdeveloped flexitarian base, bypassing retail slotting fee barriers. Target Karnataka health-conscious meat reducers through premium sausage breakfast positioning, leveraging lower competitive density versus Maharashtra saturation. For Investors and Strategic Acquirers: Valuations sit cheapest among Rajasthan-based foodservice suppliers lacking celebrity brand equity but possessing extrusion infrastructure eligible for PLI scheme support. Long-term viability hinges on FSSAI interstate distribution eligibility expansion and high-moisture extrusion patent portfolios. Monitor PLI scheme alternative protein infrastructure qualification announcements as capital deployment signal.| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Patent Filing | Secures sensory fidelity differentiation for premium burger and sausage positioning against legacy soy formulations. |
| Pea Protein Isolate Backward Integration | Captures cost structure control and FSSAI allergen-labeling compliance advantage in Rajasthan production clusters. |
| Direct-to-Consumer Platform Launch | Bypasses Mumbai and Delhi retail slotting fees while building subscription revenue in flexitarian metro segments. |
| Quick-Service Restaurant Co-Development | Locks in volume procurement through drop-in grilling workflow compatibility and specialized format customization. |
| Karnataka Distribution Expansion | Penetrates Bangalore's underdeveloped flexitarian base before incumbent brands consolidate breakfast menu placements. |
Research Methodology
Bottom-up foodservice procurement modeling reconciled against top-down ingredient supply tracking forms the analytical core of this study. Primary interviews with quick-service restaurant procurement directors, plant-based meat brand managers, FSSAI regulatory affairs specialists, and Rajasthan extrusion facility operators combined with secondary validation against FSSAI product approval databases, BIS nutritional fortification guidelines, and PLI scheme infrastructure eligibility notifications.
Input-output matrices mapped protein isolate sourcing volumes through extrusion capacity utilization to end-user channel shipments across the analysis window. Segmentation dimensions modeled include product format, protein source, distribution channel, and consumer motivation archetype. CAGRs derived from elasticity-adjusted penetration curves in Maharashtra and Karnataka urban clusters, with FSSAI approval timeline compression and quick-service menu expansion velocity as key forecast inputs.
The model holds under steady FSSAI regulatory clarity and PLI scheme continuity; deviation in binding hydrocolloid import cost spikes or interstate logistics disruptions would shift volume trajectories. Practitioners should monitor FSSAI novel protein framework amendments and Rajasthan production cluster expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Africa Pea Protein Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
Vegan Protein Blend Market
Plant Based Food
Rice Protein Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Germany Soy Protein Market
Plant Based Food
Flax-Based Protein Market
Plant Based Food
Plant Based Breads Market
Plant Based Food
Singapore Plant-Based Food and Beverages Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Plant-Based Wellness Foods Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Lentil Protein Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
United States Plant Protein Market