
 Global Organic Soy Protein Market | 2026-2036
Global Organic Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Soy Protein Market Outlook
Multi-source procurement toward vertically integrated supply chains is consolidating leverage among top processors. Archer Daniels Midland Company leverages its North American crushing footprint to secure organic bean flows. SunOpta Inc. anchors its position through certified organic processing infrastructure in the Upper Midwest. Cargill, Incorporated competes via backward integration into organic oilseed origination and farmer contracting programs.
Organic soy protein denotes defatted, minimally processed protein extracted from certified organic non-GMO soybeans, typically achieving isolate purity above 90% protein content through aqueous extraction and isoelectric precipitation. It serves primarily as a functional emulsifier, gelling agent, and complete amino acid source in formulated foods and nutritional products. Isolate commands the highest margin pool due to protein density and sports nutrition pull-through, while textured formats lead volume growth through plant-based meat analog applications. Powder form dominates current manufacturing throughput, though extruded formats are expanding via high-moisture extrusion lines serving food service channels.
FDA organic labeling enforcement and USDA National Organic Program accreditation shape product integrity claims and import eligibility for US-bound shipments. EFSA novel food assessments and EU organic regulation 2018/848 govern market access and certification reciprocity across European trading partners. Stakeholders must monitor evolving pesticide residue thresholds and carbon accounting rules that will determine competitive sourcing geographies and supplier qualification timelines.
Market Dynamics
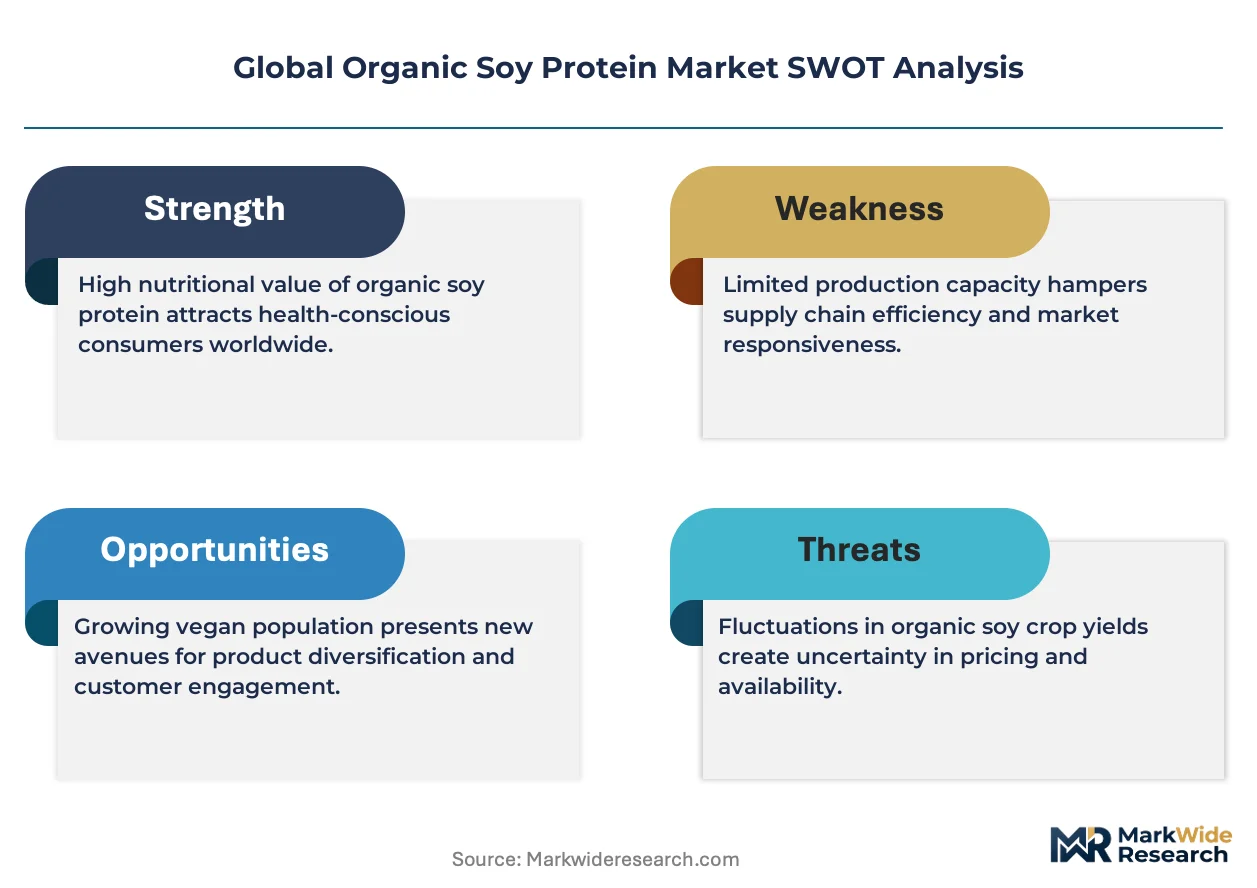
EU organic regulation 2018/848 and tightening pesticide residue thresholds are compressing supplier qualification timelines while concentrating procurement leverage among processors with captive organic oilseed origination.
Growth Catalysts
- EU Green Deal sustainability mandates:The Farm to Fork Strategy tightens criteria for imported protein crops, accelerating demand for certified organic isolates in German plant-based meat manufacturing.
- Clean-label consumer pull-through:US buyers with established organic certification infrastructure drive premium pricing for minimally processed protein isolates in sports nutrition formulations.
- High-moisture extrusion technology:Food service channels adopt extruded formats for meat analog applications, expanding throughput capacity for textured organic soy protein.
Market Restraints
- Organic soybean supply concentration:North American crushing infrastructure limits origination flexibility, creating input cost volatility during adverse growing seasons.
- EFSA novel food assessment timelines:European market access requires extended safety evaluations, delaying product launches for innovative isolate formulations.
- Pulse protein substitution:Pea and lentil concentrates compete for share in plant-based meat applications, pressuring organic soy volume growth in price-sensitive segments.
Strategic Opportunities
- Underpenetrated Brazilian organic cultivation:Cerrado expansion offers new origination geography outside traditional US and Argentine supply basins.
- Carbon accounting integration:EU CSRD disclosure requirements create differentiation for processors with verified low-emission aqueous extraction operations.
- Precision fermentation convergence:Hybrid formulations combining organic isolates with microbial proteins open novel texture profiles in premium nutrition bars.
Industry Challenges
- Organic certification skill scarcity:Auditor capacity constraints extend supplier onboarding timelines, delaying new origination program ramp-ups.
- Isoelectric precipitation capex intensity:Achieving 90%+ isolate purity requires specialized precipitation and membrane filtration infrastructure.
- USDA-NOP accreditation backlog:Third-party certifier queue delays create compliance timeline uncertainty for export-bound shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Soy Protein Market |
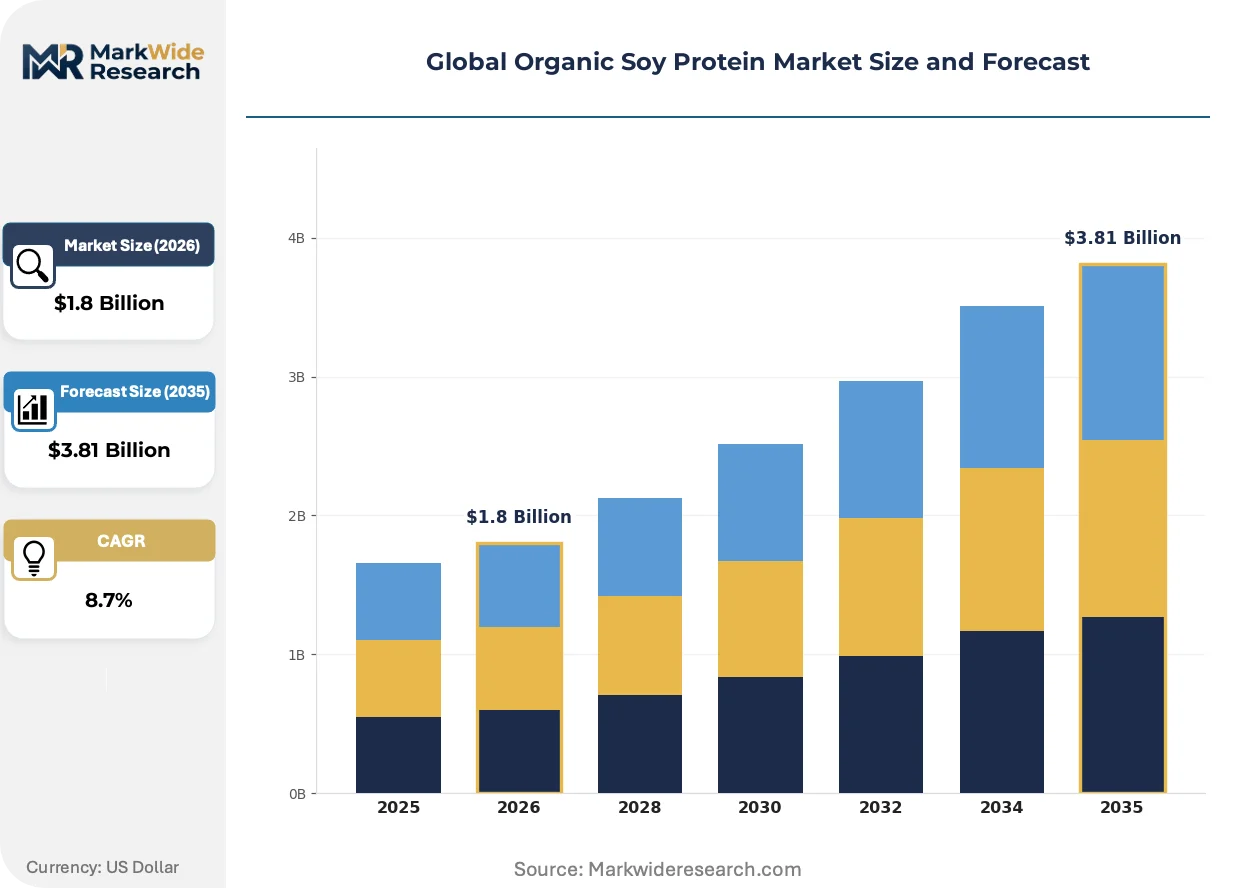
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Textured, Whole Bean Application: Food & Beverage, Nutritional Supplements, Animal Feed, Cosmetic Products Form: Powder, Liquid, Granulated, Extruded End User: Households, Food Manufacturers, Health Centers, Fitness Industry |
| Companies Covered | Archer Daniels Midland Company, SunOpta Inc., Devansoy Inc., Cargill, Incorporated, Bunge Limited, The Scoular Company, Harvest Innovations, World Food Processing, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Soy Protein Market Strategic Shifts
Processing technology convergence and regulatory disclosure mandates are compressing competitive differentiation around carbon transparency and extraction efficiency.
High-moisture extrusion lines serving food service channels are consolidating manufacturing throughput toward textured formats with superior fibrous bite. Quick-service chains in the United States adopt these extrudates for chicken-style analogs at accelerating pace. This shift is consolidating margin capture away from commodity powder suppliers toward integrated extrusion operators with formulation partnerships.
EU CSRD carbon disclosure rules now mandate Scope 3 reporting for imported protein crops, forcing processors to document embodied emissions from farm gate through aqueous extraction. German food manufacturers demand supplier-provided carbon intensity scores alongside organic certificates. Organic soy isolate imports face heightened documentation burdens, advantaging processors with vertically controlled origination in the Upper Midwest.
Clean-label preference in sports nutrition channels compresses formulation complexity, driving buyers toward single-ingredient isolates with minimal processing aids. Direct-to-consumer brands bypass traditional distribution layers, sourcing certified organic powder through specialized ingredient marketplaces. This channel disintermediation concentrates most visibly in California and New York metro clusters where subscription nutrition models dominate.
Global Organic Soy Protein Market Segmentation
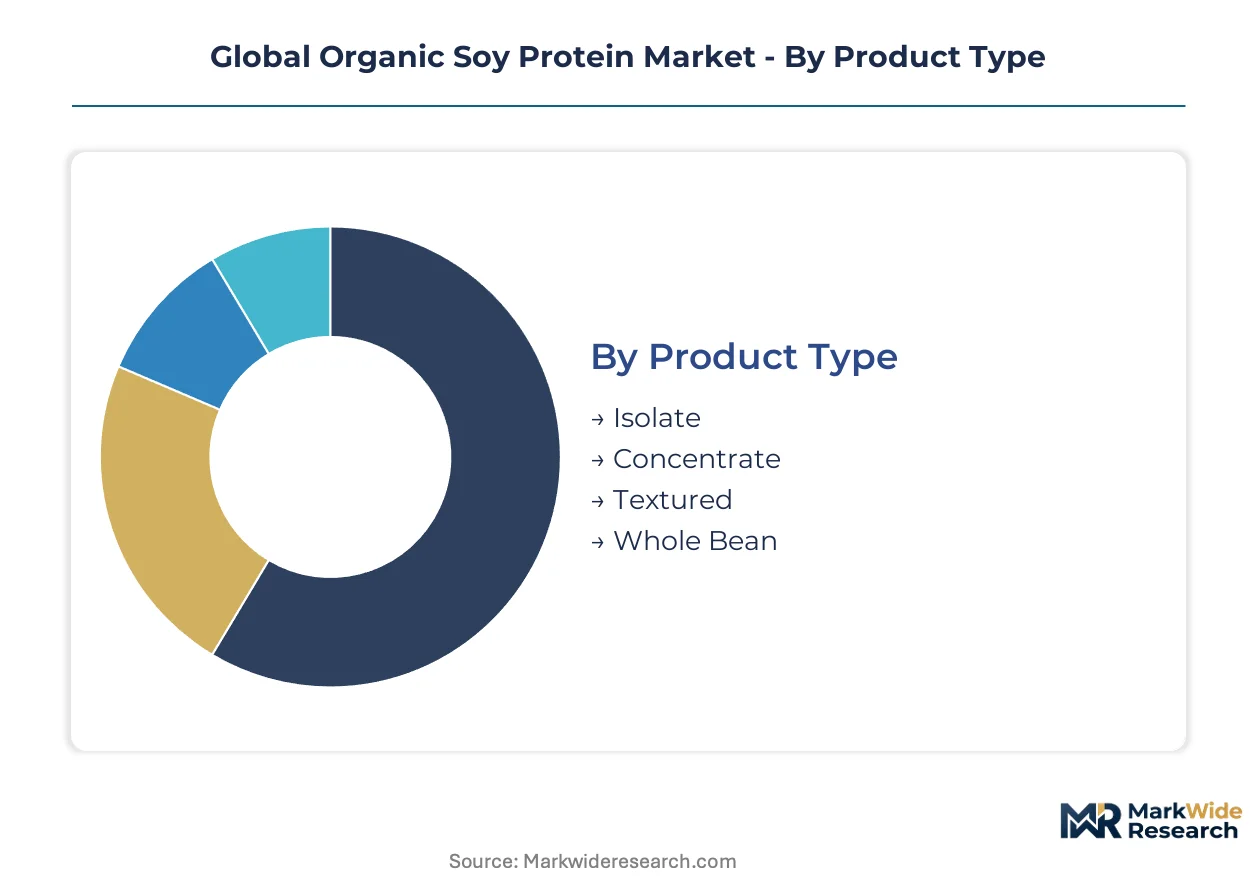
Organic soy protein buyers upgrade formulations based on functional requirements, certification tiers, and processing compatibility. Replacement cycles accelerate as food manufacturers reformulate for cleaner labels and improved texture profiles in plant-based alternatives.
Product Type:
Upgrade decisions pivot on protein density thresholds and emulsification performance required by target applications.
- Isolate:Defatted protein fraction achieving above 90% purity through aqueous extraction and isoelectric precipitation. German plant-based meat manufacturers anchor procurement of organic isolates for premium analog applications, though EFSA novel food assessments compress supplier qualification timelines.
- Concentrate:Intermediate protein content ranging from 65% to 85% with retained soluble carbohydrates and fiber. Sports nutrition formulators in the United States concentrate demand here, balancing cost efficiency against clean-label positioning requirements.
- Textured:Extruded formats with fibrous structure mimicking meat bite. High-moisture extrusion lines serving quick-service channels drive placement acceleration.
- Whole Bean:Minimally processed organic soybeans retaining full fat and fiber content. Specialty food manufacturers in California metro clusters source for artisanal applications.
Volume placements concentrate in Textured; the faster expansion belongs to Isolate.
Application:
Cost tier stratification separates premium nutritional positioning from commodity feed substitution.
- Food & Beverage:Plant-based meat analogs, dairy alternatives, and baked goods requiring emulsification and gelling functionality. EU Green Deal sustainability mandates tighten procurement criteria for German manufacturers sourcing certified organic isolates.
- Nutritional Supplements:Sports nutrition powders, meal replacements, and clinical nutrition formulations demanding complete amino acid profiles. Direct-to-consumer subscription models in New York metro clusters disintermediate traditional distribution.
- Animal Feed:Organic aquaculture and poultry operations seeking non-GMO protein inputs. USDA National Organic Program accreditation governs import eligibility for US-bound shipments.
- Cosmetic Products:Hair and skin formulations leveraging soy protein film-forming and moisture-binding properties. Niche positioning limits volume relative to ingestible applications.
Margin capture concentrates in Nutritional Supplements; Food & Beverage delivers the steepest volume trajectory.
Form:
Manufacturing throughput and supply chain configuration determine form selection for downstream compatibility.
- Powder:Spray-dried particles with extended shelf stability and reconstitution properties. Current manufacturing infrastructure dominates throughput.
- Liquid:Aqueous suspensions for ready-to-drink applications and industrial food processing. Refrigerated distribution requirements constrain geographic reach.
- Granulated:Agglomerated particles improving dispersibility in beverage systems. Health center procurement favors this format for clinical nutrition.
- Extruded:High-moisture and dry-expanded structures for meat analog texturization. Food service channel adoption accelerates capacity expansion.
Supply concentration favors Powder; Extruded formats gain share fastest through plant-based meat analog demand.
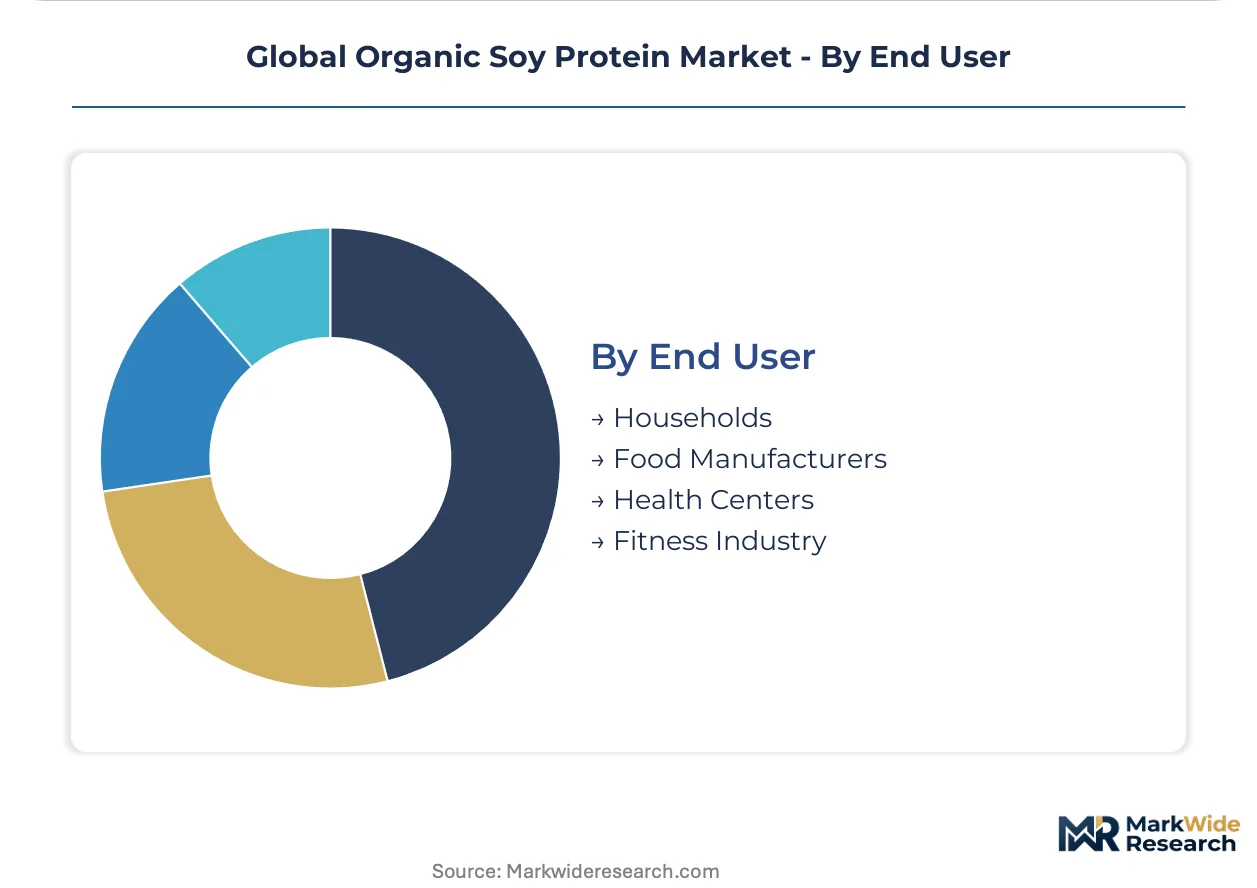
End User:
Customer type dictates procurement scale, certification documentation burden, and formulation technical support requirements.
- Households:Direct retail purchasers through natural product channels and subscription services. California and New York metro clusters dominate this fragmented demand base.
- Food Manufacturers:Industrial-scale buyers of certified organic isolates and textured formats for reformulation programs. German manufacturers exemplify procurement concentration under EU organic regulation 2018/848.
- Health Centers:Clinical nutrition and therapeutic feeding programs requiring batch traceability and organic certification documentation.
- Fitness Industry:Gym chains, sports teams, and performance nutrition retailers sourcing bulk protein for member services.
Procurement volume concentrates in Food Manufacturers; the Fitness Industry climbs fastest through subscription nutrition model expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic soybean crushing infrastructure concentrates in the Upper Midwest of the United States, where certified acreage and aqueous extraction facilities cluster within tight origination radii. German food manufacturers anchor European demand through plant-based meat reformulation programs. Brazilian Cerrado expansion offers new supply geography outside traditional North American and Argentine basins.
United States
Clean-label sports nutrition brands in California and New York metro clusters drive premium isolate procurement through direct-to-consumer subscription models. USDA National Organic Program accreditation governs import eligibility and product integrity claims for domestic-bound shipments. Archer Daniels Midland Company leverages its North American crushing footprint to secure organic bean flows across the Upper Midwest processing corridor.
Germany
Plant-based meat manufacturers anchor European demand expansion for certified organic isolates under tightening sustainability criteria. EU organic regulation 2018/848 and the Farm to Fork Strategy compress supplier qualification timelines for imported protein crops. Food manufacturers in Bavaria and North Rhine-Westphalia concentrate procurement leverage through reformulation partnerships with extrusion operators.
Brazil
Underpenetrated organic cultivation in the Cerrado biome offers origination diversification outside traditional US and Argentine supply basins. The country's national agricultural regulator oversees conversion protocols for certified organic soybean expansion. Processors in Mato Grosso and Goiás pilot farmer contracting programs to build captive organic oilseed flows for export markets.
China
Domestic food manufacturers import certified organic isolates for infant formula and clinical nutrition applications requiring non-GMO documentation. SAMR and national food safety standards govern ingredient registration and label claims for organic protein products. Processing clusters in Shandong and Jiangsu provinces concentrate aqueous extraction capacity serving Asia-Pacific formulation demand.
Canada
Prairie organic soybean acreage expands through farmer transition programs targeting North American protein ingredient supply gaps. Health Canada and the Canadian Food Inspection Agency administer organic certification reciprocity with US and EU trading partners. Crushing infrastructure in Manitoba and Saskatchewan develops backward integration into certified organic origination for isolate export.
Global Organic Soy Protein Market Competitive Environment
Global majors compete with regional champions across origination and extraction technology, creating tiered competitive dynamics around certified organic supply chain control. The vendor base concentrates among processors with captive farmer contracting programs and dedicated organic processing infrastructure. Three archetypes dominate: multinational agribusinesses with North American crushing networks, specialized organic processors with Upper Midwest facility concentration, and diversified ingredient suppliers with backward integration into oilseed origination. M&A activity targets certified organic processing assets, while capacity expansion focuses on high-moisture extrusion lines for textured format growth.
Among North American-based agribusinesses, Archer Daniels Midland Company and Cargill, Incorporated exemplify the multinational archetype with integrated origination and extraction capabilities. SunOpta Inc. occupies a specialist position through certified organic processing infrastructure concentration. Devansoy Inc. and Bunge Limited represent diversified ingredient suppliers with backward integration into farmer contracting programs. The Scoular Company, Harvest Innovations, World Food Processing, and DuPont anchor additional competitive positions across isolate, concentrate, and textured format supply.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| SunOpta Inc. |
| Devansoy Inc. |
| Cargill, Incorporated |
| Bunge Limited |
| The Scoular Company |
| Harvest Innovations |
| World Food Processing |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
Organic soybean futures on the Chicago Board of Trade serve as the primary price discovery mechanism, cascading through certified organic premiums and aqueous extraction cost layers to stratify isolate pricing across German food manufacturers and US sports nutrition brands. This commodity benchmark linkage compresses margin pools for processors lacking captive origination while amplifying pricing power for those with Upper Midwest crushing infrastructure.
Pricing Analysis
Certification documentation and carbon intensity scoring are unbundled from base isolate quotes, with EU CSRD-compliant emissions reporting commanding separate fee structures. Three-tier pricing structure across premium, standard, and economy levels separates USDA-NOP-accredited isolates with full traceability from transitional organic grades and conventional non-GMO alternatives. Pricing pressure stems from pulse protein substitution in plant-based meat applications, with pea and lentil concentrates eroding volume share in price-sensitive quick-service channels. Animal feed buyers exhibit highest price sensitivity due to commodity substitution options, while German plant-based meat manufacturers absorb premium tiers for EFSA-compliant isolate grades.
Supply Chain Analysis
Specialized technician availability in Minnesota and Iowa processing corridors constrains capacity expansion timelines for isoelectric precipitation infrastructure. Supply concentrates in the United States, Argentina, and emerging Brazilian Cerrado zones, with North American crushing infrastructure drawing from Upper Midwest certified organic acreage. Raw material flows hinge on non-GMO seed stock, aqueous extraction chemicals, and membrane filtration components. Single-source vulnerability runs through concentrated organic soybean origination in drought-exposed growing regions. Distribution runs through food ingredient marketplaces serving direct-to-consumer brands and extrusion operators with formulation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU organic regulation 2018/848 and tightening pesticide residue thresholds erect formidable barrier-to-entry moats favoring processors with established certification infrastructure and captive farmer networks.
For Market Incumbents: Deploy backward integration into Brazilian Cerrado origination to diversify supply geography beyond North American concentration risk. Anchor market position through high-moisture extrusion capacity additions serving quick-service channel partnerships, while investing in carbon accounting verification systems to meet EU CSRD disclosure mandates from German manufacturing buyers. Pulse protein substitution in price-sensitive plant-based meat segments represents the primary demand threat requiring formulation flexibility investments. For New Entrants and Emerging Players: Precision fermentation convergence technologies offer entry pathways into hybrid protein formulations combining organic isolates with microbial proteins for premium nutrition bar applications. Target underpenetrated Brazilian organic cultivation zones through farmer contracting programs that bypass established Upper Midwest supply chains. Direct-to-consumer subscription models in California and New York metro clusters provide channel disintermediation angles with reduced certification documentation burdens relative to industrial food manufacturer procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized organic processors with certified infrastructure in the Upper Midwest during periods of organic soybean supply volatility. Long-term viability centers on five-to-ten year windows where EU sustainability mandates and US clean-label preferences structurally expand addressable demand for certified isolates. Monitor EFSA novel food assessment timeline compression as the critical inflection signal indicating European market access acceleration or deceleration for innovative isolate formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Origination | Cargill's farmer contracting programs in Mato Grosso secure certified bean flows outside traditional US supply basins. |
| High-Moisture Extrusion Capacity Expansion | Integrated extrusion operators capture margin migration from commodity powder suppliers through food service channel partnerships. |
| Carbon Accounting Verification Investment | Processors with documented low-emission aqueous extraction operations meet EU CSRD Scope 3 reporting requirements from German buyers. |
| Precision Fermentation Hybrid Formulation | Novel texture profiles in premium nutrition bars open differentiation space beyond commodity isolate competition. |
| Direct-to-Consumer Channel Development | Subscription nutrition models in California metro clusters bypass traditional distribution layers and concentrate margin capture. |
Study Parameters
USDA National Organic Program accreditation databases, EU organic regulation compliance filings, and customs trade records formed the secondary backbone for supply chain mapping and certification infrastructure assessment. Primary interviews with organic processing plant managers, procurement leads at German food manufacturers, aqueous extraction technology specialists, and farmer contracting program directors validated capacity utilization rates and origination cost structures. Bottom-up isolate production estimates triangulated against top-down protein ingredient demand projections from sports nutrition and plant-based meat channels.
Historical organic soybean price trendlines and certified acreage expansion patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tiers, application categories, form factors, and end-user archetypes with additional granularity on EU versus US regulatory compliance clusters. CAGRs were derived through weighted average growth rate synthesis across demand drivers and supply constraints. Forecast inputs incorporated EFSA novel food assessment pipeline status and high-moisture extrusion line capacity additions serving food service channels.
Several conditions sit outside the modeled scope, including extreme weather events compressing North American organic soybean yields, abrupt EU pesticide residue threshold revisions, and breakthrough precision fermentation technologies displacing isolate demand. Forecasts reflect assumptions around certification auditor capacity expansion and Brazilian organic conversion protocol stability. Material deviation in organic soybean supply concentration or EFSA assessment timeline compression warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Rice Protein Market
Plant Based Food
Plant-Based Food and Beverages Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Europe Tofu Market
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
Italy Plant Protein Market
Plant Based Food
Vegan Pizza Crust Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Yucca Extract Market
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Vegan Food Market
Plant Based Food
Enzyme-Based Plant Protein Market
Plant Based Food
Plant Based Pasta Market