
 Tempeh Market | 2026-2036
Tempeh Market Size, Share, and Industry Trends Forecast 2026-2036
Tempeh Market Outlook
Organic certification tier upgrades is unwinding conventional commoditization across the tempeh industry. Maple Leaf Foods leverages its North American refrigerated distribution network to sustain shelf-stable organic lines. Lightlife Foods anchors the US retail channel through broad grocery placement. House Foods Group dominates Japanese supermarket tempeh with standardized fermentation protocols.
Tempeh denotes a fermented soybean cake produced through Rhizopus oligosporus mold cultivation on dehulled, cooked legumes, typically yielding a protein content of 18-20% and firm sliceable texture suitable for grilling, crumbling, or marinating. The product serves commercial kitchens and retail consumers seeking minimally processed, whole-food protein alternatives to textured vegetable isolates. Organic tempeh commands premium shelf positioning as supply scarcity and certification costs restrict producer entry. Frozen form extends distribution reach beyond fresh-product logistics constraints. Food service providers represent the fastest-growing end-user channel as institutional buyers reformulate menus around plant-based center-plate options.
FDA food safety regulations govern US tempeh fermentation facility inspections and hazard controls, while EU EFSA novel food assessments shape import access for non-traditional tempeh substrates. Indonesia's national food agency enforces halal certification standards that determine export eligibility across Southeast Asian markets. Stakeholders must monitor evolving protein-labeling claims enforcement and fermentation-derived allergen disclosure requirements across their priority jurisdictions.
Market Dynamics
EU Green Deal sustainability mandates are forcing food service providers to reformulate protein sourcing, redirecting procurement toward fermented whole-food alternatives and away from highly processed isolates. This regulatory pressure intersects with Indonesia's concentrated traditional production base to reshape competitive entry barriers.
Growth Catalysts
- EU Green Deal procurement mandates:Institutional buyers across European food service channels face binding sustainability disclosure requirements that favor minimally processed, low-carbon protein inputs over energy-intensive extruded isolates.
- Fermentation biotechnology maturation:Standardized Rhizopus oligosporus inoculation protocols developed through Japanese university research programs now transfer to commercial facilities, reducing batch variability and spoilage rates.
- Indonesian export infrastructure expansion:Javanese production clusters near Surabaya and Yogyakarta have established dedicated cold-chain corridors serving halal-certified markets across Southeast Asia and the Middle East.
Market Restraints
- Soybean price volatility:Tempeh margins compress when Chicago Board of Trade soybean futures spike, as the product lacks pass-through pricing power against lower-cost protein alternatives in retail channels.
- Fresh-product logistics constraints:The seven-to-fourteen-day refrigerated shelf life of unpasteurized tempeh limits distribution radius from production facilities, constraining market reach beyond urban clusters.
- Novel food assessment friction:EU EFSA classification of non-soy legume substrates as novel foods imposes eighteen-to-thirty-six-month approval timelines for product line extensions using chickpea, lentil, or lupin bases.
Strategic Opportunities
- US food service channel underpenetration:College and university dining contracts represent an open segment where procurement officers seek clean-label protein alternatives compliant with USDA organic standards.
- Frozen format distribution innovation:Blast-freezing at point of production preserves texture integrity through extended supply chains, enabling shelf-stable retail placement beyond fresh-product logistics limits.
- Halal certification arbitrage:Indonesia's national halal mandate, enforced by the national food agency, creates export eligibility advantages into Malaysian, Singaporean, and Gulf state markets where competitors face compliance gaps.
Industry Challenges
- Artisanal skill scarcity:Traditional tempeh production relies on tacit knowledge of mycelial colonization timing that commercial facilities struggle to codify, creating quality control vulnerabilities at scale.
- Organic certification timeline compression:Three-year land-use conversion requirements and annual audit costs block rapid producer entry into premium-tier positioning, freezing competitive dynamics among incumbent certified operators.
- Cross-contamination protocol complexity:Facilities producing both soy and non-soy variants must implement segregated fermentation chambers and cleaning validation to satisfy allergen disclosure requirements under FDA hazard controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tempeh Market |
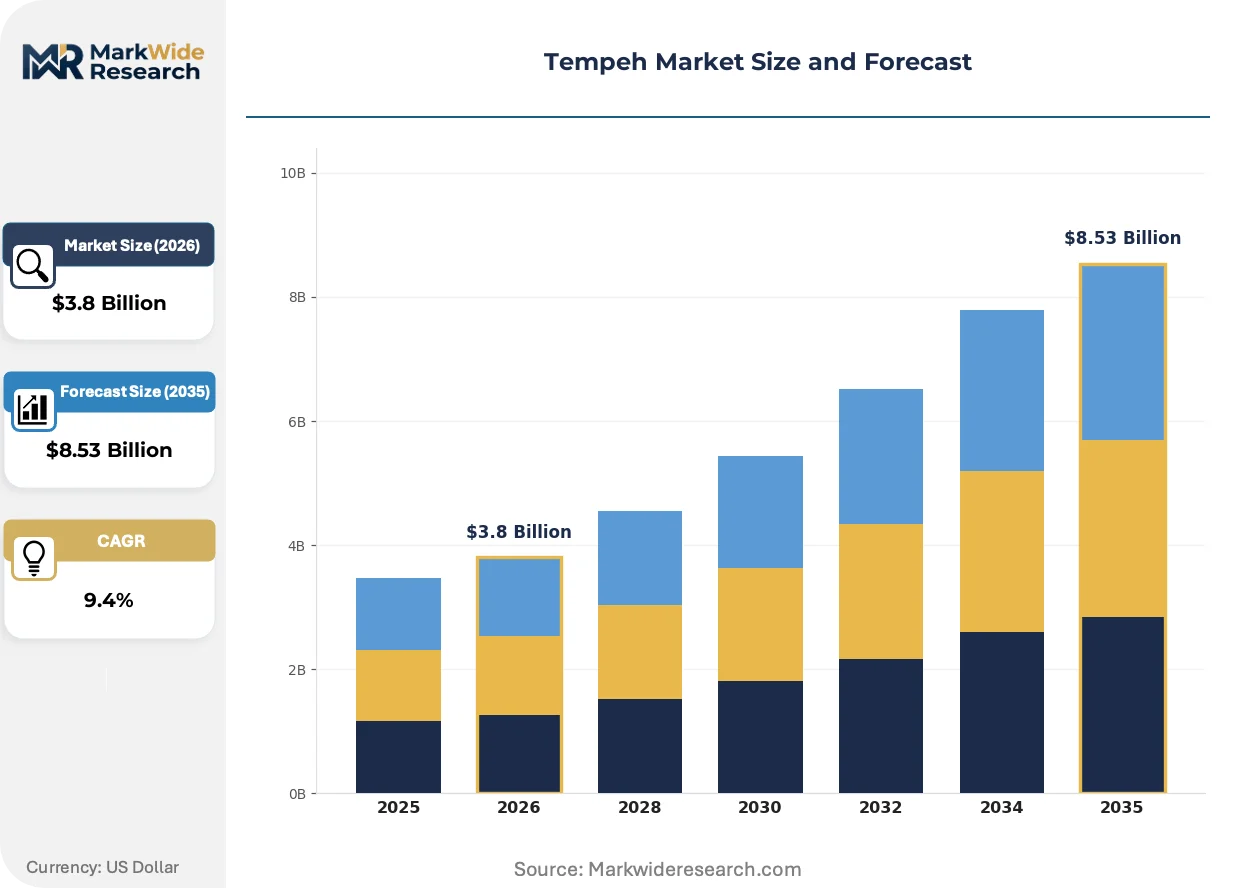
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Tempeh, Conventional Tempeh, Flavored Tempeh, Gluten-Free Tempeh Form: Fresh, Frozen, Dried, Pre-Cooked Packaging Type: Bulk Packaging, Retail Packaging, Vacuum-Sealed Packaging, Recyclable Packaging End User: Restaurants, Grocery Stores, Food Service Providers, Home Consumers |
| Companies Covered | Maple Leaf Foods, The Tofoo Company, Lightlife Foods, Vegolution India Private Limited, Noble Bean, Turtle Island Foods, House Foods Group, Tempe Azaki, Nutrisoy Pty Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tempeh Market Strategic Shifts
Controlled-environment fermentation systems are displacing open-tray traditional methods, compressing production cycles while expanding substrate flexibility beyond conventional soy bases. This technological pivot intersects with regulatory pressure and procurement model evolution to reshape competitive positioning.
Automated fermentation chambers with precise humidity and temperature modulation are displacing artisanal open-air production across commercial-scale facilities. North American contract manufacturers adopt these systems to achieve batch consistency required by retail grocery buyers. The technology is displacing small-batch craft producers from mid-market shelf positioning as unit economics favor capital-intensive continuous operations.
EU EFSA novel food assessments are tightening substrate approval pathways for legume alternatives to conventional soy. Manufacturers seeking chickpea or lupin-based formulations face extended toxicology study requirements and administrative review periods. European import-dependent markets are responding by consolidating supplier relationships with Indonesian facilities that maintain exclusively soy-based production to bypass assessment delays.
Food service procurement officers are consolidating protein vendor lists and demanding third-party organic certification as a non-negotiable entry credential. This concentration of buying power squeezes uncertified regional producers from institutional contract bidding. The shift is most visible across US college dining systems and European hospital catering networks where sustainability scorecards determine vendor selection.
Tempeh Market Segmentation
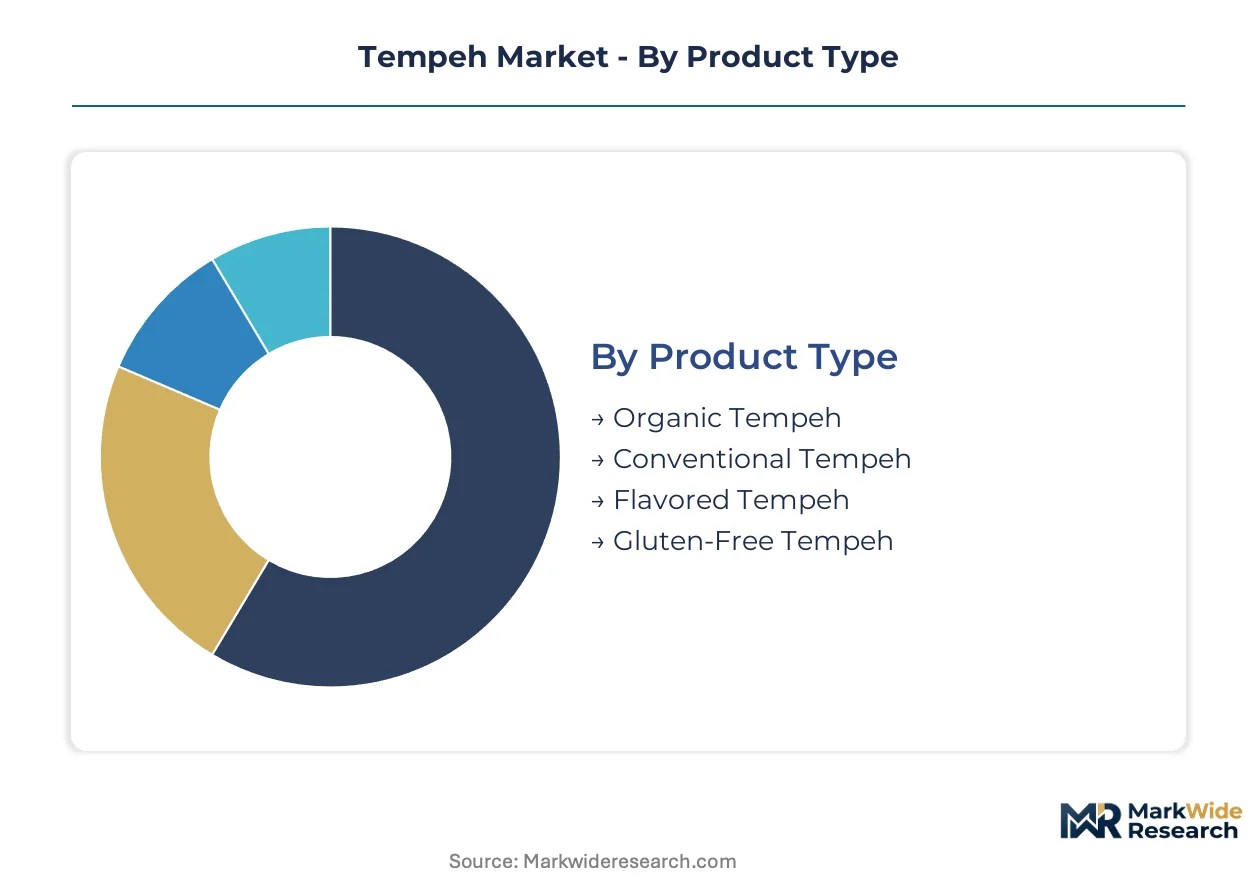
Tempeh market segmentation reveals divergent growth trajectories across certification tiers and distribution formats. Product positioning varies sharply between domestic Indonesian consumption patterns and export-oriented premium channels demanding extended shelf stability.
Product Type:
Organic certification concentration dominates export revenue streams while conventional products anchor domestic Indonesian volume. Geographic spread separates premium-tier positioning from commodity-grade supply.
- Organic Tempeh:USDA and EU organic certification mandates three-year land conversion and annual audit protocols. European food service procurement officers now require certified sourcing for institutional contracts, compressing uncertified producer margins. Organic tempeh commands dedicated refrigerated shelf space in North American natural grocery channels.
- Conventional Tempeh:Standard fermentation without certification documentation supplies price-sensitive retail and traditional wet-market channels. Indonesian domestic consumption concentrates here, with Javanese production clusters serving local daily protein needs through established distribution cooperatives.
- Flavored Tempeh:Marinated variants with soy, teriyaki, or spice infusions target convenience-oriented retail segments.
- Gluten-Free Tempeh:Segregated production protocols address celiac-sensitive consumer bases in North American and European markets.
Organic tempeh commands the established base. The steepest expansion runs through flavored variants targeting convenience-oriented retail.
Form:
Fresh versus frozen formats create distinct logistics economics and geographic reach boundaries. Cost tier separation between premium fresh and value frozen drives channel allocation decisions.
- Frozen:Blast-freezing at production preserves mycelial texture integrity through extended supply chains. North American contract manufacturers leverage frozen formats to penetrate retail grocery beyond fresh-product radius constraints. Frozen tempeh enables halal-certified Indonesian exports into Gulf state supermarkets.
- Fresh:Seven-to-fourteen-day refrigerated shelf life limits distribution to urban production proximities. Fresh tempeh dominates Indonesian domestic wet markets and Japanese supermarket deli sections where rapid turnover justifies logistics intensity.
- Dried:Dehydrated shelf-stable formats serve backpacking and emergency food supply niches.
- Pre-Cooked:Ready-to-eat marinated slices target convenience retail and grab-and-go food service applications.
Fresh tempeh retains volume leadership in traditional markets. Frozen formats are climbing the fastest as export infrastructure matures.
Packaging Type:
Packaging sophistication correlates with retail channel tier and sustainability disclosure requirements. Customer type differentiation separates institutional bulk from branded retail presentation.
- Vacuum-Sealed Packaging:Modified atmosphere sealing extends shelf life without pasteurization, preserving live-culture probiotic claims. Japanese and European retailers demand vacuum-sealed presentation for premium refrigerated placement.
- Retail Packaging:Branded consumer-facing units with nutritional labeling and recipe suggestions dominate North American natural grocery sets. Retail packaging carries organic certification logos as mandatory entry credentials.
- Bulk Packaging:Food service totes and institutional containers supply restaurant prep kitchens and college dining central commissaries.
- Recyclable Packaging:EU Green Deal compliance pressures drive fiber-based tray and film transitions across European export shipments.
Vacuum-sealed packaging holds the established base. Recyclable formats are gaining share fastest as EU procurement mandates tighten.
End User:
Application concentration varies between prepared-food service and at-home preparation contexts. Volume scale separates institutional procurement from fragmented consumer purchase patterns.
- Food Service Providers:College dining contracts, hospital catering networks, and corporate cafeteria operators consolidate vendor lists around third-party certified suppliers. USDA organic compliance and sustainability scorecard alignment determine contract eligibility.
- Restaurants:Chef-driven demand for clean-label protein alternatives drives menu reformulation toward tempeh-based center-plate options.
- Grocery Stores:Refrigerated and frozen retail placement competes for shelf space against textured vegetable protein isolates.
- Home Consumers:Direct-to-subscription and farmers market channels serve fermentation-enthusiast niches seeking unpasteurized traditional preparations.
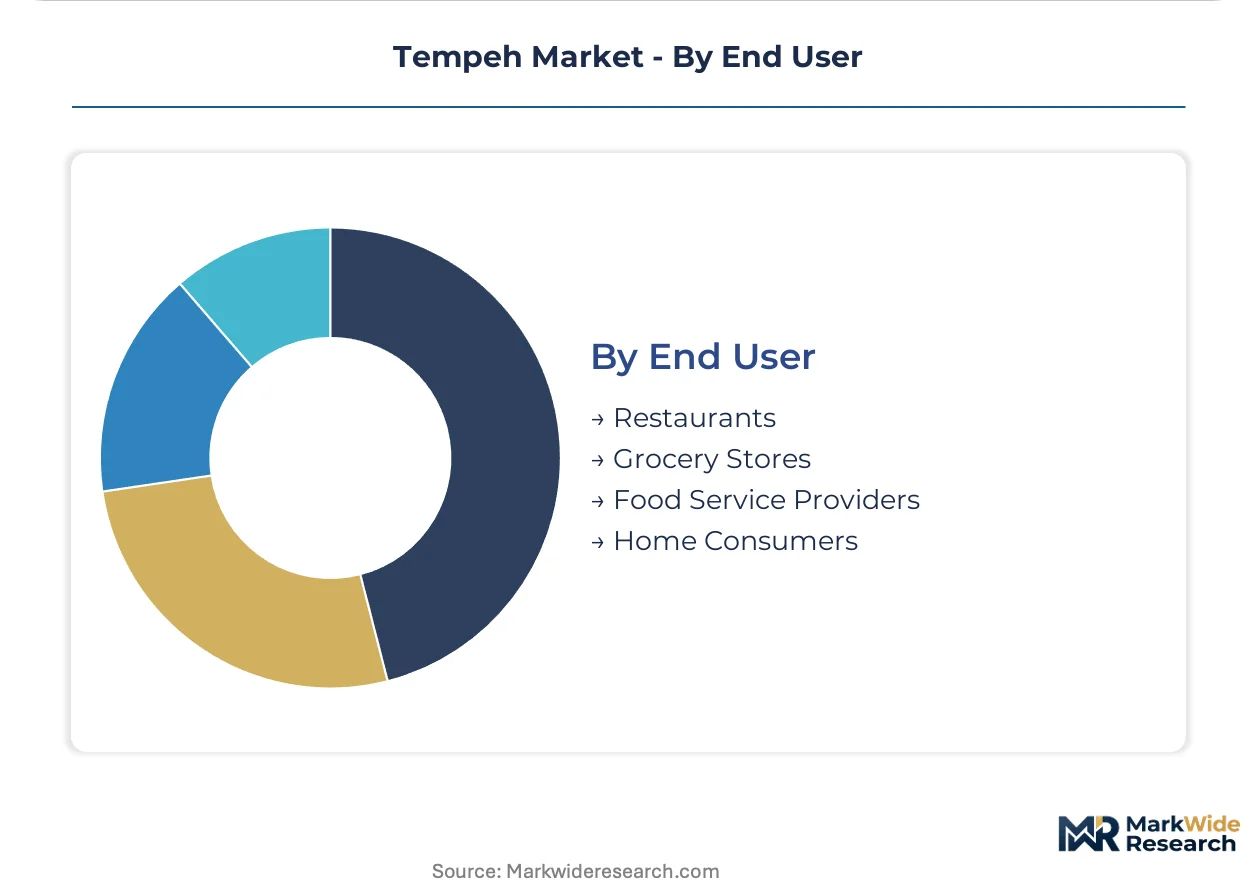
Food service providers command the established base. Restaurant adoption is expanding most quickly as menu innovation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian buyers exhibit minimal price elasticity for daily tempeh consumption, while North American and European food service procurement demonstrates acute sensitivity to organic certification premiums and supply chain transparency costs.
Indonesia
Domestic consumption exceeds export volumes by an order of magnitude, with Javanese households integrating tempeh as a staple protein across income levels. The national food agency enforces halal certification standards that determine eligibility for Middle Eastern and Southeast Asian export corridors. Production clusters near Surabaya and Yogyakarta maintain traditional open-air fermentation cooperatives alongside emerging automated facilities serving cold-chain export markets.
United States
College dining contracts and hospital catering networks drive institutional procurement of certified organic tempeh, with USDA standards serving as non-negotiable vendor credentials. FDA hazard analysis protocols govern fermentation facility inspections and allergen disclosure requirements. Midwest contract manufacturers leverage refrigerated distribution networks to supply retail grocery placements, while coastal urban markets support direct-to-consumer fresh tempeh through farmers market channels.
Japan
Supermarket deli sections and prepared food counters sustain demand for standardized, vacuum-sealed tempeh with consistent mycelial texture. METI-supported university research programs developed Rhizopus oligosporus inoculation protocols now transferring to commercial facilities. House Foods Group anchors domestic production from centralized fermentation plants serving Tokyo-Osaka corridor retail chains.
Germany
EU Green Deal sustainability disclosure mandates redirect food service procurement toward minimally processed, low-carbon protein inputs. EFSA novel food assessments impose extended timelines for non-soy legume substrate approvals, consolidating importer relationships with Indonesian soy-exclusive suppliers. Berlin and Hamburg natural grocery channels command premium positioning for certified organic tempeh against textured vegetable protein alternatives.
Australia
Health-conscious consumer segments and specialist vegetarian retailers sustain niche demand for organic and gluten-free tempeh variants. TGA-equivalent state food safety agencies regulate fermentation facility licensing and live-culture product labeling. Melbourne and Sydney production facilities serve concentrated urban markets, with limited penetration into broad retail grocery due to fresh-product logistics constraints.
Tempeh Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the tempeh industry. Automated fermentation chamber operators achieve batch consistency required by retail grocery buyers, while traditional Javanese cooperatives maintain cost advantages through labor-intensive open-air methods. Three archetypes dominate: multinational food conglomerates with refrigerated distribution networks, regional specialists with halal-certified export infrastructure, and craft-scale producers serving local wet markets. Competitive moves concentrate on organic certification acquisition and frozen format capacity expansion.
Within the multinational conglomerate tier, Maple Leaf Foods and Lightlife Foods represent North American market presence through refrigerated retail channel dominance. House Foods Group anchors Japanese supermarket positioning with standardized fermentation protocols. Among export-specialist operators, Vegolution India Private Limited and Nutrisoy Pty Ltd occupy positions serving halal-certified and health-conscious regional segments respectively.
| Leading Market Players |
|---|
| Maple Leaf Foods |
| The Tofoo Company |
| Lightlife Foods |
| Vegolution India Private Limited |
| Noble Bean |
| Turtle Island Foods |
| House Foods Group |
| Tempe Azaki |
| Nutrisoy Pty Ltd |
| Others |
Value Chain & Pricing Dynamics
Automated fermentation chamber scale economics compress unit costs below artisanal open-air methods, concentrating supply among capital-intensive operators while establishing price floors that exclude small-batch craft producers from mid-market retail positioning. This scale dynamic intersects with EU Green Deal procurement mandates to reward certified organic suppliers with premium shelf access, embedding certification costs into baseline price structures.
Pricing Analysis
EU Green Deal sustainability disclosure mandates dictate the pricing tier structure across European food service channels. Three-tier pricing structure across premium organic, certified conventional, and uncertified commodity levels separates USDA-certified suppliers from conventional operators from wet-market producers. Cost compression in conventional tiers is intensifying because soybean futures volatility lacks pass-through mechanisms against textured vegetable protein alternatives. Food service procurement officers demonstrate lowest price sensitivity, while Indonesian domestic consumers exhibit highest elasticity.
Supply Chain Analysis
Indonesia anchors traditional tempeh production through Javanese fermentation cooperatives near Surabaya and Yogyakarta. Supply draws from dehulled soybeans, Rhizopus oligosporus inoculant cultures, and halal certification infrastructure. Single-source vulnerability concentrates in Indonesian export corridors where cold-chain capacity constraints limit volume scaling. Distribution runs through refrigerated logistics networks for fresh formats and blast-freezing facilities for frozen export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tacit knowledge of mycelial colonization timing represents the critical capability gap, as commercial facilities struggle to codify artisanal quality control expertise that traditional Javanese producers command through generational transmission.
For Market Incumbents: Compound organic certification holdings by accelerating three-year land conversion timelines before competitor entry saturates premium tier positioning. Expand blast-freezing capacity at Indonesian export hubs to capture Gulf state supermarket contracts. Vertical integration into captive inoculant culture production reduces batch variability vulnerability against emerging automated facility operators. For New Entrants and Emerging Players: White-label contract manufacturing for North American college dining systems represents the most penetrable service-layer gap, as incumbent refrigerated distributors under-serve USDA organic compliance demands at price points accessible to institutional procurement officers. Target frozen format production with third-party organic certification to bypass fresh-product logistics constraints that limit geographic radius. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated fermentation chamber operators with established halal certification infrastructure and cold-chain export relationships. Long-term viability hinges on substrate flexibility beyond conventional soy bases. Acquisition target archetype: Indonesian facilities with exclusive EU EFSA soy-based production bypassing novel food assessment delays. Watch EU EFSA chickpea and lupin substrate approval timelines as inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Acquisition | Three-year land conversion timelines lock in premium shelf positioning before competitor saturation. |
| Blast-Freezing Capacity Expansion | Point-of-production freezing preserves texture integrity through extended Gulf state export corridors. |
| Halal Certification Infrastructure | Indonesian national food agency mandates create export eligibility arbitrage into Malaysian and Singaporean markets. |
| Automated Fermentation Chamber Deployment | Japanese METI-supported Rhizopus protocols transfer to commercial facilities for batch consistency. |
| Backward Integration into Inoculant Culture Production | In-house mycelial strain development reduces spoilage rates and supplier dependency. |
Study Parameters
A standing panel of fermentation facility operators, food service procurement officers, halal certification auditors, and refrigerated distribution network managers provided ongoing calibration against secondary validation from FDA food safety filings, EU EFSA novel food assessment records, Indonesian trade statistics, and USDA organic certification databases. Bottom-up volume estimates from production facility interviews triangulated against top-down demand aggregation across end-user channels.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include certification tier, form factor, packaging sophistication, and end-user application. CAGRs derived from fitted growth curves incorporating soybean futures volatility patterns, EU Green Deal procurement mandate implementation timelines, and cold-chain infrastructure expansion rates.
Underlying assumptions cover sustained EU sustainability disclosure enforcement, stable Indonesian halal certification standards, and FDA hazard control protocol continuity, with deviation risk concentrated in novel food assessment timeline extensions and soybean commodity price spikes. Recalibration cycles align with material shifts in EU procurement mandate enforcement and EFSA substrate approval decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant Based Protein Market
Plant Based Food
Hemp-Based Food Market
Plant Based Food
Plant Based Tuna Market
Plant Based Food
Vegan Drink Mixes Market
Plant Based Food
United Kingdom Tofu Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Waters Market
Plant Based Food
Middle East and Africa Plant-Based Egg Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Vegan Tortillas Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Flax-Based Protein Market
Plant Based Food
Veggie Meals Market