
 New Jersey Vegan Products Market | 2026-2036
New Jersey Vegan Products Market Size, Share, and Industry Trends Forecast 2026-2036
New Jersey Vegan Products Market Intelligence
Demand from retail consumers seeking convenience is bifurcating the market away from a sole focus on specialty health food stores. Impossible Foods Inc. specializes in innovative plant-based meat alternatives, driving growth in the foodservice channel. The Campbell's Company leverages its extensive distribution network within New Jersey to introduce vegan product lines. The Hain Celestial Group, Inc. sustains its position through a strong presence in health food stores and organic product offerings.
New Jersey vegan products are food and beverage items formulated entirely without animal-derived ingredients, including meat, dairy, eggs, and honey. These products serve as dietary alternatives for consumers motivated by ethical, health, or environmental concerns. The plant-based meat category currently leads sales, while dairy alternatives represent the fastest-growing segment. Supermarkets remain the primary distribution channel, though online retail is rapidly expanding its share of the market.
The U.S. Food and Drug Administration (FDA) governs labeling requirements for vegan products, ensuring clarity and preventing misleading claims. Concurrently, USDA organic certification provides a key differentiator for brands targeting health-conscious consumers in the state. Navigating the evolving definitions of 'plant-based' versus 'vegan' in marketing will be a critical decision point for brand positioning and consumer trust.
Market Dynamics
The bifurcation of demand between foodservice channels and retail consumers is the central force shaping the New Jersey vegan products market. This dual-front expansion requires manufacturers to develop distinct product strategies, packaging formats, and supply chain logistics for each channel.
Growth Catalysts
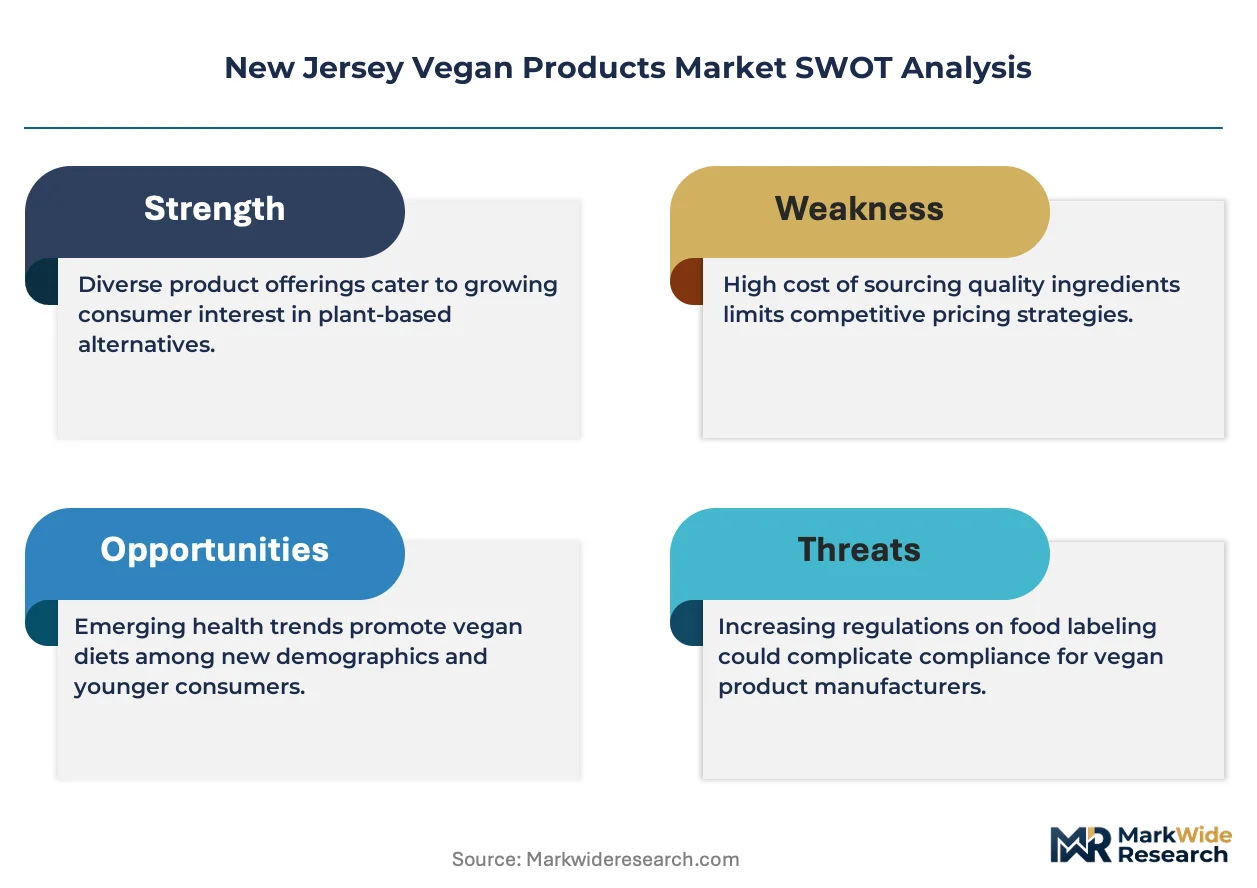
- Favorable Regulatory Guidance:Federal FDA rules on plant-based food labeling provide essential clarity, reducing market entry barriers for manufacturers targeting New Jersey consumers and ensuring consistent communication on packaging.
- Urban Demographic Shifts:Concentrated demand from younger, health-focused consumers in cities like Jersey City and Hoboken, coupled with high population density, accelerates product trial and adoption through local retail and cafes.
- Mainstream Retail Integration:The movement of vegan products from niche health food stores into the dedicated aisles of major supermarkets across New Jersey significantly expands accessibility and normalizes consumer purchasing behavior.
Market Restraints
- Price Disparity:The higher retail price of many processed vegan meat and cheese alternatives compared to their conventional animal-based counterparts remains a significant barrier for budget-conscious households in New Jersey.
- Ingredient Supply Bottlenecks:Reliance on a concentrated global supply base for key inputs like pea and soy protein isolates exposes New Jersey manufacturers to price volatility and potential sourcing disruptions.
- Sensory Acceptance Gaps:Despite innovation, a segment of mainstream consumers remains hesitant to adopt vegan alternatives due to perceived deficits in taste, texture, and mouthfeel compared to traditional dairy and meat products.
Strategic Opportunities
- Foodservice Sector Penetration:A significant opportunity exists in expanding dedicated vegan offerings within New Jersey's institutional catering sectors, including corporate cafeterias, universities, and healthcare facilities, which remain underserved.
- Clean-Label Product Development:Formulating products with shorter, more recognizable ingredient lists and leveraging New Jersey's "Garden State" agricultural identity can attract consumers wary of highly processed plant-based options.
- Vegan Seafood Alternatives:Given New Jersey's coastal proximity and consumer familiarity with seafood, developing plant-based fish and shellfish alternatives presents a targeted growth avenue with less market saturation than meat analogues.
Industry Challenges
- Cold Chain Complexity:Managing temperature-sensitive logistics for a rapidly growing number of refrigerated and frozen vegan products across diverse retail and foodservice endpoints strains existing distribution infrastructure within the state.
- Marketing Message Fragmentation:Brands face the challenge of clearly communicating value propositions while navigating the nuanced and often confusing consumer definitions of 'plant-based,' 'vegan,' and 'whole food' to build lasting trust.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Jersey Vegan Products Market |
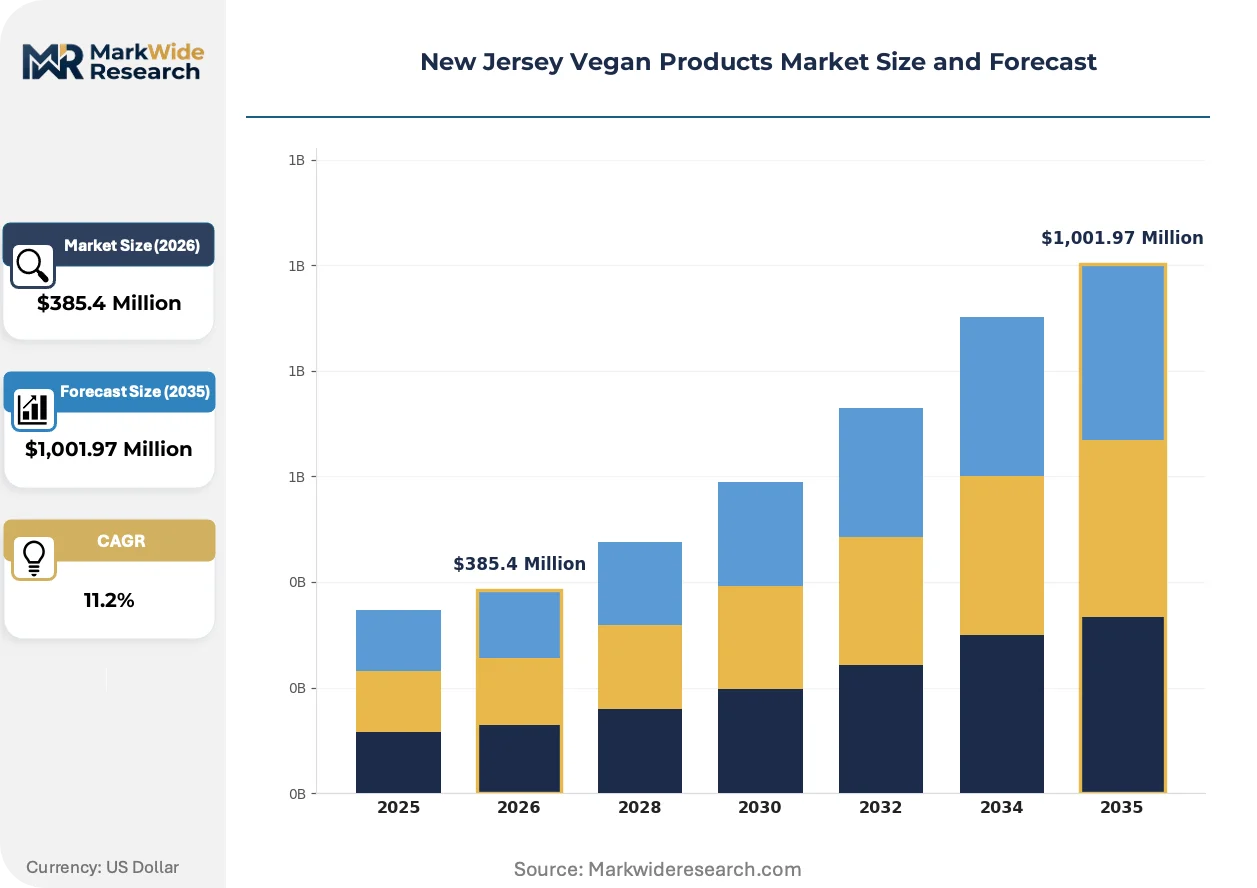
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,001.97 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based Meat, Dairy Alternatives, Snacks, Condiments End User: Retail Consumers, Restaurants, Cafes, Meal Delivery Services Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Farmers Markets Packaging Type: Bottles, Boxes, Pouches, Jars |
| Companies Covered | General Mills Inc., Conagra Brands, Inc., The Hain Celestial Group, Inc., Blue Diamond Growers, Impossible Foods Inc., Daiya Foods, Inc., Nature's Path Foods, Inc., Eden Foods, Inc., The Campbell's Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Jersey Vegan Products Market Strategic Shifts & Innovations
Technological advancements in ingredient science and evolving consumer expectations for convenience are maturing the New Jersey vegan market. The focus is shifting from simple substitution to creating products that offer superior taste, nutritional profiles, and novel consumption experiences.
Precision fermentation is a key enabling technology for the next generation of animal-free products. This process uses microorganisms to produce specific proteins, such as whey and casein, without involving animals. Ingredient-focused startups are rapidly adopting this method, which is displacing the market's previous reliance on plant-derived starches and texturizers to mimic dairy and meat textures.
The U.S. Food and Drug Administration's draft guidance on labeling plant-based milk alternatives is a significant regulatory development. It allows the use of dairy terms like "milk" while recommending voluntary nutritional disclaimers if the product is not a direct nutritional equivalent. This directly affects the dairy alternatives segment in New Jersey, compelling brands to reassess packaging claims and marketing strategies to ensure transparency.
Direct-to-consumer (DTC) sales models and curated subscription boxes are gaining traction among vegan consumers in New Jersey. This behavioral shift disrupts the traditional dominance of supermarkets by offering greater product variety and convenience. The trend is most pronounced in affluent and densely populated urban centers like Hoboken, where delivery-based services align with fast-paced consumer lifestyles.
New Jersey Vegan Products Market Segmentation
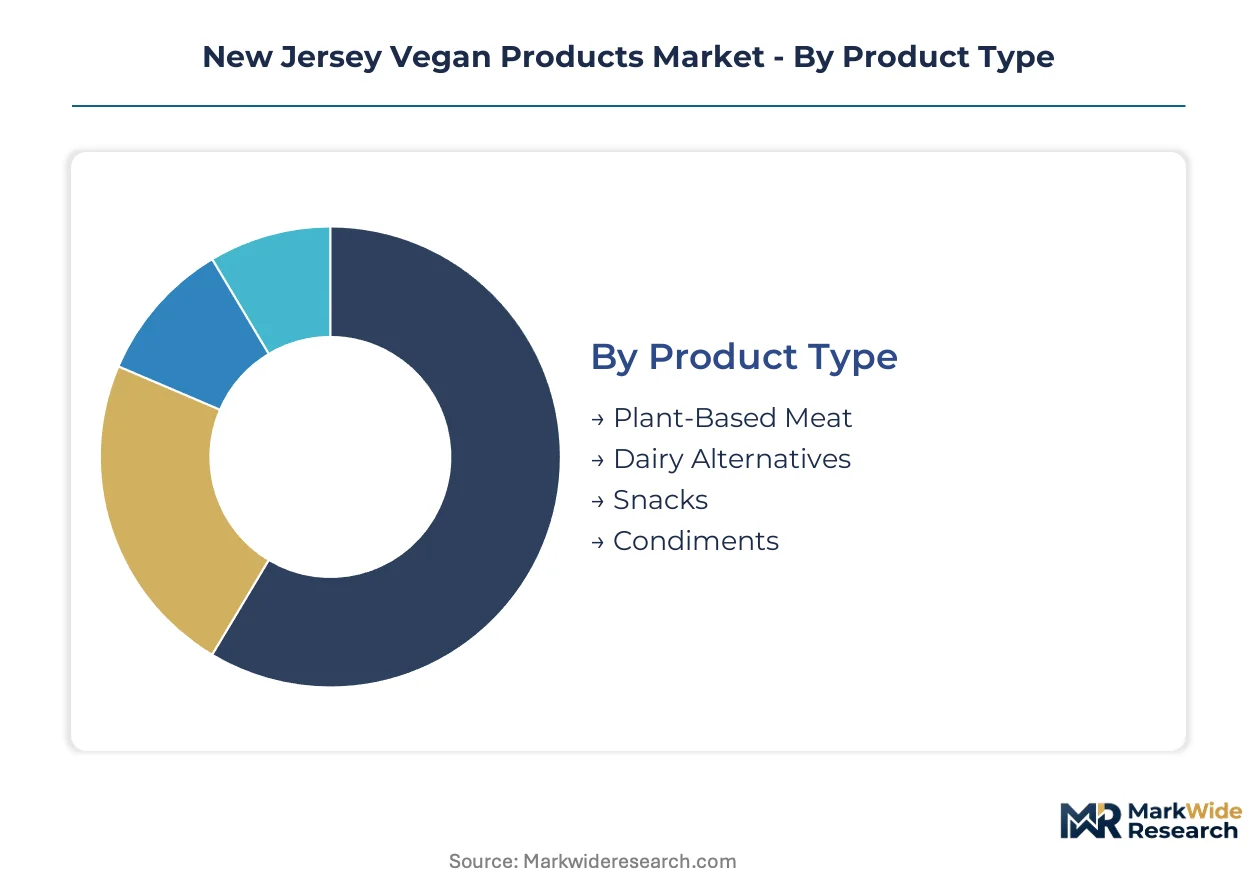
The New Jersey vegan products market exhibits distinct segmentation across various dimensions, reflecting diverse consumer preferences and operational requirements. Understanding these segments enables manufacturers and retailers to tailor product development, marketing efforts, and distribution strategies effectively within the state. This granular view highlights areas of concentrated demand and emerging opportunities for market participants.
Product Type:
Segments within product type face varying degrees of substitution pressure from conventional animal-based alternatives, influencing innovation and market penetration. Significant consumer education efforts accompany the introduction of novel plant-based formulations in New Jersey.
- Plant-Based Meat:These products mimic the taste, texture, and appearance of traditional meat, utilizing ingredients like soy, pea protein, and mushrooms. Demand concentrates in urban centers such as Newark, where health-conscious consumers and a growing foodservice sector drive purchases.
- Dairy Alternatives:Formulations that replicate milk, cheese, and yogurt using plant sources like oats, almonds, and soy. New Jersey consumers increasingly seek these alternatives for health benefits and ethical considerations, expanding their presence in mainstream supermarkets.
- Snacks:This category includes vegan cookies, chips, bars, and other convenient grab-and-go items. New Jersey consumers value these options for on-the-go consumption and dietary compliance.
- Condiments:Vegan mayonnaise, dressings, sauces, and dips formulated without animal products. These items support a wider range of plant-based meal preparation across New Jersey households.
Plant-Based Meat anchors the volume base while Dairy Alternatives gains share at the steepest rate.
End User:
The end-user segmentation reveals distinct purchasing patterns and volume requirements, shaping product formats and pricing strategies for New Jersey market players. Each user group presents unique engagement points for vegan product suppliers.
- Retail Consumers:Individual shoppers purchasing vegan products for home consumption through various channels. New Jersey retail consumers prioritize convenience and product availability in their local stores.
- Restaurants:Food service establishments incorporating vegan options into their menus to cater to diverse dietary needs. New Jersey restaurants in cities like Jersey City actively seek high-quality, reliable vegan ingredient suppliers.
- Cafes:Smaller food service outlets and coffee shops offering vegan pastries, sandwiches, and beverages. New Jersey cafes experience strong demand for plant-based milk alternatives and quick vegan meal solutions.
- Meal Delivery Services:Companies preparing and delivering ready-to-eat vegan meals directly to consumers. This segment's expansion in New Jersey urban areas reflects a preference for convenience and curated dietary options.
Retail Consumers command the largest purchasing volume, while Meal Delivery Services demonstrate the most rapid expansion.
Distribution Channel:
The distribution channel highlights the primary avenues through which vegan products reach New Jersey consumers, influencing market accessibility and brand visibility. Each channel presents distinct logistical and marketing challenges.
- Supermarkets:Large retail grocery stores offering a wide array of vegan products, from fresh produce to packaged goods. Supermarkets in New Jersey provide broad accessibility for mainstream vegan consumers.
- Online Retail:E-commerce platforms and brand-specific websites facilitating direct-to-consumer sales and home delivery. Online retail experiences significant growth in New Jersey, driven by convenience and wider product selection.
- Health Food Stores:Specialty retailers focusing on organic, natural, and dietary-specific products. These stores serve a niche segment of New Jersey consumers seeking premium or specialized vegan items.
- Farmers Markets:Local outdoor markets selling fresh produce and artisanal goods directly from producers. New Jersey farmers markets offer a direct connection for consumers seeking locally sourced vegan products.
Supermarkets maintain the highest product throughput, with Online Retail experiencing the most accelerated growth trajectory.
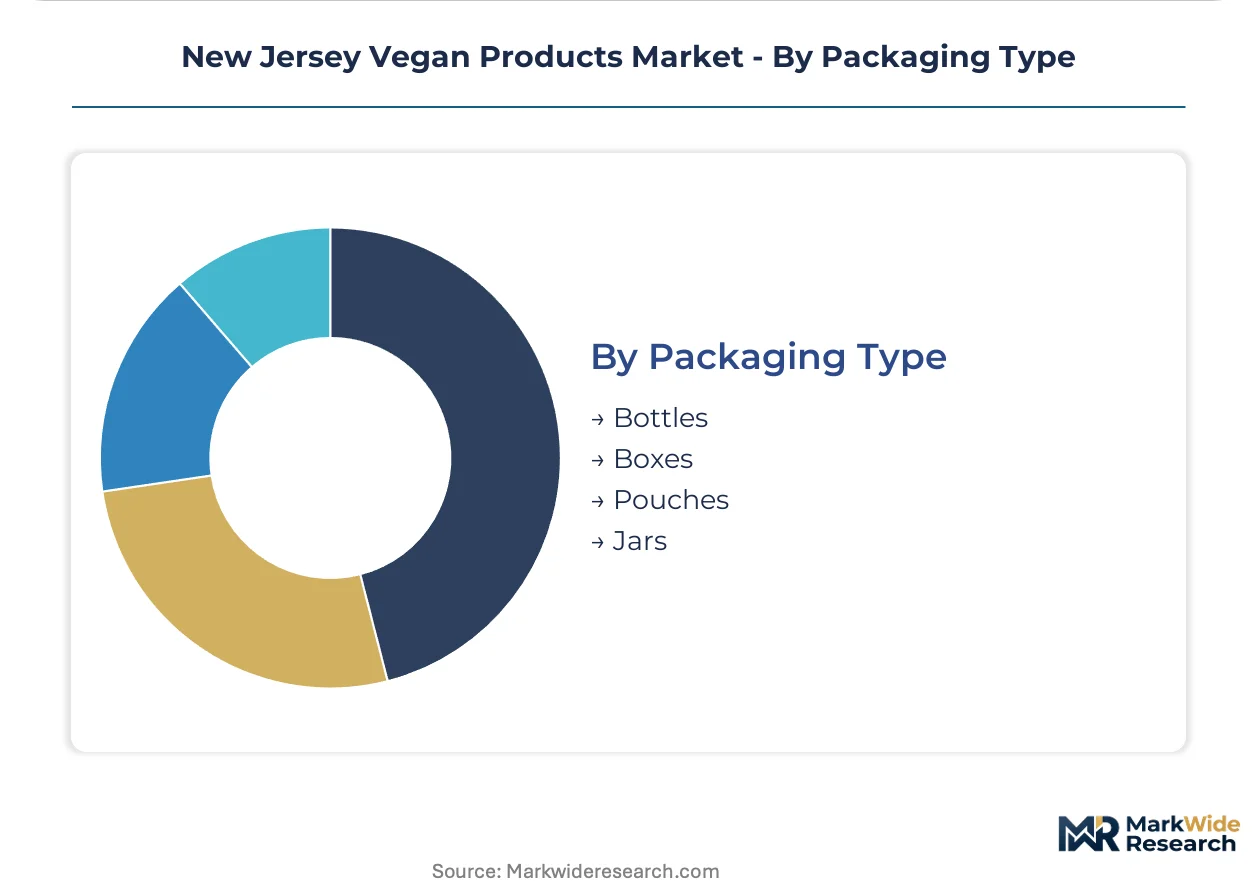
Packaging Type:
Packaging type is a critical consideration for product integrity, consumer convenience, and environmental impact within the New Jersey vegan products market. Material choices and design directly influence shelf life and consumer appeal.
- Bottles:Commonly used for plant-based milks, juices, and liquid condiments, offering resealability and portion control. New Jersey consumers prefer bottles for beverages due to their convenience and perceived freshness.
- Pouches:Flexible packaging solutions for snacks, sauces, and smaller portions of vegan ingredients, valued for their light weight and reduced material usage. Pouches gain traction in New Jersey for on-the-go convenience and sustainability efforts.
- Boxes:Utilized for dry goods like vegan cereals, crackers, and frozen plant-based meats, providing structural integrity and branding surface. New Jersey retailers stock boxed vegan products for their stackability and protection during transport.
- Jars:Glass or plastic containers for spreads, sauces, and preserves, offering visibility of the product and often perceived as premium. Jars are popular in New Jersey for artisanal vegan condiments and specialty items.
Bottles constitute a substantial volume segment, while Pouches display the most pronounced growth in New Jersey packaging preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The trade-flow corridor for vegan products within New Jersey primarily moves from state-wide distribution centers into its dense urban consumption hubs. This internal distribution network connects diverse consumer segments, from metropolitan residents to suburban families. Manufacturers adapt their supply chain strategies to cater to the varying demands across these distinct geographic areas. The state's diverse economic landscape supports both high-volume retail and specialized foodservice requirements for plant-based goods.
Jersey City
Jersey City experiences concentrated demand from younger, health-conscious demographics and expanding retail availability. Federal FDA regulations on plant-based food labeling provide essential clarity for products sold here. This dense urban center accelerates product trial and adoption through numerous local retail outlets and cafes.
Hoboken
Hoboken's affluent and health-aware population drives significant demand for premium vegan products and convenient delivery services. USDA organic certification provides a key differentiator for brands targeting these discerning consumers. The city's fast-paced lifestyle aligns well with the growth of direct-to-consumer (DTC) sales models and curated subscription boxes.
Newark
Newark, a major urban hub, exhibits strong foodservice demand from restaurants and cafes incorporating vegan options into their menus. The federal FDA's guidance on plant-based milk alternatives influences product offerings and marketing strategies here. Clean-label product development finds resonance among consumers seeking transparent ingredient lists in this diverse market.
Central New Jersey
Affluent consumers in Central New Jersey, particularly around university towns and corporate campuses, seek both retail and institutional vegan offerings. USDA organic certification appeals to the health-conscious segment in this region. Opportunities exist in expanding dedicated vegan options within corporate cafeterias and university dining facilities.
Southern New Jersey
Southern New Jersey represents a significant market for mainstream retail integration of vegan products, particularly in supermarkets. Federal FDA rules on plant-based food labeling ensure consistent communication on packaging for a broad consumer base. This area shows potential for growth in vegan seafood alternatives, given the region's coastal proximity and consumer familiarity with seafood.
New Jersey Vegan Products Market Key Industry Players
Player mix skews toward a blend of established food conglomerates and specialized plant-based innovators within the New Jersey vegan products market. The market structure is moderately fragmented, with diverse players catering to distinct consumer preferences. Strategic archetypes include large-scale consumer packaged goods (CPG) companies, innovative plant-based protein developers, and niche health-focused brands. Dominant competitive moves involve expanding distribution networks and continuous product portfolio diversification.
Specialists in innovative plant-based meat alternatives, such as Impossible Foods Inc., drive growth in the foodservice channel. The Campbell's Company, a large CPG player, leverages its extensive distribution network within New Jersey to introduce vegan product lines across mainstream retail. The Hain Celestial Group, Inc. maintains its strong presence through health food stores and organic product offerings, catering to health-conscious consumers in urban and suburban areas. These companies collectively shape market dynamics through targeted product development and channel-specific strategies.
| Leading Market Players |
|---|
| General Mills Inc. |
| Conagra Brands, Inc. |
| The Hain Celestial Group, Inc. |
| Blue Diamond Growers |
| Impossible Foods Inc. |
| Daiya Foods, Inc. |
| Nature's Path Foods, Inc. |
| Eden Foods, Inc. |
| The Campbell's Company |
| Others |
Cost & Logistics Intelligence
High volume production economies of scale in plant-based dairy alternatives directly influence supply concentration and establish competitive price floors across New Jersey retail channels. This dynamic compels manufacturers to optimize sourcing and distribution for cost efficiency.
Pricing Analysis
The pricing gap between precision fermentation-derived vegan products and traditional plant-based alternatives remains substantial. New Jersey's vegan market operates primarily on a per-unit transactional model for retail and contract-based long-term offtake for foodservice. Brand premium and USDA organic certification drive price differentiation for health-conscious consumers. Pricing pressure stems from the higher ingredient costs of novel formulations and consumer hesitancy regarding perceived sensory acceptance gaps. Budget-conscious households in Southern New Jersey are most price-sensitive, while affluent Hoboken consumers show less sensitivity to premium vegan offerings.
Supply Chain Analysis
Just-in-time inventory strategies dominate for fresh and refrigerated vegan products, while frozen alternatives allow for strategic stockpiles within New Jersey's cold chain. Key protein isolates like pea and soy primarily source from China and the USA. Manufacturers depend on pea protein, soy protein isolates, and specialized flavor compounds. Commodity price volatility for these agricultural inputs presents a significant structural risk. Distribution runs through a dual system, with large-scale CPG networks for supermarkets and specialized cold chain logistics for foodservice and online retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The New Jersey vegan products market is experiencing a significant buyer-power shift, driven by the fragmentation of retail consumers into distinct preference groups and the growing influence of meal delivery services. This necessitates tailored engagement strategies.
For Market Incumbents:Secure long-term supply agreements for pea and soy protein isolates to mitigate commodity price volatility. Diversify product lines into vegan seafood alternatives, leveraging New Jersey's coastal identity. Emerging precision fermentation startups pose a threat to traditional plant-based dairy alternative market share. Strengthen distribution network control within New Jersey's urban centers.
For New Entrants and Emerging Players:USDA organic certification fast-tracks market entry for premium vegan snacks targeting affluent Hoboken consumers. Focus on underserved institutional catering sectors like corporate cafeterias and universities in Central New Jersey. The meal delivery services segment in Jersey City offers a highly penetrable entry point. Leverage direct-to-consumer (DTC) models to build brand loyalty and collect consumer feedback rapidly.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among meal delivery services and subscription box providers in the New Jersey vegan market. The market offers strong long-term viability over the next 5-10 years, supported by sustained demographic shifts. Target specialized plant-based protein developers with proprietary precision fermentation technologies. Monitor the regulatory clarity on "plant-based" versus "vegan" labeling as an inflection indicator for market trust and expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Distribution Channel Expansion | Extend reach into institutional foodservice across Central and Southern New Jersey. |
| Product Launch | Introduce novel vegan seafood alternatives tailored for New Jersey's coastal consumers. |
| Strategic Partnership | Collaborate with local New Jersey cafes to co-develop plant-based milk alternatives. |
| Manufacturing Scale-Up | Increase production capacity for popular dairy alternatives to meet retail demand. |
| Sustainability Repositioning | Emphasize clean-label ingredients and local sourcing to appeal to health-conscious buyers. |
Research Approach
A spread of perspectives from brand managers, retail category buyers, foodservice procurement specialists, and regulatory affairs leads converged on the working assumptions for this New Jersey market analysis. This study combined insights from primary interviews with extensive secondary validation. Data drew from USDA organic certification records, FDA labeling guidance documents, and New Jersey Department of Agriculture statistics. Bottom-up and top-down triangulation ensured robust data integrity.
Product type, end user, distribution channel, packaging type, and New Jersey sub-region constituted the segmentation dimensions modeled over the projection horizon. Compound annual growth rates derived from historical market performance and projected demand shifts. Key forecast inputs included New Jersey demographic changes and consumer dietary preference surveys. The analytical framework assessed market volume and value across these granular segments.
Decision-makers should treat outputs as directional under current New Jersey consumer preference and regulatory stability assumptions; material deviation would warrant model refresh. Shifts in federal FDA labeling enforcement or significant agricultural commodity price fluctuations could revise forecasts. Revision becomes warranted when new plant-based ingredient technologies gain widespread commercial adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Organic Rice Protein Market
Plant Based Food
Plant-Based Frozen Dessert Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Vegan Bacon Market
Plant Based Food
Vegan Drink Mixes Market
Plant Based Food
Yellow Pea Protein Market
Plant Based Food
Plant Chocolate Protein Powder Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Global Organic Soy Protein Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Global Textured Vegetable Protein Market
Plant Based Food
Soy- Based Food Market
Plant Based Food
Targeting Pod Market
Plant Based Food
United States Pea Protein Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Vegan Meals Market