
 Soy Protein Market | 2026-2036
Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Protein Market Intelligence
Buyer concentration in the food and beverage sector is shifting as multinational processors consolidate procurement while specialty nutrition startups fragment demand across niche channels. Archer Daniels Midland Company leverages its North American crush footprint to anchor supply contracts with large meat-alternative brands. Cargill Incorporated competes through integrated origination-to-ingredient pipelines that sustain margin capture across volatile soybean markets. Kerry Group plc differentiates via customized protein systems that navigate clean-label requirements for European and Asian customers.
Soy protein denotes the isolated or concentrated protein fraction extracted from defatted soybean meal, typically achieving protein contents of 50% to 90% depending on processing intensity via aqueous extraction or alcohol washing. It serves primarily as a functional binding, emulsifying, and gelling agent in formulated foods, nutritional products, and feed rations. Soy protein isolate commands the highest margin pool among product types due to its superior functional performance in meat alternatives and sports nutrition applications. Powder form dominates current volume flows, though liquid concentrates are gaining traction in ready-to-drink dairy alternatives where dispersion speed matters.
The FDA governs nutrition labeling and health claim substantiation for soy protein in the United States, while the EFSA evaluates novel food applications and protein quality claims across European markets. China's SAMR enforces GB standards for plant protein purity and contaminant limits that shape export eligibility for international suppliers. Stakeholders must monitor evolving regulatory divergence on protein content thresholds and allergen declaration protocols as these determine market access and formulation flexibility across jurisdictions.
Market Dynamics
The FDA's updated nutrition labeling requirements are compressing formulation timelines as manufacturers reformulate to meet cleaner ingredient declarations while maintaining functional performance in meat alternatives and sports nutrition.
Growth Catalysts
- Clean-label mandates:The FDA's revised nutrition labeling rules are accelerating reformulation cycles across US food manufacturers, pulling soy protein isolates into premium positioning.
- Brazil crush expansion:Rising soybean processing capacity in Mato Grosso and Paraná is concentrating supply-side power and lowering landed costs for Atlantic-facing buyers.
- Sports nutrition pivot:Plant-based protein powders are displacing whey in endurance athlete segments, with soy isolates capturing share in pre-workout and recovery formulations.
Market Restraints
- Soybean price volatility:Crush margins swing with La Niña-driven harvest uncertainty in Argentina and Brazil, compressing ingredient processor margins unpredictably.
- Allergen labeling friction:EFSA's evolving protocols for soy allergen thresholds are creating compliance drag for European exporters and reformulation costs.
- Pea protein substitution:Yellow pea concentrates are capturing share in dairy alternatives where neutral flavor and lighter color outperform soy's beany notes.
Strategic Opportunities
- India nutrition access:The FSSAI's protein fortification mandates for school feeding programs are opening institutional procurement channels for imported isolates.
- Precision fermentation hybrids:Blending soy protein with microbial-derived dairy proteins is expanding into premium ice cream and cheese alternatives.
- Direct-to-brand supply:Bypassing traditional distributors, ingredient suppliers are building captive relationships with fast-growing meat-alternative startups.
Industry Challenges
- Extraction engineering talent:Shortages of process engineers skilled in aqueous protein fractionation are slowing capacity ramp-ups at new crush facilities.
- Organic certification timelines:Non-GMO and organic soy protein approvals stretch 18-24 months, delaying premium product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Protein Market |
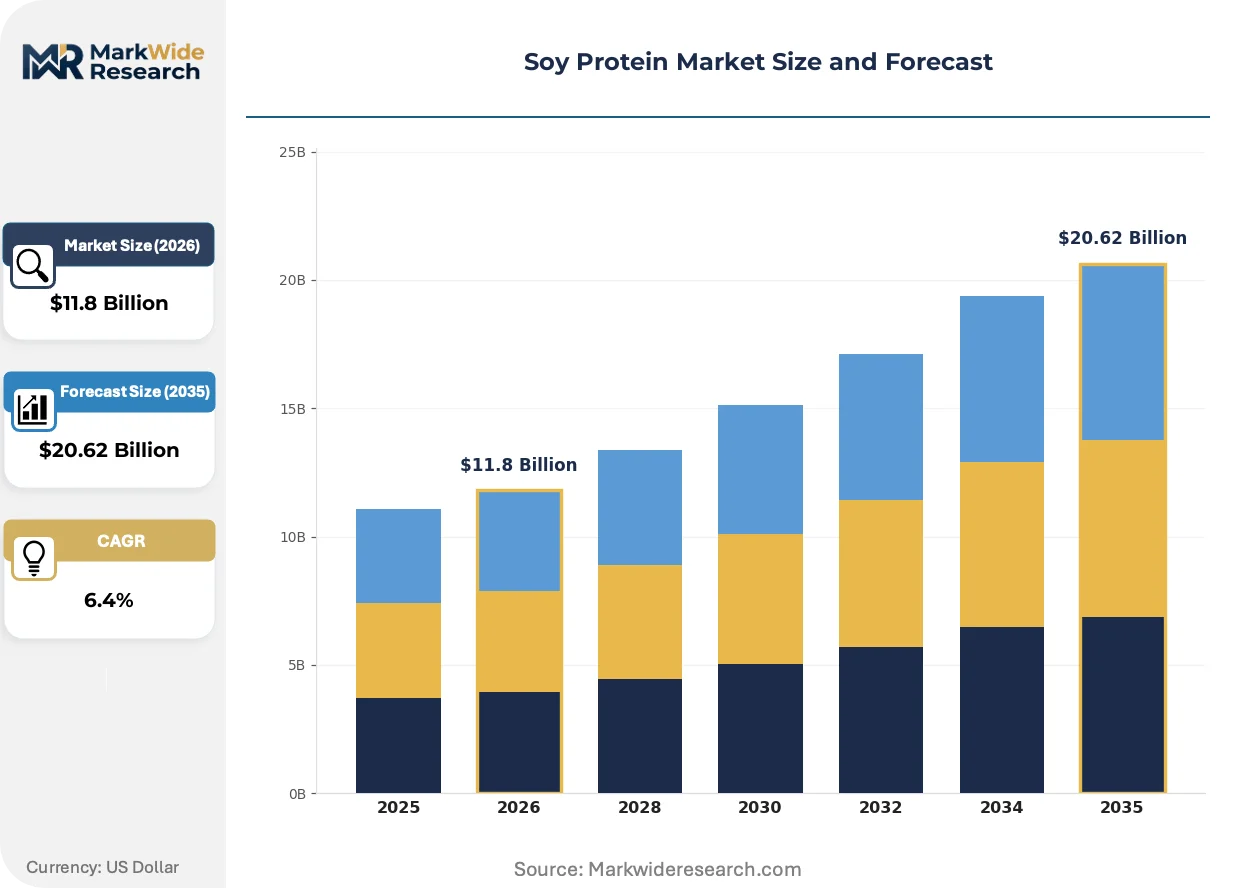
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Soy Protein, Soy Protein Isolate, Soy Protein Concentrate, Soy Flour Form: Powder, Flakes, Granules, Liquid Application: Meat Alternatives, Bakery Products, Dairy Alternatives, Nutritional Supplements, Infant Nutrition End User: Food & Beverage Manufacturers, Sports Nutrition Companies, Animal Feed Producers, Pharmaceutical Companies |
| Companies Covered | Wilmar International Limited, Fuji Oil Holdings Inc., Archer Daniels Midland Company, Kerry Group plc, DuPont de Nemours Inc., Cargill Incorporated, CHS Inc., Roquette Frères, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Protein Market Strategic Shifts & Innovations
Processing technology advances and regulatory precision are compressing the gap between commodity soy meal and high-function isolates, while procurement relationships bypass traditional distribution layers.
Enzymatic hydrolysis is expanding into soy protein modification, breaking large polypeptides into smaller fractions that improve solubility and reduce grit in ready-to-drink applications. Beverage formulators in South Korea and Japan are adopting these hydrolysates for clear protein waters. The technology is expanding into premium positioning where mouthfeel differentiation commands price premiums over standard isolates.
REACH registration requirements for novel protein processing aids are tightening purity documentation obligations on European suppliers. Manufacturers must now trace solvent residues and heavy metals through multi-tier supply chains. Sports nutrition brands exporting to Germany and France are absorbing third-party testing costs to maintain market access.
Long-term offtake agreements are displacing spot purchasing among large meat-alternative brands, locking in volume commitments that extend 24-36 months. These contracts transfer price risk to processors while securing supply certainty for scaling production. The shift is most visible in North American and European procurement desks where inventory volatility disrupted operations during recent harvest shocks.
Soy Protein Market Segmentation
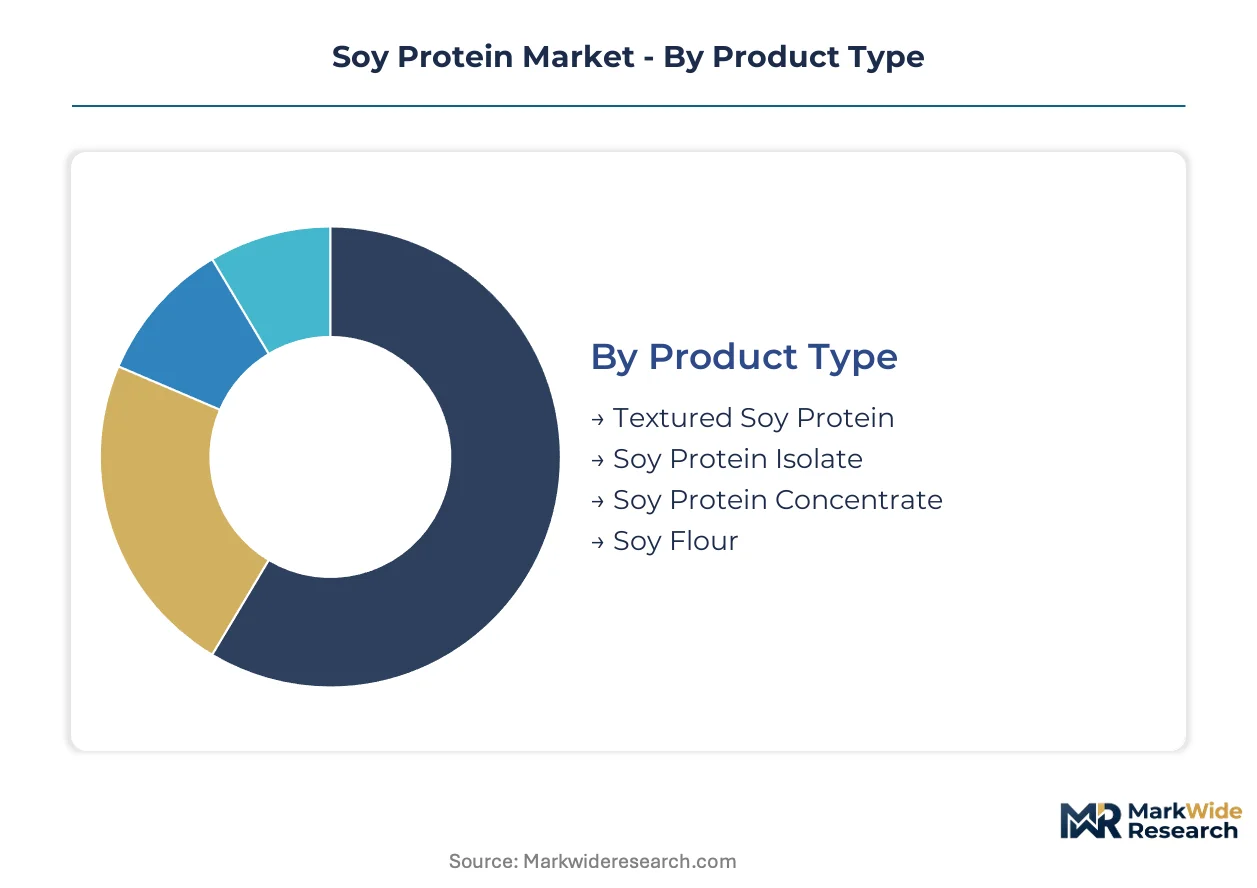
Segmentation in soy protein reveals how processing intensity and functional specifications align with diverging price points across meat alternatives, sports nutrition, and infant formula channels. Understanding these divisions exposes where margin pools concentrate and where formulation flexibility creates competitive advantage.
Product Type:
Processing intensity and protein purity define the technology ladder, with extraction method determining functional performance in finished applications.
- Soy Protein Isolate:Achieves protein contents of 90% or higher through aqueous extraction and isoelectric precipitation, delivering superior emulsification and gelation. Demand concentrates in meat-alternative brands where texture replication commands premium positioning, though organic certification timelines stretch 18-24 months for this grade.
- Soy Protein Concentrate:Contains 65-70% protein with retained soluble carbohydrates, offering cost-efficient binding in processed meats and baked goods. Brazil's expanding crush capacity in Mato Grosso is lowering landed costs for Atlantic-facing buyers of this mid-tier grade.
- Textured Soy Protein:Extruded concentrates or isolates reformed into fibrous structures mimicking meat mouthfeel. Food & beverage manufacturers in India leverage FSSAI fortification mandates to source this grade for school feeding programs.
- Soy Flour:Full-fat or defatted meal with 40-50% protein, serving as an economical extender in bakery applications where functional demands remain modest.
Soy protein isolate leads on scale; textured soy protein leads on momentum.
Form:
Physical state determines dispersion speed, shelf stability, and equipment compatibility across manufacturing lines.
- Powder:Dominates current volume flows due to extended shelf life and ease of dry blending in meat-alternative and sports nutrition facilities. Kerry Group plc supplies customized powder systems navigating EFSA clean-label requirements for European customers.
- Liquid:Gaining traction in ready-to-drink dairy alternatives where dispersion speed matters, though refrigerated supply chains constrain geographic reach. South Korean and Japanese beverage formulators adopt liquid concentrates for clear protein waters.
- Flakes:Preferred in rehydration-heavy applications such as meat extenders and pet food, where rapid water absorption reduces processing time.
- Granules:Target extrusion and texturization lines where controlled particle size improves hydration uniformity in high-throughput operations.
Powder commands installed base; liquid climbs the fastest.
Application:
End-use channel dictates protein specification, with functional requirements ranging from neutral flavor masking to precise amino acid profiling.
- Meat Alternatives:Requires isolates with fibrous texture and high water-holding capacity to replicate muscle protein structure. Archer Daniels Midland Company anchors supply contracts with large brands through its North American crush footprint.
- Nutritional Supplements:Sports nutrition companies are expanding procurement of isolates for plant-based pre-workout and recovery formulations, displacing whey in endurance athlete segments.
- Dairy Alternatives:Pea protein substitution threatens soy's position where neutral flavor and lighter color outperform beany notes, though enzymatic hydrolysis is improving soy's sensory profile.
- Bakery Products:Concentrates and flours provide dough conditioning and moisture retention in commercial bread and pastry operations.
- Infant Nutrition:Demands the highest purity grades with stringent contaminant controls under China's SAMR GB standards and FDA infant formula regulations.
Meat alternatives anchor volume; nutritional supplements show steepest expansion trajectory.
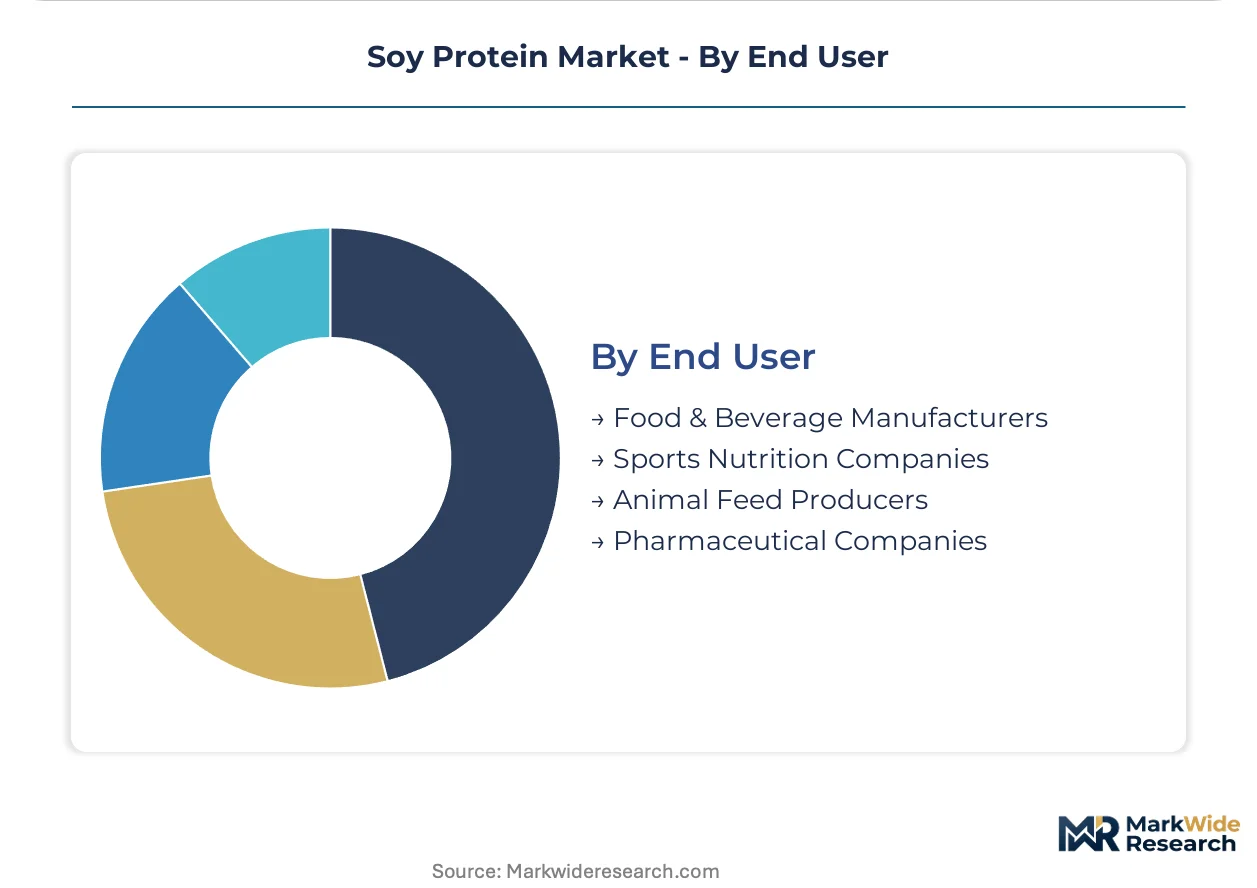
End User:
Customer scale and technical sophistication create tiered service requirements from commodity supply to co-development partnerships.
- Food & Beverage Manufacturers:Multinational processors consolidate procurement through long-term offtake agreements extending 24-36 months, transferring price risk to suppliers while securing volume certainty.
- Sports Nutrition Companies:Fragmented demand across specialty startups drives customized protein system development, with direct-to-brand supply relationships bypassing traditional distributors.
- Animal Feed Producers:Absorb lower-grade concentrates and meals where protein content requirements tolerate higher fiber and residual oil levels.
- Pharmaceutical Companies:Source isolates for medical nutrition and excipient applications under FDA and EMA drug substance guidelines, requiring extensive documentation and batch traceability.
Food & beverage manufacturers dominate procurement scale; sports nutrition companies drive innovation momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's crush capacity expansion contrasts with India's import-dependent protein fortification programs, revealing divergent supply-side positioning across major soybean processing geographies.
United States
Meat-alternative brands and sports nutrition formulators drive isolate demand, with FDA nutrition labeling revisions compressing reformulation timelines. The agency's updated declaration requirements push manufacturers toward cleaner ingredient panels. Processing clusters in Illinois and Iowa leverage proximity to soybean crush infrastructure for cost-efficient supply.
Brazil
Soybean crush expansion in Mato Grosso and Paraná concentrates supply-side power for Atlantic-facing buyers. ANVISA's evolving food additive protocols shape export eligibility documentation requirements. Port infrastructure investments in Santos and Paranaguá reduce lead times for European and Asian protein shipments.
China
SAMR enforces GB standards for plant protein purity and contaminant limits that determine import eligibility for international suppliers. Infant formula manufacturers demand the highest isolate grades under national food safety mandates. Processing capacity clusters in Shandong and Jiangsu provinces serve domestic dairy alternative brands.
Germany
EFSA evaluations of novel food applications and protein quality claims create compliance benchmarks for European market access. REACH registration requirements for processing aids tighten purity documentation obligations on suppliers. The country's ingredient formulators in North Rhine-Westphalia absorb third-party testing costs to maintain export channels.
India
FSSAI protein fortification mandates for school feeding programs open institutional procurement channels for imported isolates. Textured soy protein demand concentrates in bakery and processed food applications. Maharashtra and Gujarat-based food manufacturers leverage direct import relationships to bypass traditional distribution layers.
Soy Protein Market Key Industry Players
North American producers anchor one tier; European specialists hold differentiated positions in customized protein systems. The vendor base separates between integrated agribusiness conglomerates with crush-to-ingredient pipelines and focused ingredient technology firms. Three archetypes dominate: origination-integrated processors, functional systems formulators, and regional crush operators. Capacity expansion and long-term offtake contracting represent the dominant competitive moves as brands seek supply certainty.
Within the integrated processor tier, Archer Daniels Midland Company and Cargill Incorporated exemplify North American crush-anchored supply structures. Kerry Group plc occupies a position representing European functional systems specialization. These three entities collectively illustrate how geographic origination advantage and formulation capability create divergent competitive positioning across isolate, concentrate, and textured product grades.
| Leading Market Players |
|---|
| Wilmar International Limited |
| Fuji Oil Holdings Inc. |
| Archer Daniels Midland Company |
| Kerry Group plc |
| DuPont de Nemours Inc. |
| Cargill Incorporated |
| CHS Inc. |
| Roquette Frères |
| Bunge Limited |
| Others |
Cost & Logistics Intelligence
Non-GMO and organic certification timelines stretching 18-24 months gate qualified supply access and anchor premium-tier pricing power for soy protein isolates, filtering out commodity-grade competitors from clean-label procurement channels.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for mid-tier concentrates while isolate premiums hold firm. Pricing stratifies across organic-certified isolates, standard food-grade concentrates, and economy feed-grade meals. Cost compression in standard concentrates is intensifying because Mato Grosso crush expansion floods Atlantic-facing markets. Animal feed producers exhibit highest price sensitivity; infant formula manufacturers show least.
Supply Chain Analysis
Regional distribution centers in Santos and Paranaguá anchor hub-and-spoke patterns for European and Asian protein shipments. Supply concentrates in Brazil, the United States, and Argentina. Processing draws from soybean meal, hexane solvent systems, and enzymatic hydrolysis units. Single-source vulnerability runs through La Niña-driven harvest shocks in South America. Distribution runs through long-term offtake contracts displacing spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in enzymatic hydrolysis capabilities and direct-to-brand supply relationships that bypass traditional distribution markups.
For Market Incumbents: To counter pea protein substitution in dairy alternatives, deepen backward integration into Brazilian crush capacity and accelerate enzymatic hydrolysis R&D for sensory-neutral isolates. Lock 24-36 month offtake contracts with scaling meat-alternative brands to transfer price risk downstream. For New Entrants and Emerging Players: Begin with FSSAI-mandated school feeding programs in India where institutional procurement channels favor textured soy protein imports. Target precision fermentation hybrid applications in premium ice cream alternatives. Lead with direct-to-brand supply relationships that bypass established distributor networks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional crush operators lacking isolate fractionation capabilities. Five-to-ten year viability hinges on origination-adjacent processing assets in Brazil and North America. Watch enzymatic hydrolysis patent filings as inflection signal for premium-tier positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Scale-Up | Enables clear protein water applications for South Korean and Japanese beverage formulators. |
| Long-Term Offtake Agreements | Locks 24-36 month volume commitments transferring price risk to processors. |
| Direct-to-Brand Supply Relationships | Bypasses distributor markups for fast-growing meat-alternative startups. |
| Organic Certification Investment | Opens 18-24 month approval pipelines for premium isolate positioning. |
| Brazil Crush Capacity Expansion | Lowers landed costs for Atlantic-facing buyers of standard concentrates. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged soy protein procurement managers at meat-alternative brands, crush facility operations directors, sports nutrition formulators, FSSAI compliance officers, and EFSA regulatory consultants. Secondary validation drew from FDA nutrition labeling guidance documents, SAMR GB standards filings, ANVISA food additive protocols, customs trade data, and SEC 10-K disclosures from listed agribusiness conglomerates. Bottom-up volume modeling and top-down market sizing triangulated to convergence.
Historical reference periods anchored the projection horizon to observed crush margin cycles and certification timeline patterns. Segmentation dimensions spanned processing intensity tiers, physical form factors, end-use application channels, and customer scale archetypes. CAGRs derived from regression against soybean harvest volatility and protein fortification policy trajectories. Forecast inputs incorporated La Niña probability distributions and enzymatic hydrolysis adoption curves.
Caveats apply where EFSA allergen threshold revisions or SAMR contaminant limit updates could materially shift the outlook. Forecasts reflect documented assumptions on crush capacity ramp schedules and organic certification throughput rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Diet Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
North America Plant-Based Egg Market
Plant Based Food
Indoor Leafy Green Precision Nutrition Program Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Plant Based Breads Market
Plant Based Food
Plant Based Collagen Market
Plant Based Food
South America Soy Beverages Market
Plant Based Food
Vegan Protein Foods Market
Plant Based Food
Vegan Bacon Market
Plant Based Food
Plant-Based Hot Dogs Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Plant-Based Vegan Eggs Market