
 Plant-Based Meatballs Market | 2026-2036
Plant-Based Meatballs Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Meatballs Market Outlook
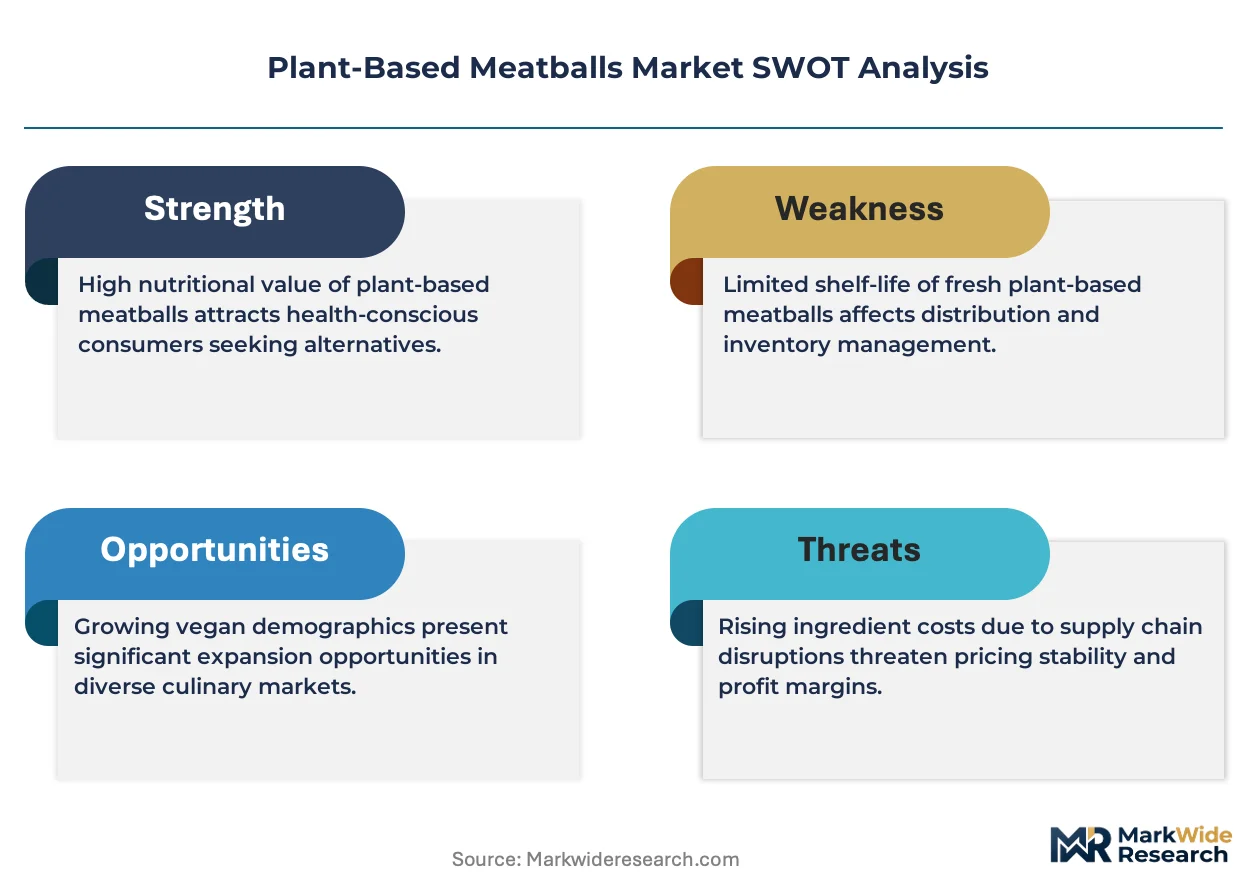
Pea protein isolate is hardening as the dominant binder in premium plant-based meatballs, displacing soy concentrates that face allergen labeling burdens in multiple jurisdictions. Beyond Meat leverages vertical integration into pea protein processing to secure supply continuity and cost predictability. Impossible Foods anchors its formulation strategy on heme technology, which sustains sensory parity with conventional meat across foodservice applications. Nestlé competes through Garden Gourmet's European manufacturing scale and Sweet Earth Foods' retail penetration in North America.
Plant-based meatballs are spheroid analogues manufactured from extruded vegetable proteins, starches, and lipid systems, typically containing 14-22 grams of protein per serving and designed to replicate the chew, moisture retention, and Maillard browning of ground meat preparations. Their primary commercial purpose is to substitute conventional meatballs in foodservice and retail channels without requiring menu or recipe reformulation by end users. Frozen product type dominates volume due to extended shelf life and established cold-chain infrastructure, while chilled formats command margin premiums through freshness positioning in specialty retail. Pea protein ingredient formulations are expanding fastest among allergen-sensitive consumer segments, though soy protein retains cost advantages in mass-market distribution.
The FDA regulates labeling claims and nutritional equivalence standards for plant-based meat alternatives in the United States, while the USDA oversees facility inspection requirements where these products share processing lines with conventional meat. The EU Green Deal and F-Gas Regulation are accelerating clean-label and low-carbon manufacturing requirements for European suppliers, reshaping ingredient sourcing and energy-intensive extrusion processes. Stakeholders must monitor evolving nomenclature restrictions and carbon accounting mandates that will determine market access and premium positioning across jurisdictions.
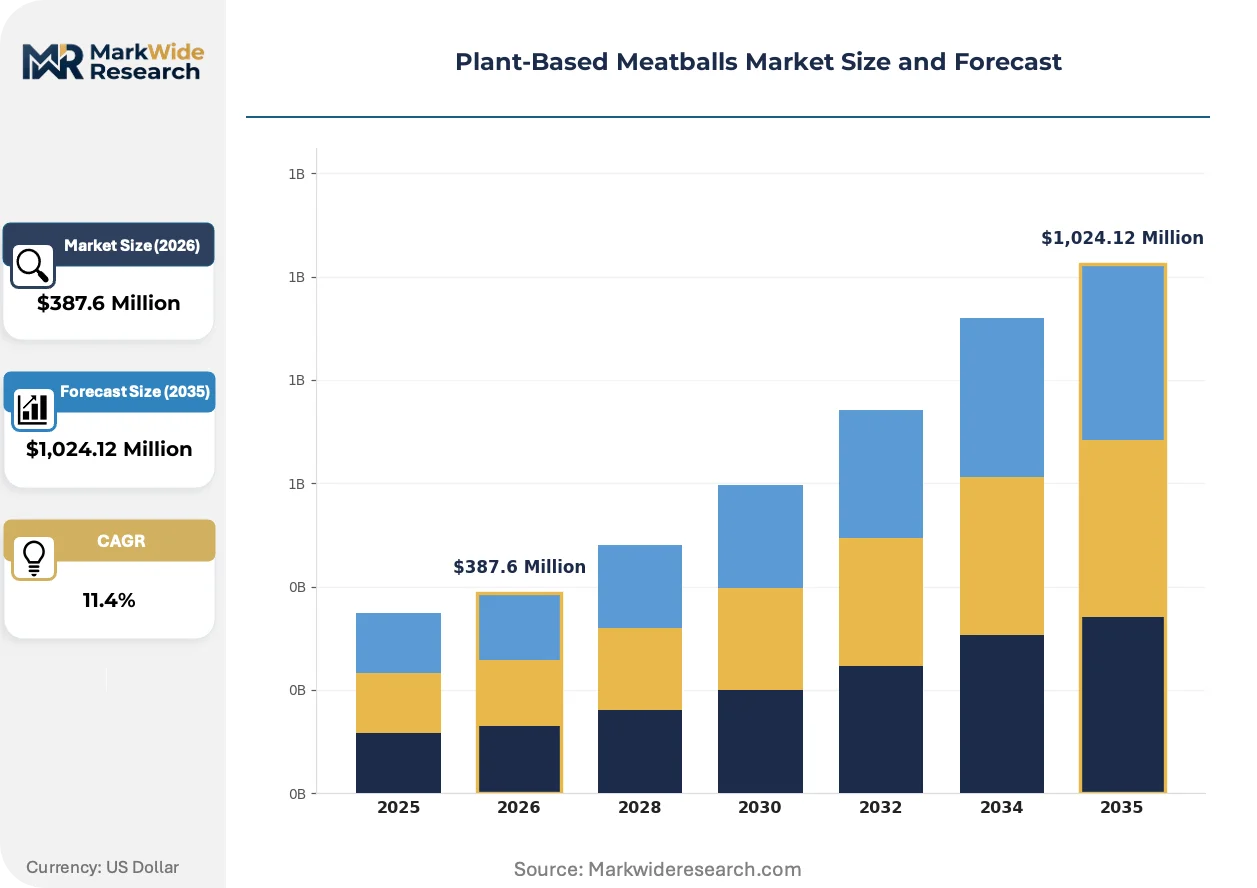
Market Dynamics
Pea protein supply consolidation and FDA labeling clarity are compressing formulation timelines while flexitarian household expansion in the United States pulls volume through foodservice channels.
Growth Catalysts
- EU Green Deal carbon accounting:European suppliers are retooling extrusion processes to meet low-carbon manufacturing mandates, opening premium positioning for clean-label formulations.
- Quick-service restaurant procurement:Foodservice operators are standardizing plant-based meatballs across menu categories without recipe reformulation by kitchen staff.
- Heme technology maturation:Advanced lipid-protein binding systems are achieving Maillard browning parity with conventional meat in high-heat applications.
Market Restraints
- Pea protein input volatility:Weather-driven harvest variability in Canada and France concentrates price risk for manufacturers dependent on isolate supply.
- Extrusion equipment capex intensity:High-shear texturization lines require seven-figure capital commitments that freeze out regional processors.
- Allergen labeling burdens:Soy concentrate formulations face mandatory disclosure requirements in multiple US state jurisdictions and EU member markets.
Strategic Opportunities
- Institutional catering penetration:US school districts and hospital systems represent undercontracted volume pools with standardized nutrition requirements.
- Chilled format distribution:Specialty retail cold cases command margin premiums through freshness positioning against frozen mass-market SKUs.
- F-Gas Regulation compliance:European freezer technology upgrades are creating first-mover advantages for brands with low-carbon cold-chain partnerships.
Industry Challenges
- Extrusion engineering talent scarcity:The specialized skill set for high-moisture extrusion texturization is concentrated among a handful of equipment vendors and research institutions.
- Dual jurisdiction facility compliance:Shared processing lines with conventional meat trigger simultaneous FDA labeling oversight and USDA inspection protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Meatballs Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Chilled, Shelf Stable, Ready-to-Cook Ingredient: Pea Protein, Soy Protein, Lentils, Seitan Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Foodservice End User: Vegetarians, Vegans, Flexitarians, Health-Conscious Consumers |
| Companies Covered | Beyond Meat, Impossible Foods, Nestlé (Garden Gourmet / Sweet Earth Foods), Kellogg Company (MorningStar Farms), IKEA Food Services, Quorn Foods, Gardein, Lightlife Foods (Greenleaf Foods), Field Roast Grain Meat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Meatballs Market Strategic Shifts
Formulation science and regulatory precision are converging to compress product development cycles while demand-side purchasing patterns fragment across channel types.
High-moisture extrusion technology is rewriting the texture-performance frontier for plant-based meatballs by enabling fibrous protein alignment previously achievable only through animal muscle structure. Foodservice distributors are adopting these systems at accelerated pace to secure supply continuity for quick-service chains. The structural consequence is a compression of sensory parity timelines from multi-year development cycles to eighteen-month windows.
The FDA's updated guidance on cell-cultured and plant-based meat alternative labeling is clarifying compliance pathways for manufacturers navigating nutritional equivalence claims. This regulatory precision is reducing legal uncertainty for brands expanding across state lines. Frozen product categories are responding fastest by standardizing front-of-package disclosure formats ahead of enforcement deadlines.
Flexitarian households are fragmenting procurement patterns between retail stock-up trips and foodservice trial occasions, creating dual-channel loyalty programs. Traditional grocery freezer dominance is yielding to direct-to-restaurant supply relationships for weekly consumption occasions. This behavioral pivot is most visible in US metropolitan markets where specialty retail and quick-service locations operate within overlapping trade areas.
Plant-Based Meatballs Market Segmentation
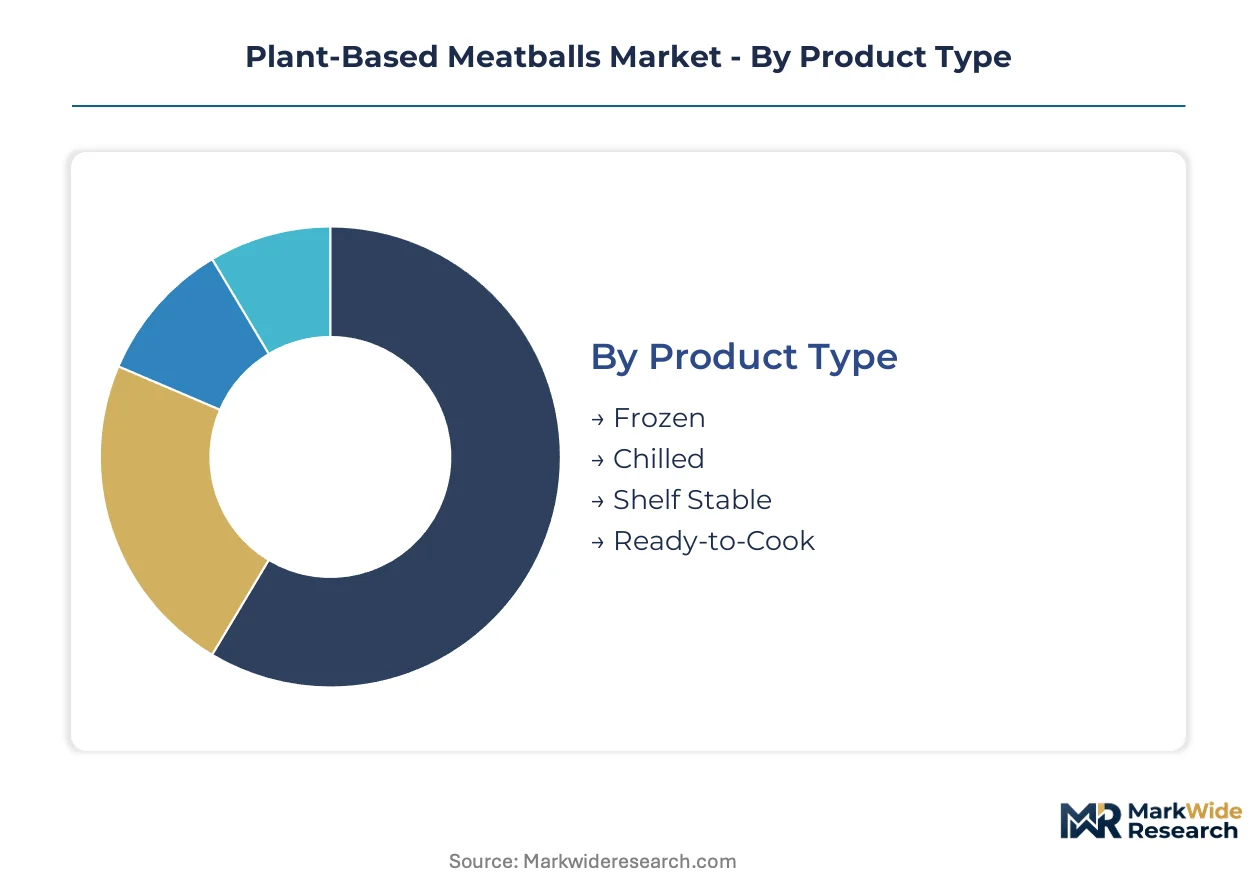
Plant-based meatballs fragment across preservation formats, protein sources, and channel strategies that each demand distinct cold-chain investments and labeling compliance. Manufacturers configure production lines around specific segment requirements rather than attempting universal formulations. The resulting specialization creates margin tiering that rewards precise targeting over broad coverage.
Product Type:
Upgrade cycles in freezing technology and retail cold-case expansion are reshaping which preservation formats capture household and foodservice volume.
- Frozen:Extended shelf life and established cold-chain infrastructure make this the default format for mass-market retail and institutional procurement. Quick-service restaurants in the United States standardize frozen SKUs to minimize kitchen handling complexity and inventory spoilage risk.
- Chilled:Freshness positioning commands margin premiums in specialty retail and metropolitan markets with reliable refrigerated distribution. European retailers are expanding chilled case space for plant-based proteins under EU Green Deal carbon accounting that favors shorter supply chains.
- Shelf Stable:Retort packaging and aseptic processing enable ambient distribution in regions with underdeveloped cold-chain infrastructure.
- Ready-to-Cook:Pre-seasoned and sauced formats reduce preparation steps for time-constrained households and casual dining operators.
Volume placements concentrate in Frozen; the faster expansion belongs to Chilled.
Ingredient:
Cost tiers separate commodity protein sources from premium isolate formulations that carry allergen and clean-label advantages.
- Pea Protein:Isolate formulations achieve superior binding and neutral flavor profiles that support premium positioning. FDA labeling clarity on allergen declarations is accelerating pea protein adoption in US retail channels where soy disclosure burdens deter certain buyers.
- Soy Protein:Concentrate and isolate variants retain cost advantages in mass-market distribution and Asian markets with established soy consumption patterns. State-level allergen labeling mandates in the US and EU member requirements continue to compress soy's addressable market in allergen-sensitive segments.
- Lentils:Whole-food positioning and fiber content appeal to clean-label seekers in European specialty retail.
- Seitan:Wheat gluten base serves niche vegetarian markets with established acceptance of traditional meat analogues.
Cost efficiency clusters in Soy Protein; the steepest expansion trajectory is Pea Protein.
Distribution Channel:
Customer type fragmentation between stock-up shoppers and immediate-consumption buyers is forcing parallel channel investments.
- Supermarkets:Freezer and refrigerated case placement drives trial among mainstream shoppers. US chains are expanding facings for plant-based meatballs in conventional meat adjacent sections to capture flexitarian crossover traffic.
- Foodservice:Direct supply relationships with quick-service chains and institutional caterers generate predictable volume commitments. School districts and hospital systems in the United States represent undercontracted pools with standardized nutrition requirements.
- Online Retail:Subscription models and direct-to-consumer shipping enable trial sizes and flavor variety packs.
- Specialty Stores:Curated assortments and educated staff support premium chilled formats and emerging ingredient technologies.
Revenue scale favors Supermarkets; margin expansion is concentrating in Foodservice.
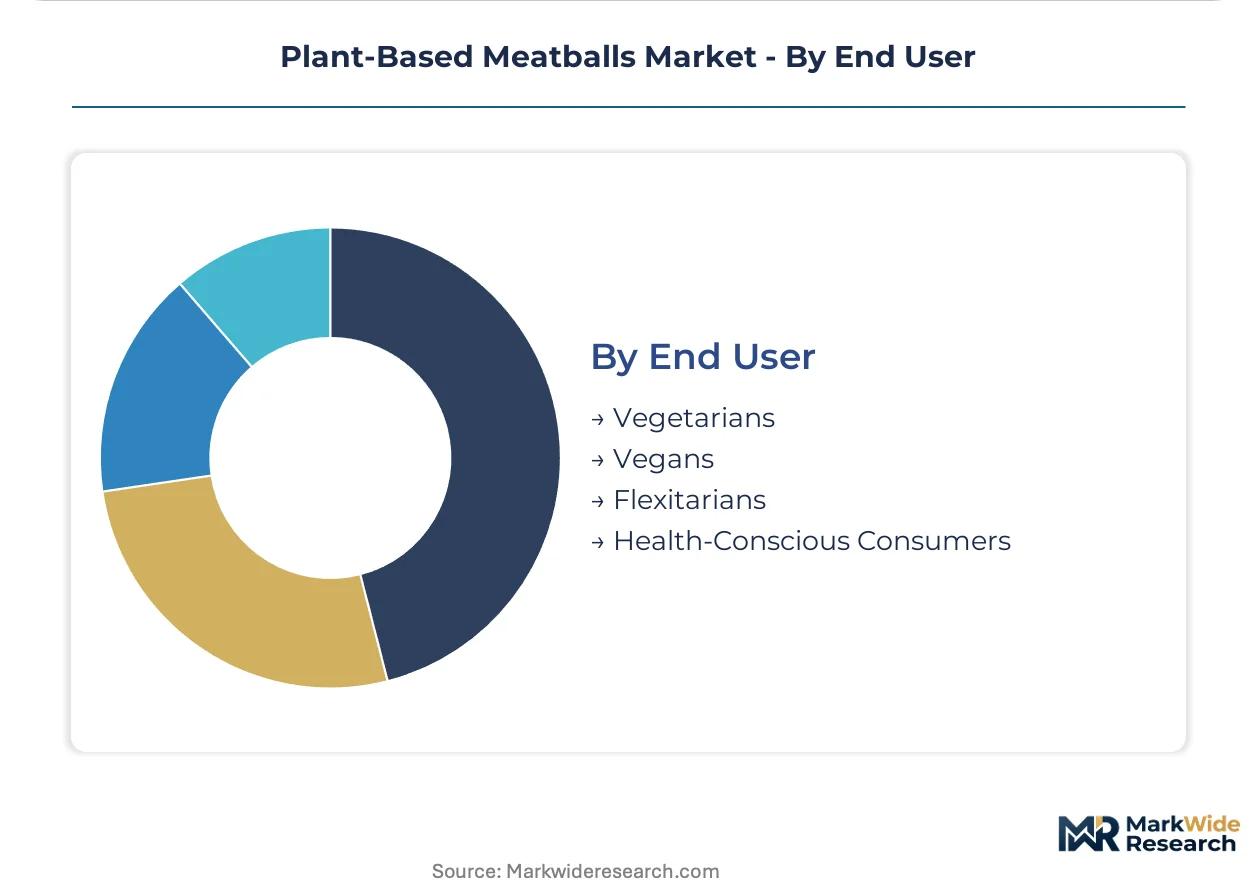
End User:
Application maturity varies sharply across dietary commitment levels, with occasional users now outnumbering strict adherents.
- Flexitarians:Occasional meat reduction drives the largest addressable population and fastest purchase frequency. Metropolitan US households in this cohort split procurement between weekly retail stock-ups and foodservice trial occasions.
- Health-Conscious Consumers:Protein content and clean-label positioning motivate purchase independent of ethical or environmental framing. European buyers in this segment prioritize carbon footprint disclosure under EU Green Deal transparency requirements.
- Vegetarians:Established category users with consistent replenishment patterns and brand loyalty.
- Vegans:Strict formulation requirements around cross-contamination and ingredient sourcing support premium pricing.
Volume concentrates in Flexitarians; the fastest share gain is Health-Conscious Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexitarian household expansion in the United States is pulling the largest volume share through foodservice channels, while European suppliers retool manufacturing to meet carbon accounting mandates under the EU Green Deal.
United States
Quick-service restaurant procurement and institutional catering contracts are standardizing plant-based meatballs across menu categories without kitchen reformulation. FDA labeling guidance on cell-cultured and plant-based meat alternatives is clarifying compliance pathways for nutritional equivalence claims. Chicago and Los Angeles metropolitan areas concentrate foodservice distributor activity where direct-to-restaurant supply relationships are displacing traditional grocery freezer dominance.
Germany
Clean-label positioning and EU Green Deal carbon transparency requirements are accelerating demand among health-conscious consumer segments. The F-Gas Regulation is forcing freezer technology upgrades that create first-mover advantages for brands with low-carbon cold-chain partnerships. Bavaria hosts manufacturing scale for Garden Gourmet's European operations, with extrusion facilities retooling to meet low-carbon manufacturing mandates.
United Kingdom
Specialty retail cold-case expansion and metropolitan flexitarian purchasing patterns are fragmenting procurement between stock-up and immediate-consumption occasions. EFSA and national allergen labeling standards are compressing soy protein's addressable market in favor of pea isolate formulations. London and the Southeast concentrate chilled format distribution where freshness positioning commands margin premiums against frozen mass-market SKUs.
Canada
Weather-driven pea protein harvest variability is concentrating price risk for manufacturers dependent on Canadian isolate supply. Health Canada and the Canadian Food Inspection Agency oversee dual jurisdiction facility compliance where shared processing lines trigger simultaneous labeling and inspection protocols. Prairie provinces anchor pea protein cultivation, with processing capacity expanding to secure supply continuity for North American manufacturers.
France
Lentil-based whole-food positioning and fiber content are appealing to clean-label seekers in European specialty retail. REACH and national carbon accounting standards are reshaping ingredient sourcing and energy-intensive extrusion processes for suppliers serving French markets. The Île-de-France region concentrates foodservice procurement for institutional catering contracts with standardized nutrition requirements.
Plant-Based Meatballs Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers secure pea protein processing capabilities and high-moisture extrusion lines. The vendor base clusters around three strategic archetypes: vertically integrated protein processors, technology-licensing specialists, and retail-brand holding companies. M&A activity and strategic partnerships are consolidating supply chain control, while geographic expansion and portfolio diversification target undercontracted institutional channels.
Within the technology-licensing tier, Impossible Foods anchors heme-based formulation strategies, while Beyond Meat exemplifies backward integration into pea protein processing. Nestlé occupies a position across multiple archetypes through its dual-brand structure, with Garden Gourmet representing European manufacturing scale and Sweet Earth Foods anchoring North American retail penetration.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Nestlé (Garden Gourmet / Sweet Earth Foods) |
| Kellogg Company (MorningStar Farms) |
| IKEA Food Services |
| Quorn Foods |
| Gardein |
| Lightlife Foods (Greenleaf Foods) |
| Field Roast Grain Meat |
| Others |
Value Chain & Pricing Dynamics
Quick-service restaurant procurement concentration in the United States is compressing margins through high-volume contract terms that favor frozen SKU standardization over premium chilled formats. This buyer archetype dominance forces manufacturers into three-tier pricing structures across premium isolate formulations, standard concentrate blends, and economy private-label supply.
Pricing Analysis
Volume placements in frozen mass-market SKUs sacrifice margin for scale commitments from quick-service chains, while chilled specialty retail formats capture premium pricing through freshness positioning and shorter supply chains. Price differentiation separates pea protein isolates carrying allergen-clean-label advantages from soy concentrates facing disclosure burdens in multiple US state jurisdictions. Pricing pressure stems from weather-driven pea harvest variability in Canada and France that concentrates input cost volatility for isolate-dependent manufacturers. Foodservice operators exhibit the highest price sensitivity due to standardized nutrition requirements and competitive bidding protocols, whereas specialty retail buyers accept premiums for carbon-transparent sourcing under EU Green Deal mandates.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-controlled returns remains underdeveloped outside metropolitan cold-chain hubs, creating spoilage liability concentrated with distributors rather than manufacturers. Raw material supply draws from Canadian and French pea protein cultivation, US midwest soy processing, and European lentil sourcing for whole-food positioning. Single-source vulnerability concentrates in high-moisture extrusion equipment where specialized engineering talent is tethered to a handful of German and Italian vendors. Distribution runs through foodservice direct-supply relationships displacing traditional grocery freezer dominance in US metropolitan markets, with institutional catering contracts generating predictable volume commitments for manufacturers meeting USDA facility inspection protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is accelerating into a vertical-integration race as manufacturers pursue captive pea protein processing to insulate margins from harvest-driven input volatility and secure supply continuity for foodservice scale commitments.
For Market Incumbents: Anticipate margin compression from emerging private-label entrants by securing long-term offtake agreements with Canadian prairie processors and retooling extrusion lines for low-carbon manufacturing compliance ahead of EU F-Gas Regulation enforcement deadlines. Capacity addition in Bavaria and the US Midwest reinforces defensive positioning against supply disruption. For New Entrants and Emerging Players: Begin with institutional catering penetration in US school districts and hospital systems where standardized nutrition requirements and undercontracted volume pools offer lower competitive intensity than branded retail shelf space. Direct-to-foodservice supply relationships bypass incumbent freezer dominance and establish trial velocity before retail expansion. For Investors and Strategic Acquirers: The window for entry favors technology-licensing specialists with differentiated heme or high-moisture extrusion capabilities that incumbent holding companies lack in-house. Watch FDA enforcement timelines on cell-cultured and plant-based labeling guidance as the signal for regulatory clarity that triggers consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Processing | Beyond Meat's captive supply secures cost predictability against Canadian harvest volatility. |
| Heme Technology Licensing | Impossible Foods' lipid-protein binding systems achieve Maillard browning parity in high-heat foodservice applications. |
| Low-Carbon Extrusion Retooling | Garden Gourmet's Bavaria facilities meet EU Green Deal carbon accounting mandates for premium positioning. |
| Institutional Catering Contracts | Sweet Earth Foods penetrates US school districts with standardized nutrition compliance bypassing retail competition. |
| Chilled Format Cold-Chain Partnerships | Specialty retail distribution in London and Los Angeles commands freshness premiums against frozen mass-market SKUs. |
Study Parameters
Document review covered FDA labeling guidance filings, EU Green Deal implementation protocols, and USDA facility inspection records, complemented by interviews with plant-based protein R&D directors, foodservice procurement managers at quick-service chains, extrusion equipment engineers, and specialty retail category buyers. Secondary validation drew from SEC filings of publicly traded protein processors, trade customs data on pea isolate imports, and cold-chain infrastructure disclosures. Bottom-up volume modeling across preservation formats, protein sources, and distribution channels was triangulated against top-down market sizing from macroeconomic consumption trend analysis.
Cross-referencing historical CAGRs from analogous protein alternative categories against panel input from manufacturing executives and distributor planning officers anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include preservation format, protein source ingredient, distribution channel strategy, and end-user dietary commitment level. Growth trajectories incorporate foodservice procurement velocity, flexitarian household expansion patterns, and regulatory enforcement timeline assumptions without year-specific event forecasting.
Pea protein harvest variability, FDA labeling enforcement acceleration, and EU F-Gas Regulation compliance cost inflation are the dominant revision risks that could compress or extend manufacturer margin recovery timelines. Practitioners should monitor Canadian prairie weather patterns, state-level allergen disclosure mandate expansion, and cold-chain technology upgrade cycles for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
France Plant Protein Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Rice Protein Market
Plant Based Food
Vegan Pizza Crust Market
Plant Based Food
Plant-Based Chorizo Market
Plant Based Food
Vegan Food Market
Plant Based Food
Canada Plant-Based Food and Beverages Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Plant-Based Yogurt Market
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
Plant-Based Sausages Market