
 US Potato Chips Market | 2026-2036
US Potato Chips Market Size, Share, and Industry Trends Forecast 2026-2036
US Potato Chips Market Outlook
Convenience store channel expansion is repositioning how manufacturers prioritize single-serve and grab-and-go pack formats. PepsiCo (Frito-Lay) dominates the mass-market landscape through its direct-store-delivery network that controls retail shelf placement. Utz Brands competes aggressively in the Mid-Atlantic and Southeast with a manufacturing footprint that sustains regional freshness positioning. Kettle Foods differentiates through small-batch kettle-cooked production that anchors its premium price tier in natural and specialty grocers.
US potato chips are thin-sliced potatoes fried or baked until crisp, typically containing two to three millimeters thickness, oil content between 30 and 40 percent by weight, and moisture levels below two percent for shelf stability. The product serves as a ready-to-eat salty snack for immediate consumption across retail and foodservice channels. Kettle-cooked variants command margin premiums through thicker cuts and longer fry times that deliver audible crunch and artisanal positioning. Flavored segments lead volume contribution, with barbecue and sour cream & onion profiles driving repeat purchase rates above plain salted baseline SKUs. Flexible bag packaging remains the structural default, though rigid containers are gaining traction in club and e-commerce channels where crush protection determines fulfillment viability.
The FDA enforces nutrition labeling accuracy and allergen disclosure under the Food Safety Modernization Act, while the USDA oversees potato grading standards that affect raw material procurement costs for processors. State-level regulations in California and New York are advancing sodium warning requirements and extended producer responsibility frameworks for flexible packaging waste. Stakeholders must monitor how FDA front-of-pack labeling proposals and emerging state packaging EPR laws will reshape formulation investment and material sourcing decisions.
Market Dynamics
Convenience store channel expansion is absorbing disproportionate promotional investment from manufacturers, with single-serve pack formats capturing impulse purchase occasions that traditional grocery multi-packs cannot reach. This channel shift is compressing margins while demanding faster inventory turns and localized distribution infrastructure.
Growth Catalysts
- Sun Belt Climate Concentration:Year-round warm temperatures in Texas, Florida, and Arizona sustain elevated per-capita salty snack consumption that outpaces seasonal northern markets.
- FDA Nutrition Facts Modernization:Updated serving-size accuracy requirements are forcing formulation transparency that builds consumer trust and reduces litigation exposure for compliant manufacturers.
- Kettle-Cooked Premiumization:Thicker-cut, longer-fry production methods are absorbing consumer willingness to pay artisanal price premiums in natural and specialty grocery channels.
Market Restraints
- Input Cost Volatility:Russet potato prices fluctuate with drought conditions in Idaho and Washington growing regions, compressing processor margins during poor harvest cycles.
- Sodium Disclosure Friction:FDA front-of-pack labeling proposals threaten to relegate high-sodium SKUs to less visible shelf positions, requiring expensive reformulation.
- Flexible Packaging Waste Liability:Extended producer responsibility frameworks advancing in California and New York impose end-of-life collection costs that commodity brands cannot easily absorb.
Strategic Opportunities
- Club Channel Rigid Container Adoption:Crush-resistant packaging formats are absorbing e-commerce fulfillment requirements where flexible bags fail, opening bulk purchase occasions.
- Barbecue and Sour Cream & Onion Flavor Extensions:Repeat purchase rates above plain salted baselines indicate white space for regional flavor localization in underpenetrated Midwest markets.
- USDA Grading Standard Arbitrage:Processors with superior raw material sorting capabilities can extract margin from grade-B potato streams that competitors discard.
Industry Challenges
- Sensory Panel Talent Scarcity:Qualified flavor chemists capable of optimizing fry-time and oil-absorption interactions for kettle-cooked texture targets command premium compensation that mid-tier processors struggle to match.
- Moisture Control Capex Intensity:Achieving sub-two-percent moisture levels for shelf stability requires continuous fryer and packaging line investments that strain regional manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Potato Chips Market |
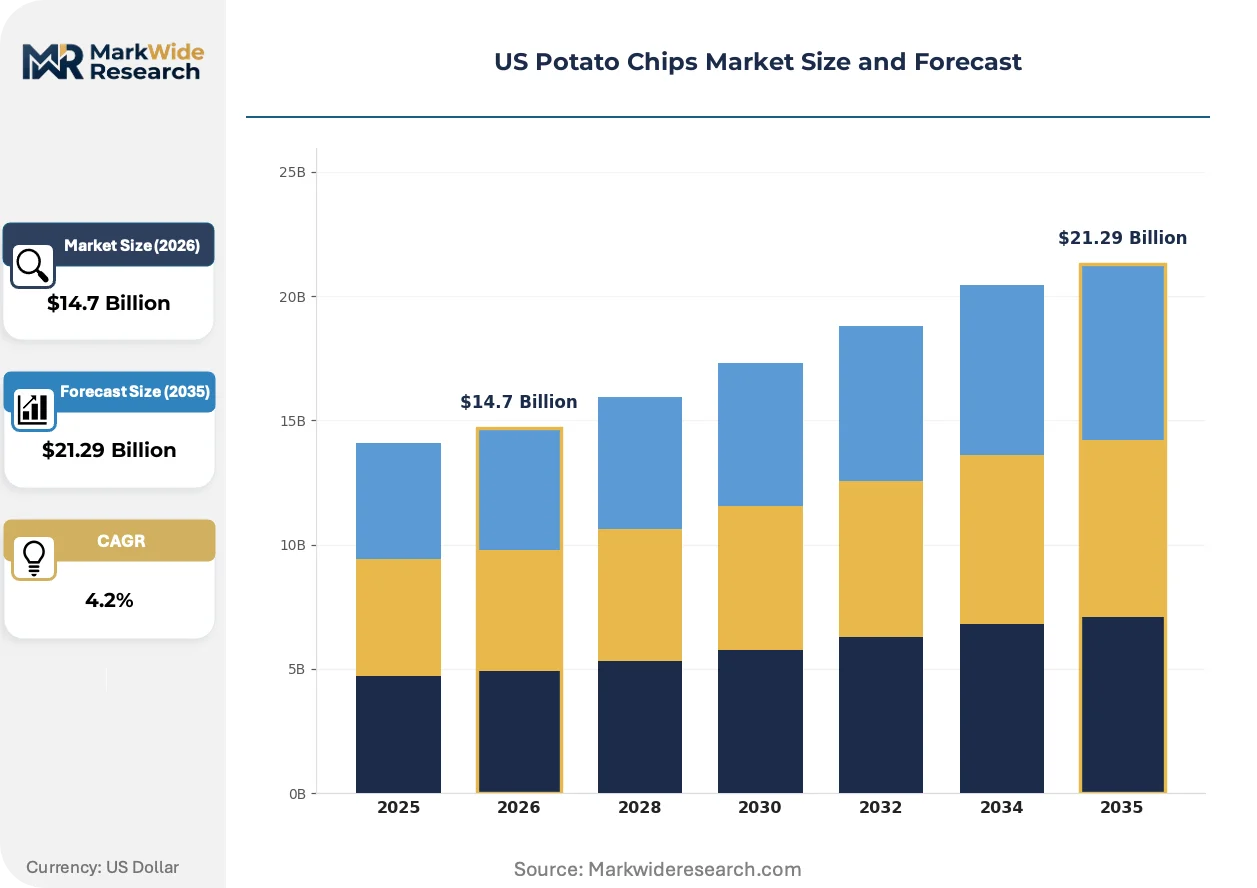
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $21.29 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Kettle-Cooked, Baked, Flavored Packaging Type: Flexible Bags, Rigid Containers, Bulk Packaging, Cans Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Foodservice Flavor Profile: Salted, Barbecue, Sour Cream & Onion, Cheddar Cheese |
| Companies Covered | Kellogg Company (Pringles), Kettle Foods, PepsiCo (Frito-Lay), Burts Potato Chips, Mars, Utz Brands, The Campbell Soup Company, Calbee, Herr Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Potato Chips Market Strategic Shifts
Processing technology and packaging material evolution are absorbing capital allocation that previously flowed into brand advertising. Manufacturers now compete on throughput efficiency and sustainability credentials rather than traditional media spend alone.
Vacuum frying technology is absorbing oil uptake reduction targets while preserving the crisp texture consumers expect from conventional atmospheric frying. Mid-Atlantic and Southeast processors are piloting these systems to meet pending sodium-reduction mandates without sacrificing mouthfeel. The structural consequence is that capital-intensive equipment upgrades are absorbing smaller competitors who cannot finance the transition, consolidating production capacity among scaled operators.
California's advancing extended producer responsibility legislation is absorbing packaging R&D budgets that previously targeted cost reduction alone. Flexible multilayer films must now demonstrate recyclability or compostability pathways to avoid fees that would erase commodity chip margins. Natural and specialty grocery segments are responding fastest, demanding supplier certifications that verify end-of-life material handling.
Direct-store-delivery networks are absorbing last-mile logistics functions that wholesalers once performed, giving manufacturers real-time velocity data and shelf-space control. Foodservice and vending channels are replacing traditional warehouse distribution for immediate consumption occasions. This disintermediation is most visible in Sun Belt metropolitan areas where convenience store density supports daily replenishment cycles that bulk distribution cannot match.
US Potato Chips Market Segmentation
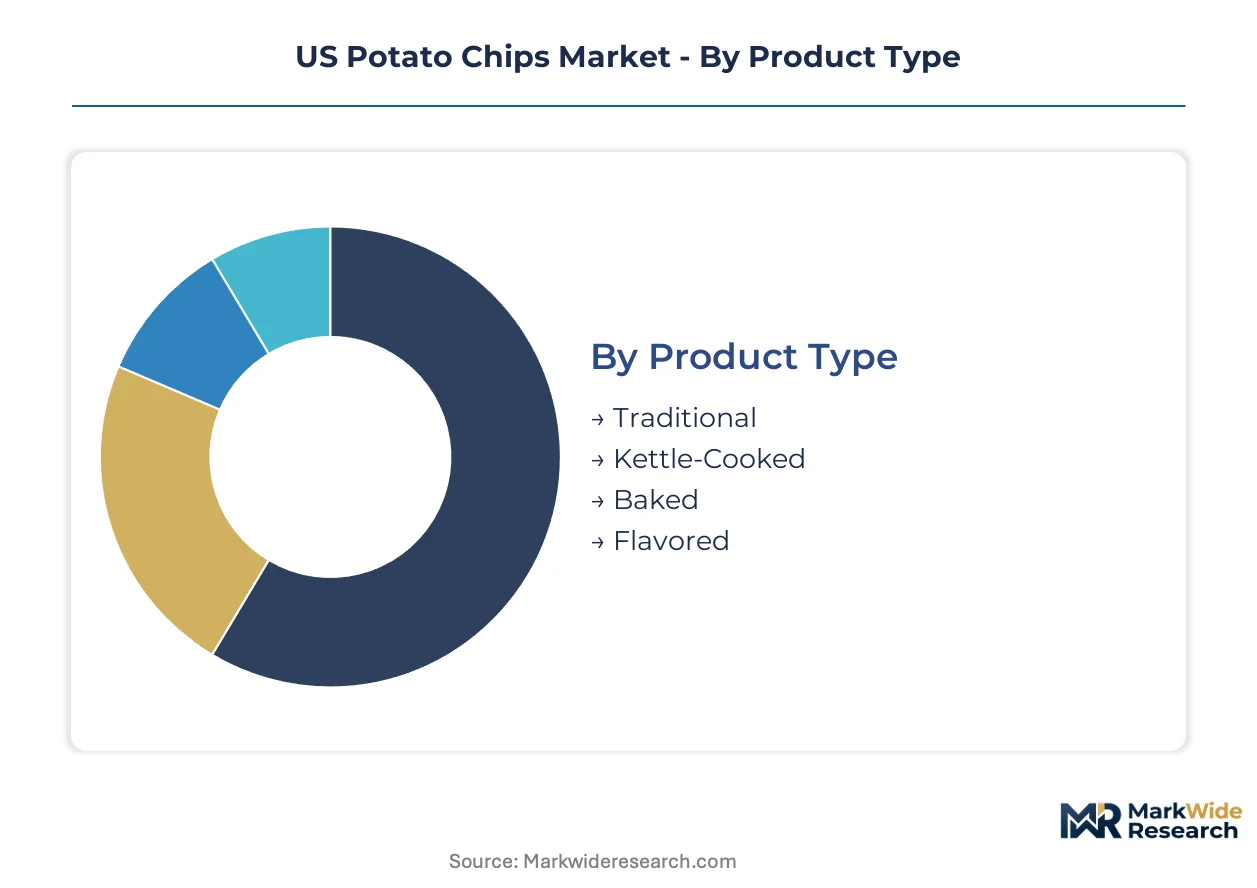
US potato chip segmentation reveals how manufacturers allocate capital across production technologies, packaging formats, and channel-specific demand patterns. Each dimension carries distinct margin profiles and regulatory exposure that shape portfolio strategy.
Product Type:
Consumer upgrade cycles from basic to premium textures are lengthening fry times and thickening slice specifications across manufacturing footprints.
- Traditional:Thin-sliced potatoes fried at atmospheric pressure achieve 30-40 percent oil content and sub-two-percent moisture for shelf stability. Demand concentrates in Midwest and Southeast mass-market grocery where price-sensitive households prioritize volume value over texture differentiation.
- Kettle-Cooked:Thicker cuts and batch-fry methods deliver audible crunch and artisanal positioning that commands margin premiums in natural and specialty grocers. Texas and Florida convenience store chains are expanding dedicated kettle-cooked facings to capture Sun Belt impulse purchase occasions.
- Baked:Hot-air circulation reduces oil absorption for health-positioned SKUs targeting sodium-conscious consumers in California and New York metro areas.
- Flavored:Seasoning application lines enable barbecue, sour cream & onion, and cheddar cheese profiles that drive repeat purchase rates above plain salted baselines.
Traditional sits at the top of the volume ranking, with Kettle-Cooked climbing the fastest.
Packaging Type:
Cost tier stratification separates commodity flexible formats from premium rigid solutions serving club and e-commerce fulfillment requirements.
- Flexible Bags:Multilayer films dominate shelf presence with moisture barrier properties and vertical display efficiency. California and New York extended producer responsibility frameworks are forcing recyclability certifications that commodity brands struggle to absorb.
- Rigid Containers:Crush-resistant tubs and canisters protect product integrity through e-commerce last-mile handling. Club channel adoption in Texas and Arizona is absorbing bulk purchase occasions where flexible bags fail.
- Bulk Packaging:Foodservice totes and institutional sacks serve vending and concession operators with portion-control requirements.
- Cans:Metal and composite cylinders preserve freshness for premium export and gift segments with extended distribution cycles.
Flexible Bags maintain volume leadership, with Rigid Containers expanding most quickly.
Distribution Channel:
Application-specific consumption occasions are fragmenting inventory deployment between immediate consumption and planned pantry stocking.
- Supermarkets:Multi-pack promotions and end-cap displays anchor household stock-up behavior. Idaho and Washington retail networks leverage proximity to processing facilities for freshness positioning.
- Convenience Stores:Single-serve grab-and-go formats capture impulse occasions that compressed margins demand faster inventory turns. Sun Belt metropolitan density supports daily direct-store-delivery replenishment cycles.
- Online Retailers:Subscription bundles and variety packs require crush-resistant packaging configurations that rigid containers satisfy.
- Foodservice:Portion cups and bulk totes serve stadium, cinema, and lodging channels with controlled serving specifications.
Supermarkets hold the volume base, with Convenience Stores gaining share fastest.
Flavor Profile:
Customer type differentiation separates baseline salted households from flavor-adventurous repeat purchasers willing to pay formulation premiums.
- Salted:Unseasoned baseline SKUs serve traditionalist consumers and private-label programs with minimal ingredient complexity. Midwest mass-market penetration remains deepest where plain profiles dominate pantry staples.
- Barbecue:Tomato-based seasoning with smoke and sweetness profiles drives above-baseline repeat rates. Regional localization opportunities exist in underpenetrated Midwest markets where Kansas City and Memphis smoke variations could expand.
- Sour Cream & Onion:Dairy-forward seasoning systems require allergen disclosure precision under FDA labeling mandates. Natural and specialty grocers in California demand clean-label dairy alternatives.
- Cheddar Cheese:Cheese powder application lines target youth and family segments with bold color and umami intensity.
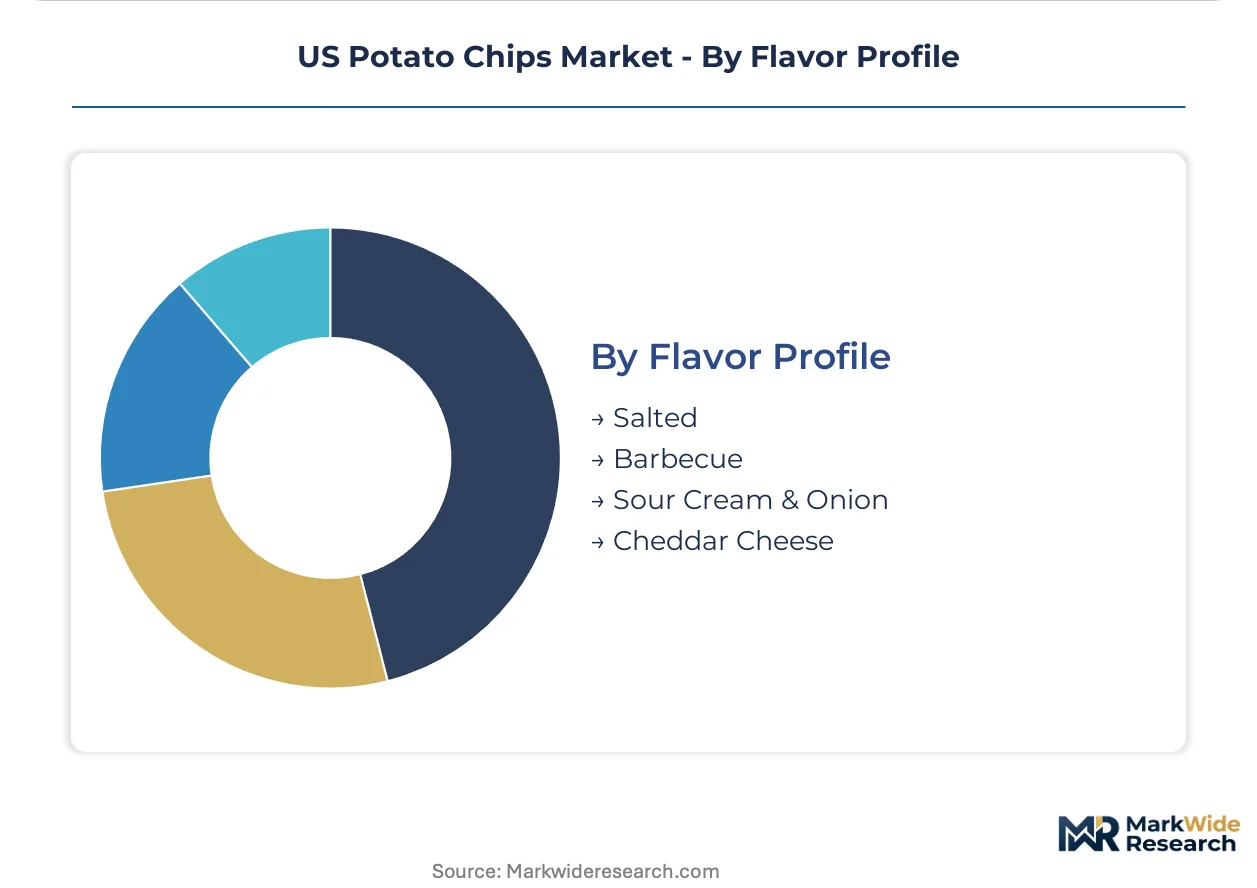
Salted remains the volume foundation, with Barbecue showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processors are relocating production capacity toward states with lower compliance burdens for sodium disclosure and packaging waste regulations. Idaho and Washington maintain raw material advantages while Sun Belt states absorb volume growth from year-round consumption patterns.
Texas
Convenience store density in Dallas-Fort Worth and Houston sustains daily direct-store-delivery replenishment cycles unmatched elsewhere. The Texas Department of State Health Services enforces food safety standards that remain less prescriptive than California's sodium warning mandates. Kettle-cooked facings are expanding across Buc-ee's and Stripes chains to capture impulse purchases from warm-weather snacking behavior.
California
Health-positioned baked SKUs concentrate in Los Angeles and San Francisco metro natural grocery channels. The state's extended producer responsibility framework imposes packaging end-of-life fees that commodity brands struggle to absorb. Vacuum frying pilot programs in Central Valley processing facilities target sodium reduction without texture degradation.
Florida
Tourism-driven foodservice demand in Orlando and Miami absorbs bulk tote formats for stadium and lodging channels. The Florida Department of Agriculture and Consumer Services oversees potato grading standards with enforcement lighter than USDA federal requirements. Publix and Winn-Dixie distribution networks prioritize regional freshness positioning through Southeast manufacturing partnerships.
Idaho
Proximity to Russet potato growing regions in the Magic Valley sustains lowest raw material procurement costs nationwide. EPA water discharge permits for processing facilities face stricter scrutiny under updated Clean Water Act interpretations. Lamb Weston and J.R. Simplot processing clusters anchor national supply chains with rail connectivity to West Coast ports.
New York
Metro area specialty grocers in Manhattan and Brooklyn demand clean-label dairy alternatives for sour cream and onion formulations. The state's advancing extended producer responsibility legislation mirrors California's packaging fee structures. Herr Foods and Utz Brands maintain distribution advantages through Mid-Atlantic manufacturing footprints serving Northeast corridor density.
US Potato Chips Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with direct-store-delivery networks controlling shelf placement in convenience channels while private-label programs absorb supermarket volume. The structure concentrates among three scaled operators with national distribution infrastructure, leaving mid-tier regional processors to compete on freshness positioning and flavor localization. Strategic archetypes include mass-market volume leaders, premium kettle-cooked specialists, and private-label contract manufacturers. Competitive moves center on M&A consolidation of regional brands and capital-intensive kettle-cooking capacity expansion.
Among mass-market operators, PepsiCo (Frito-Lay) and Kellogg Company (Pringles) anchor national distribution through direct-store-delivery networks that control retail shelf placement. Utz Brands exemplifies the regional consolidation archetype, occupying a position built on Mid-Atlantic and Southeast manufacturing proximity. Kettle Foods represents the premium-tier specialist model, sitting within the natural and specialty grocery channel where small-batch production commands artisanal price positioning.
| Leading Market Players |
|---|
| Kellogg Company (Pringles) |
| Kettle Foods |
| PepsiCo (Frito-Lay) |
| Burts Potato Chips |
| Mars |
| Utz Brands |
| The Campbell Soup Company |
| Calbee |
| Herr Foods |
| Others |
Value Chain & Pricing Dynamics
Russet potato procurement costs flow from Idaho and Washington growing regions through three-tier pricing structures that separate kettle-cooked premiums from traditional economy SKUs. Oil and energy inputs anchor variable cost positions that manufacturers pass through contract structures or absorb via formulation efficiency.
Pricing Analysis
Retailer markup layers absorb direct-store-delivery premiums that Frito-Lay and Utz Brands negotiate for shelf-space control. Pricing stratifies across premium kettle-cooked, standard traditional, and economy private-label tiers based on slice thickness and fry-time specifications. Cost compression in commodity flexible packaging is intensifying because California and New York extended producer responsibility fees threaten margin structures. Mass-market grocery buyers in the Midwest exhibit highest price sensitivity, while natural channel consumers in California demonstrate lowest sensitivity to artisanal positioning.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale replenishment through PepsiCo's direct-store-delivery network that bypasses wholesale intermediaries. Geographic supply concentration centers on Idaho, Washington, and Texas, where processing clusters minimize raw material transit. The supply chain rests on Russet potato grades, frying oil stocks, and multilayer film packaging as critical inputs. Single-source vulnerability in Idaho potato sourcing exposes processors to drought-driven harvest volatility. Distribution runs through regional manufacturing footprints with rail connectivity to Sun Belt consumption centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Kettle-cooked upgrade cycles demonstrate sustained consumer willingness to pay texture premiums that absorb input cost volatility.
For Market Incumbents: Lock in shelf-space exclusivity through direct-store-delivery network density that emerging competitors cannot replicate. Kettle-cooking capacity expansion in Texas and Florida captures Sun Belt impulse occasions before regional processors consolidate. Sodium disclosure mandates from FDA front-of-pack proposals threaten to displace high-SKU facings, requiring reformulation investment as defensive priority. For New Entrants and Emerging Players: The price-point gap between kettle-cooked premiums and traditional economy tiers offers white-space for mid-market texture positioning. Underpenetrated Midwest barbecue flavor localization presents the most penetrable segment, with Kansas City smoke variations absorbing regional identity marketing. Foodservice bulk tote formats for stadium and cinema channels provide lower-barrier go-to-market entry than retail shelf competition. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier regional processors face capital intensity for vacuum frying compliance and moisture control capex. Long-term viability favors scaled operators with backward integration into potato sourcing and multichannel distribution infrastructure. Target acquisition archetypes include Southeast regional brands with freshness positioning and underutilized kettle-cooking capacity. The signal to monitor is California extended producer responsibility fee implementation timing, which will accelerate distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Kettle-Cooking Capacity Expansion | Captures Sun Belt impulse demand through thicker-cut, longer-fry production methods. |
| Direct-Store-Delivery Network Densification | Secures shelf-space control against wholesale-dependent competitors in convenience channels. |
| Sodium Reduction Reformulation | Prevents FDA front-of-pack labeling displacement through vacuum frying pilot programs. |
| Extended Producer Responsibility Compliance | Avoids California and New York packaging fees that erase commodity chip margins. |
| Regional Flavor Localization | Exploits barbecue repeat purchase premiums in underpenetrated Midwest markets. |
Study Parameters
Multiple input streams — primary interviews with brand managers and category buyers at retailers, supply planners at processors, and channel sales heads — were reconciled against secondary validation from Nielsen retail audit data, USDA potato grading reports, and FDA labeling guidance documents. Bottom-up volume modeling across product type, packaging format, and distribution channel dimensions was triangulated with top-down category sizing from customs records and processor capacity disclosures.
Historical consumption patterns were cross-referenced against panel input from Sun Belt convenience store operators and natural grocery procurement leads. Segmentation dimensions modeled include product texture tier, packaging rigidity, channel fulfillment requirements, and regional climate-driven demand patterns. CAGRs were derived from trend extrapolation adjusted for regulatory phase-in schedules and capital investment cycles. Industry-specific forecast inputs incorporated Idaho potato harvest yield variability and California packaging legislation implementation trajectories.
Caveats apply where FDA sodium disclosure finalization timing or extended producer responsibility fee structures could materially shift the outlook. Forecasts reflect documented assumptions regarding convenience store channel share expansion and kettle-cooked premiumization sustainability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Super Low Calorie Snacks Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Low Calorie Cookies Market
Snacks
Packaged Rice Snacks Market
Snacks
Australia Snack Bar Market
Snacks
Organic Snacks Market
Snacks
France Energy Bar Market
Snacks
Sweet Potato Fries Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Global Vegetable Chips Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
Baked Chips Market
Snacks
Legume-Based Snacks Market
Snacks
Europe Snacks Food Market
Snacks
India Energy Bar Market
Snacks
South Korea Snack Bar Market