
 Global Plant Protein Market | 2026-2036
Global Plant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plant Protein Market Outlook
Asset-light toll manufacturing and third-party protein extraction leasing is tilting competitive dynamics toward specialized processors without crushing capital burdens. Cargill, Incorporated leverages its North American oilseed crush network to anchor soy protein isolate supply for food manufacturers. Roquette Frères specializes in pea protein fractionation from its Manitoba facility, sustaining European and North American customer relationships through dedicated crop contracting.
Plant protein denotes protein concentrates, isolates, and hydrolysates extracted from legumes, cereals, and oilseeds through aqueous or alkaline extraction, typically achieving protein contents of 50% to 90% by dry weight for food-grade applications. These ingredients function as functional emulsifiers, gelling agents, and nutritional fortifiers across formulated foods, supplements, and feed matrices. Soy protein dominates current volume flows due to established crush infrastructure and cost-optimized extraction protocols, while pea protein captures accelerating demand from allergen-free and non-GMO product specifications in European and North American retail channels. Wheat protein occupies a narrower but defensible position in bakery and meat analog applications where gluten functionality provides irreplaceable viscoelastic properties.
The FDA governs plant protein ingredient safety through GRAS notifications and food additive petitions, while EFSA evaluates novel protein sources under EU novel food regulations including recent rulings on insect and algae proteins that indirectly shape plant protein competitive positioning. REACH compliance for processing aids and extraction solvents affects European manufacturing economics, particularly for organic solvent-based isolate production. Stakeholders must monitor evolving protein content labeling thresholds and carbon footprint disclosure requirements that will determine which extraction technologies and source crops achieve preferred procurement status.
Market Dynamics
EU Green Deal protein diversification mandates are forcing food manufacturers to reconfigure ingredient procurement away from animal-derived inputs toward certified plant protein streams, compressing reformulation timelines and supplier qualification cycles.
Growth Catalysts
- EU Green Deal protein targets:Binding diversification mandates in Germany, France, and the Netherlands compel CPG brands to reformulate with minimum plant protein thresholds by 2030.
- Precision fermentation integration:Hybrid processing combining traditional extraction with biomass fermentation is reducing isolate production energy intensity by 30-40% in pilot facilities.
- Brazilian soybean infrastructure:Domestic crush capacity expansion in Mato Grosso and Paraná is shortening supply chains for South American meat analog manufacturers.
Market Restraints
- Soybean price volatility:Weather-driven yield fluctuations in Argentina and Illinois soybean belts transmit directly to isolate input costs with 3-6 month lags.
- Pea protein supply concentration:Fractionation capacity clusters in Manitoba, Canada and northern France, creating single-source dependency for European formulators.
- Functional gap in high-moisture extrusion:Current pea and fava isolates fail to replicate soy's fibrous bite texture in whole-muscle analog applications above 60% moisture.
Strategic Opportunities
- India pulse protein valorization:Underutilized chickpea and mung bean processing infrastructure in Gujarat and Madhya Pradesh offers low-capex entry for isolate production.
- Pet food protein fortification:Premium companion animal nutrition brands in the US and UK are specifying 25%+ protein content from single-source plant bases.
- Carbon labeling differentiation:Early adopters of ISO 14067-compliant footprint disclosure are securing preferred supplier status with UK and Scandinavian retailers.
Industry Challenges
- Food technologist scarcity:Formulation expertise spanning protein chemistry, extrusion engineering, and sensory science commands 40-60% salary premiums in the US and EU.
- Organic certification timelines:Three-year transition periods for contracted pulse acres delay organic isolate availability, mismatching brand launch calendars.
- Cross-contamination protocols:Allergen-free production lines require dedicated facilities, compressing margins for mid-scale toll manufacturers serving niche brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plant Protein Market |
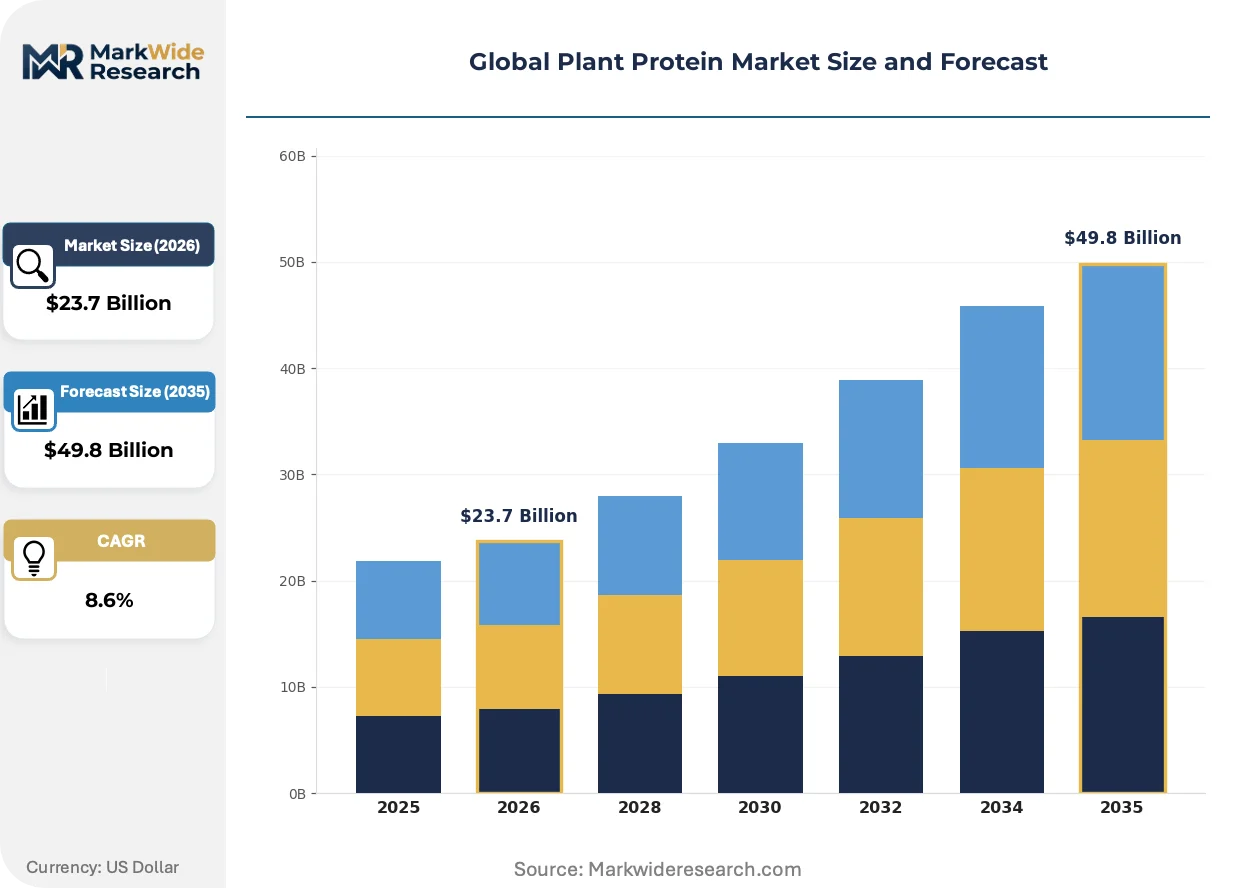
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Protein, Pea Protein, Wheat Protein, Rice Protein Application: Food & Beverage, Nutritional Supplements, Animal Feed, Pharmaceuticals End User: Retail Consumers, Food Manufacturers, Dietary Supplement Companies, Animal Feed Producers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Kerry Group PLC, Ingredion Incorporated, Roquette Frères, Wilmar International Ltd., Glanbia PLC, AGT Food and Ingredients, International Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plant Protein Market Strategic Shifts
Digital twin modeling of extraction processes is compressing R&D cycles and enabling real-time optimization of yield and energy consumption across distributed processing networks.
Membrane filtration technology is virtualizing traditional acid-precipitation steps in protein isolate production. European ingredient houses in the Netherlands and Denmark are deploying ceramic microfiltration at commercial scale, eliminating isoelectric point adjustment chemicals. This virtualization is collapsing the capital intensity gap between soy and emerging protein sources.
EFSA novel food rulings on precision-fermented proteins are indirectly tightening plant protein labeling requirements. The EU regulator's 2024 guidance on biomass-derived ingredients now demands explicit protein origin disclosure on packaging. German and French retail chains are responding with dedicated shelf-space segregation between extraction-based and fermentation-derived proteins.
Direct contracting between food brands and regional crusher-processor networks is displacing traditional ingredient distributor intermediation. Large CPG manufacturers in the US Midwest and São Paulo state are establishing multi-year offtake agreements with specific elevator-processor facilities. This pattern is most visible in identity-preserved non-GMO soybean and yellow pea supply chains where traceability commands 8-15% price premiums.
Global Plant Protein Market Segmentation
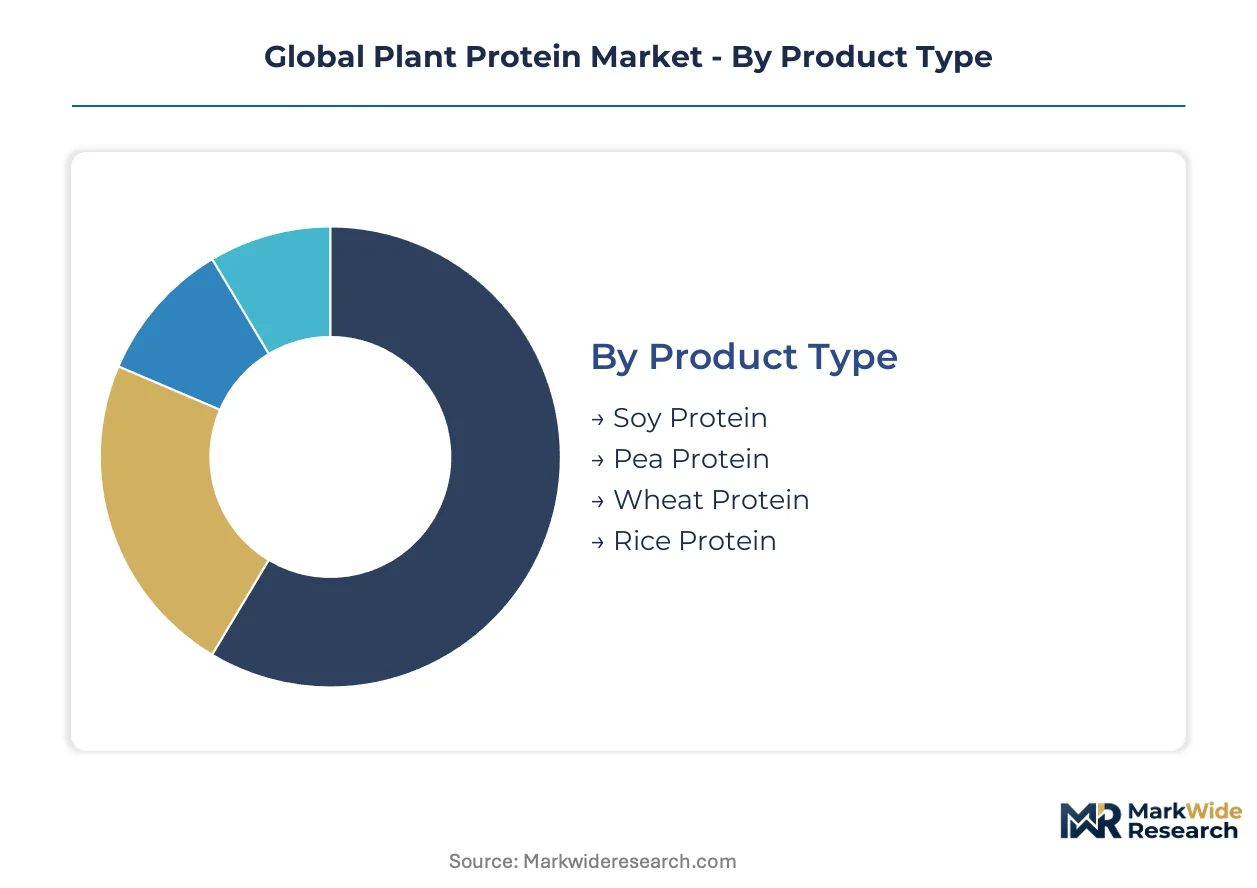
Plant protein market segmentation reveals divergent technical specifications and procurement patterns across protein sources and customer types. Manufacturers configure extraction capacity and sales channels differently depending on whether they serve commodity food processors or premium supplement brands.
Product Type:
After-sales service intensity varies sharply across protein categories, with isolate customers demanding technical formulation support while concentrate buyers prioritize logistics reliability.
- Soy Protein:Isolates achieve 90% protein content through alkaline extraction and acid precipitation, delivering superior emulsification for meat analogs. Demand concentrates in Brazilian and German food manufacturing where EU Green Deal mandates and domestic crush infrastructure align. Soy protein holds the largest share; momentum sits with pea protein.
- Pea Protein:Fractionated from yellow peas through wet milling and membrane filtration, yielding isolates with balanced amino acid profiles and low allergenicity. European and North American retail channels specify pea protein for clean-label positioning, though Manitoba and northern France capacity concentration creates supply vulnerability.
- Wheat Protein:Vital wheat gluten provides viscoelastic functionality irreplaceable in bakery applications and certain textured meat analogs.
- Rice Protein:Hypoallergenic concentrates from brown rice serve niche supplement formulations targeting sensitive consumer segments.
Cost tier separation between commodity isolates and premium specialty proteins determines margin architecture across the category.
Application:
Application segmentation tracks protein content thresholds and functional property requirements that dictate extraction technology selection.
- Food & Beverage:Extruded texturized proteins for meat analogs require 50-70% protein concentrates with specific water absorption indices. German and Dutch manufacturers reformulate under binding EU Green Deal diversification targets. Food & Beverage holds the largest share; momentum sits with Nutritional Supplements.
- Nutritional Supplements:Isolates and hydrolysates with 85-90% protein content serve powder and ready-to-drink formats. US and UK premium brands specify single-source plant bases with carbon footprint disclosure.
- Animal Feed:Lower-specification concentrates fortify companion animal nutrition at 25%+ protein inclusion rates.
- Pharmaceuticals:Hydrolyzed isolates meet excipient and specialized nutritional therapy standards.
Volume concentration in food manufacturing contrasts with value concentration in pharmaceutical and supplement applications.
End User:
End user segmentation reflects divergent procurement sophistication, from spot-market commodity buying to multi-year identity-preserved contracting.
- Retail Consumers:Direct purchasers of protein powders and fortified foods respond to shelf-positioning and certification labeling. Scandinavian and UK retailers segregate extraction-based from fermentation-derived proteins following EFSA guidance. Retail Consumers represent the broadest base; momentum sits with Food Manufacturers.
- Food Manufacturers:Large CPG brands in São Paulo state and the US Midwest establish direct elevator-processor offtake agreements for traceability premiums.
- Dietary Supplement Companies:Brands specify organic-certified isolates despite three-year transition delays for contracted pulse acres.
- Animal Feed Producers:Pet food manufacturers drive specification of high-digestibility concentrates.
Customer type determines whether relationships run through distributors or direct processor networks.
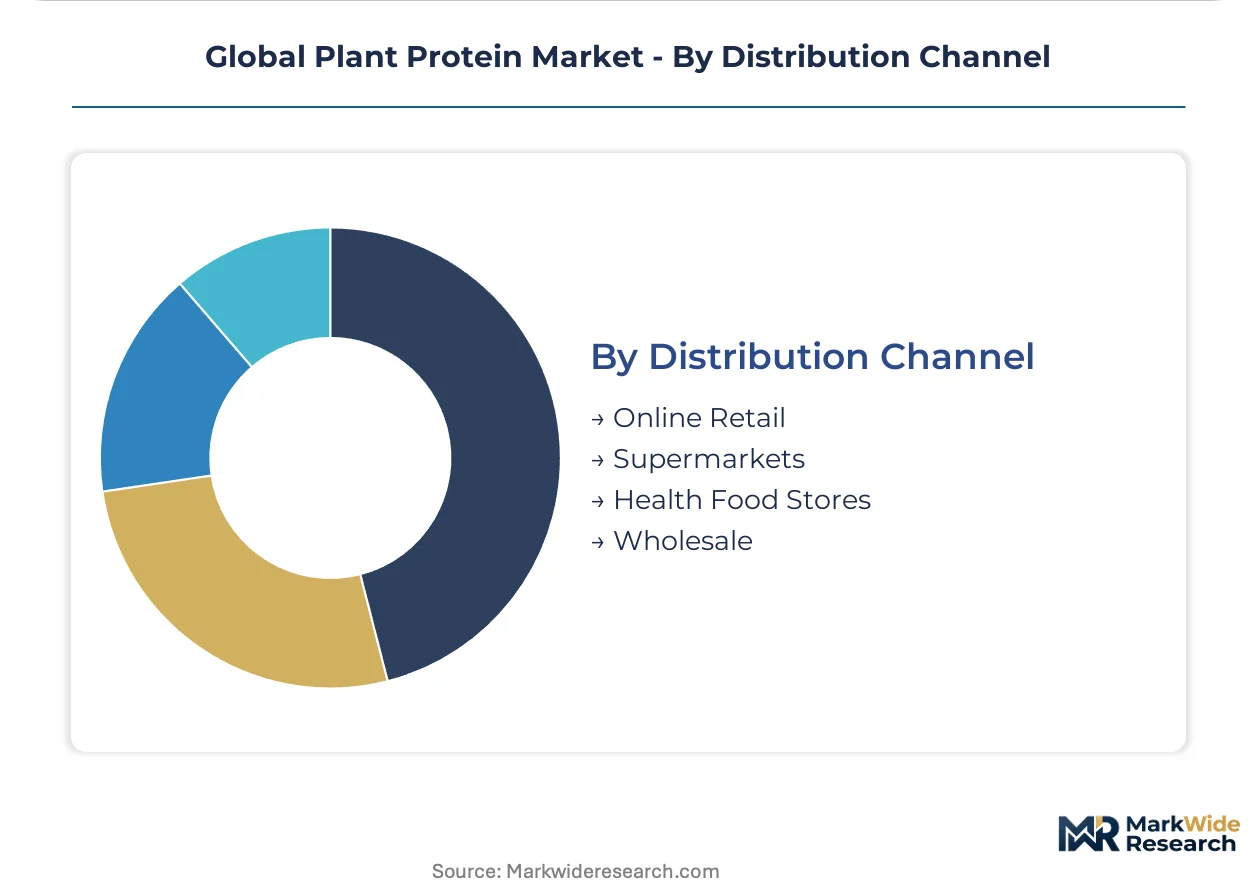
Distribution Channel:
Channel segmentation tracks the displacement of traditional ingredient distributors by direct brand-processor contracting in traceability-sensitive supply chains.
- Online Retail:E-commerce platforms capture premium supplement sales with subscription models and direct-to-consumer fulfillment. UK and German consumers access specialized isolate grades unavailable through conventional retail. Online Retail gains share fastest; Supermarkets retain volume dominance.
- Supermarkets:Mass retail channels distribute commodity concentrates and consumer-packaged protein products.
- Health Food Stores:Specialty retailers curate organic and non-GMO certified isolates for discerning consumers.
- Wholesale:Bulk ingredient distributors serve mid-scale formulators without direct processor relationships.
Channel strategy bifurcates between premium direct-to-consumer routes and commodity bulk distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across major plant protein economies. Brazil and the United States run isolate surpluses feeding European and Asian formulation demand. Germany and the Netherlands import raw pulse streams while exporting finished ingredient systems. India remains a net importer of high-specification isolates despite abundant domestic pulse production.
United States
Midwestern soybean crush infrastructure around Decatur, Illinois and Cedar Rapids, Iowa supplies global isolate demand. FDA GRAS notifications govern novel protein ingredient approvals, creating compliance timelines that favor established oilseed processors. Direct contracting between CPG brands and elevator-processor networks in Iowa and Minnesota is displacing traditional distributor channels for identity-preserved non-GMO streams.
Germany
Food manufacturers in Hamburg and Cologne are reformulating under binding EU Green Deal protein diversification mandates. EFSA novel food regulations shape competitive positioning between extraction-based and fermentation-derived proteins. The northern port cluster around Hamburg anchors import flows of Canadian and Baltic pea protein concentrates for Central European redistribution.
Brazil
Domestic crush capacity expansion in Mato Grosso and Paraná shortens supply chains for South American meat analog manufacturers. ANVISA governs ingredient safety standards for protein fortification in processed foods. São Paulo state CPG brands are establishing multi-year offtake agreements with specific elevator-processor facilities in the Center-West region.
India
Underutilized chickpea and mung bean processing infrastructure in Gujarat and Madhya Pradesh offers low-capex entry for isolate production. FSSAI regulations on protein content labeling and fortification standards are tightening compliance requirements for domestic and imported ingredients. The Indore-Dewas corridor in Madhya Pradesh is emerging as a pulse fractionation cluster serving domestic nutritional supplement brands.
Netherlands
Ingredient houses in Rotterdam and Groningen deploy ceramic microfiltration at commercial scale, eliminating isoelectric point adjustment chemicals in isolate production. REACH compliance for processing aids affects manufacturing economics for organic solvent-based extraction. The Dutch port and processing cluster serves as the primary European entry point for South American and North American protein streams.
Global Plant Protein Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in fractionation and isolate production. The vendor base spans multinational agribusiness conglomerates with crushing networks, regional pulse processors with dedicated crop contracting, and specialized ingredient houses with membrane filtration capabilities. Three archetypes dominate: oilseed-anchored multinationals leveraging existing crush infrastructure, pulse-focused fractionators with geographic crop sourcing advantages, and technology-led specialists deploying novel extraction methods. Competitive moves concentrate on direct brand-processor contracting for traceability premiums and membrane filtration capacity expansion to collapse capital intensity gaps between protein sources.
Among North American agribusiness conglomerates, Cargill, Incorporated and Archer Daniels Midland Company exemplify the oilseed-anchored archetype with extensive crush network leverage. Kerry Group PLC represents the formulation-integrated tier, bridging ingredient supply with finished product application support for European and North American food manufacturers. Roquette Frères occupies a specialist position in pea protein fractionation with dedicated crop contracting relationships sustaining customer stickiness across Atlantic supply chains.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Kerry Group PLC |
| Ingredion Incorporated |
| Roquette Frères |
| Wilmar International Ltd. |
| Glanbia PLC |
| AGT Food and Ingredients |
| International Flavors & Fragrances Inc. |
| Others |
Value Chain & Pricing Dynamics
The Paranaguá-Santos corridor freight differential compresses margins for European pea protein buyers while amplifying price spreads between identity-preserved non-GMO soybeans and commodity crush streams. This logistics chokepoint concentrates procurement leverage with Brazilian processors serving South American meat analog manufacturers, forcing Northern European formulators to absorb delivery premiums or switch to Baltic-origin pulse concentrates.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate high-volume food manufacturing procurement. Three-tier pricing structure across premium, standard, and economy levels reflects organic certification status and carbon footprint disclosure compliance under ISO 14067. Cost compression in standard-grade isolates is intensifying because membrane filtration capacity expansion in the Netherlands and Denmark collapses capital barriers for emerging protein sources. Small-scale dietary supplement brands exhibit highest price sensitivity, while multinational CPG manufacturers prioritize traceability premiums over unit economics.
Supply Chain Analysis
Yellow pea and soybean feedstock availability centers on Manitoba in Canada, Mato Grosso in Brazil, and northern France. Protein isolate production draws from hexane solvent supplies, ceramic membrane filtration systems, and food-grade acid precipitation chemicals. Single-source vulnerability concentrates in Manitoba and northern France pea fractionation facilities, where European formulators lack qualified alternative suppliers. Distribution runs through direct elevator-processor contracting networks displacing traditional ingredient distributors in identity-preserved supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plant protein market exhibits cyclical recovery characteristics tied to EU Green Deal protein diversification mandate implementation timelines. Binding reformulation thresholds in Germany, France, and the Netherlands create predictable demand pulses as CPG brands hit compliance deadlines.
For Market Incumbents: Pre-empt precision-fermented protein substitution threats by accelerating membrane filtration capacity deployment in Rotterdam and Groningen clusters. Deepen backward integration into dedicated yellow pea contracting across Baltic states to dilute Manitoba supply concentration risk. Secure ANVISA pre-approval for novel isolate grades in Brazil before local crush capacity fully ramps.
For New Entrants and Emerging Players: Pursue underutilized chickpea and mung bean processing infrastructure in Gujarat and Madhya Pradesh for low-capex isolate production entry. Target pet food protein fortification specifications in the US and UK where 25%+ single-source plant protein inclusion rates command premium positioning. Lead with carbon footprint disclosure compliance as the primary go-to-market wedge against established commodity suppliers.
For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates seeking to divest non-core specialty ingredient divisions with pea protein fractionation capabilities. Long-term viability hinges on membrane filtration technology ownership and direct brand-processor contracting relationships rather than distributor-dependent revenue. Watch EFSA novel food rulings on biomass-derived proteins as the signal for accelerated shelf-space segregation between extraction-based and fermentation-derived categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Ceramic microfiltration deployment in Rotterdam eliminates isoelectric point chemicals and collapses soy-pea capital intensity gaps. |
| Direct Elevator-Processor Contracting | Multi-year offtake agreements with Mato Grosso crush facilities secure identity-preserved non-GMO supply for São Paulo CPG brands. |
| Carbon Footprint Certification Program | ISO 14067-compliant disclosure secures preferred supplier status with UK and Scandinavian retailers segregating protein origins. |
| Backward Integration into Pulse Contracting | Dedicated yellow pea acre agreements in Baltic states dilute Manitoba supply concentration vulnerability for European fractionators. |
| Pet Food Protein Fortification Partnership | Premium companion animal nutrition specifications in the US and UK drive 25%+ single-source plant protein inclusion commitments. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA GRAS notifications, EFSA novel food rulings, EU Green Deal implementation documents, and trade flow data from Brazilian and Canadian customs authorities. Conversations with plant protein extraction engineers, food manufacturer procurement directors, specialty ingredient sales heads, and regulatory affairs specialists at CPG brands informed demand-side assumptions. Bottom-up capacity modeling across Manitoba, northern France, and Dutch processing clusters triangulates against top-down consumption estimates from food and supplement application segments.
Forecast inputs include protein content thresholds by application, extraction technology yield curves, and EU Green Deal compliance timeline assumptions across the analysis window. Segmentation dimensions span protein source type, isolate versus concentrate versus hydrolysate grade, end-use application, and customer procurement sophistication. CAGRs derive from installed capacity expansion schedules, reformulation mandate deadlines, and substitution elasticity between plant and fermentation-derived proteins.
Sensitivities concentrate around EFSA regulatory shifts, soybean price volatility transmission from Argentina and Illinois production belts, and membrane filtration technology diffusion rates. Cross-checking against FSSAI fortification standard revisions and ANVISA ingredient approval timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Plant Based Pork Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Meat Substitutes Market
Plant Based Food
Indonesia Plant-Based Food and Beverages Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Plant-Based Fish Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Veggie Burger Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Meatless Meat Market