
 Europe Meat Substitutes Market | 2026-2036
Europe Meat Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Meat Substitutes Market Foresight
The EU Green Deal is repositioning protein sourcing requirements across European food manufacturing. Quorn leverages mycoprotein fermentation scale to anchor supply contracts with British retailers. Schouten Europe B.V. competes through textured-vegetable-protein specialization for Dutch and German foodservice channels. Vivera Foodgroup dominates chilled plant-based meat allocation in Benelux supermarket chains.
Europe meat substitutes comprise formulated protein products designed to replicate the sensory and nutritional properties of conventional meat, typically containing protein isolates, binders, and flavor systems processed through extrusion or fermentation to achieve target moisture content and fibrous texture. These products serve commercial food manufacturers and retail channels seeking compliant alternatives to animal-derived proteins under tightening sustainability procurement rules. Mycoprotein leads in texture fidelity for whole-muscle applications while pea-derived isolates represent the fastest-growing source category as ingredient costs compress and EFSA clearance pathways mature. Foodservice distribution channels concentrate margin pools through direct-volume contracts with hospitality groups, though supermarket private-label expansion is compressing branded pricing power.
EMA feed-additive oversight, EFSA novel food authorization protocols, and EU Green Deal carbon-footprint disclosure requirements collectively shape formulation standards and market access timelines for new entrants. REACH chemical safety assessments extend to processing aids and flavor compounds used in extruded protein matrices, adding compliance layers for imported ingredient streams. Stakeholders must monitor how CSRD scope-three reporting obligations will recalibrate procurement priorities across European retail and foodservice buying consortia.
Market Dynamics
EU Green Deal protein diversification mandates are forcing food manufacturers to reformulate product portfolios, compressing ingredient qualification timelines and rewiring procurement relationships across the European meat substitutes value chain.
Growth Catalysts
- EFSA Novel Food Streamlining:Accelerated safety assessments for mycoprotein and fermented protein ingredients shorten market access from 24 months to 12-18 months for qualified dossiers.
- Carbon Footprint Labeling Mandates:CSRD scope-three disclosure requirements push retail buyers toward verified low-carbon protein alternatives in chilled and frozen categories.
- Foodservice Contract Expansion:Dutch and German hospitality groups are embedding plant-based options into procurement specifications for corporate catering and institutional feeding programs.
Market Restraints
- Pea Protein Concentration Risk:Over 70% of European pea-protein isolate supply depends on North American and Ukrainian yellow pea processors, exposing formulators to agricultural commodity volatility.
- Extrusion Equipment Bottlenecks:High-shear twin-screw extruders capable of fibrous texture replication face 14-18 month lead times from specialized German and Italian machinery suppliers.
- Flavor Masking Limitations:Bitter off-notes from legume-derived isolates require expensive yeast-extract and natural-flavor overbuilds that compress gross margins on economy-tier products.
Strategic Opportunities
- Central European Manufacturing Expansion:Poland and Czech Republic offer underutilized food-processing infrastructure with lower utility costs for extrusion and fermentation operations.
- Precision Fermentation Convergence:Combining mycoprotein biomass with animal-free heme and fat technologies enables whole-muscle cuts that replicate beef and pork sensory profiles.
- Quick-Service Restaurant Partnerships:Direct supply agreements with pan-European burger and sandwich chains bypass supermarket slotting-fee barriers and build brand recognition.
Industry Challenges
- Food Technologist Talent Scarcity:Formulation expertise spanning protein chemistry, extrusion physics, and sensory science commands premium compensation and long recruitment cycles.
- REACH Compliance Burden:Processing aids, flavor carriers, and color stabilizers require extended chemical-safety dossiers that delay new product launches by 6-9 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Meat Substitutes Market |
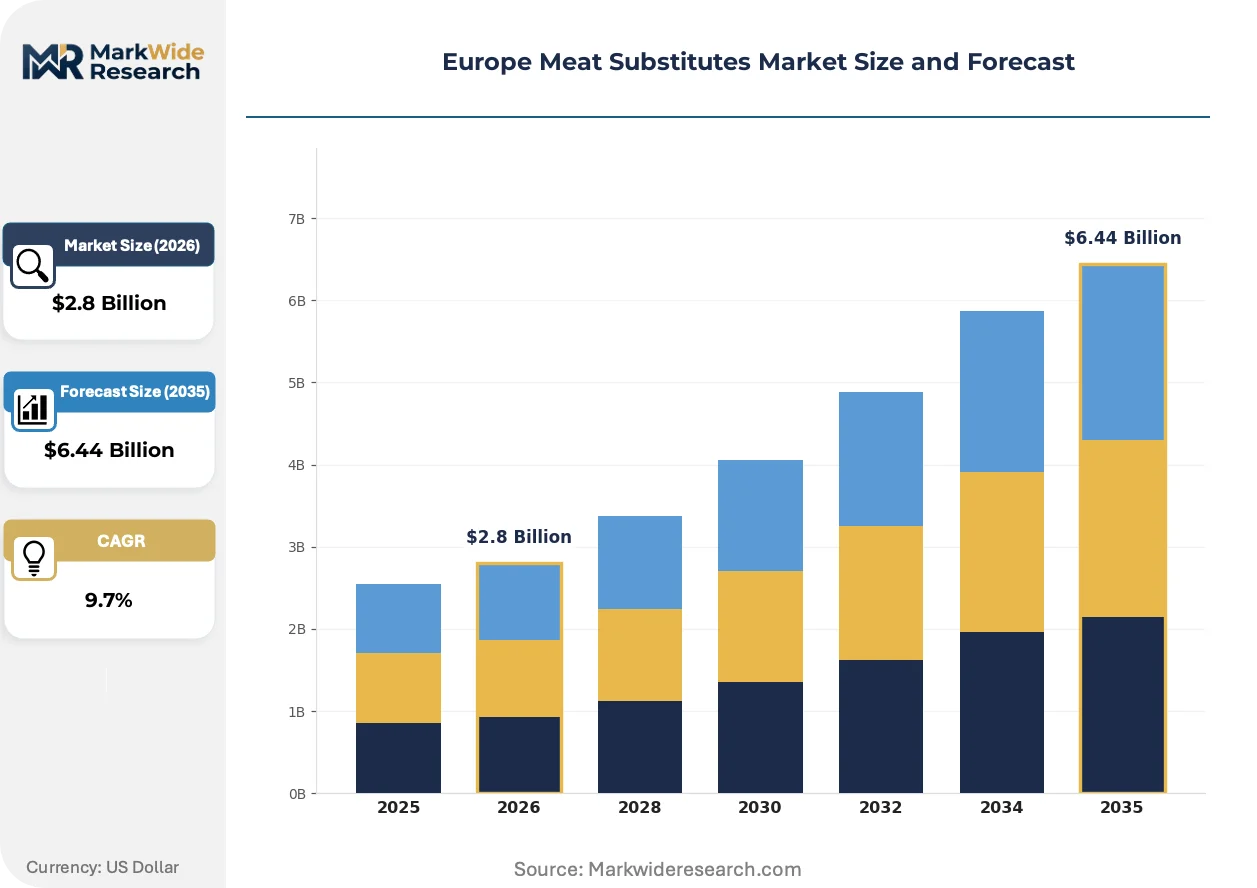
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofu, Seitan, Tempeh, Mycoprotein Source: Legumes, Grains, Nuts, Peas Texture: Chunky, Minced, Slices, Burgers Distribution Channel: Supermarkets, Online, Specialty Stores, Foodservice |
| Companies Covered | Quorn, Vbites Foods Ltd., Monde Nissin Corporation, Schouten Europe B.V., Taifun-Tofu GmbH, Vivera Foodgroup, Rügenwalder Mühle Carl Müller GmbH & Co. KG, Moving Mountains Foods, The Meatless Farm, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Meat Substitutes Market Shifts & Advancements
European meat substitute development is pivoting from ingredient substitution toward structural replication of whole-muscle anatomy, with fermentation scale and extrusion precision becoming the primary competitive battlegrounds.
High-moisture extrusion technology is modularizing production economics for plant-based whole cuts. Mid-sized manufacturers in Spain and Italy are adopting second-generation extruders with real-time rheology control to reduce texture variability batch-to-batch. Equipment modularity is enabling co-manufacturers to switch between minced, pulled, and steak-format products without full line changeovers, compressing capital requirements for SKU expansion.
EFSA's 2023 updated guidance on novel food equivalence assessments is accelerating ingredient approval pathways for precision-fermented proteins. The regulatory shift reduces toxicology study requirements for substances with established consumption history, cutting dossier preparation costs by approximately one-third. Dutch and Danish biotech developers are prioritizing mycelium and single-cell protein platforms to exploit this streamlined route.
Retail buyers in Benelux and Scandinavian markets are consolidating supplier relationships around vertically integrated partners who control fermentation, formulation, and chilled distribution. This procurement concentration displaces fragmented ingredient-trader networks and forces smaller brands to accept private-label manufacturing terms or exit mainstream supermarket channels entirely. Germany's REWE and EDEKA chains are piloting single-source contracts covering 80% of their plant-based meat SKUs.
Europe Meat Substitutes Market Segmentation
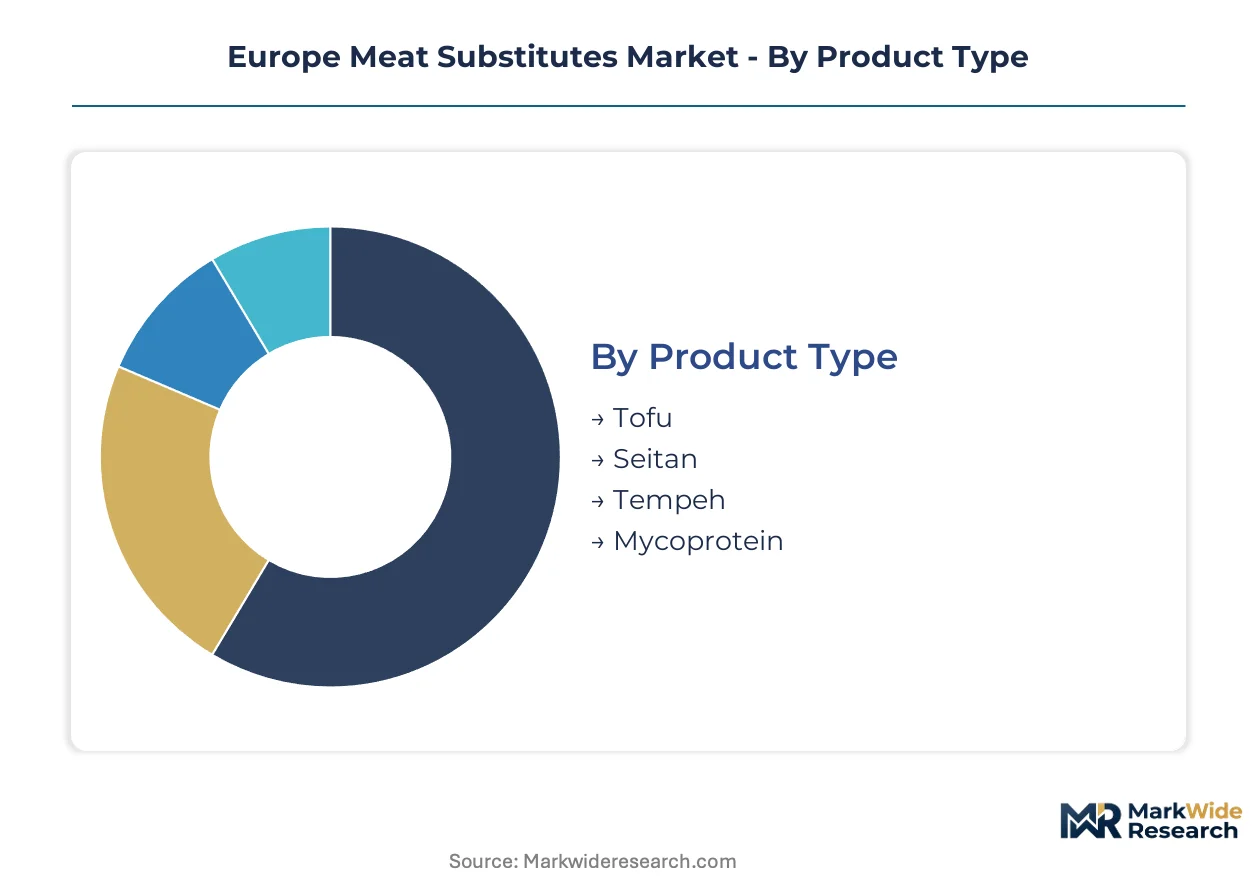
Segmentation reveals how capital intensity, formulation complexity, and channel access stratify competitive position across European meat substitute manufacturing. Each dimension exposes distinct margin structures and regulatory exposure that shape investment allocation.
Product Type:
Fermentation-based segments demand substantially higher upfront capital than extruded or coagulated alternatives, with bioreactor infrastructure and sterile processing lines representing the dominant fixed-cost burden.
- Tofu:Soybean curd produced through calcium sulfate or magnesium chloride coagulation offers the lowest capital barrier to entry. German and Dutch food manufacturers dominate European production, though price compression from Asian imports limits margin expansion in economy-tier retail placement.
- Mycoprotein:Fungal biomass cultivated in submerged fermentation achieves superior fibrous texture for whole-muscle replication. British supply contracts anchor volume, with EFSA novel food streamlining enabling faster geographic expansion into Benelux and Scandinavian retail channels.
- Seitan:Wheat gluten extraction requires moderate extrusion equipment and delivers high protein density for foodservice applications.
- Tempeh:Whole-soybean fermentation with Rhizopus oligosporus demands controlled humidity infrastructure and commands premium positioning in specialty retail.
Mycoprotein absorbs the bulk of installed fermentation capacity; tofu manufacturing is expanding most quickly through co-manufacturer networks in Poland and Czech Republic.
Source:
Ingredient sourcing concentration determines supply security and carbon-footprint verification complexity under CSRD scope-three disclosure mandates.
- Peas:Yellow and green pea protein isolates deliver complete amino acid profiles with lower allergenicity than soy. North American and Ukrainian processor concentration exposes formulators to agricultural commodity volatility, driving backward integration efforts among Dutch ingredient developers.
- Legumes:Fava bean and lupin proteins offer regional European cultivation advantages with established supply contracts in France and Germany. EFSA clearance for novel legume isolates accelerates formulation flexibility for mid-tier manufacturers seeking supply diversification.
- Grains:Wheat and oat proteins provide cost-effective binding functionality but limited standalone nutritional completeness.
- Nuts:Almond and cashew bases serve premium chilled formats with high fat content for sensory richness.
Pea-derived isolates command the steepest expansion trajectory as ingredient costs compress and EFSA pathways mature; legume sourcing anchors regional supply security.
Texture:
Texture replication fidelity determines equipment sophistication requirements and end-use market access, with high-moisture extrusion representing the critical manufacturing bottleneck.
- Burgers:Patty formats utilizing high-moisture extrusion or shear-cell technology achieve price parity with conventional ground meat in German and Dutch retail. Pan-European quick-service restaurant chains consolidate procurement around certified low-carbon suppliers with verified texture consistency.
- Minced:Crumbled formats for sauce integration and ready-meal applications require lower extrusion precision, enabling mid-sized Spanish and Italian manufacturers to compete on volume.
- Slices:Deli-meat replication demands precise moisture control and binding systems for stacked presentation.
- Chunky:Diced formats for stew and stir-fry applications prioritize freeze-thaw stability over fibrous structure.
Burger formats absorb the bulk of high-shear extrusion capacity; minced products are gaining share fastest through foodservice contract expansion.
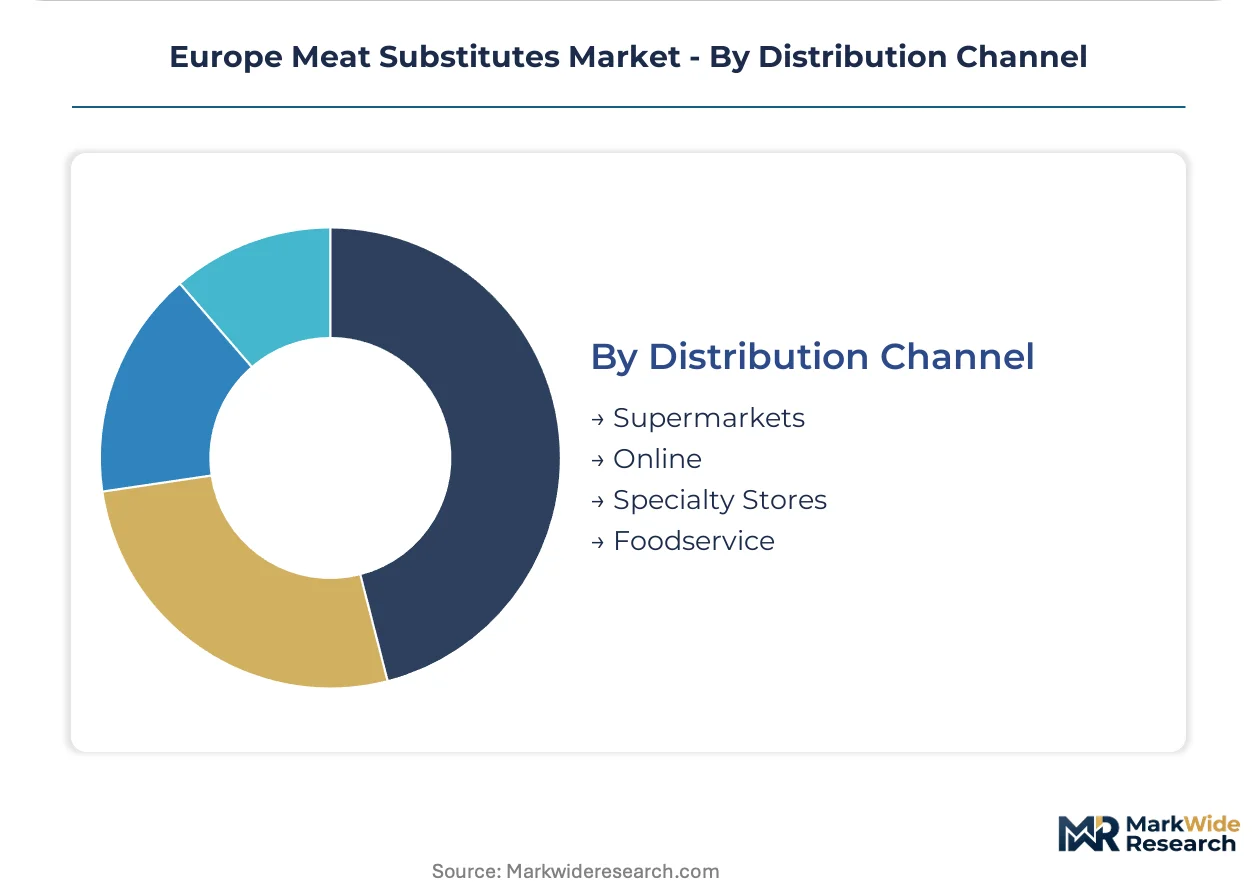
Distribution Channel:
Channel selection dictates margin capture, brand control, and regulatory documentation burden, with direct foodservice contracts offering superior terms versus retail slotting-fee structures.
- Foodservice:Direct supply agreements with hospitality groups, institutional caterers, and quick-service chains bypass supermarket fee structures. Dutch and German procurement specifications now embed plant-based minimums for corporate feeding programs, locking in multi-year volume commitments.
- Supermarkets:Chilled and frozen retail placement demands substantial slotting investments and private-label manufacturing flexibility. REWE and EDEKA pilot single-source contracts covering the majority of plant-based meat SKUs, displacing fragmented supplier networks.
- Online:Direct-to-consumer and aggregator platforms serve trial-size formats and subscription models with lower capital requirements.
- Specialty Stores:Independent organic and vegan retailers sustain premium pricing for artisan-positioned brands with limited scale.
Foodservice channels absorb the bulk of branded volume at superior margins; supermarket private-label expansion is climbing fastest as retail buyers consolidate supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in the Netherlands and Germany while consumption spreads across Western European retail and foodservice channels. This geographic split shapes logistics networks and cold-chain investment priorities.
Germany
Foodservice procurement specifications now mandate plant-based minimums for institutional catering contracts. The EU Green Deal carbon-footprint disclosure requirements drive REWE and EDEKA toward consolidated supplier relationships. Berlin-Brandenburg hosts fermentation scale-up facilities serving pan-European distribution.
Netherlands
Dutch hospitality groups embed meat-free options into corporate feeding program tenders. EFSA novel food streamlining accelerates mycoprotein and precision-fermented protein approvals. The Randstad corridor concentrates extrusion equipment manufacturing and biotech pilot facilities.
United Kingdom
British retailers anchor mycoprotein supply contracts under tightened sustainability procurement rules. REACH chemical safety assessments extend to processing aids used in extruded protein matrices. The East Midlands hosts high-shear extruder manufacturing clusters serving continental European buyers.
France
French food manufacturers reformulate portfolios to meet EU Green Deal protein diversification targets. EMA feed-additive oversight shapes ingredient qualification timelines for novel proteins. Île-de-France houses R&D partnerships between ingredient developers and quick-service restaurant chains.
Spain
Spanish co-manufacturers adopt second-generation extruders with real-time rheology control for texture consistency. CSRD scope-three reporting obligations recalibrate procurement priorities for retail buyers. Catalonia hosts mid-sized producers competing on minced-format volume for foodservice contracts.
Europe Meat Substitutes Market Competitive Landscape
The competitive structure tilts toward fermentation specialists with captive bioreactor infrastructure and high-moisture extrusion operators with equipment lock-in. Tiered positioning separates premium mycoprotein platforms from economy-tier textured-vegetable-protein suppliers. Strategic archetypes include vertical integrators controlling fermentation-to-retail pipelines and co-manufacturers offering SKU flexibility without capital intensity. Dominant competitive moves center on backward integration into ingredient supply and direct foodservice contract capture bypassing retail slotting fees.
Among British-based mycoprotein developers, Quorn occupies a position exemplifying fermentation scale advantages. Dutch specialists Schouten Europe B.V. and Vivera Foodgroup sit within the textured-protein and chilled-distribution archetypes respectively, representing divergent paths to foodservice and retail channel access.
| Leading Market Players |
|---|
| Quorn |
| Vbites Foods Ltd. |
| Monde Nissin Corporation |
| Schouten Europe B.V. |
| Taifun-Tofu GmbH |
| Vivera Foodgroup |
| Rügenwalder Mühle Carl Müller GmbH & Co. KG |
| Moving Mountains Foods |
| The Meatless Farm |
| Others |
Supply & Pricing Matrix
Captive fermentation infrastructure anchors supply positioning and pricing power for mycoprotein specialists serving British and Dutch retail channels, while extrusion-dependent operators face margin compression from equipment bottlenecks and raw material volatility.
Pricing Analysis
Margin tightening in economy-tier extruded products traces to pea-protein isolate cost volatility and supermarket private-label expansion. Three-tier pricing structure across premium mycoprotein, standard textured-vegetable-protein, and economy frozen formats separates texture fidelity from commodity positioning. Cost-down pressure on branded chilled lines accelerates because REWE and EDEKA single-source contracts consolidate buyer leverage. Foodservice procurement teams show lowest price sensitivity, prioritizing carbon-footprint verification and multi-year volume guarantees over per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with North American and Ukrainian yellow pea processors supplying over 70% of European isolate demand. Mycoprotein fermentation draws from British bioreactor clusters, while high-shear extrusion equipment rests on German and Italian machinery suppliers. Tariff exposure on imported legume concentrates compounds agricultural commodity risk. Distribution runs through chilled logistics networks serving Benelux and German retail, with foodservice bypassing supermarket slotting-fee structures entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where fermentation scale and extrusion equipment lock-in determine who captures margin pools across the value chain.
For Market Incumbents: Anticipate supermarket consolidation by securing captive pea-protein processing through Dutch backward integration partnerships. Defend against precision-fermentation entrants by expanding mycoprotein bioreactor capacity in the East Midlands corridor. EFSA novel food streamlining accelerates competitive entry timelines, demanding faster dossier preparation cycles.
For New Entrants and Emerging Players: EU Green Deal carbon-footprint mandates in Germany open a window for certified low-carbon suppliers to bypass incumbent slotting-fee advantages. Target Polish and Czech co-manufacturing partnerships to exploit underutilized extrusion infrastructure. Lead with direct foodservice contracts embedding plant-based procurement minimums for Dutch institutional catering.
For Investors and Strategic Acquirers: Exit pathways concentrate in fermentation-to-retail vertical integrators with EFSA-cleared ingredient platforms. Long-term viability hinges on controlling upstream biomass production rather than formulation alone. Watch for CSRD scope-three disclosure acceleration as the signal that carbon-verified supply chains command acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Protein Processing | Dutch ingredient developers secure supply security against North American agricultural volatility. |
| High-Moisture Extrusion Capacity Expansion | Spanish and Italian co-manufacturers capture foodservice contract volume with modular equipment. |
| EFSA Novel Food Dossier Acceleration | Danish and Dutch biotech platforms exploit streamlined toxicology study requirements. |
| Direct Foodservice Supply Agreements | Quick-service restaurant chains in Germany bypass supermarket slotting-fee barriers. |
| Precision Fermentation Convergence | Mycoprotein biomass combined with animal-free heme replicates whole-muscle sensory profiles. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with food technologists, extrusion equipment engineers, retail category buyers, and EFSA regulatory consultants combined with EMA submissions, REACH dossiers, and EU Green Deal implementation reports. Bottom-up SKU-level modeling triangulated against top-down protein diversification targets across the analysis window.
Granularity-level modeling tracked fermentation-based, extruded, and coagulated product types at the country level, with source categories, texture formats, and distribution channels mapped across the projection horizon. CAGRs derived from volume trajectory analysis incorporating EFSA approval timelines, equipment lead times, and procurement contract durations. Carbon-footprint verification requirements and CSRD disclosure phases served as structural demand inputs.
The model assumes a particular technology adoption path; alternative pathways for precision-fermented proteins would alter the outlook. Forecasts reflect assumptions about EFSA streamlining continuity, agricultural commodity stability, and extrusion equipment availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Pea Protein Market
Plant Based Food
Oat-Based Cereals Market
Plant Based Food
Plant-Based Nuggets Market
Plant Based Food
Packed Vegan Foods Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Targeting Pod Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
Plant-Based Seafood Market
Plant Based Food
Plant-Based Bacon Market
Plant Based Food
Vegan Tortillas Market
Plant Based Food
Plant-Based Fish Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
Plant-Based Sausages Market