
 Europe Collagen Peptides Market | 2026-2036
Europe Collagen Peptides Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Collagen Peptides Market Insights
Germany is rewriting capacity dynamics for collagen peptide supply across the continent. GELITA AG leverages its Eberbach facility to sustain integrated production from hide processing through enzymatic hydrolysis. Rousselot anchors French supply through its Angoulême operations, while Weishardt Group competes via specialized marine collagen extraction from North Atlantic fisheries.
Collagen peptides constitute short-chain amino acid sequences derived from partial enzymatic hydrolysis of native collagen, typically yielding molecular weights below 10 kDa for enhanced bioavailability and cold-water solubility. These peptides function primarily as functional protein ingredients in nutraceutical and cosmetic matrices. Hydrolyzed collagen dominates value contribution due to established clinical validation for dermal and osteoarticular applications. Marine source material commands premium positioning within cosmetics, whereas bovine-derived grades anchor volume in sports nutrition and functional foods.
EFSA maintains strict novel food authorization pathways for non-traditional collagen sources, while REACH governs chemical safety in processing aids and the EU Green Deal drives carbon accounting through raw material chains. EMA pharmacovigilance frameworks increasingly scrutinize collagen-based medical devices and wound care formulations. Stakeholders must monitor evolving ECHA restrictions on tanning industry byproducts that constrain hide availability for gelatin precursor supply.
Market Dynamics
EFSA novel food authorization pathways and EU Green Deal carbon accounting mandates are forcing nutraceutical manufacturers to restructure raw material provenance systems, compressing supplier qualification timelines while elevating traceability infrastructure investments across German and French production networks.
Growth Catalysts
- Clean-label protein enrichment:Functional food reformulators in Germany are integrating hydrolyzed collagen into beverage and snack matrices to meet consumer demand for recognizable ingredient decks. This trend accelerates procurement from enzymatic hydrolysis specialists with verified hide-to-peptide chain documentation.
- Joint health formulation expansion:EFSA-approved health claims for osteoarticular applications enable nutraceutical brands to position collagen peptides as clinically validated active ingredients. French and German manufacturers leverage this regulatory clarity to differentiate against unvalidated protein alternatives.
- Sustainable sourcing mandates:The EU Green Deal's carbon border adjustment mechanisms incentivize tannery byproduct utilization for gelatin precursor supply. This policy framework redirects investment toward circular economy models in hide-processing regions.
Market Restraints
- Hide availability constraints:ECHA restrictions on chromium tanning processes reduce qualified raw material streams for bovine collagen production. This technical limitation tightens precursor supply for volume-grade peptide manufacturing.
- Marine source cost volatility:North Atlantic fishery quota fluctuations and fuel price instability elevate extraction costs for premium cosmetic-grade marine collagen. This input cost pressure compresses margin structures for specialized peptide variants.
- Novel food authorization timelines:EFSA's 12-18 month assessment windows for non-traditional collagen sources create regulatory friction for innovators seeking to commercialize alternative raw materials. This procedural barrier delays market entry for emerging supply chains.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland and Romania exhibit nascent functional food infrastructure with limited local collagen peptide production. Early entrants can establish supplier relationships ahead of retail channel maturation.
- Medical device convergence:EMA pharmacovigilance frameworks for wound care formulations create regulatory tailwinds for collagen-based biomaterials. This emerging application segment offers premium pricing potential beyond nutraceutical commoditization.
- Direct-to-practitioner channels:Sports medicine clinics and physiotherapy networks represent untapped distribution pathways for clinical-grade joint health formulations. This channel innovation bypasses retail margin erosion.
Industry Challenges
- Enzymatic hydrolysis expertise scarcity:Qualified process engineers with experience in molecular weight control below 10 kDa command premium compensation. This talent gap constrains capacity expansion timelines for mid-scale manufacturers.
- Multi-jurisdiction certification complexity:Simultaneous compliance with EFSA novel food, REACH chemical safety, and CSRD sustainability reporting creates administrative burden. This operational overhead diverts resources from R&D investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Collagen Peptides Market |
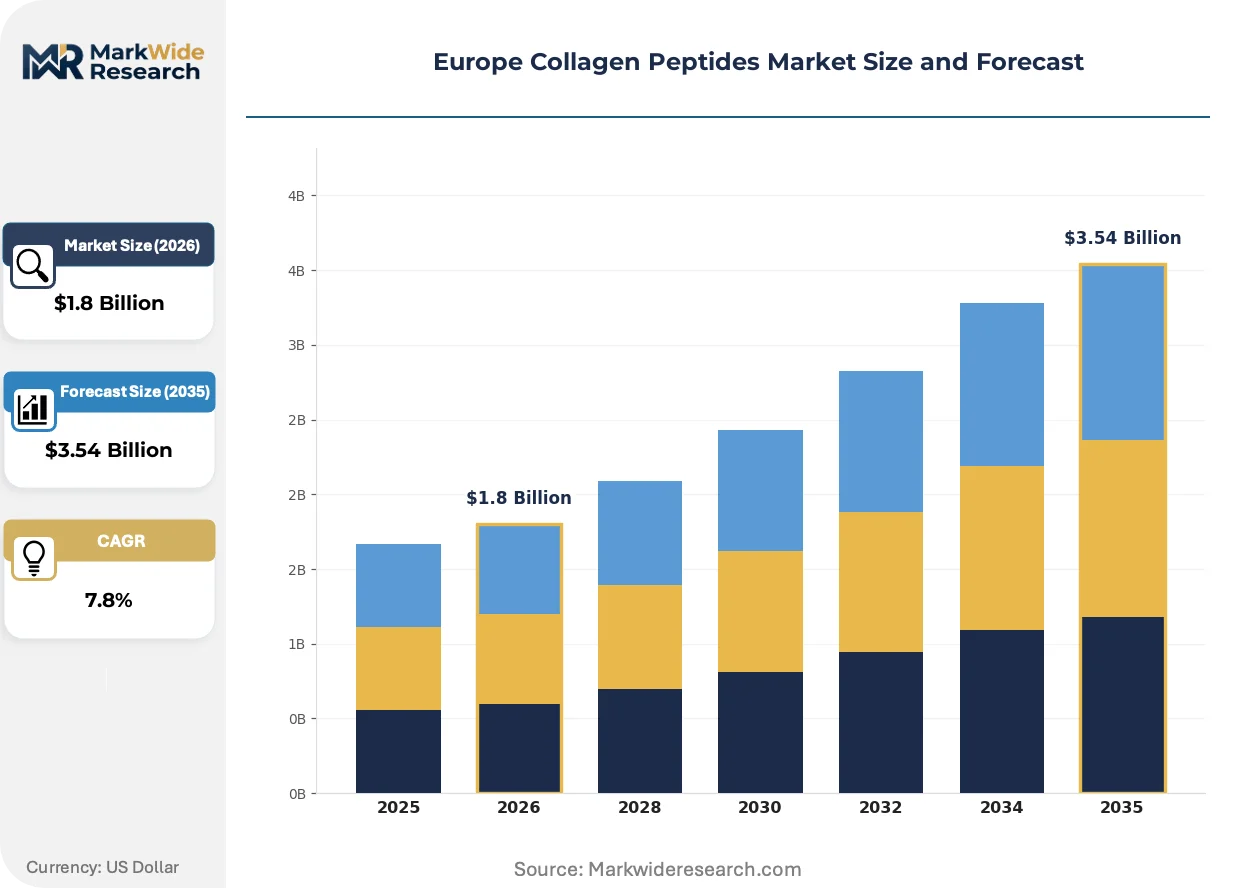
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptide Powders, Collagen Supplements Application: Nutraceuticals, Functional Foods, Cosmetics, Pharmaceuticals Source: Bovine, Porcine, Marine, Poultry Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Stores |
| Companies Covered | GELITA AG, Rousselot, Weishardt Group, Tessenderlo Group, Cargill, Lapi Gelatine, Ewald-Gelatine GmbH, Italgelatine SpA, Protein S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Collagen Peptides Market Trends and Innovations
Precision enzymatic engineering and blockchain-enabled provenance tracking are restructuring competitive differentiation mechanisms, compressing the premium commanded by legacy supply chains while elevating technical barriers for new entrants.
Continuous flow enzymatic hydrolysis systems enable real-time molecular weight modulation through immobilized enzyme bed configurations. German nutraceutical manufacturers adopt these platforms to reduce batch-to-batch variability and accelerate production cycles. This process intensification is rendering obsolete traditional stirred-tank operations with extended residence times and inconsistent peptide size distributions.
REACH registration requirements for processing aid chemicals now mandate comprehensive toxicological dossiers for enzymatic catalysts used in peptide extraction. Industrial consequence includes supplier consolidation as smaller catalyst producers exit due to compliance cost burdens. Cosmetic-grade peptide segments face the steepest reformulation pressures, driving substitution toward bio-based processing alternatives.
Sports nutrition buyers now demand certificate-of-origin documentation linking finished peptides to specific tannery operations and fishery harvest zones. This specification intensity disrupts traditional spot-market purchasing, replacing it with multi-year offtake agreements with embedded sustainability clauses. German functional food brands exhibit the most pronounced preference for chain-of-custody transparency.
Europe Collagen Peptides Market Segmentation
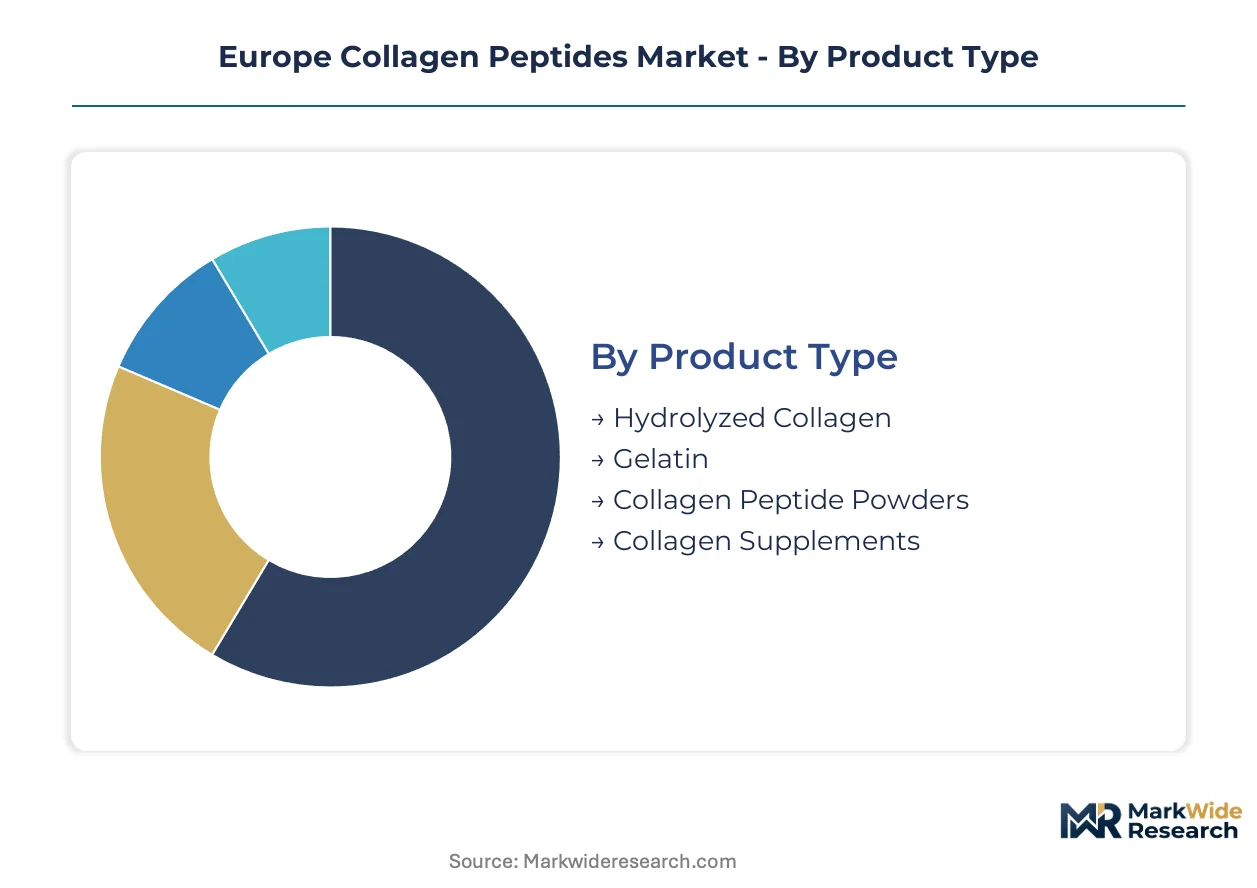
Collagen peptide procurement patterns diverge sharply across end-use specifications, with nutraceutical formulators prioritizing bioavailability metrics while cosmetic buyers emphasize molecular weight consistency. Source material traceability and distribution channel transparency increasingly determine supplier selection criteria across German and French manufacturing networks.
Product Type:
Functional protein matrices span from partially hydrolyzed gelatin through to highly fractionated peptide isolates, each commanding distinct specification requirements and price positioning.
- Hydrolyzed Collagen:Enzymatically processed to achieve molecular weights below 10 kDa for enhanced intestinal absorption. German functional food manufacturers dominate procurement volume, driven by clean-label protein enrichment mandates in beverage reformulation.
- Gelatin:Partial hydrolysis product retaining gelling functionality with higher bloom strength specifications. French confectionery and pharmaceutical capsule producers anchor demand, though ECHA tanning restrictions constrain hide-derived precursor availability.
- Collagen Peptide Powders:Spray-dried isolates optimized for solubility and neutral organoleptic profile.
- Collagen Supplements:Finished dosage forms including tablets and ready-to-drink formulations.
Established volume favors gelatin; emerging adoption favors hydrolyzed collagen.
Application:
End-use concentration patterns reflect divergent regulatory pathways and margin structures across European manufacturing clusters.
- Nutraceuticals:Dietary supplement formulations leveraging EFSA-approved osteoarticular health claims. German and French brands drive procurement, with direct-to-practitioner channels expanding fastest for clinical-grade joint health positioning.
- Functional Foods:Protein-fortified beverages, snack bars, and dairy alternatives requiring cold-water soluble peptides without flavor interference. Clean-label reformulation activity concentrates in German retail chains.
- Cosmetics:Dermal anti-aging formulations utilizing marine-derived peptides for premium positioning.
- Pharmaceuticals:Wound care matrices and medical device coatings subject to EMA pharmacovigilance frameworks.
Nutraceuticals capture the widest supplier base; functional foods exhibit the steepest specification escalation.
Source:
Raw material provenance determines carbon accounting outcomes and religious dietary compliance across European supply chains.
- Bovine:Hide-derived collagen dominating volume-grade peptide production. German tannery byproduct utilization aligns with EU Green Deal circular economy incentives, though chromium tanning restrictions tighten qualified supply streams.
- Marine:North Atlantic fishery extracts commanding premium positioning in cosmetic applications. Weishardt Group and comparable specialists compete on traceability documentation.
- Porcine:Skin and bone-derived peptides serving halal-excluded markets and specific pharmaceutical applications.
- Poultry:Emerging cartilage-sourced collagen for niche allergen-avoidance formulations.
Bovine anchors cost-sensitive volume; marine claims the highest per-kilogram realization.
Distribution Channel:
Channel selection increasingly reflects buyer demands for chain-of-custody documentation and sustainability certification.
- Online Retail:Direct-to-consumer platforms enabling subscription-based peptide procurement with embedded traceability apps. German functional food brands exhibit strongest preference for digital channel integration.
- Supermarkets:Mass-market retail requiring standardized SKUs and consolidated logistics.
- Health Stores:Pharmacy-adjacent channels emphasizing clinical validation and practitioner endorsement.
- Specialty Stores:Cosmetic boutiques and sports nutrition outlets serving premium positioning requirements.
Online retail expands most quickly; health stores retain the highest margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food authorization pathways shape procurement decisions across the continent, with national regulators enforcing divergent traceability standards that fragment supplier qualification timelines. German functional food manufacturers and French nutraceutical formulators anchor regional demand concentration.
Germany
Clean-label protein enrichment drives beverage reformulation by brands like dm-drogerie markt and Rossmann private labels. The EU Green Deal's carbon border adjustment mechanisms incentivize tannery byproduct utilization in Bavaria and Baden-Württemberg. The Eberbach facility cluster sustains integrated hide-to-peptide production for enzymatic hydrolysis specialists.
France
Osteoarticular health claim formulations dominate nutraceutical procurement from Paris-based contract manufacturers. ANSM pharmacovigilance frameworks for medical device applications create dual-use opportunities for collagen biomaterials. The Angoulême industrial zone anchors French supply through integrated gelatin precursor operations.
Italy
Pharmaceutical capsule and confectionery applications sustain demand for higher-bloom gelatin grades in Lombardy and Emilia-Romagna. REACH registration requirements for processing aids compress qualified catalyst supplier lists. Bologna's packaging machinery cluster enables automated peptide powder handling for export-oriented formulators.
Netherlands
Rotterdam's port logistics infrastructure facilitates marine collagen import from North Atlantic fisheries for cosmetic-grade extraction. CSRD sustainability reporting mandates drive blockchain-enabled provenance investments among Dutch traders. The Randstad distribution network accelerates just-in-time delivery to German functional food manufacturers.
Poland
Nascent functional food infrastructure in Warsaw and Kraków offers first-mover positioning ahead of retail channel maturation. EFSA novel food authorization timelines create regulatory lag for local brands seeking non-traditional collagen sources. Poznań's agri-food processing hub attracts toll manufacturing partnerships with Western European peptide suppliers.
Europe Collagen Peptides Market Competitive Landscape
Capability concentration sits with integrated hide processors commanding enzymatic hydrolysis expertise; scale advantage sits with diversified ingredient conglomerates leveraging procurement volume. The vendor base organizes around three archetypes: tannery-integrated gelatin specialists, marine extraction pure-plays, and diversified food ingredient conglomerates. Dominant competitive moves include backward integration into raw material streams and multi-year offtake agreements embedding sustainability clauses.
Among German-integrated processors, GELITA AG and Ewald-Gelatine GmbH exemplify the tannery-linked archetype with captive hide supply. Rousselot occupies a position within the French specialist tier, representing marine and bovine dual-source capabilities. These named entities anchor industry commentary without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| GELITA AG |
| Rousselot |
| Weishardt Group |
| Tessenderlo Group |
| Cargill |
| Lapi Gelatine |
| Ewald-Gelatine GmbH |
| Italgelatine SpA |
| Protein S.A. |
| Others |
Pricing and Supply Chain Analysis
EFSA novel food authorization timelines compress supplier qualification windows while elevating traceability infrastructure investments, forcing both premium-mid-economy pricing differentiation and consolidation of procurement relationships around multi-year offtake agreements with embedded sustainability clauses.
Pricing Analysis
German functional food manufacturers pay substantial premiums over Polish toll-converters for equivalent hydrolyzed collagen grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with EFSA-validated osteoarticular health claims commanding the widest spreads. Pricing pressure stems from North Atlantic fishery quota volatility elevating marine source input costs. Sports nutrition buyers exhibit the highest price sensitivity, while cosmetic formulators absorb premiums for molecular weight consistency.
Supply Chain Analysis
Extended payment terms now stretch to 90 days for mid-scale enzymatic hydrolysis specialists purchasing from German and French tannery-integrated processors. Supply concentration rests on Germany, France, and the Netherlands, with Rotterdam port logistics anchoring North Atlantic marine collagen flows. Raw material dependencies include hide-derived gelatin precursors, fishery extracts, and immobilized enzyme catalysts. Single-source vulnerability concentrates in qualified enzymatic hydrolysis engineers with molecular weight control expertise below 10 kDa. Distribution runs through direct-to-practitioner channels and online retail platforms with embedded traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Traceability-as-a-service offerings and subscription-based certificate-of-origin verification are expanding faster than commodity peptide volumes, creating recurring-revenue layers that decouple supplier economics from spot-market volatility.
For Market Incumbents: Insulate margin structures by securing captive hide supply through backward integration into Bavarian and Baden-Württemberg tannery operations. Accelerate investment in continuous flow enzymatic hydrolysis systems to displace batch-process competitors on consistency metrics. Prioritize blockchain-enabled provenance infrastructure to preempt ECHA tanning restriction impacts on raw material qualification.
For New Entrants and Emerging Players: Pursue toll-manufacturing partnerships with Warsaw and Kraków functional food brands ahead of retail channel maturation in Poland. Target direct-to-practitioner distribution for clinical-grade joint health formulations, bypassing retail margin compression. Leverage EFSA regulatory lag for non-traditional collagen sources to establish first-mover positioning in poultry-derived allergen-avoidance segments.
For Investors and Strategic Acquirers: Marine extraction pure-plays with verified North Atlantic fishery documentation represent the most defensible acquisition archetype against input cost volatility. Long-term viability hinges on carbon accounting compliance infrastructure rather than commodity scale. Watch for EMA pharmacovigilance framework expansion into wound care biomaterials as the inflection signal for medical device convergence premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hide Processing | Captive supply from Bavarian tanneries secures precursor availability against ECHA chromium restrictions. |
| Continuous Flow Enzymatic Hydrolysis Deployment | Real-time molecular weight modulation displaces batch variability in German nutraceutical manufacturing. |
| Blockchain-Enabled Provenance Investment | Chain-of-custody transparency satisfies EU Green Deal carbon accounting mandates for Dutch traders. |
| Direct-to-Practitioner Channel Development | Sports medicine clinic networks bypass retail margin erosion for clinical-grade joint health formulations. |
| Medical Device Regulatory Pathway Navigation | EMA pharmacovigilance compliance unlocks premium pricing beyond nutraceutical commoditization. |
Research Methodology
A spread of perspectives from enzymatic hydrolysis process engineers, nutraceutical procurement leads at German functional food manufacturers, tannery operations managers, EFSA regulatory affairs specialists, and cosmetic formulators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against REACH registration databases, EFSA novel food authorization filings, EU trade customs records, and CSRD sustainability disclosure frameworks. Bottom-up peptide volume estimates triangulated against top-down functional food and nutraceutical market sizing.
Demand-supply balance modeling tracked procurement intensity from German beverage reformulators and French osteoarticular supplement brands against hide availability constraints and North Atlantic fishery quota allocations. Segmentation dimensions spanned product type, application, source material, and distribution channel, with regional production hub clustering added for supply-side calibration. CAGRs derived from curve-fitting historical authorization timelines and procurement cycle data across the projection horizon. Industry-specific inputs included EFSA assessment duration distributions and enzymatic catalyst REACH registration status.
Macroeconomic conditions sit as an overlay; deviation in energy costs affecting North Atlantic fishing operations or hide processing economics would shift the trajectory. Forecasts assume stable ECHA regulatory enforcement and continued EU Green Deal carbon border mechanism implementation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Chaga Mushroom Extract Market
Nutritional Supplements
Dextrose Monohydrate Market
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
South America Collagen Supplements Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Personalized Nutrition Market
Nutritional Supplements
Folate Market
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
Diet Pills Market
Nutritional Supplements
Micellar Casein Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Non-Fish Omega 3 Supplements Market
Nutritional Supplements
Nutraceutical Gummies Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
Throat Lozenges Market
Nutritional Supplements
Fiber Supplements Market