
 Targeting Pod Market | 2026-2036
Targeting Pod Market Size, Share, and Industry Trends Forecast 2026-2036
Targeting Pod Market Analysis
Carbon-fiber composite housings replacing legacy aluminum enclosures is realigning targeting pod weight-to-performance ratios. Lockheed Martin leverages captive aerostructures expertise to integrate sensor payloads across fixed-wing platforms. RTX Corporation sustains dual-waveform laser designator leadership through internal compound semiconductor foundries. Northrop Grumman anchors naval aviation demand with pod variants qualified for carrier-based electromagnetic launch environments.
A targeting pod is an externally carried electro-optical sensor system combining forward-looking infrared, laser rangefinder-designator, and charge-coupled device television for target acquisition, tracking, and guidance handoff to precision munitions; modern units operate across mid-wave and long-wave infrared bands with stabilization accuracies below 50 microradians for high-altitude engagements. Multi-use pods command the installed base due to modular processor architectures permitting sensor swap-outs without airframe recertification, while single-use pods face obsolescence pressure from platform-specific integration costs. Refillable pods concentrate emerging demand in unmanned combat aerial vehicle programs where payload fraction constraints dominate design trades.
The US Department of Defense MIL-STD-810 environmental qualification framework and NATO STANAG 3733 laser safety protocols govern pod interoperability and export eligibility, while FAA airworthiness directives shape commercial derivative certification pathways for dual-use platforms. The EU AI Act's risk classification schema for autonomous targeting assistance functions is creating new compliance layers for European defense contractors. Stakeholders must monitor evolving electromagnetic spectrum allocation rulings that could restrict laser designator operating bands in contested operating environments.
Market Dynamics
Defense modernization programs are compressing targeting pod replacement cycles as NATO member states prioritize electro-optical precision over legacy radar-guided systems, forcing suppliers to reconfigure sensor architectures for multi-platform compatibility.
Growth Catalysts
- US F-35 Fleet Expansion:The Department of Defense's precision strike emphasis drives pod integration across fifth-generation platforms, requiring stabilized multi-spectral targeting at extended ranges.
- NATO STANAG 3733 Harmonization:Laser safety protocol standardization across allied forces enables cross-border interoperability and streamlines export certification for European defense contractors.
- Carbon-Fiber Composite Adoption:Advanced polymer housings reduce airframe payload penalties, permitting extended mission profiles on unmanned combat aerial vehicles where weight fraction constraints dominate design trades.
Market Restraints
- Compound Semiconductor Supply Concentration:Dual-waveform laser designator production depends on captive foundry capacity concentrated among three US and European suppliers, creating single-source vulnerability.
- FAA Airworthiness Recertification Burden:Commercial derivative platforms face dual-use certification pathways that extend development timelines and inflate non-recurring engineering costs.
- Electromagnetic Spectrum Allocation Uncertainty:Contested operating environments risk restricting laser designator operating bands, degrading target handoff reliability in denied airspace.
Strategic Opportunities
- Naval Electromagnetic Launch Qualification:Carrier-based aviation programs require pod variants hardened for catapult launch stresses, opening specialized procurement channels.
- EU AI Act Compliance Layer:Autonomous targeting assistance functions face new risk classification requirements, creating first-mover advantage for European contractors with embedded ethical-review architectures.
- Modular Processor Architecture Convergence:Sensor swap-out capability without airframe recertification permits platform-agnostic pod configurations, reducing program-specific development costs.
Industry Challenges
- Stabilization Accuracy Talent Scarcity:Sub-50 microradian precision engineering for high-altitude engagements requires specialized optomechanical expertise concentrated among aging workforce cohorts.
- MIL-STD-810 Environmental Qualification Timeline:Extended thermal, shock, and vibration testing protocols compress development schedules and delay platform integration milestones.
- Mid-Wave to Long-Wave Infrared Integration Complexity:Dual-band sensor fusion demands signal processing architectures that strain legacy aircraft power and cooling budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Targeting Pod Market |
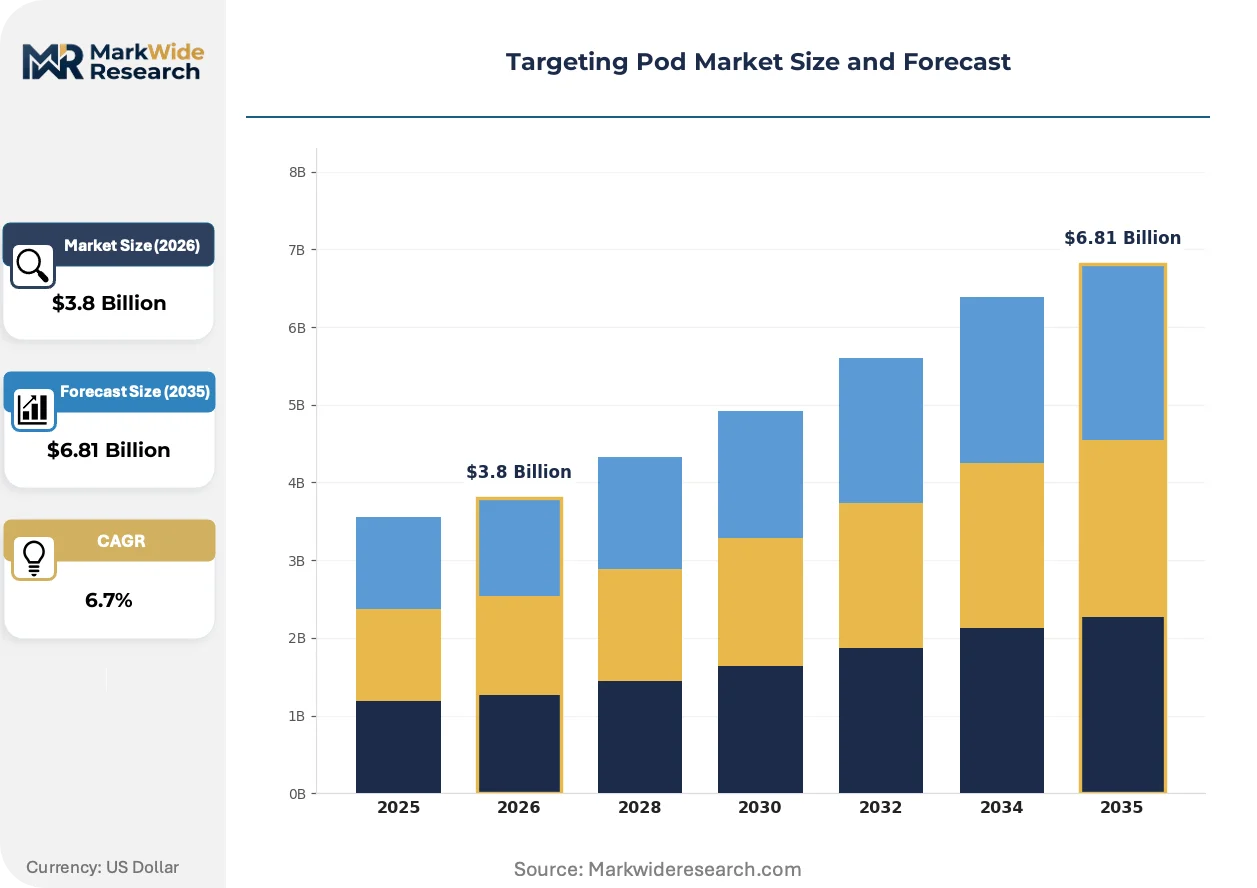
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Pods, Multi-Use Pods, Refillable Pods, Disposable Pods Material: Plastic, Glass, Aluminum, Biodegradable Materials Application: Healthcare, Personal Care, Food & Beverage, Household Cleaning Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, L3Harris Technologies, Thales Group, ASELSAN A.Ş., Rafael Advanced Defense Systems Ltd., Israel Aerospace Industries, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Targeting Pod Market Emerging Trajectories
Active sensor fusion architectures are displacing discrete targeting subsystems, compressing hardware footprints while expanding spectral coverage across contested electromagnetic environments.
Multi-spectral sensor fusion is absorbing discrete electro-optical functions into unified processing chains. Unmanned combat aerial vehicle programs are adopting these integrated payloads fastest, driven by payload fraction constraints that penalize redundant hardware. The technology is absorbing legacy single-function pods into obsolescence as modular architectures permit software-defined targeting profiles without hardware swap-outs.
EU AI Act risk classification for autonomous targeting assistance is mandating algorithmic transparency documentation across European defense supply chains. Contractors must embed ethical-review checkpoints and decision-audit trails into sensor processing firmware. Naval aviation programs face the steepest compliance burden as carrier-based strike platforms integrate increasingly autonomous target recognition.
Platform-agnostic procurement specifications are fragmenting traditional prime-contractor relationships as defense ministries prioritize interoperability over vendor lock-in. System integrators now compete on modular adapter design rather than proprietary airframe integration. The United Kingdom and Australia demonstrate this shift most visibly through joint targeting pod qualification programs that accept multiple supplier configurations per platform type.
Targeting Pod Market Segmentation
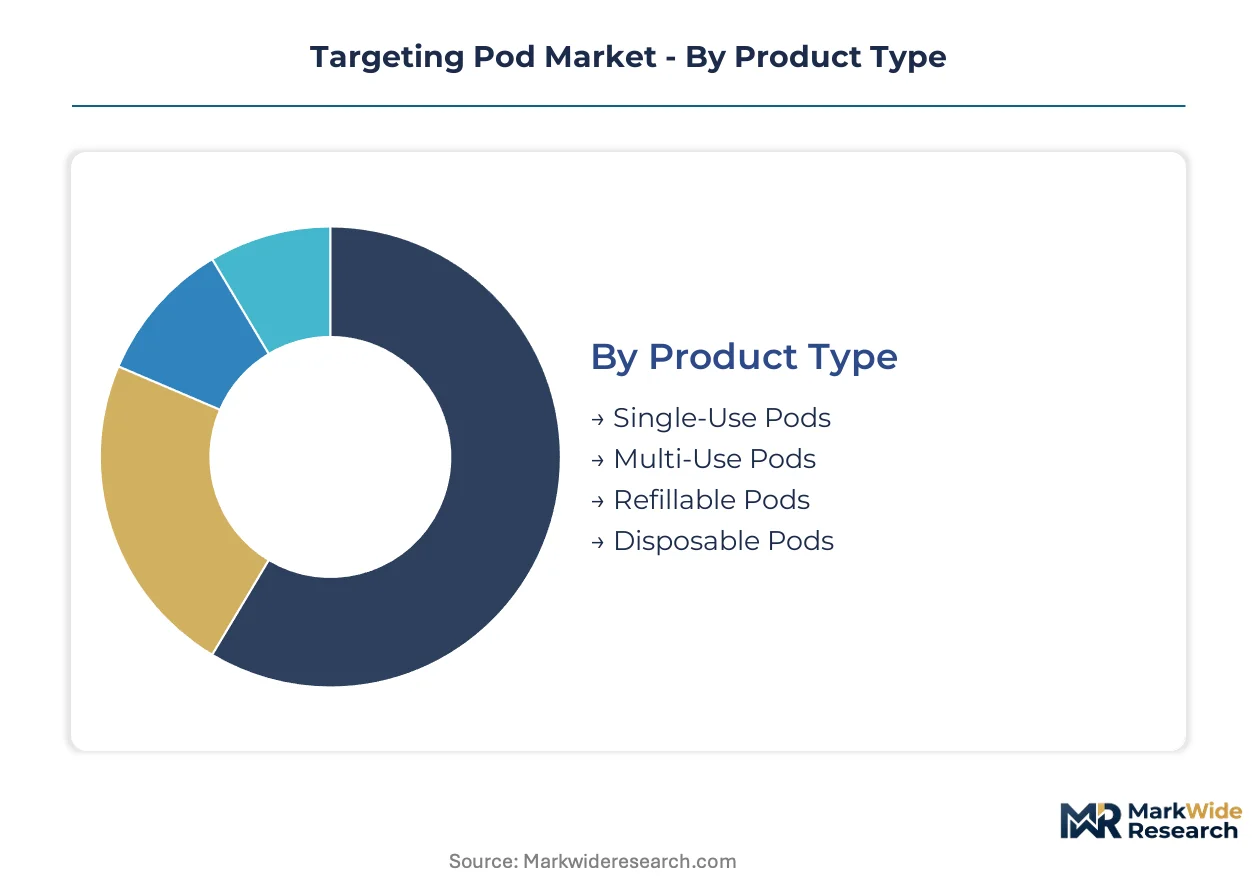
Targeting pod procurement decisions hinge on platform-specific integration requirements, environmental qualification tiers, and mission profile demands. Segmentation reveals how defense contractors allocate engineering resources across pod architectures with divergent lifecycle economics and interoperability constraints.
Product Type:
Capital intensity escalates sharply with pod complexity, as multi-use architectures demand modular processor investments that dwarf single-use alternatives.
- Multi-Use Pods:Modular processor architectures enable sensor swap-outs without airframe recertification, concentrating procurement among NATO F-35 and legacy fighter upgrade programs where platform flexibility commands premium pricing. Carbon-fiber composite housings and dual-waveform laser designators drive non-recurring engineering above single-use alternatives.
- Refillable Pods:Dominant in unmanned combat aerial vehicle programs where payload fraction constraints penalize disposable alternatives. The US Department of Defense's precision strike emphasis accelerates procurement for extended-range engagement profiles requiring stabilized multi-spectral targeting.
- Single-Use Pods:Face obsolescence pressure from platform-specific integration costs that fragment production runs.
- Disposable Pods:Limited to contingency scenarios where battlefield recovery is impractical; minimal installed base.
Multi-use pods absorb the bulk of installed capacity; refillable pods are expanding most quickly.
Material:
Weight-to-performance ratios differentiate procurement tiers, with advanced composites commanding aerospace-grade qualification premiums over legacy metals.
- Carbon-Fiber Composite:Replacing aluminum enclosures across next-generation pod programs, reducing airframe payload penalties and enabling extended mission profiles on carrier-based electromagnetic launch platforms. Lockheed Martin and RTX Corporation leverage captive aerostructures expertise for integrated sensor payload housings.
- Aluminum:Sustains legacy fighter upgrade programs where MIL-STD-810 environmental qualification frameworks already govern existing airframe interfaces.
- Plastic:Restricted to training pod variants with relaxed thermal and shock specifications.
- Glass:Limited to specialized optical window applications requiring specific transmission properties.
Carbon-fiber composite absorbs the bulk of new program investment; aluminum retains the largest legacy installed base.
Application:
Mission-criticality determines environmental qualification depth, with naval aviation imposing the steepest electromagnetic launch and salt-corrosion resistance requirements.
- Fixed-Wing Combat Aviation:Demands sub-50 microradian stabilization accuracy for high-altitude engagements across mid-wave and long-wave infrared bands. Northrop Grumman anchors this segment with carrier-qualified variants hardened for catapult launch stresses.
- Unmanned Combat Aerial Vehicles:Prioritize payload fraction optimization, driving rapid adoption of integrated multi-spectral sensor fusion architectures that compress hardware footprints.
- Rotary-Wing Platforms:Requires specialized vibration isolation for hover-stable target designation.
- Ground-Based Targeting:Limited to expeditionary applications with reduced environmental qualification burdens.
Fixed-wing combat aviation commands the deepest qualification investment; unmanned platforms are climbing the fastest.
Distribution Channel:
Procurement concentration reflects defense acquisition reform trends favoring platform-agnostic specifications over prime-contractor lock-in.
- Direct Military Procurement:Dominates through US Department of Defense F-35 fleet expansion and NATO STANAG 3733 harmonization programs. The United Kingdom and Australia demonstrate joint qualification accepting multiple supplier configurations per platform type.
- Foreign Military Sales:Constrained by ITAR and laser safety protocol export eligibility requirements.
- Commercial Derivative Pathways:Faces FAA airworthiness recertification burdens that extend development timelines.
- Aftermarket Support Contracts:Concentrates in legacy platform sustainment with diminishing procurement share.
Direct military procurement channels absorb the bulk of program value; foreign military sales channels face steepest regulatory expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentrates heavily in the United States, where F-35 fleet expansion and legacy fighter upgrades drive the majority of electro-optical targeting system demand. NATO harmonization efforts and unmanned combat aerial vehicle programs are redistributing investment patterns across allied nations.
United States
The Department of Defense's precision strike emphasis accelerates pod integration across fifth-generation platforms and unmanned systems. FAA airworthiness directives govern commercial derivative certification pathways for dual-use platforms. Arizona and Texas host major final assembly operations where carbon-fiber composite housings undergo MIL-STD-810 environmental qualification.
United Kingdom
Joint qualification programs with Australia accept multiple supplier configurations per platform type, fragmenting traditional prime-contractor relationships. The country's national defense procurement authority prioritizes interoperability over vendor lock-in. Bristol and Lancashire clusters concentrate sensor fusion engineering talent for carrier-based electromagnetic launch environments.
Germany
EU AI Act risk classification requirements create compliance layers for autonomous targeting assistance functions in European defense supply chains. The national aerospace regulator oversees platform-agnostic procurement specifications. Bavaria's precision engineering corridor anchors optomechanical stabilization expertise for sub-50 microradian accuracy systems.
Israel
Export-oriented defense contractors supply electro-optical targeting systems to allied forces under foreign military sales frameworks constrained by laser safety protocol eligibility. The national defense export control authority governs dual-waveform laser designator shipments. Haifa and Tel Aviv metropolitan areas concentrate compound semiconductor foundry capacity for captive laser component production.
Australia
Joint targeting pod qualification programs with the United Kingdom demonstrate procurement reform favoring modular adapter design over proprietary airframe integration. The national defense department emphasizes extended-range engagement profiles for Indo-Pacific operating environments. South Australian shipbuilding and aerospace clusters support naval electromagnetic launch qualification testing.
Targeting Pod Market Vendor Landscape
Platform-agnostic procurement specification dominates the current landscape as defense ministries fragment traditional prime-contractor relationships. The vendor base organizes around three strategic archetypes: systems integrators competing on modular adapter design, captive aerostructures specialists leveraging composite housing expertise, and compound semiconductor foundry operators controlling dual-waveform laser component supply. M&A activity concentrates in sensor fusion capabilities while strategic partnerships address electromagnetic spectrum allocation uncertainty.
Among US-based defense primes, Lockheed Martin Corporation, RTX Corporation, and Northrop Grumman Corporation occupy positions across the integrated systems tier. Lockheed Martin exemplifies the captive aerostructures archetype through carbon-fiber composite housing production. RTX Corporation sits within the compound semiconductor foundry operator category. Northrop Grumman anchors naval aviation demand representation. European and Israeli specialists including Thales Group, ASELSAN A.Ş., Rafael Advanced Defense Systems Ltd., Israel Aerospace Industries, and BAE Systems occupy regional supplier positions shaped by EU AI Act compliance requirements and NATO STANAG 3733 harmonization protocols.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| L3Harris Technologies |
| Thales Group |
| ASELSAN A.Ş. |
| Rafael Advanced Defense Systems Ltd. |
| Israel Aerospace Industries |
| BAE Systems |
| Others |
Supply Flow & Price Mechanics
MIL-STD-810 environmental qualification gates both qualified supply and premium-tier pricing access, as defense contractors must absorb extended thermal and vibration testing costs before bidding on F-35 integration programs. Carbon-fiber composite housing suppliers command aerospace-grade premiums over legacy aluminum alternatives, while compound semiconductor foundry capacity concentrates pricing power among captive producers.
Pricing Analysis
Volume-vs-margin splits sharply across pod architectures, with multi-use configurations trading lower unit volumes for platform-agnostic premiums against refillable alternatives chasing unmanned combat aerial vehicle scale. Pricing stratifies across MIL-810 qualified, STANAG 3733 certified, and training-grade tiers, with certification depth driving differentiation. Cost compression in single-use segments is intensifying because platform-specific integration fragments production economics. Foreign military sales channels exhibit highest price sensitivity due to ITAR compliance overhead, while direct US Department of procurement shows lowest sensitivity to unit premiums.
Supply Chain Analysis
Dual-sourcing requirements mandated by NATO STANAG protocols force prime contractors to qualify secondary compound semiconductor foundries in the United States and Israel, reducing single-source vulnerability for dual-waveform laser designators. Supply draws from captive aerostructures facilities in Arizona and Texas, compound semiconductor foundries in Haifa, and precision optics clusters in Bavaria. Tariff exposure on carbon-fiber pre-preg imports from Japan threatens housing cost structures. Distribution runs through foreign military sales frameworks constrained by laser safety protocol eligibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active sensor fusion architectures are displacing discrete targeting subsystems, compressing hardware footprints while rendering legacy single-function pods obsolete across NATO modernization programs.
For Market Incumbents: Cement captive compound semiconductor foundry capacity to defend against supply concentration risks threatening dual-waveform laser designator output. Deepen backward integration into carbon-fiber composite aerostructures to capture housing premiums and accelerate MIL-STD-810 qualification timelines. For New Entrants and Emerging Players: Capture naval electromagnetic launch qualification niches where Northrop Grumman's carrier-hardened variants face limited competition, and exploit EU AI Act compliance service layers for European defense contractors lacking embedded ethical-review architectures. Target Australia's joint qualification programs with the United Kingdom, where platform-agnostic specifications fragment prime-contractor lock-in and reward modular adapter design. For Investors and Strategic Acquirers: Joint UK-Australia targeting pod qualification programs accepting multiple supplier configurations is the leading indicator that platform-agnostic procurement is structurally displacing proprietary integration economics. Long-term viability favors sensor fusion specialists with software-defined targeting profiles over hardware-centric legacy pod manufacturers. Watch for electromagnetic spectrum allocation rulings restricting laser designator bands as the signal for accelerated obsolescence in single-wavelength architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Compound Semiconductor Foundry Expansion | Captive dual-waveform laser production reduces RTX Corporation-style supply vulnerability for NATO contractors. |
| Carbon-Fiber Housing Integration | Lockheed Martin's aerostructures expertise enables payload fraction optimization for unmanned combat aerial vehicles. |
| Naval Electromagnetic Launch Qualification | Carrier-hardened variants open specialized procurement channels beyond fixed-wing Air Force programs. |
| EU AI Act Compliance Architecture | Embedded ethical-review checkpoints create first-mover advantage for Thales Group and BAE Systems in European defense supply chains. |
| Modular Processor Platform Development | Sensor swap-out capability without airframe recertification reduces program-specific engineering costs across F-35 and legacy fighter upgrades. |
Methodological Framework
Multi-period observation of F-35 fleet delivery schedules, NATO STANAG 3733 harmonization progress, and unmanned combat aerial vehicle program awards anchored the trend analysis, supplemented by interviews with electro-optical systems program managers, defense procurement officers at the US Department of Defense and UK Ministry of Defence, compound semiconductor foundry operations directors, and carrier-based aviation qualification engineers. Secondary validation drew from Department of Defense budget justification documents, NATO standardization office publications, FAA airworthiness directive filings, and EU AI Act implementation guidance. Bottom-up platform integration timelines and top-down defense expenditure patterns were triangulated to cross-check volume assumptions.
Input-output matrices mapped pod architecture complexity against platform-specific qualification burdens, segmenting across multi-use, refillable, and single-use configurations; carbon-fiber composite, aluminum, and plastic material tiers; fixed-wing, unmanned, rotary-wing, and ground-based applications; and direct military, foreign military sales, and commercial derivative channels. CAGRs were derived from defense modernization program pacing and replacement cycle compression across the analysis window. Forecast inputs incorporated F-35 procurement trajectories and unmanned combat aerial vehicle payload fraction constraints.
The model holds under sustained NATO defense expenditure and stable electromagnetic spectrum allocation for laser designator bands; deviation in compound semiconductor foundry capacity constraints or restrictive spectrum rulings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Soy Food Products Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
USA Plant-Based Creamers Market
Plant Based Food
United States Rice Protein Market
Plant Based Food
Black Rice Protein Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Plant-Based Protein Food Market
Plant Based Food
Kava Root Extract Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Plant-Based Hot Dogs Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Plant-Based Frozen Dessert Market
Plant Based Food
Plant Chocolate Protein Powder Market
Plant Based Food
Vegan Pasta Market