
 US Plant-Based Meat Market | 2026-2036
US Plant-Based Meat Market Size, Share, and Industry Trends Forecast 2026-2036
US Plant-Based Meat Market Analysis
Buyer concentration across the US food service channel is broadening as regional restaurant chains and college dining programs diversify procurement beyond legacy suppliers. Beyond Meat Inc. leverages direct-to-foodservice distribution to secure institutional contracts, while Impossible Foods Inc. anchors its position through burger-centric formulation R&D. Maple Leaf Foods Inc. competes via vertically controlled pea protein sourcing, and Kellogg Company extends refrigerated retail shelf access through established grocery networks.
Plant-based meat comprises extruded or shear-cell processed protein isolates, binders, and lipid systems engineered to replicate animal muscle tissue texture and thermal behavior, primarily serving commercial food manufacturing and prepared food retail. Pea protein dominates formulation pipelines due to allergen labeling advantages over soy, while wheat protein retains cost competitiveness in nugget and meatball applications where gluten functionality aids binding. Distribution through supermarkets still captures the largest revenue pool, though online channel velocity is accelerating fastest among repeat-purchase households.
FDA nutrition labeling rules and USDA FSIS oversight of cell-cultured and plant-based terminology directly shape permissible marketing claims and retail placement eligibility across interstate commerce. State-level California Proposition 12 compliance requirements and municipal procurement preferences in Seattle and Portland further constrain supplier qualification criteria. Stakeholders must monitor evolving FDA guidance on fermentation-derived ingredients and state legislative battles over meat nomenclature restrictions to anticipate reformulation and relabeling obligations.
Market Dynamics
Food service procurement decentralization is fragmenting buyer power across regional restaurant chains and institutional dining programs, forcing suppliers to rebuild distribution networks around localized fulfillment rather than national bulk contracts.
Growth Catalysts
- USDA FSIS labeling clarity:The agency's 2023 guidance on permissible "meat" terminology for plant-based products reduced interstate commerce friction and unlocked shelf placement in conventional retail channels previously blocked by nomenclature disputes.
- Shear-cell processing:This extrusion alternative achieves fibrous texture without high-temperature steps, cutting energy inputs and enabling cleaner-label positioning that resonates with college dining procurement committees.
- California Proposition 12 compliance:The state's animal welfare standards are accelerating food service operator interest in plant alternatives as hedges against conventional protein cost volatility and supply uncertainty.
Market Restraints
- Pea protein supply concentration:North American processing capacity clusters in the upper Midwest, creating geographic single-source risk for formulators dependent on non-soy isolates.
- Clean-label lipid systems:Coconut and sunflower oil costs swing with tropical weather patterns and Black Sea export disruptions, compressing margin stability for premium-positioned products.
- FDA fermentation oversight uncertainty:Pending guidance on precision-fermented heme and other novel ingredients is freezing R&D pipelines and delaying product launches that require GRAS self-determination.
Strategic Opportunities
- K-12 school nutrition programs:USDA child nutrition meal pattern updates are creating procurement windows for plant-based entrees that meet protein and iron equivalency standards at reimbursable price points.
- Convenience store foodservice:Roller-grill and hot-hold equipment in 7-Eleven and Circle K locations represents untapped velocity for pre-cooked plant-based sausages and breakfast patties.
- IRA clean energy tax credits:Processing facility investments in renewable-powered extrusion lines qualify for accelerated depreciation, lowering capex hurdles for regional co-manufacturers.
Industry Challenges
- Food technologist scarcity:Formulation expertise spanning protein chemistry, lipid oxidation control, and sensory science commands premium compensation that mid-scale entrants struggle to match.
- Dual certification timelines:Simultaneous pursuit of USDA Organic and Non-GMO Project verification extends launch calendars by 8-14 months, delaying revenue recognition.
- Legacy equipment retrofitting:Conventional meat processing lines require stainless steel segregation, dedicated sanitation protocols, and allergen changeover procedures that inflate operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Plant-Based Meat Market |
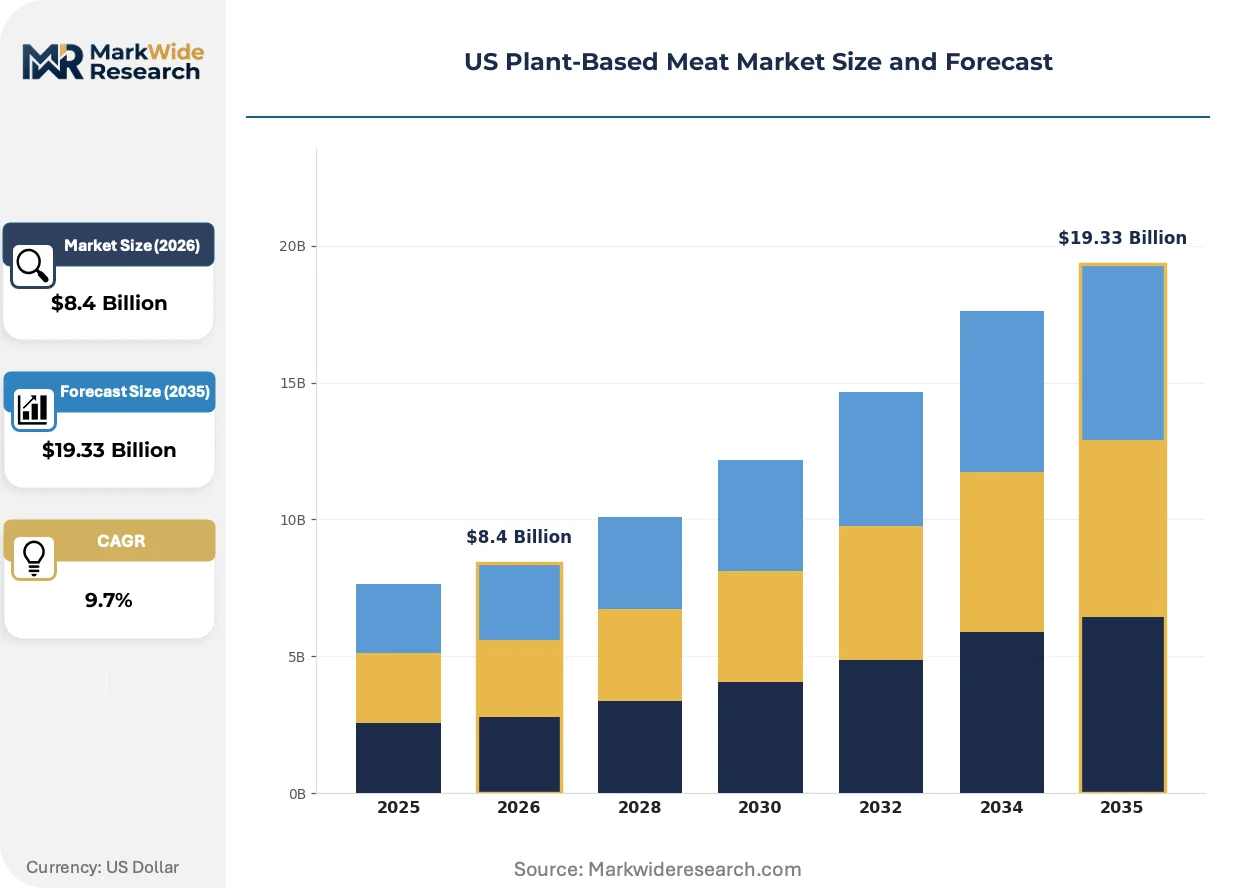
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
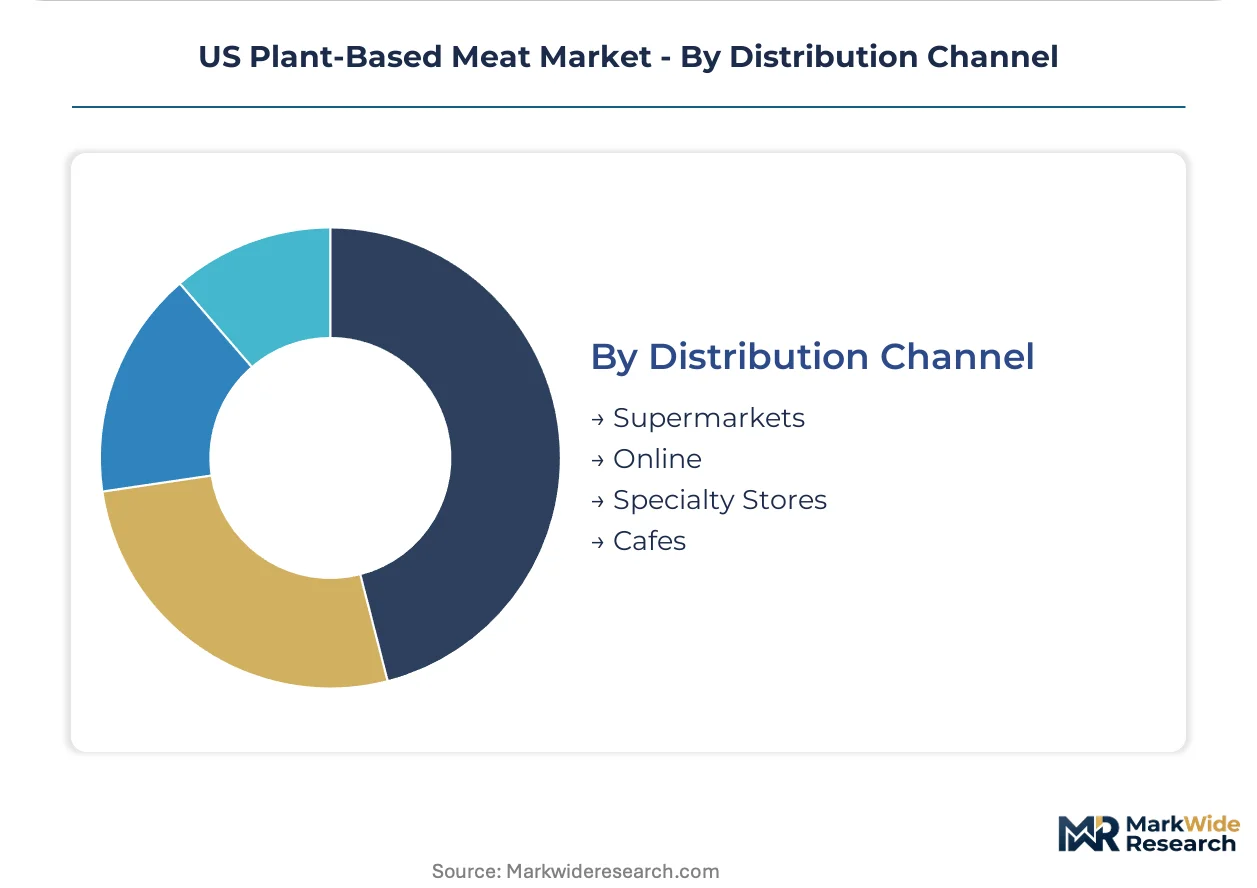
| Segmentation | Product Type: Burgers, Sausages, Nuggets, Meatballs Source: Pea Protein, Soy Protein, Wheat Protein, Rice Protein End User: Retail Consumers, Food Service, Restaurants, Meal Kits Distribution Channel: Supermarkets, Online, Specialty Stores, Cafes |
| Companies Covered | Tofurky, Maple Leaf Foods Inc., Beyond Meat Inc., Quorn Foods, Kellogg Company, Impossible Foods Inc., Conagra Brands, Inc., Atlantic Natural Foods LLC, Amy’s Kitchen Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Plant-Based Meat Market Emerging Trajectories
Texture replication and thermal performance are converging with clean-label demands to redefine competitive differentiation, while regulatory clarity and procurement decentralization are reshaping how products reach end consumers.
High-moisture extrusion with post-texturization cooling is rewriting the cost-quality tradeoff for whole-muscle analogs. Regional burger chains in Texas and Florida are adopting these formulations for limited-time offerings at price parity with conventional patties. The technology is compressing the premium gap that previously confined plant-based proteins to coastal urban markets.
FDA's evolving framework for fermentation-derived ingredients is forcing reformulation roadmaps across the sector. Companies banking on mycelium or precision-fermented proteins face extended GRAS consultation timelines that delay commercialization. The uncertainty most acutely affects startups targeting clean-label positioning without soy or pea base materials.
Direct-to-foodservice distribution bypasses traditional broker networks that extracted 15-20 point margins. College dining consortiums and regional restaurant groups are consolidating procurement through cooperative purchasing agreements that favor suppliers with localized production. This pattern concentrates in the Pacific Northwest and Northeast corridor where sustainability scoring drives vendor selection.
US Plant-Based Meat Market Segmentation
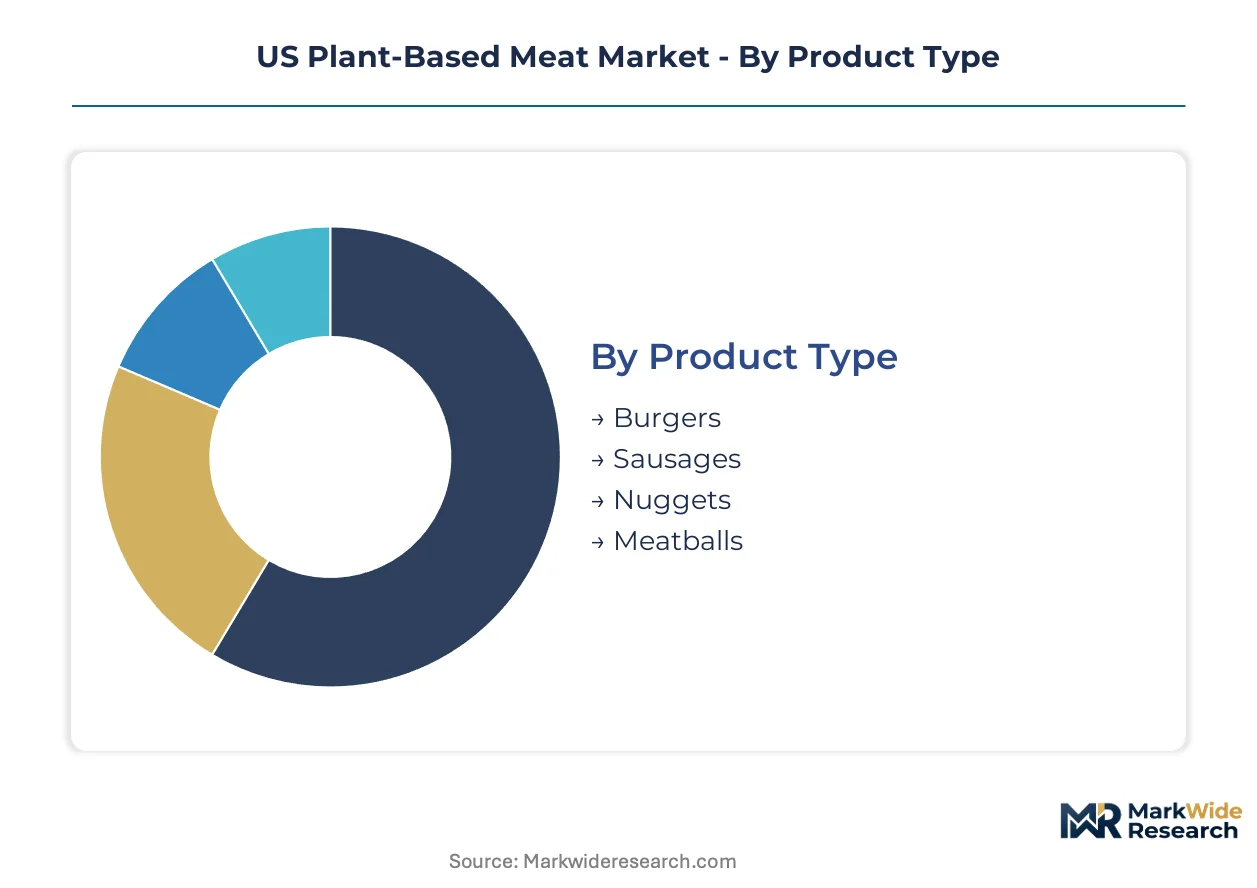
Segmentation in the US plant-based meat market reveals how formulation choices, procurement channels, and end-use applications create distinct competitive arenas. Understanding these divides exposes where margin pools concentrate and where supplier capabilities must adapt.
Product Type:
Food service operators select formats based on equipment compatibility and speed-scratch preparation requirements.
- Burgers:High-moisture extrusion creates fibrous, grillable patties with Maillard-reactive surfaces. Demand clusters in quick-service chains across Texas and Florida where price parity testing with conventional beef is accelerating.
- Sausages:Co-extruded alginate casings replicate snap and juiciness in breakfast and dinner applications. College dining programs in the Pacific Northwest specify these for sustainability-scored procurement menus.
- Nuggets:Wheat-gluten binding systems dominate this battered format for cost efficiency in K-12 reimbursable meals.
- Meatballs:Pre-cooked frozen formats suit institutional batch cooking with standardized portion control.
Burgers lead on scale; sausages lead on momentum.
Source:
Protein base selection hinges on allergen labeling exposure and regional crop processing proximity.
- Pea Protein:Isolates from yellow split peas deliver complete amino acid profiles without soy allergen warnings. Formulators in California and the Pacific Northwest prioritize this for clean-label positioning in retail and food service channels.
- Soy Protein:Textured concentrates remain cost-competitive for nugget and crumble applications where allergen warnings are acceptable trade-offs.
- Wheat Protein:Vital gluten provides elastic binding in meatballs and nuggets with established Midwest supply chains.
- Rice Protein:Hypoallergenic positioning serves niche pediatric and specialty diet segments with limited volume scale.
Pea protein leads on scale; rice protein leads on momentum.
End User:
Procurement decentralization is fragmenting buyer power across channel types with diverging technical specifications.
- Food Service:Institutional dining programs demand frozen, pre-cooked formats with validated hold times and HACCP-compliant reheating protocols. Regional restaurant chains in the Northeast corridor are consolidating purchases through cooperative agreements.
- Restaurants:Independent operators seek fresh, refrigerated patties with shorter ingredient lists for menu storytelling.
- Retail Consumers:Repeat-purchase households drive velocity in supermarket refrigerated cases with brand loyalty built on texture consistency.
- Meal Kits:Pre-portioned, quick-thaw components require modified atmosphere packaging for shelf-life extension in direct-to-home logistics.
Food service leads on scale; meal kits lead on momentum.
Distribution Channel:
Channel selection determines margin structure and brand control intensity.
- Supermarkets:Refrigerated retail placement demands slotting fees and promotional compliance with chain-specific sustainability scorecards. This channel captures the largest revenue pool through established grocery network access.
- Online:Direct-to-consumer subscriptions and marketplace listings accelerate fastest among repeat-purchase households seeking flavor variety packs. Fulfillment complexity limits this to ambient-stable or frozen formats.
- Specialty Stores:Natural and organic retailers command premium positioning with Non-GMO Project verification as table stakes.
- Cafes:Limited-service coffee chains with hot-hold equipment represent emerging velocity for breakfast sausage patties and pre-cooked strips.
Supermarkets lead on scale; online leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision-fermentation infrastructure attracts more capital than France's traditional extrusion base, yet both countries operate under EU regulatory frameworks that diverge sharply from FDA pathways in the United States.
California
San Francisco Bay Area venture capital flows into mycelium startups while Los Angeles anchors celebrity-backed brand launches. California Proposition 12 compliance requirements push food service operators toward plant alternatives as hedges against conventional protein volatility. The Sacramento Central Valley hosts pea protein processing clusters serving West Coast formulators.
Texas
Dallas-Fort Worth regional burger chains test price-parity patties for limited-time offerings in suburban drive-through markets. USDA FSIS labeling guidance enables interstate shipment of Texas-manufactured products to conventional retail channels previously blocked by nomenclature disputes. Houston's petrochemical corridor supplies lipid system precursors for clean-label formulations.
Pacific Northwest
Seattle and Portland municipal procurement preferences prioritize sustainability-scored vendor selection for institutional dining contracts. Shear-cell processing adoption accelerates in Washington State facilities seeking energy-efficient alternatives to high-temperature extrusion. Oregon's Willamette Valley food hub concentrates co-manufacturing capacity for regional restaurant cooperatives.
Northeast Corridor
Boston's college dining consortiums consolidate procurement through cooperative purchasing agreements favoring localized production. New York Metro's refrigerated distribution networks extend shelf access for fresh patties in independent restaurant channels. FDA fermentation oversight uncertainty freezes R&D pipelines for Philadelphia-area startups targeting clean-label positioning.
Midwest
Illinois and Michigan house legacy meat processing equipment retrofitted for plant-based segregation protocols under allergen changeover procedures. Chicago's food ingredient trading floors set regional pricing for wheat gluten binding systems. Ohio's soy protein concentrate capacity serves cost-competitive nugget applications for K-12 reimbursable meal programs.
US Plant-Based Meat Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channel access and formulation R&D depth. The vendor base stratifies into three tiers: multinational CPG holding companies with refrigerated retail networks, dedicated alternative protein ventures with food service direct distribution, and regional co-manufacturers serving institutional buyers. Consolidation pressure intensifies as slotting fee requirements and dual certification timelines favor scaled balance sheets over startup agility.
Among North American pure-play specialists, Beyond Meat Inc. and Impossible Foods Inc. occupy positions defined by contrasting channel strategies. Maple Leaf Foods Inc. exemplifies diversified conglomerate entry through vertically controlled supply chain integration. These three anchors represent archetypes that smaller entrants must navigate around when securing college dining contracts or regional restaurant procurement.
| Leading Market Players |
|---|
| Tofurky |
| Maple Leaf Foods Inc. |
| Beyond Meat Inc. |
| Quorn Foods |
| Kellogg Company |
| Impossible Foods Inc. |
| Conagra Brands, Inc. |
| Atlantic Natural Foods LLC |
| Amy's Kitchen Inc. |
| Others |
Supply Flow & Price Mechanics
Venture-backed pure-play specialists and legacy CPG conglomerates anchor divergent pricing architectures across the US plant-based meat sector, with the former absorbing margin compression to secure food service contracts while the latter leverage captive retail shelf access to defend premium positioning against input cost volatility.
Pricing Analysis
Capacity additions in the upper Midwest are reshaping price floors for pea protein isolates, compressing the premium gap that previously separated coastal clean-label formulations from heartland commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with USDA Organic and Non-GMO Project verification commanding 15-20 point markups. Cost compression in the economy tier is intensifying because wheat-gluten binding systems undercut pea isolates on per-pound basis. K-12 reimbursable meal programs exhibit highest price sensitivity; independent restaurants with menu storytelling requirements show least.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised frozen patties and expired refrigerated formats remain underdeveloped, forcing write-offs that inflate net landed costs for regional distributors. North American supply concentrates in the upper Midwest for pea protein processing, California for mycelium fermentation infrastructure, and Texas for lipid system precursor manufacturing. Formulation pipelines draw from yellow split pea isolates, coconut and sunflower oil systems, and vital wheat gluten. Single-source vulnerability in pea protein processing creates geographic concentration risk. Distribution runs through direct-to-foodservice networks bypassing traditional broker margins, supplemented by refrigerated retail brokerage for supermarket placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US plant-based meat market functions as a stable compounder anchored by institutional procurement shifts that lock in multi-year volume commitments regardless of consumer trial volatility.
For Market Incumbents: Acquire shear-cell processing equipment portfolios to secure energy-efficient production capacity before regional co-manufacturers capture IRA clean energy tax credits. Consolidate backward integration into yellow split pea processing to neutralize upper Midwest supply concentration risk. Defend against precision-fermentation startups by accelerating GRAS self-determination timelines for clean-label heme alternatives. For New Entrants and Emerging Players: Enter via convenience store foodservice channels where roller-grill equipment creates velocity gaps unclaimed by established burger-centric suppliers. Target K-12 school nutrition programs as the most penetrable segment given USDA child nutrition meal pattern updates opening procurement windows. Pursue cooperative purchasing agreements with college dining consortiums as the dominant go-to-market angle in sustainability-scored procurement corridors. For Investors and Strategic Acquirers: Valuations sit cheapest among regional co-manufacturers with localized production and USDA Organic certification already secured. Long-term viability across the five-to-ten year window hinges on fermentation-derived ingredient pipelines achieving regulatory clarity. Monitor FDA guidance publication on precision-fermented heme as the critical inflection signal for clean-label positioning premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Shear-Cell Processing Adoption | Washington State facilities cut energy inputs while satisfying Pacific Northwest sustainability procurement criteria. |
| Direct-to-Foodservice Distribution Buildout | Bypassing broker networks recaptures 15-20 point margins for college dining contract competitiveness. |
| Dual Certification Investment | Simultaneous USDA Organic and Non-GMO Project verification unlocks premium positioning in natural retail channels. |
| Regional Co-Manufacturing Partnership | Localized production satisfies Seattle and Portland municipal procurement preferences for shortened supply chains. |
| Fermentation-Derived Ingredient Pipeline | Precision-fermented heme alternatives await FDA GRAS clarity to displace soy and pea base materials in clean-label formulations. |
Methodological Framework
Multiple input streams — regulatory filing analysis, trade data reconciliation, and procurement contract review — were reconciled against primary interviews with food service procurement directors, plant-based formulation scientists, college dining consortium managers, and refrigerated distribution operators. Secondary validation drew from USDA FSIS guidance documents, FDA GRAS notification databases, California Proposition 12 compliance filings, and cooperative purchasing agreement disclosures. Bottom-up volume modeling and top-down value reconciliation triangulated segment-level estimates.
Data-stream reconciliation across supply-side capacity announcements, buyer procurement patterns, and ingredient cost indices informed the analytical framework. Segmentation dimensions modeled include product format, protein source, end-user channel, and distribution pathway across the projection horizon. CAGRs were derived from fitted growth curves anchored to disclosed contract volumes and capacity expansion timelines. Forecast inputs incorporated shear-cell processing adoption rates and fermentation-derived ingredient regulatory status transitions.
The model holds under stable FDA guidance interpretation and sustained IRA clean energy credit availability; deviation in precision-fermentation oversight stringency or Proposition 12 enforcement scope would shift volume trajectories. Forecasts reflect documented assumptions regarding procurement decentralization velocity and certification timeline standardization. Practitioners should monitor FDA draft guidance publication schedules and state-level meat nomenclature legislative battles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
Yellow Pea Protein Market
Plant Based Food
India Plant Protein Market
Plant Based Food
Vegan Alternatives Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Veggie Meals Market
Plant Based Food
Asia-Pacific Plant-Based Seafood Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Packed Vegan Foods Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Vegan Drink Mixes Market
Plant Based Food
Vegan Meat Alternatives Market