
 Soy Food Products Market | 2026-2036
Soy Food Products Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Food Products Market Analysis
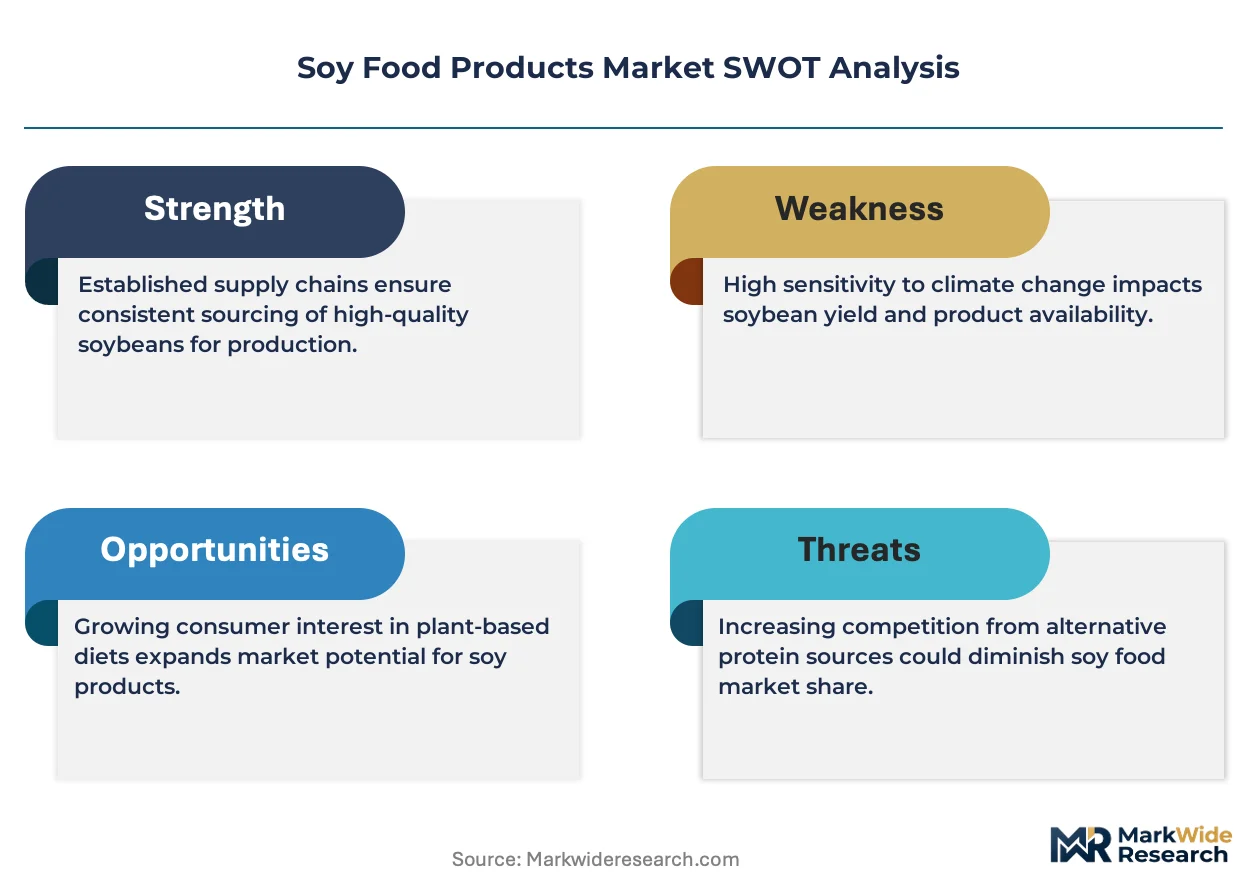
Premium organic certification tiers are redrawing competitive boundaries in the soy food products landscape. Danone S.A. leverages its European dairy-alternative infrastructure to dominate refrigerated soy milk distribution. Vitasoy International Holdings anchors its position through deep channel control across Asian retail networks. Nestlé S.A. extends its R&D intensity into fermented soy proteins for specialized nutrition applications.
Soy food products encompass processed and minimally processed goods derived from Glycine max, typically containing protein isolates with PDCAAS scores approaching animal protein completeness and isoflavone concentrations of 1-3 mg per gram of protein. These products serve industrial formulation, direct consumption, and nutritional supplementation purposes across commercial and institutional channels. The liquid form category leads volume throughput due to soy milk's established retail presence, while powder formats represent the fastest-growing margin pool through sports nutrition and clinical nutrition integration. Meat alternatives within the application dimension concentrate investment as foodservice operators reformulate menus around plant-based center-plate proteins.
The FDA governs soy protein health claim substantiation in the United States, while EFSA evaluates novel food authorizations for fermented soy innovations across European markets. China's SAMR enforces GB standards for soy beverage labeling and additive thresholds, directly affecting import access and domestic formulation requirements. Stakeholders must monitor evolving protein quality thresholds and fermentation process approvals as regulatory science catches up to processing innovation.
Market Dynamics
Plant-based meat alternatives are compressing traditional protein supply chains as foodservice operators accelerate menu reformulation around soy-based center-plate options, forcing ingredient suppliers to retool capacity toward textured protein isolates.
Growth Catalysts
- FDA Health Claim Authorization:The FDA's updated soy protein health claim substantiation framework permits cardiovascular benefit labeling, expanding permissible positioning for soy milk and protein fortification products in US retail channels.
- Foodservice Menu Reformulation:Quick-service and full-service restaurant chains are embedding soy-based meat alternatives into permanent menu architecture, creating sustained offtake contracts for textured vegetable protein suppliers.
- East Asian Consumption Persistence:Traditional tofu and fermented soy formats in China, Japan, and South Korea anchor baseline demand while modern processed variants capture younger demographic trial.
Market Restraints
- Input Cost Volatility:Non-GMO soybean premiums and organic certification requirements inflate raw material costs versus conventional commodity soy, compressing margin structures for mid-tier processors.
- Supply Concentration Risk:Brazil and the United States dominate global soybean origination, exposing formulated product manufacturers to weather-driven harvest variability and export policy shifts.
- Allergen Labeling Friction:EFSA's stringent novel food authorization pathways for fermented soy proteins extend time-to-market for European innovators, delaying revenue recognition against R&D investment.
Strategic Opportunities
- Clinical Nutrition Integration:Powder format soy proteins with PDCAAS scores approaching animal completeness are penetrating enteral and sports nutrition applications, opening pharmaceutical and performance nutrition channels.
- Refrigerated Distribution Innovation:Cold-chain infrastructure investments in Southeast Asia enable fresh tofu and chilled soy milk formats to reach previously unserved urban retail nodes.
- Dual Carbon Policy Alignment:China's SAMR enforcement of GB standards for plant-based protein labeling aligns with national decarbonization mandates, creating regulatory tailwinds for domestic soy food expansion.
Industry Challenges
- Fermentation Process Scale-Up:Commercializing novel fermented soy protein formats requires bioreactor capacity and strain optimization expertise scarce among traditional soy processors.
- Cross-Contamination Protocols:Facilities producing both soy and dairy alternatives face complex allergen segregation requirements under FDA Food Safety Modernization Act enforcement, elevating compliance engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Food Products Market |
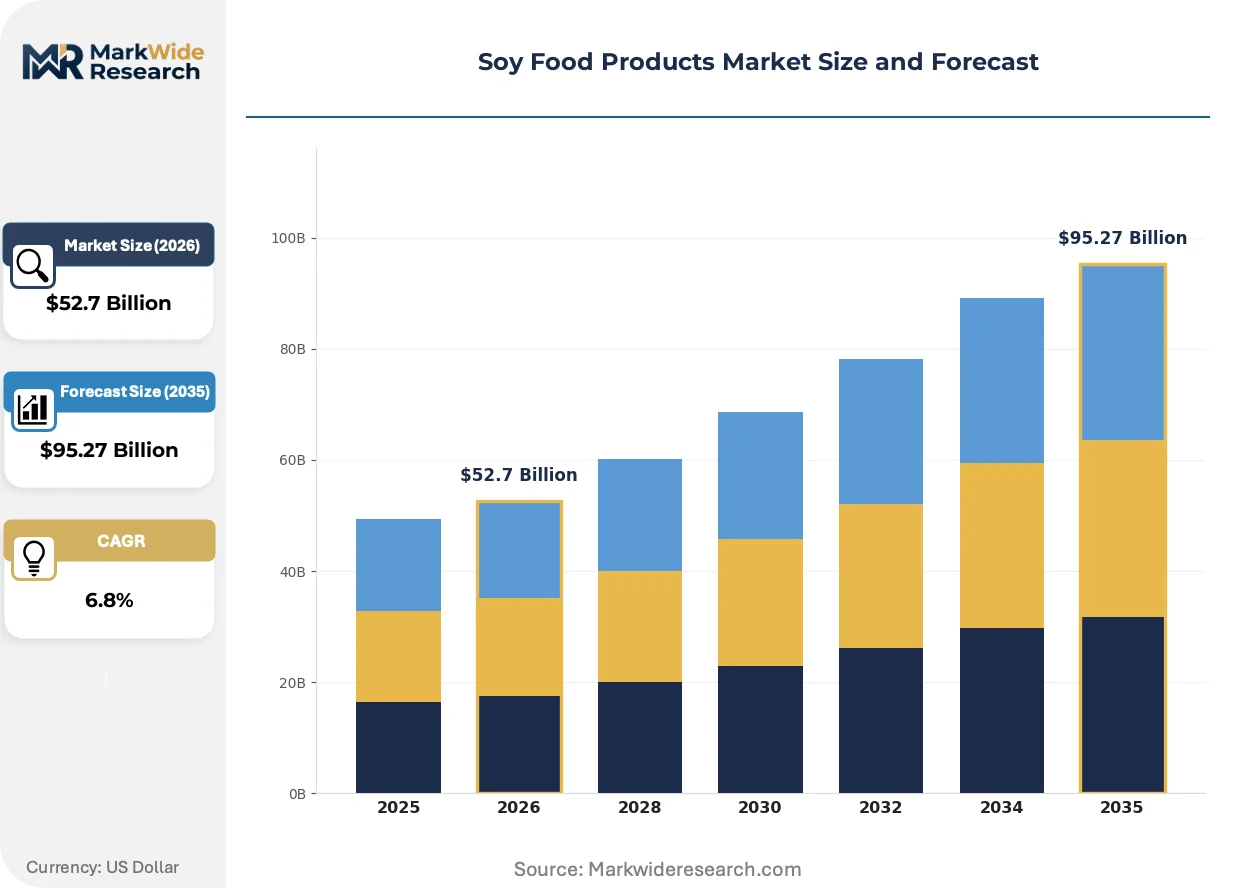
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Milk, Tofu, Tempeh, Edamame End Use: Household, Foodservice, Industrial, Nutraceuticals Form: Liquid, Solid, Powder, Granule Application: Baking, Snacks, Soups, Meat Alternatives |
| Companies Covered | Danone S.A., Vitasoy International Holdings, Nestlé S.A., Unilever PLC, Conagra Brands Inc., Archer Daniels Midland, Cargill, House Foods America Holding, Hain Celestial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Food Products Market Emerging Trajectories
Processing technology convergence and regulatory science advancement are simultaneously expanding product format possibilities while tightening substantiation requirements for health-positioned offerings.
Precision fermentation of soy protein isolates is decomposing the traditional commodity hierarchy between commodity soy meal and high-value specialty proteins. Biotechnology firms and ingredient majors are deploying recombinant strain platforms to produce customized protein fractions with enhanced functional properties for meat analog applications. This capability is compressing price premiums between industrial-grade and food-grade isolates, forcing legacy processors to defend margin through backward integration into strain development or captive organic soybean supply.
EFSA's evolving novel food authorization framework for precision-fermented ingredients is extending safety assessment timelines for European market entry. The regulation requires comprehensive toxicological and allergenicity dossiers that smaller biotechnology entrants struggle to assemble without partnership capital. Fermented soy protein innovators are responding by prioritizing US FDA GRAS self-determination pathways first, sequencing European submissions behind commercial proof points.
Certification-driven procurement is restructuring buyer-supplier contracting in foodservice channels. Large restaurant chains are mandating third-verified non-GMO and organic soy documentation as a condition of vendor qualification, displacing spot-market commodity sourcing. This pattern is most visible in North American and Western European contract manufacturing agreements, where sustainability scorecard integration now precedes price negotiation in RFP workflows.
Soy Food Products Market Segmentation
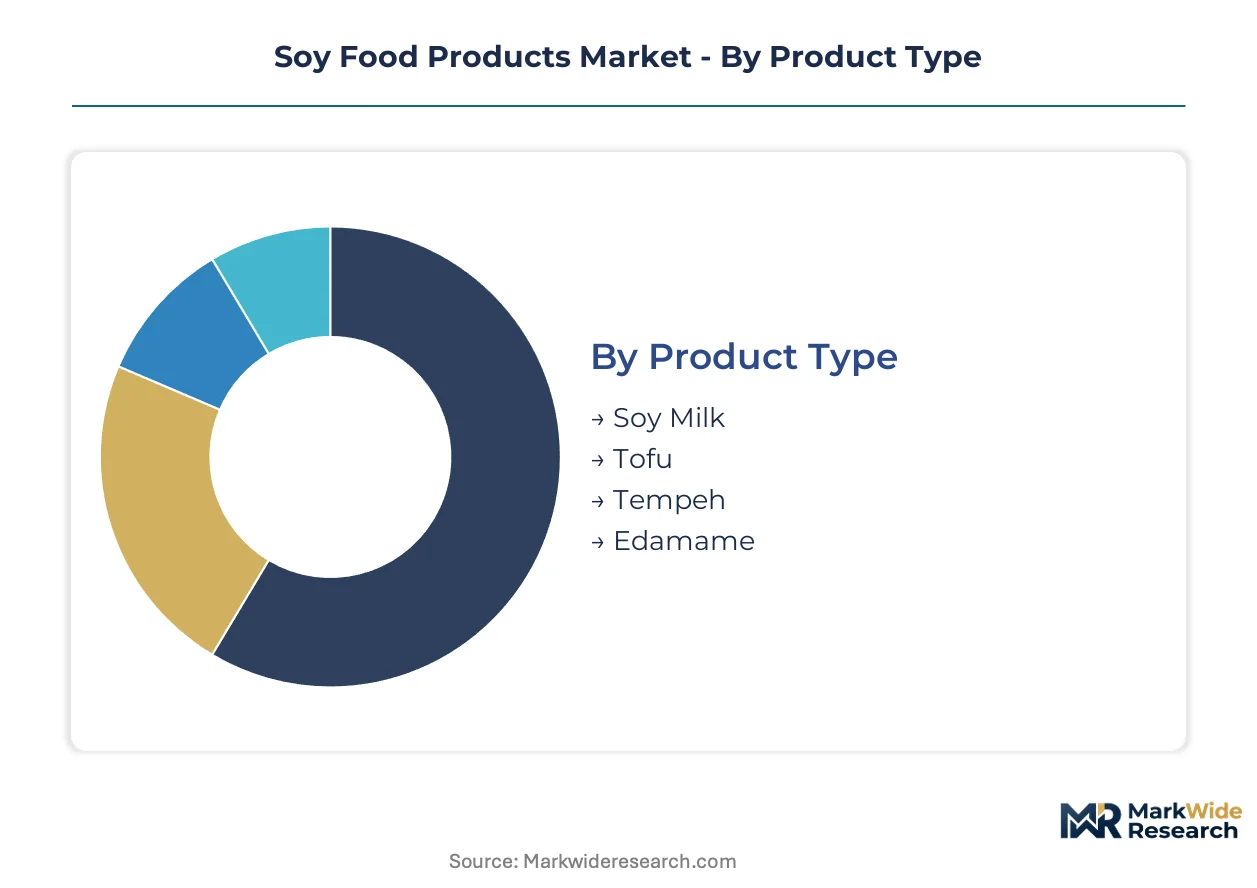
Soy food products fragment across four functional dimensions that determine pricing power and channel access. Product type and form dictate cold-chain requirements, while end use and application shape formulation specifications and regulatory exposure.
Product Type:
Soy milk faces the most intense substitution pressure from oat and almond alternatives in refrigerated retail, while tempeh and edamame defend position through protein density differentiation.
- Soy Milk:Standardized beverage with protein isolates achieving PDCAAS scores near animal equivalence. Demand concentrates in North American and European retail channels where barista-grade formulations command premium placement against oat competitors.
- Tofu:Coagulated curd with moisture content ranging from silken to extra-firm grades. East Asian household consumption anchors volume, while Western foodservice adoption drives specialty organic premiums.
- Tempeh:Fermented whole-bean cake with intact fiber and enhanced bioavailability. Indonesian traditional markets sustain baseline production; Western plant-based meat alternatives absorb expanding export volumes.
- Edamame:Immature whole soybeans harvested pre-hardening for direct consumption. Frozen retail and appetizer-menu placement in US and Japanese foodservice channels dominate offtake.
Soy milk retains volume leadership; tempeh holds the steepest expansion curve.
End Use:
Cost tier stratification separates commodity bulk supply from certified organic and clinical-grade specifications, with nutraceuticals commanding the highest purity premiums.
- Household:Direct retail purchase for home preparation. Supermarket and e-commerce channels in Japan, South Korea, and the United States concentrate demand for shelf-stable and refrigerated formats.
- Foodservice:Restaurant, café, and institutional procurement. Quick-service chains in North America are embedding soy-based meat alternatives into permanent menu architecture, requiring textured protein isolates with standardized hydration ratios.
- Industrial:Ingredient supply to processed food manufacturers. Bakery and confectionery formulators in Europe leverage soy lecithin and protein concentrates for emulsification and fortification.
- Nutraceuticals:Clinical nutrition, sports supplements, and functional foods. Powder isolates with documented isoflavone content penetrate enteral feeding and performance nutrition applications under FDA and EFSA health claim frameworks.
Foodservice is gaining share fastest; nutraceuticals maintain the widest margin spreads.
Form:
Application requirements drive format selection, with liquid and powder capturing divergent margin pools through distribution infrastructure intensity.
- Liquid:Ready-to-consume beverages and cooking bases. Refrigerated distribution in Southeast Asian urban centers enables fresh soy milk penetration previously limited by cold-chain gaps.
- Solid:Block, cake, and whole-bean presentations. Tofu and tempeh blocks dominate East Asian wet-market retail and Western specialty grocery placement.
- Powder:Dehydrated isolates and concentrates for reconstitution. Sports nutrition and clinical feeding applications in the United States and Europe absorb high-purity spray-dried proteins.
- Granule:Textured vegetable protein for hydration and restructuring. Meat alternative manufacturers in Germany and the Netherlands utilize extruded granules for burger and sausage analog production.
Liquid retains volume leadership; powder holds the steepest expansion curve.
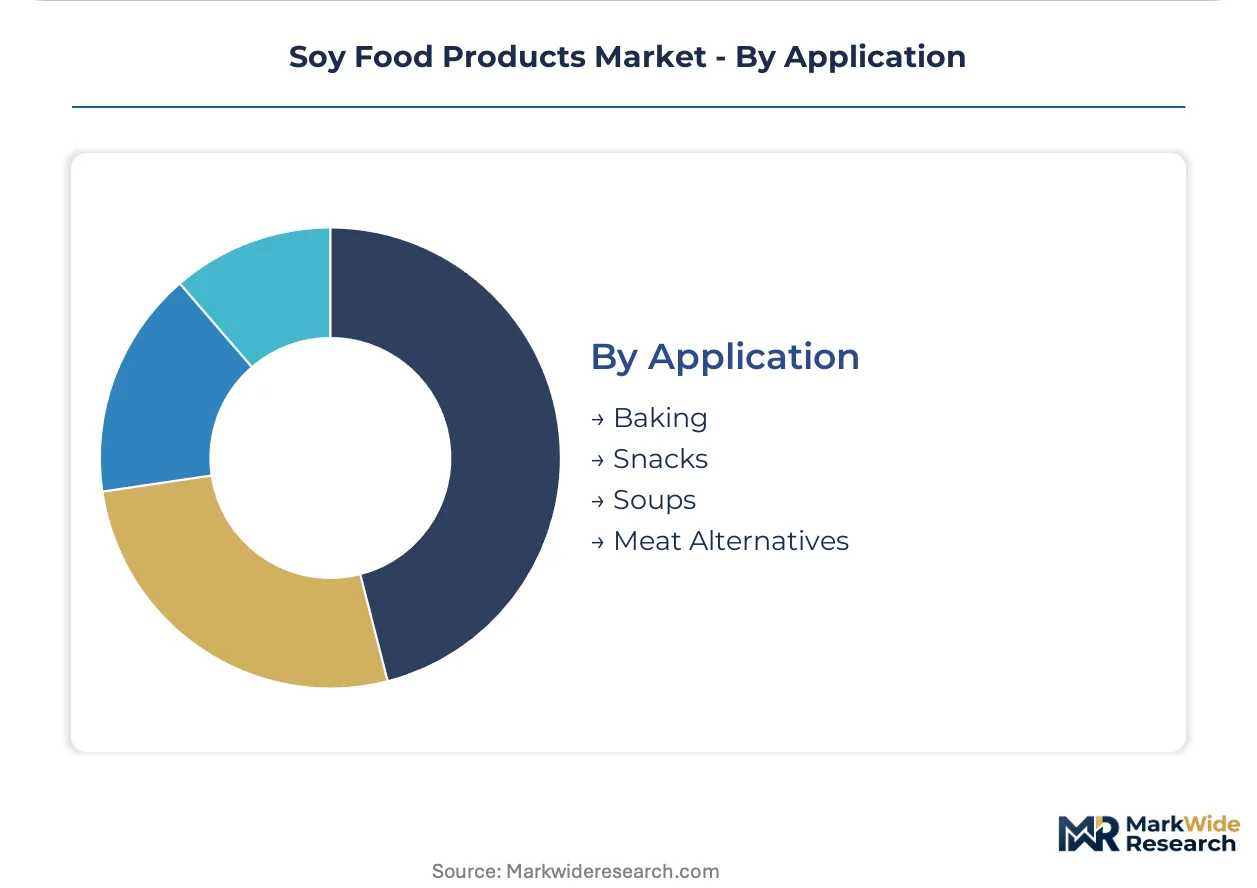
Application:
Customer type segmentation separates commodity ingredient supply from branded finished goods, with meat alternatives attracting the most concentrated R&D investment.
- Baking:Soy flour and lecithin incorporation for moisture retention and emulsification. European artisan and industrial bakeries utilize defatted soy flour for protein fortification and crumb structure modification.
- Snacks:Roasted soy nuts, chips, and extruded puffs. Health-positioned retail brands in the United States and Japan target protein-seeking consumers with single-serve packaging.
- Soups:Miso, broth bases, and textured inclusions. Traditional Japanese and Korean household consumption sustains fermented paste demand; Western ready-meal manufacturers adopt soy protein for cream-style texture.
- Meat Alternatives:Center-plate protein replacements utilizing textured isolates. Foodservice operators across North America and Western Europe are reformulating permanent menu items around soy-based analogs, creating sustained offtake contracts for specialized extrusion capacity.
Meat alternatives are climbing the fastest; baking maintains the most stable demand base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in processed soy derivatives are redirecting investment toward regional processing hubs. Brazil and the United States dominate raw soybean origination, while East Asian markets absorb the highest per-capita volumes of finished soy foods.
United States
Foodservice operators in Chicago and Los Angeles are embedding soy-based meat alternatives into permanent quick-service menus. The FDA's updated soy protein health claim framework permits cardiovascular benefit labeling on retail soy milk. Archer Daniels Midland operates extensive crushing and isolate production facilities in Decatur, Illinois, supplying textured proteins to domestic meat analog manufacturers.
China
Traditional tofu consumption in Shanghai and Beijing household markets persists alongside surging demand for packaged soy milk among urban millennials. SAMR enforces GB standards for soy beverage labeling and additive thresholds that directly shape import access rules. The Yangtze River Delta cluster around Suzhou and Hangzhou concentrates fermented soy paste and specialty protein manufacturing capacity.
Japan
Miso and natto consumption in Tokyo and Osaka maintains baseline demand for fermented soy formats while convenience-store soy milk trials capture younger demographics. METI oversees food labeling standards that govern isoflavone content declarations on functional positioning. The Kansai industrial corridor anchors traditional shoyu and specialty fermented soy protein production for domestic and export markets.
Germany
Meat alternative startups in Berlin and Cologne are contracting for extruded soy protein isolates to supply European retail and foodservice channels. EFSA's novel food authorization pathways extend timelines for fermented soy protein market entry. The Rhine-Ruhr manufacturing belt hosts specialized extrusion capacity serving plant-based meat analog producers across Western Europe.
Brazil
Domestic soy food processing in São Paulo and Curitiba is expanding beyond commodity export orientation toward finished consumer goods. The national agricultural regulator enforces traceability requirements for non-GMO and organic soybean certification tiers. The Paraná industrial corridor is developing crushing and isolate capacity to capture value-added processing margins previously realized in import markets.
Soy Food Products Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and channel access dimensions. The vendor base stratifies between multinational food conglomerates with refrigerated distribution infrastructure and regional specialists with deep traditional format expertise. Three archetypes dominate: dairy-alternative portfolio extenders leveraging existing cold-chain assets, Asian market incumbents with fermented product heritage, and ingredient majors with backward integration into soybean origination. Competitive moves concentrate on M&A to acquire precision fermentation capabilities and strategic partnerships to secure certified organic soybean supply.
Within the multinational tier, Danone S.A. and Nestlé S.A. exemplify dairy-alternative portfolio extension strategies, while Vitasoy International Holdings anchors the Asia-centric traditional formats position. These three occupy distinct competitive spaces—European refrigerated distribution dominance, global R&D-intensive specialized nutrition, and deep Asian retail channel control—without direct overlap in core geographic strongholds.
| Leading Market Players |
|---|
| Danone S.A. |
| Vitasoy International Holdings |
| Nestlé S.A. |
| Unilever PLC |
| Conagra Brands Inc. |
| Archer Daniels Midland |
| Cargill |
| House Foods America Holding |
| Hain Celestial |
| Others |
Supply Flow & Price Mechanics
Crushing capacity utilization at 85 percent in the US Midwest and Paraná corridor simultaneously compresses spot soybean meal premiums and elevates isolate price floors. This scale concentration rewards backward-integrated multinationals with captive origination while squeezing toll processors exposed to Brazilian export parity volatility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with three-tier pricing stratification across premium organic, verified non-GMO, and commodity commodity grades. Price differentiation hinges on certification tier and volume scale, with organic premiums widening as Chinese import demand absorbs available supply. Pricing pressure stems from oat and almond milk substitution in North American refrigerated retail, compressing soy milk margins. Foodservice operators show least price sensitivity due to menu reformulation lock-in, while private-label retail buyers drive hardest bargain negotiations.
Supply Chain Analysis
Strategic stockpile preferences dominate among Asian fermented soy processors, while just-in-time inventory governs North American extruded protein supply to meat analog manufacturers. Raw material flows concentrate in Brazil, the United States, and Argentina, with formulated product manufacturing anchored in China, Germany, and Japan. Dependency structures rest on non-GMO soybean premiums, organic certification documentation, and specialized extrusion equipment. Single-source vulnerability concentrates in Brazilian origination corridors exposed to climate-driven harvest variability. Distribution runs through refrigerated cold-chain networks in urban Southeast Asia and ambient shelf-stable channels in European retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in clinical nutrition and precision-fermented protein tiers, where diverging regulatory approval timelines between FDA and EFSA create arbitrage windows for nimble formulators.
For Market Incumbents: Shield refrigerated distribution advantages by certifying additional organic processing lines before Chinese SAMR tightens import documentation requirements. Deepen backward integration into Paraná and Illinois soybean origination to offset Brazilian export policy shifts. Priority defensive moves center on acquiring precision fermentation bioreactor capacity and locking multi-year organic supply contracts. For New Entrants and Emerging Players: White-space concentration in clinical-grade powder isolates for enteral feeding applications reveals where incumbent R&D pipelines lag. Target pharmaceutical channel partnerships before nutraceutical consolidation accelerates. Go-to-market execution should leverage FDA GRAS self-determination pathways to compress time-to-revenue versus EFSA-bound competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among foodservice contract manufacturers with multi-year textured protein supply agreements. Long-term viability across the projection horizon favors targets with demonstrated strain optimization capabilities and existing SAMR registration dossiers. Acquisition focus should center on mid-cap precision fermentation specialists. Signal to monitor: EFSA novel food authorization backlog clearance rates as inflection indicator for European market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Bioreactor deployment unlocks customized protein fractions for meat analog texture optimization under FDA oversight. |
| Organic Certification Expansion | Third-party verification secures vendor qualification with North American quick-service chains mandating documentation. |
| Clinical Nutrition Partnership | Enteral feeding channel access elevates powder isolate margins through pharmaceutical procurement frameworks. |
| Cold-Chain Infrastructure Investment | Southeast Asian urban distribution nodes enable fresh tofu penetration previously limited by logistics gaps. |
| Backward Integration into Origination | Captive Brazilian and US Midwest soybean supply buffers against export policy volatility and weather shocks. |
Methodological Framework
Operator-level perspectives from soy protein procurement managers, foodservice menu development directors, and fermented product R&D leads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA GRAS notifications, EFSA novel food submissions, and Chinese SAMR GB standard updates. Trade flow analysis drew from customs records and crushing margin reports. Bottom-up volume modeling triangulated against top-down macroeconomic demand elasticity estimates.
Sensitivity analysis tested forecast robustness across protein substitution scenarios and regulatory approval timeline variations. Segmentation dimensions modeled include product form, certification tier, end-use channel, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for menu reformulation acceleration and clinical nutrition penetration rates. Forecast inputs incorporated soybean origination cost curves and cold-chain infrastructure buildout schedules.
Forecasts assume regulatory continuity in FDA health claim frameworks and EFSA novel food pathways; material policy shifts would require re-modeling. Specific risk factors include Brazilian export tax volatility, SAMR labeling requirement changes, and precision fermentation strain approval delays. Revision becomes warranted when foodservice contract cancellation rates or organic soybean premium spreads cross historical threshold bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Singapore Plant-Based Food and Beverages Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
United Kingdom Tofu Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Global Textured Vegetable Protein Market
Plant Based Food
Plant-Based Fish Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Europe Plant-Based Food and Beverage Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Flax-Based Protein Market
Plant Based Food
India Pea Protein Market
Plant Based Food
Black Rice Protein Market