
 Yard Crane Market | 2026-2036
Yard Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Yard Crane Market Analytics
ISO 4301-1 crane classification is unwinding competitive barriers for new entrants in automated terminal equipment. Konecranes leverages its port automation software stack to anchor long-term service contracts. Liebherr sustains engineering intensity through in-house steel fabrication and custom boom configurations. ZPMC dominates manufacturing scale, shipping complete crane assemblies from its Changxing Island production base.
Yard cranes are rail-mounted or rubber-tired portal structures engineered to lift intermodal containers across stacking yards, typically spanning 30-50 meters with lifting heights exceeding 18 meters and rated capacities from 40 to 65 tons. These machines serve as the critical velocity constraint in container terminal throughput, translating vessel unloading rates into organized storage density. Gantry cranes command the largest installed base among product types, while electric drive technology captures the fastest replacement cycle as diesel emission restrictions tighten at European and Chinese ports. The heavy industry end-user segment presents concentrated margin pools due to custom engineering requirements and extended procurement timelines.
FERC guidelines on port electrification infrastructure in the United States, coupled with EU Green Deal emission benchmarks for harbor equipment and China's GB/T 31052 safety standards, collectively mandate powertrain transitions and telemetry integration. Terminal operators now face capital allocation decisions between retrofitting existing fleets versus specifying fully electric architectures in new orders. Stakeholders must monitor how battery energy density improvements and shore power availability reshape total cost of ownership calculations before committing to platform transitions.
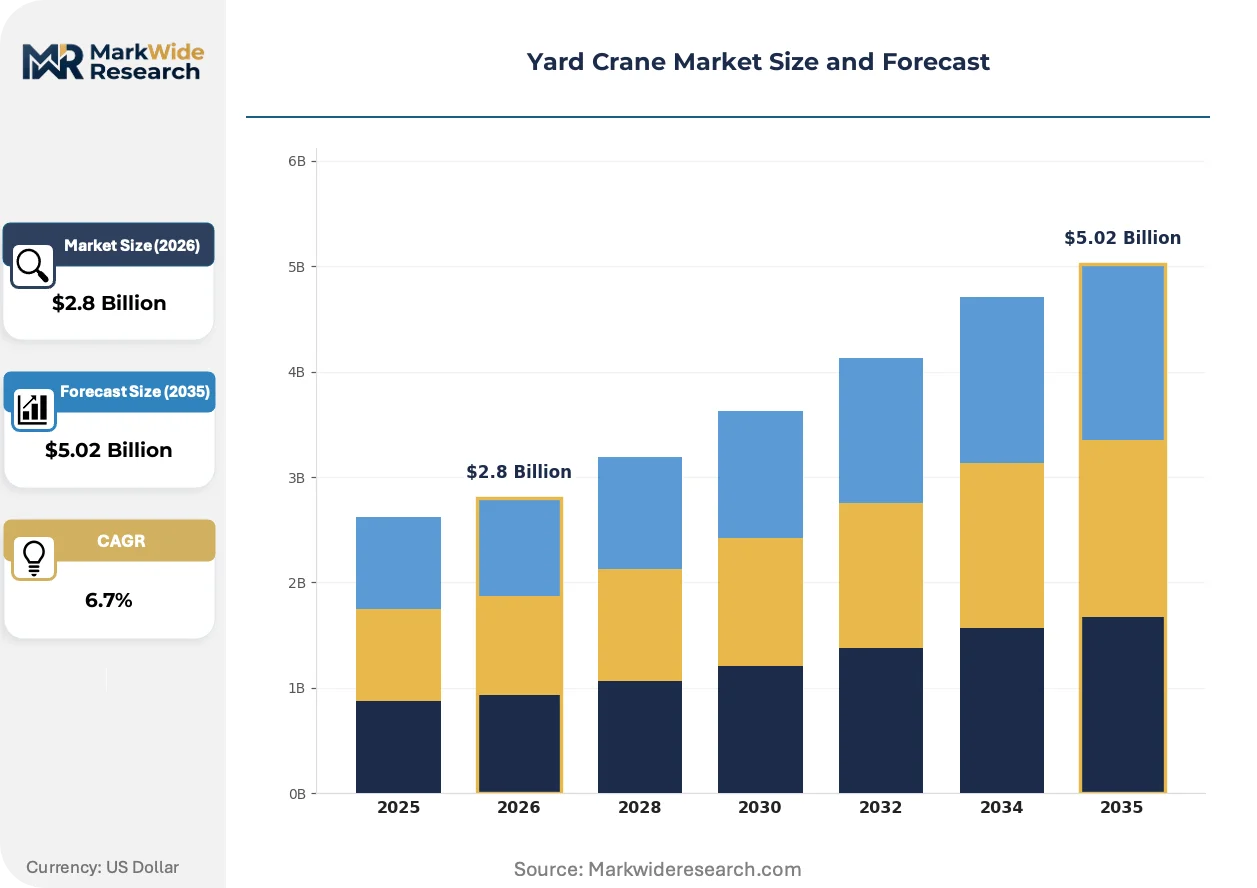
Market Dynamics
Port electrification mandates are compressing equipment replacement cycles as terminal operators face simultaneous pressure from emission restrictions and transshipment volume expansion in Southeast Asian logistics corridors.
Growth Catalysts
- EU Green Deal benchmarks:Harbor equipment emission standards in Rotterdam and Hamburg are forcing terminal operators to accelerate fleet turnover toward electric drive systems.
- Vietnam's Cai Mep-Thi Vai expansion:Transshipment volume growth in this port cluster is triggering concentrated procurement of rubber-tired gantry cranes with higher stacking density.
- ISO 4301-1 classification:Standardized crane duty cycles are reducing engineering validation costs for automated terminal equipment vendors entering port automation contracts.
Market Restraints
- Steel price volatility:Boom and frame fabrication costs fluctuate with alloy input markets, compressing margin predictability for custom-engineered heavy lift configurations.
- Changxing Island supply concentration:Complete crane assembly exports from this single manufacturing base create geopolitical logistics risk for global terminal procurement timelines.
- Battery energy density limits:Current lithium-ion chemistry constraints operational uptime for fully electric rubber-tired gantries without shore power infrastructure.
Strategic Opportunities
- Indonesia's New Priok terminal development:Greenfield port construction in Jakarta's expanded harbor zone allows direct specification of electric-native crane architectures without retrofit burden.
- Telemetry-integrated service contracts:Predictive maintenance platforms bundled with equipment sales are creating recurring revenue streams that decouple vendor economics from unit shipment cycles.
- FERC port electrification guidelines:US infrastructure incentives for shore power installation are opening retrofit markets for existing diesel fleets in California and Pacific Northwest terminals.
Industry Challenges
- Automation software integration:Terminal operating system compatibility gaps between legacy equipment and new crane management platforms extend commissioning timelines.
- GB/T 31052 certification complexity:China's safety standard compliance documentation requirements create approval bottlenecks for European and Korean manufacturers without local testing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yard Crane Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Cranes, Tower Cranes, Gantry Cranes, Fixed Cranes End User: Construction, Shipping, Manufacturing, Heavy Industry Technology: Hydraulic, Electric, Diesel, Hybrid Application: Loading, Unloading, Material Handling, Heavy Lifting |
| Companies Covered | ZPMC, Konecranes, Liebherr, Cargotec Corporation, SANY Group, Terex Corporation, XCMG Group, Kato Works Co., Ltd., ANDRITZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yard Crane Market Evolving Landscape
Electrification is rewriting equipment specification criteria while automation software stacks are becoming the primary vendor differentiation mechanism beyond mechanical lifting performance.
High-voltage battery-electric powertrains are supplanting diesel-electric hybrid systems in new rubber-tired gantry crane orders. Mediterranean and North European terminal operators are specifying 600kWh+ battery packs with opportunity charging at stack ends. This shift is compressing the installed base of legacy diesel fleets faster than residual value depreciation schedules anticipated.
China's GB standards for crane safety and emissions compliance are mandating telemetry integration and real-time load monitoring on all new installations. Manufacturers must now certify remote diagnostic capability as a condition of type approval. Domestic port operators in Ningbo and Qingdao are responding by pre-qualifying vendors based on data platform architecture rather than mechanical specifications alone.
Terminal operators are unbundling crane procurement from long-term maintenance agreements and selecting automation software providers independently of equipment OEMs. This disintermediation is fragmenting vendor relationships in Singapore and Rotterdam, where port authorities now run competitive tenders for crane management systems separate from hardware supply contracts.
Yard Crane Market Segmentation
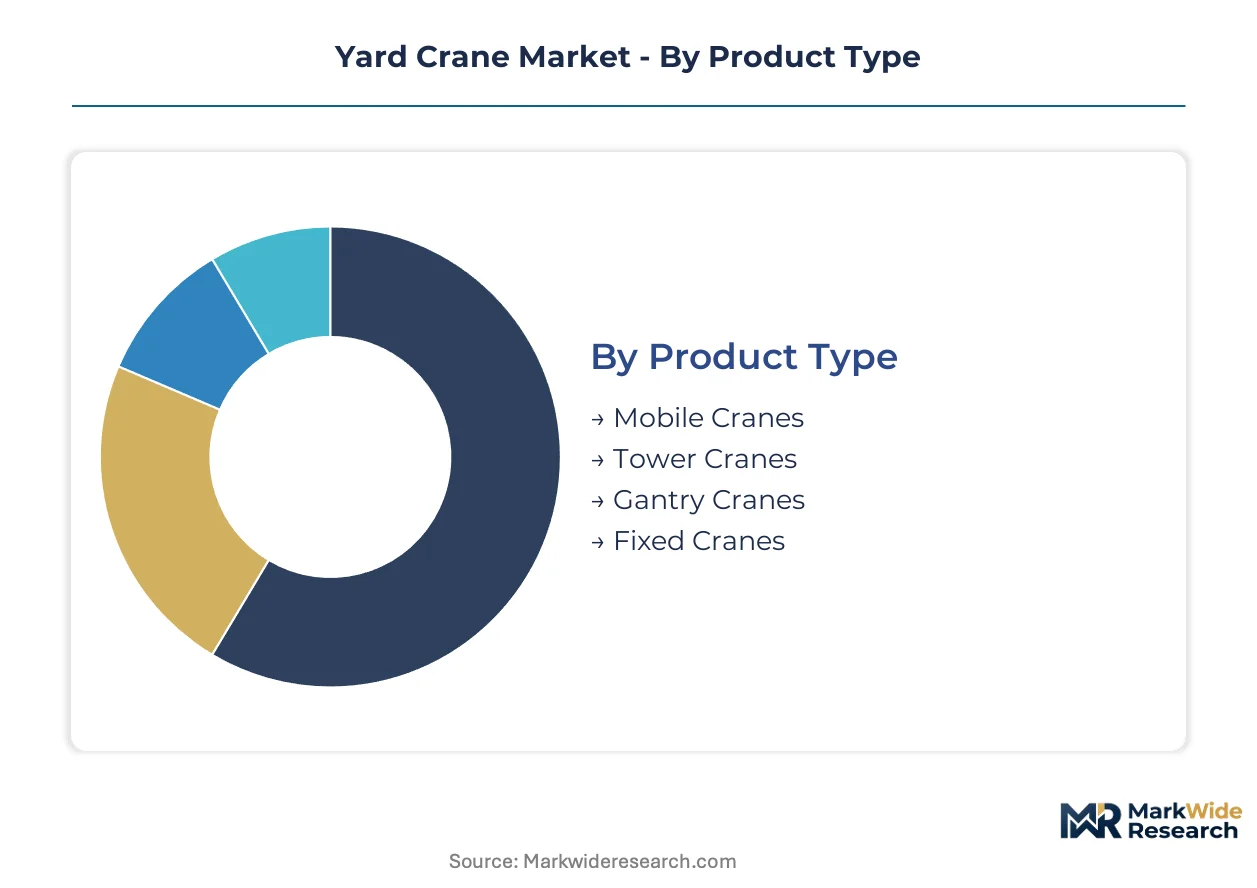
Yard crane procurement decisions split across mechanical configuration, powertrain technology, and operational intensity. Terminal operators weight stacking density requirements against electrification mandates when selecting equipment categories. Each segment carries distinct margin profiles tied to engineering complexity and regulatory compliance burdens.
Product Type:
Gantry cranes command the deepest margin pools due to custom span engineering and port-specific foundation requirements. Mobile configurations compete on volume with standardized production runs.
- Gantry Cranes:Rail-mounted portal structures span 30-50 meters with lifting heights exceeding 18 meters. Vietnam's Cai Mep-Thi Vai port cluster is driving concentrated orders for rubber-tired variants as transshipment volumes expand and terminal operators pursue higher stacking density.
- Mobile Cranes:Self-propelled wheeled configurations relocate across terminal yards without fixed rail infrastructure. European port electrification timelines are compressing replacement cycles for diesel-powered mobile fleets ahead of residual value depreciation schedules.
- Tower Cranes:Vertical mast structures with luffing jib configurations serve high-density container storage applications. Fixed foundation requirements limit deployment flexibility.
- Fixed Cranes:Permanent installations with dedicated structural support anchor high-throughput vessel loading operations. Chinese GB standards mandate telemetry integration for all new fixed crane approvals.
Gantry cranes hold installed capacity. Mobile cranes are rotating up the share rankings.
End User:
Heavy industry applications generate premium pricing through extended procurement timelines and custom engineering specifications. Construction demand fluctuates with infrastructure investment cycles.
- Heavy Industry:Steel fabrication, shipbuilding, and energy infrastructure projects require specialized boom configurations and extended duty cycles. China's Changxing Island production base supplies complete crane assemblies for domestic heavy industry modernization programs.
- Shipping:Container terminal operators specify equipment matched to vessel size classes and transshipment throughput targets. Southeast Asian logistics corridors are triggering fleet procurement as port automation accelerates.
- Construction:Civil engineering and building projects deploy cranes for temporary material placement. Project-based demand creates irregular order patterns.
- Manufacturing:Factory yards and assembly facilities utilize cranes for component movement and logistics staging. Standardized specifications dominate this segment.
Shipping holds installed capacity. Heavy industry is rotating up the share rankings.
Technology:
Electric powertrains are climbing the fastest as emission restrictions reshape procurement criteria. Diesel systems face compressed residual values in regulated port zones.
- Electric:High-voltage battery-electric systems with 600kWh+ packs and opportunity charging infrastructure. Mediterranean and North European terminal operators are specifying native electric architectures as EU Green Deal benchmarks tighten harbor equipment standards.
- Hybrid:Diesel-electric configurations with regenerative braking and selective engine downsizing. Transitional technology serving ports with incomplete shore power infrastructure.
- Hydraulic:Fluid power transmission systems for precision load control in heavy lifting applications. Mature technology with established maintenance protocols.
- Diesel:Conventional internal combustion powertrains with Tier 4 emission compliance. FERC port electrification guidelines in the United States are accelerating retrofit decisions for existing diesel fleets.
Diesel holds installed capacity. Electric is rotating up the share rankings.
Application:
Material handling operations concentrate volume demand across repetitive container movements. Heavy lifting commands technical premiums for specialized engineering.
- Material Handling:Repetitive container stacking and retrieval across terminal yards. Automation software integration is becoming the primary vendor selection criterion beyond mechanical specifications.
- Loading:Vessel-to-shore container transfer operations synchronized with quay crane cycles. Throughput velocity constraints drive equipment specification priorities.
- Unloading:Shore-to-yard container distribution following vessel discharge sequences. Terminal operating system compatibility requirements extend commissioning timelines for new installations.
- Heavy Lifting:Project cargo and oversized load operations exceeding standard container dimensions. Custom boom configurations and reinforced frame structures generate engineering-intensive margin pools.
Material handling holds installed capacity. Heavy lifting is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container terminal operators in Vietnam, China, and Germany are driving equipment procurement as port electrification mandates compress replacement cycles across three distinct regulatory environments.
China
GB/T 31052 safety standards and dual carbon goals are reshaping manufacturer design priorities for domestic port operators. MIIT certification requirements now mandate telemetry integration and real-time load monitoring as conditions of type approval. Ningbo and Qingdao port authorities are pre-qualifying vendors based on data platform architecture rather than mechanical specifications alone.
Vietnam
Cai Mep-Thi Vai port cluster expansion is triggering concentrated procurement of rubber-tired gantry cranes with higher stacking density configurations. The government's logistics corridor development program is accelerating transshipment volume growth through 2030. Ho Chi Minh City terminal operators are modernizing fleets to capture regional transshipment traffic shifting from Singapore.
Germany
Hamburg and Bremerhaven terminal operators face EU Green Deal harbor equipment emission standards forcing accelerated fleet turnover toward electric drive systems. The national hydrogen strategy is creating pilot programs for fuel-cell auxiliary power in heavy port equipment. Port of Hamburg is testing 600kWh+ battery packs with opportunity charging infrastructure at stack ends.
United States
FERC port electrification guidelines and California Air Resources Board emission restrictions are accelerating retrofit decisions for existing diesel fleets. Pacific Northwest terminals are accessing federal infrastructure incentives for shore power installation. Los Angeles-Long Beach port complex is specifying native electric architectures in new terminal construction to avoid retrofit burden.
Indonesia
New Priok terminal development in Jakarta's expanded harbor zone allows direct specification of electric-native crane architectures without retrofit constraints. The national maritime connectivity program is funding greenfield port construction with integrated electrification infrastructure. Surabaya and Belawan terminal operators are studying procurement models from Vietnam's Cai Mep-Thi Vai cluster.
Yard Crane Market Competitive Landscape
Player mix skews toward integrated port automation specialists with captive manufacturing bases and regional engineering fabricators serving custom heavy-lift requirements. Market structure concentrates around three strategic archetypes: scale-driven assembly exporters, software-anchored service contract vendors, and in-house steel fabrication specialists. Dominant competitive moves include backward integration into boom and frame production and technology licensing for crane management platforms.
Within the scale-driven assembly tier, ZPMC exemplifies manufacturing concentration through its Changxing Island production base. Konecranes and Liebherr occupy positions as integrated automation specialists combining mechanical fabrication with software stack development. These three anchors represent distinct competitive vectors: ZPMC through complete crane export scale, Konecranes through port automation software anchoring long-term service contracts, and Liebherr through in-house steel fabrication and custom boom engineering intensity.
| Leading Market Players |
|---|
| ZPMC |
| Konecranes |
| Liebherr |
| Cargotec Corporation |
| SANY Group |
| Terex Corporation |
| XCMG Group |
| Kato Works Co., Ltd. |
| ANDRITZ |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with steel price indexation lock in boom fabrication capacity for terminal operators while exposing procurement teams to alloy market volatility. These agreements tie yard crane deliveries to Shanghai Futures Exchange benchmarks, compressing margin buffers for European and Korean manufacturers without backward integration into in-house steel production.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate heavy lift equipment procurement, anchoring final pricing to nickel and high-strength alloy benchmarks. Price differentiation rests on GB/T 31052 certification tier and telemetry platform sophistication, with Chinese port operators paying premiums for real-time load monitoring integration. Cost compression in standard gantry configurations is intensifying because ZPMC's Changxing Island scale advantages compress competitor margins. Heavy industry buyers exhibit lowest price sensitivity due to custom boom engineering requirements, while construction segment procurement teams drive aggressive vendor consolidation.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and Red Sea container availability constraints are extending delivery timelines for complete crane assemblies shipped from Changxing Island. Manufacturing gravity centers on China, Germany, and Finland, with boom fabrication drawing from Swedish specialty steel and South Korean high-tensile plate. Single-source vulnerability concentrates in ZPMC's integrated production base, where geopolitical disruption would cascade through global terminal procurement schedules. Distribution runs through OEM-direct contracts with port authorities, bypassing traditional equipment dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendor fragmentation creates entry niches as terminal operators unbundle automation software from hardware procurement. Port authorities in Rotterdam and Singapore now tender crane management systems independently, fragmenting incumbent supplier relationships.
For Market Incumbents: Compound service contract attachment rates by embedding predictive maintenance platforms within new equipment sales. Konecranes' software-anchored model demonstrates how telemetry integration defends against disintermediation threats from independent automation vendors. Backward integration into battery pack assembly secures margin pools as electrification mandates accelerate fleet turnover cycles. For New Entrants and Emerging Players: Lead with electric-native architectures targeting Indonesia's New Priok greenfield development, where absence of retrofit constraints enables clean-sheet specification. Vietnam's Cai Mep-Thi Vai expansion presents the most penetrable geography for rubber-tired gantry orders with higher stacking density configurations. Position through port authority software tenders rather than OEM hardware partnerships to bypass established vendor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale automation specialists with captive telemetry platforms and regional service infrastructure. Long-term viability across the analysis window hinges on crane management software recurring revenue rather than unit shipment economics. Watch for EU Green Deal enforcement acceleration at Hamburg and Bremerhaven as inflection signal for electric fleet replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Assembly | Captures margin pools as EU Green Deal mandates accelerate port electrification timelines. |
| Telemetry Platform Licensing | Enables recurring revenue streams decoupled from yard crane unit shipment cycles. |
| Greenfield Port Partnership | Indonesia's New Priok development allows electric-native specification without retrofit burden. |
| Steel Fabrication Capacity Expansion | Reduces exposure to Shanghai Futures Exchange price volatility for boom production. |
| GB/T 31052 Certification Investment | Unlocks access to Ningbo and Qingdao port authority pre-qualification lists. |
Research Methodology
Operator-level perspectives from terminal engineering directors, port authority procurement leads, and aftermarket service managers anchored the qualitative base. Primary fieldwork combined structured interviews with maintenance supervisors at Cai Mep-Thi Vai and Hamburg terminals alongside OEM sales executives at Konecranes and Liebherr. Secondary validation drew from FERC electrification filings, EU Green Deal harbor equipment benchmarks, and MIIT certification databases. Bottom-up equipment shipment tracking triangulated against top-down port capacity expansion announcements.
Sensitivity analysis tested forecast outputs against battery energy density improvement trajectories and shore power infrastructure deployment rates across the projection horizon. The analytical framework modeled segmentation across powertrain technology, mechanical configuration, end-use intensity, and regional regulatory cluster. CAGRs derived from equipment replacement cycle compression analysis and transshipment volume elasticity to port automation investment. Steel price volatility and Changxing Island supply concentration served as scenario variables.
Forecasts assume regulatory continuity in EU Green Deal enforcement, FERC port electrification guidelines, and China's GB/T 31052 safety standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Industrial Agitators Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Piles Turner Market
Construction Equipment
Global Excavators Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
Fixed Crane Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
Stud Welding Machine Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Pile Cage Welding Machine Market