
 Piles Turner Market | 2026-2036
Piles Turner Market Size, Share, and Industry Trends Forecast 2026-2036
Piles Turner Market Insights
Automation in pile-turning equipment is tilting capital allocation toward sensor-guided and remotely monitored systems. Toppy Packaging leverages European manufacturing scale to supply hydraulic turners for industrial composting lines. Black Clawson anchors North American demand through specialized aerated turners engineered for high-throughput waste management facilities. EMR USA competes on aftermarket service density across Midwest agricultural cooperatives.
A piles turner is a material-handling machine designed to invert, aerate, and homogenize bulk organic piles through rotating drum assemblies or paddle mechanisms, typically operating at throughput rates of 100–1,000 cubic meters per hour depending on pile density and moisture content. Its primary industrial purpose is to accelerate aerobic decomposition, reduce pathogen loads, and standardize compost maturity for regulatory-compliant output. Hydraulic turners dominate capital expenditure in large composting facilities where continuous operation and pile height exceeding three meters demand sustained torque output. Automated systems represent the fastest-expanding technology segment as facility operators seek labor reduction and real-time oxygen monitoring integration. Portable turners occupy a specialized niche in landscaping and mid-scale agriculture where equipment mobility between sites outweighs throughput maximization.
The EPA administers permitting under the Clean Air Act for composting operations exceeding specified volatile organic compound thresholds, while OSHA mandates confined-space protocols for enclosed turning operations. The EU F-Gas Regulation indirectly shapes equipment design by restricting refrigerants in associated aeration climate-control systems. USDA conservation programs subsidize precision composting infrastructure on certified organic farms. Stakeholders must weigh total cost of ownership against automation premiums as regulatory compliance tightens and energy costs fluctuate across operating geographies.
Market Dynamics
Automation mandates under the EU Green Deal are compressing capital deployment timelines for municipal composting operators, forcing rapid replacement of manual turning systems with sensor-integrated equipment across European waste treatment infrastructure.
Growth Catalysts
- Anaerobic Digestion Co-location:The Netherlands clusters biomass management facilities where combined composting and biogas operations demand high-throughput turning equipment. Integrated sites achieve operational density that standalone composting cannot match.
- EU F-Gas Regulation:Climate-control system redesigns for aeration equipment indirectly drive new turner procurement as facilities modernize entire processing lines to meet refrigerant restrictions.
- OSHA Confined-Space Protocols:US enforcement of worker safety standards in enclosed composting operations accelerates automated system adoption to eliminate manual exposure risks.
Market Restraints
- Hydraulic System Input Costs:Steel and precision hydraulic component prices fluctuate with energy markets, squeezing margins for turner manufacturers dependent on continuous torque engineering.
- European Manufacturing Concentration:Production of industrial-scale drum assemblies clusters in Germany and northern Italy, creating vulnerability to regional supply disruptions or logistics bottlenecks.
- Portable Turner Substitution:Mid-scale agricultural operators increasingly rent rather than purchase equipment, limiting addressable market for capital sales in landscaping segments.
Strategic Opportunities
- USDA Conservation Program Access:Certified organic farms in the US Midwest qualify for subsidized precision composting infrastructure, creating a channel for premium automated turner penetration.
- Real-Time Oxygen Monitoring Convergence:Integration of IoT sensors with turning equipment enables predictive maintenance and process optimization, commanding higher service contract values.
- Mid-Scale Agricultural Underpenetration:France's regional composting cooperatives outside major urban waste zones operate aging equipment, presenting retrofit demand for efficient portable systems.
Industry Challenges
- Electro-Hydraulic Technician Scarcity:Facilities deploying automated turners face hiring gaps for specialists capable of maintaining integrated sensor-hydraulic systems, extending downtime during failures.
- EPA Clean Air Act Permitting Timelines:Volatile organic compound threshold compliance for large composting operations requires lengthy approval processes that delay equipment commissioning and revenue realization.
- Legacy System Integration Complexity:Municipal facilities with decades-old aeration infrastructure struggle to retrofit automated turning equipment without complete line reconstruction, inflating project scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piles Turner Market |
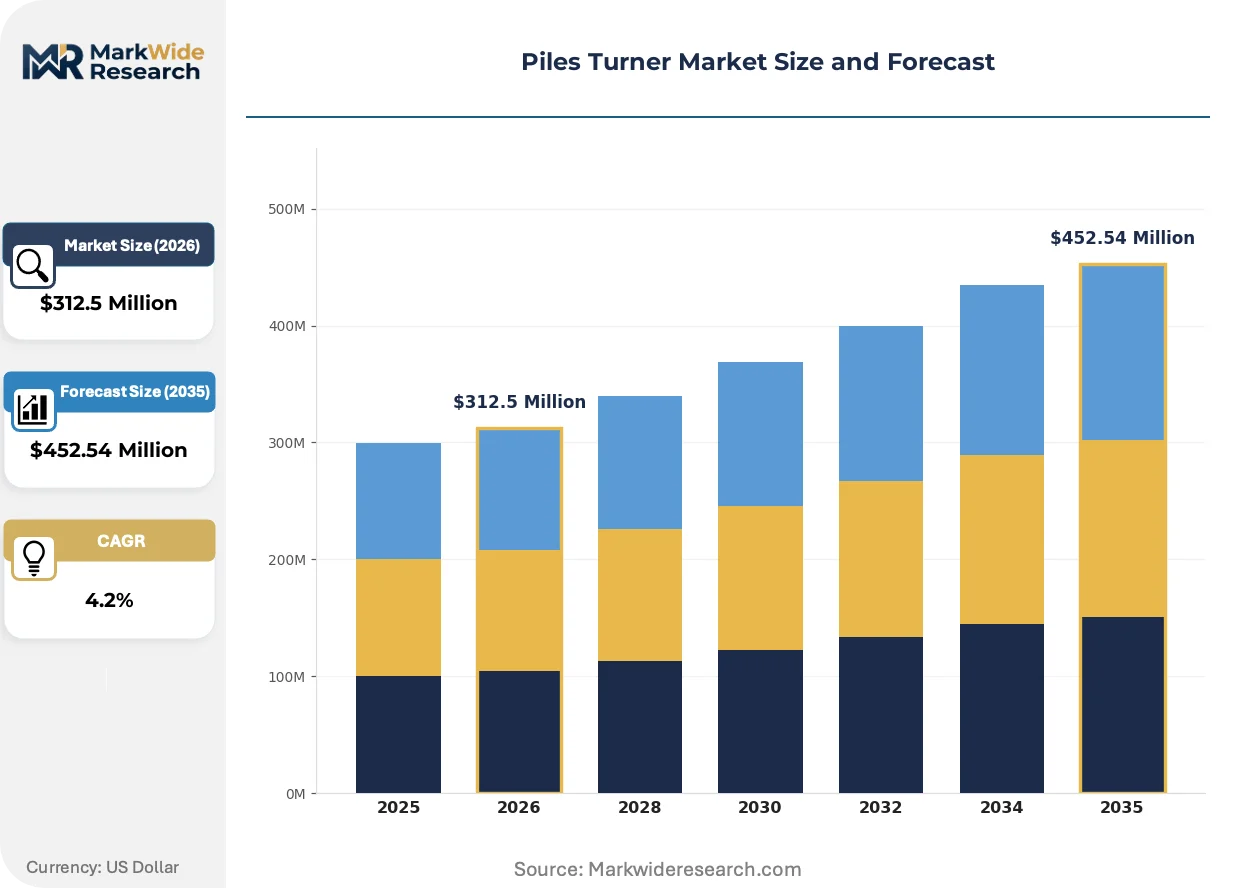
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $452.54 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Turners, Mechanical Turners, Aerated Turners, Portable Turners End User: Agriculture, Landscaping, Composting Facilities, Waste Management Application: Soil Aeration, Organic Waste Treatment, Biomass Management, Compost Production Technology: Manual Systems, Automated Systems, PTO-Driven Systems, Electric Systems |
| Companies Covered | Toppy Packaging, Black Clawson, EMR USA, Premier Paper Machinery, Neopac, VI-CART, Cremonini, Layer-Pack, Pro System, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piles Turner Market Trends and Innovations
Sensor-guided automation is collapsing the traditional labor-capital tradeoff in organic waste processing, compressing operational models that relied on manual pile management into integrated technology platforms requiring minimal on-site staffing.
Drum-mounted infrared moisture sensors paired with variable-speed paddle drives are collapsing the distinction between turning and real-time process control. German municipal facilities deploy these systems to maintain optimal aerobic conditions without manual sampling. The technology is collapsing response times for pile management from hours to minutes, eliminating the lag between condition detection and mechanical intervention.
REACH chemical compliance requirements are reshaping equipment material specifications for composting machinery sold in European markets. Manufacturers substitute traditional hydraulic fluids and coating systems with bio-based alternatives to meet substance restrictions. French and Dutch procurement authorities now embed REACH conformity into tender evaluations, filtering supplier pools before technical assessment begins.
Equipment-as-service contracting is displacing outright purchase in mid-scale agricultural segments where capital constraints outweigh throughput optimization priorities. German cooperative banks facilitate lease structures that bundle maintenance and sensor subscriptions. This financing innovation concentrates most visible in Bavaria's dairy farming regions where manure-to-compost operations expand under nutrient management regulations.
Piles Turner Market Segmentation
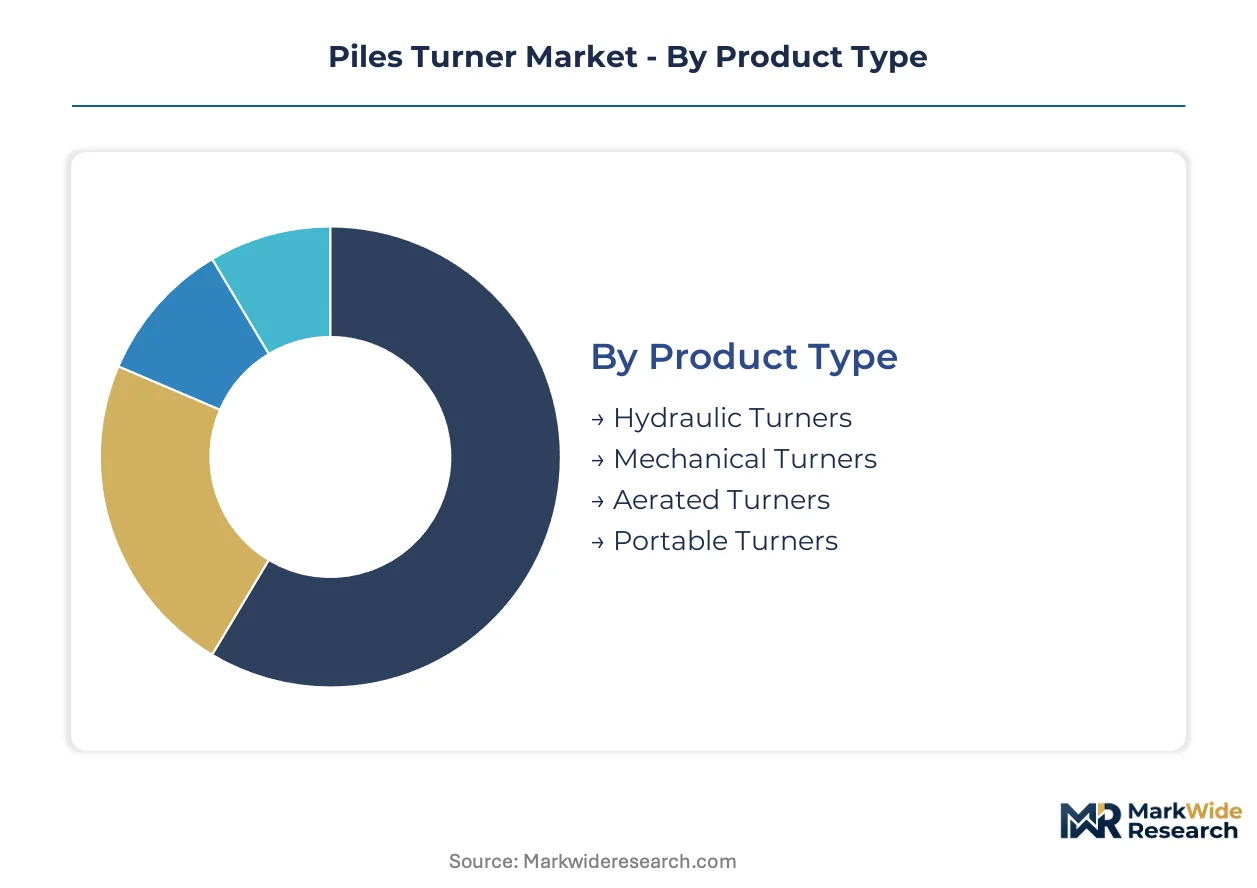
Piles turner segmentation reflects divergent capital intensity and operational scale across waste management infrastructure. Equipment specifications vary sharply between municipal composting operations demanding continuous throughput and agricultural users prioritizing equipment mobility.
Product Type:
Cost tier differentiation separates industrial-scale installations from mid-market agricultural deployments.
- Hydraulic Turners:Drum assemblies powered by high-pressure hydraulic circuits deliver sustained torque for piles exceeding three meters in height. German municipal composting facilities under EU Green Deal mandates deploy these systems for continuous operation where pile density demands mechanical force beyond electric alternatives.
- Automated Systems:Sensor-integrated turners with real-time oxygen monitoring compress labor requirements while maintaining aerobic decomposition parameters. Dutch biomass management clusters combine these with anaerobic digestion operations to achieve integrated processing density.
- Mechanical Turners:Gear-driven assemblies without hydraulic complexity serve mid-scale composting where capital constraints limit infrastructure investment.
- Aerated Turners:Equipment engineered for forced-air integration dominates North American high-throughput waste management facilities.
- Portable Turners:Compact units with trailer mounting serve landscaping contractors and regional French agricultural cooperatives requiring site-to-site mobility.
Hydraulic turners hold installed capacity. Automated systems are rotating up the share rankings.
End User:
Customer type determines procurement channel and financing structure across equipment categories.
- Composting Facilities:Municipal and commercial operations processing organic waste at industrial scale require continuous-duty equipment with automated monitoring capabilities. EPA Clean Air Act permitting thresholds shape capital deployment timelines for these installations.
- Waste Management:Integrated solid waste operators deploy high-throughput turning equipment as part of landfill diversion strategies. OSHA confined-space protocols accelerate automated system adoption to eliminate manual exposure in enclosed operations.
- Agriculture:Dairy farming regions in Bavaria expand manure-to-compost operations under nutrient management regulations, accessing USDA conservation program subsidies for precision infrastructure.
- Landscaping:Regional contractors in France operate aging equipment fleets, creating retrofit demand for efficient portable systems with lease-based financing.
Waste management commands capital deployment velocity. Composting facilities are gaining share fastest.
Application:
Volume requirements differentiate continuous-process industrial sites from batch-operated agricultural composting.
- Organic Waste Treatment:Municipal facilities processing food waste and yard trimmings deploy automated turning systems to maintain aerobic conditions and reduce pathogen loads for regulatory-compliant output.
- Compost Production:Commercial operations standardizing maturity indices for horticultural markets require precise moisture and oxygen control through sensor-integrated equipment.
- Biomass Management:Dutch integrated sites combine composting with biogas production, demanding turners that interface with anaerobic digestion feedstock preparation.
- Soil Aeration:Landscaping and remediation applications use portable equipment for site-specific decompaction without continuous processing requirements.
Organic waste treatment holds operational scale. Compost production is climbing the fastest.
Technology:
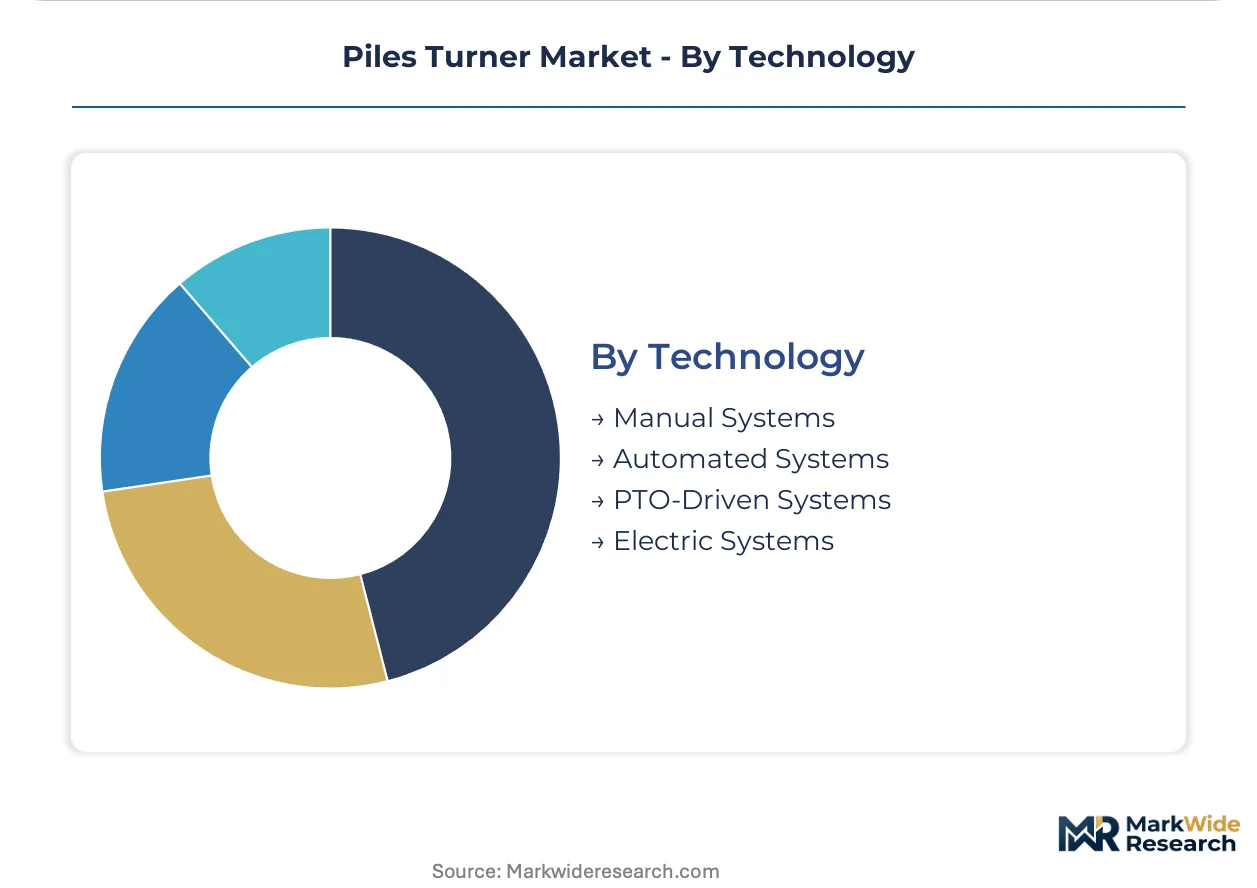
Maturity curves separate legacy manual systems from sensor-integrated automation platforms.
- Automated Systems:IoT-enabled turners with predictive maintenance capabilities command premium pricing through service contract bundling. German cooperative banks facilitate lease structures that bundle maintenance and sensor subscriptions for Bavarian dairy operations.
- Electric Systems:Battery-powered and grid-connected units eliminate hydraulic fluid compliance costs under REACH chemical restrictions, reshaping material specifications for European market access.
- Manual Systems:Operator-controlled equipment faces replacement pressure from EU Green Deal automation mandates and OSHA worker safety enforcement.
- PTO-Driven Systems:Tractor-powered turners serve mid-scale agricultural operators with existing equipment fleets, limiting standalone capital requirements.
Manual systems retain legacy installed base. Automated systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports drum assemblies and hydraulic systems to composting facilities across Europe while importing specialized sensor components from Dutch and Italian suppliers. France and the Netherlands maintain trade surpluses in automated turning equipment. The United States sources European-manufactured industrial-scale units while exporting portable systems to Canadian agricultural markets.
Germany
Municipal composting facilities in Bavaria and North Rhine-Westphalia drive procurement of hydraulic turners under EU Green Deal automation mandates. The country's national environmental regulator enforces stringent volatile organic compound thresholds through permitting protocols that accelerate equipment replacement cycles. Stuttgart and Munich host manufacturing clusters where drum assembly production supplies industrial-scale systems to domestic and export markets.
Netherlands
Biomass management clusters in Gelderland and North Brabant combine anaerobic digestion with composting operations, creating integrated demand for high-throughput turning equipment. The EU F-Gas Regulation shapes climate-control system redesigns that indirectly drive new turner procurement as facilities modernize entire processing lines. Eindhoven and Wageningen anchor research partnerships between equipment manufacturers and agricultural universities developing sensor-integrated automation.
France
Regional composting cooperatives in Auvergne-Rhône-Alpes and Nouvelle-Aquitaine operate aging equipment fleets, presenting retrofit demand for efficient portable systems. ANSM and national environmental authorities embed REACH chemical conformity into tender evaluations, filtering supplier pools before technical assessment begins. Lyon and Bordeaux serve as distribution hubs where lease-based financing structures gain traction among mid-scale agricultural operators.
United States
Midwest agricultural cooperatives in Iowa and Illinois access USDA conservation program subsidies for precision composting infrastructure, creating channels for premium automated turner penetration. OSHA enforces confined-space protocols that accelerate automated system adoption to eliminate manual exposure risks in enclosed operations. Chicago and Minneapolis-St. Paul anchor aftermarket service networks where maintenance density determines competitive positioning.
Italy
Industrial-scale drum assembly manufacturing concentrates in Emilia-Romagna and Lombardy, supplying hydraulic turners to German and French municipal markets. The country's national environmental and workplace safety regulators align equipment certification with EU-wide machinery directives. Bologna and Milan host engineering firms specializing in high-torque drive systems for continuous-duty composting operations.
Piles Turner Market Competitive Landscape
On the supply side, the industry is moderately consolidated around European manufacturing scale and North American aftermarket specialization. Tier differentiation separates industrial-scale hydraulic system fabricators from portable equipment specialists and sensor-integrated automation developers. Strategic archetypes include torque-engineering specialists, IoT-enabled platform builders, and service-density operators. Competitive moves concentrate on geographic expansion through distribution partnerships and technology licensing agreements that accelerate automated system deployment.
Among European-based manufacturers, Toppy Packaging occupies a position representing hydraulic turner engineering for industrial composting lines, while Cremonini exemplifies Italian drum assembly specialization. Black Clawson anchors North American demand through aerated turner configurations. These three entities represent distinct archetypes: continental manufacturing scale, precision mechanical engineering, and regional application specialization.
| Leading Market Players |
|---|
| Toppy Packaging |
| Black Clawson |
| EMR USA |
| Premier Paper Machinery |
| Neopac |
| VI-CART |
| Cremonini |
| Layer-Pack |
| Pro System |
| Others |
Pricing and Supply Chain Analysis
Stuttgart's drum assembly manufacturing cluster shapes downstream pricing power across European composting infrastructure, with hydraulic system fabricators commanding premiums based on torque engineering specialization and REACH-compliant material specifications. German municipal procurement under EU Green Deal mandates compresses negotiation timelines, transferring cost volatility from steel and precision hydraulic inputs directly into equipment pricing tiers.
Pricing Analysis
Next-generation automated turners command substantial premiums over prior-generation hydraulic systems and legacy mechanical units, with pricing stratifying across premium sensor-integrated, standard hydraulic, and economy mechanical tiers. Certification under EU machinery directives and OSHA safety protocols drives price differentiation alongside after-sales service bundling. Cost compression in economy-tier portable equipment intensifies as rental substitution pressures capital sales. Mid-scale agricultural cooperatives exhibit highest price sensitivity, while municipal waste management operators prioritize automation premiums over unit economics.
Supply Chain Analysis
Dual-use sensor technology export controls from Dutch and German authorities restrict IoT component flows to certain non-European destinations, complicating procurement for manufacturers assembling automated systems. Drum assembly production concentrates in Germany, Italy, and the Netherlands, with precision hydraulic components sourced from specialized foundries in northern Italy and Bavaria. Steel price volatility and single-source vulnerability for high-torque drive systems constitute primary supply risks. Distribution runs through OEM-direct channels for municipal accounts and cooperative bank-facilitated leasing networks for agricultural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The piles turner market exhibits cyclical recovery characteristics as EU Green Deal automation mandates and OSHA enforcement cycles compress replacement timelines for aging manual systems across municipal infrastructure.
For Market Incumbents: Harden aftermarket service density in Midwest agricultural cooperatives where EMR USA has established maintenance networks, while deepening captive supply of sensor-integrated control systems to offset portable equipment rental substitution. Vertical integration into drum assembly manufacturing insulates margin pressure from Italian and German supply concentration. For New Entrants and Emerging Players: France's regional composting cooperatives in Auvergne-Rhône-Alpes present underpenetrated retrofit demand for efficient portable systems with lease-based financing structures. Target USDA conservation program channels in Iowa and Illinois dairy regions where subsidized precision infrastructure creates accessible entry points. Partner with German cooperative banks to bundle equipment-as-service contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-integrated automation developers with established IoT maintenance platforms over pure hydraulic engineering specialists. Five-to-ten year viability hinges on regulatory enforcement durability rather than commodity cost cycles. Monitor EPA Clean Air Act permitting velocity as inflection indicator for municipal capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Platform Development | REACH-compliant IoT systems command premium pricing through predictive maintenance subscriptions in Dutch biomass clusters. |
| Backward Integration into Drum Manufacturing | Captive production of high-torque assemblies mitigates supply risk from Emilia-Romagna concentration. |
| Equipment-as-Service Contracting | Bavarian dairy operations access precision composting infrastructure through cooperative bank lease structures. |
| Regional Service Network Expansion | Aftermarket density in Chicago and Minneapolis-St. Paul determines competitive positioning for Midwest agricultural accounts. |
| REACH Chemical Compliance Certification | French ANSM tender evaluations filter supplier pools before technical assessment, creating compliance barriers. |
Research Methodology
Desk research of EU regulatory filings, EPA permitting databases, and trade flow records preceded structured interviews with municipal waste management directors, composting facility operations managers, agricultural cooperative procurement leads, and hydraulic equipment maintenance technicians. Secondary validation drew from customs data, machinery directive certification registries, and USDA conservation program disbursement records. Bottom-up equipment shipment analysis triangulated against top-down infrastructure investment forecasts across the projection horizon.
Assumptions held fixed include EU Green Deal automation mandate enforcement timelines and OSHA confined-space protocol implementation rates, while steel price trajectories and anaerobic digestion co-location adoption were varied across sensitivity scenarios. Segmentation modeling spanned product type, end user, application, and technology maturity dimensions. CAGRs derived from equipment replacement cycle analysis and regulatory-driven capital deployment patterns, with sensor integration penetration curves and rental substitution rates as industry-specific inputs.
Practitioners should monitor EPA permitting backlog durations and EU F-Gas Regulation implementation rigor for early signals of forecast deviation. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and energy cost stabilization. Material shifts in EU machinery directive timelines or hydraulic component trade flows would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Europe Stud Welding Machine Market
Construction Equipment
Cable Winches Market
Construction Equipment
Ground Engaging Tools (GET) Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Construction Equipment Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
South Korea Aerial Work Platform (AWP) Rental Market
Construction Equipment
Concrete Chain Saw Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Concrete Spreader Market
Construction Equipment
Water Sprinkler Market
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Hydraulic Cylinders Market
Construction Equipment
Industrial Grout Pumps Market