
 Tower Crane Rental Market | 2026-2036
Tower Crane Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Tower Crane Rental Market Intelligence
Chinese tower crane manufacturing clusters is shifting capacity toward rental-service integration rather than pure equipment sales. Morrow Equipment dominates the North American self-erecting segment through dealer density and technical support networks. Maxim Crane Works anchors its position via fleet scale and project-logistics coordination across major US metropolitan zones.
A tower crane rental arrangement supplies lifting machinery on a temporary-use contract, with equipment typically rated between 8-ton and 64-ton lifting capacity and configured via hammerhead, flat-top, luffing-jib, or self-erecting geometries to match building height and site footprint constraints. Hammerhead configurations lead in commercial high-rise deployment due to proven load-radius performance, while self-erecting units represent the fastest-expanding product category as urban infill sites restrict assembly space and labor availability. Infrastructure developers command the largest end-user share by project value, though construction companies generate higher transaction frequency and shorter rental cycles.
OSHA crane operator certification mandates and China's GB/T 5031 structural standards shape fleet compliance investments and operator training costs across operational territories. The EU Machinery Directive and CE marking requirements govern access for imported European equipment, creating certification barriers for non-compliant Asian manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions as compliance cost spreads widen competitive positioning between integrated rental operators and fragmented local fleets.
Market Dynamics
Chinese manufacturing clusters are pivoting from equipment sales toward rental-service integration, compressing margins for pure-play distributors while elevating fleet utilization metrics as the primary competitive currency.
Growth Catalysts
- India's urban corridor concentration:Mumbai-Delhi infrastructure corridors are generating sustained equipment deployment cycles. State-level transit-oriented development mandates are locking in multi-year rental contracts.
- OSHA crane operator certification:Federal mandates are professionalizing the operator pool. Training infrastructure investments are creating captive customer relationships between certified fleets and major contractors.
- Self-erecting geometry adoption:Urban infill site constraints are accelerating demand for compact assembly configurations. Labor scarcity on dense construction sites is amplifying the value proposition of reduced rigging crews.
Market Restraints
- Steel input cost volatility:Crane structural components face commodity price swings. Fabrication cost uncertainty is compressing rental rate visibility for multi-year contracts.
- Regional fleet fragmentation:Local operators in secondary Indian and Southeast Asian markets lack scale for maintenance standardization. Service inconsistency is limiting cross-border project coordination.
- CE marking compliance barriers:Non-compliant Asian manufacturers face exclusion from EU project participation. Certification gaps are narrowing the addressable market for cost-focused equipment suppliers.
Strategic Opportunities
- Vietnam's high-rise residential pipeline:Ho Chi Minh City and Hanoi zoning changes are unlocking vertical construction density. Early fleet positioning captures emerging demand before local supply matures.
- Telematics-converged fleet management:Real-time load monitoring and predictive maintenance algorithms are differentiating integrated operators. Data-enabled uptime guarantees command rate premiums over conventional rental arrangements.
- China's GB/T 5031 structural standards:Tightening stability requirements are accelerating fleet replacement cycles. Compliance-driven obsolescence creates equipment refresh demand for certified rental providers.
Industry Challenges
- Certified operator pipeline gaps:OSHA and state-level licensure requirements are outpacing training program capacity. Project delays from crew availability constraints are eroding rental utilization rates.
- Cross-jurisdictional compliance complexity:Divergent GB, CE, and OSHA standards force fleet operators to maintain multiple equipment specifications. Documentation and inspection cost layering is squeezing mid-scale operator margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tower Crane Rental Market |
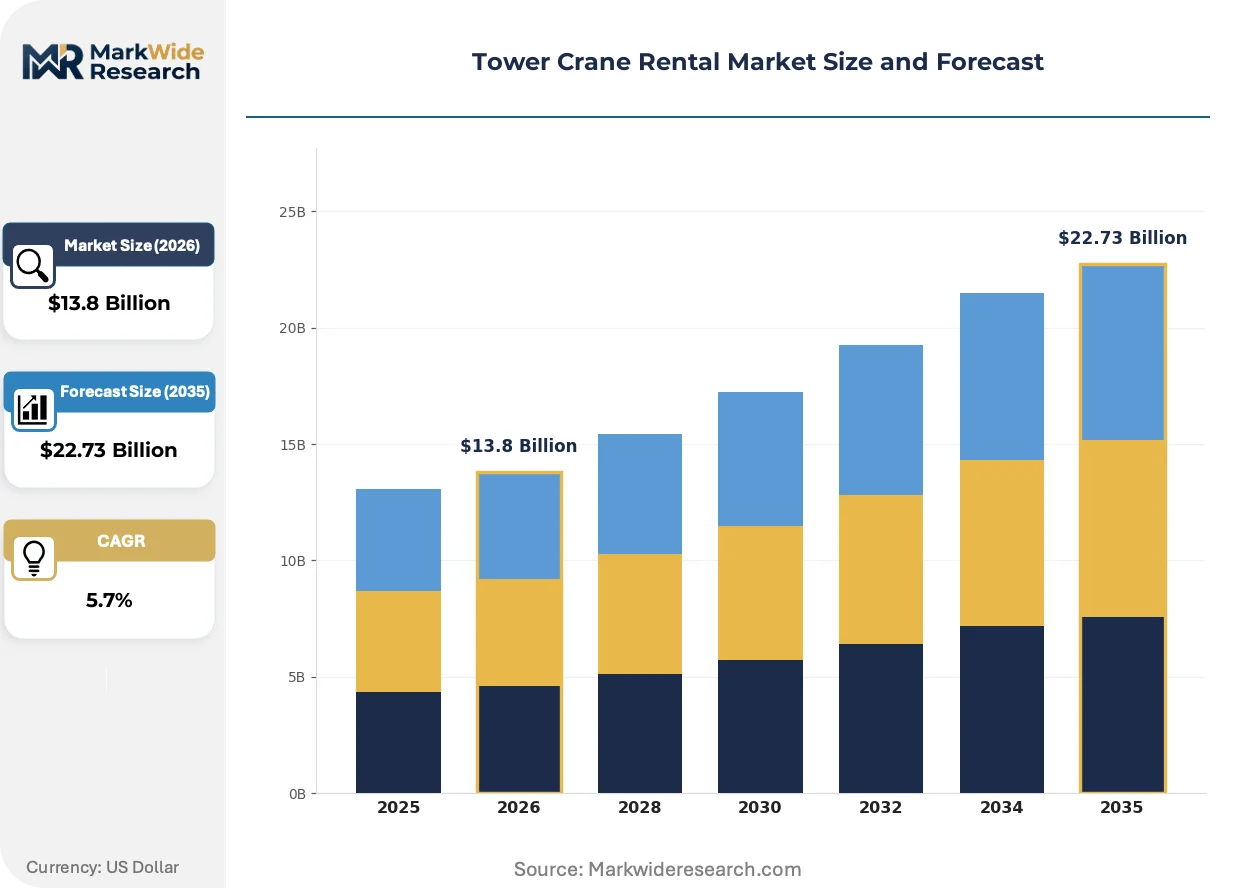
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.73 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hammerhead, Flat Top, Luffing Jib, Self-Erecting End User: Construction Companies, Infrastructure Developers, Shipping Firms, Public Sector Projects Deployment: On-Site, Off-Site, Temporary, Permanent Service Type: Equipment Rental, Maintenance Services, Operator Services, Logistics Support |
| Companies Covered | Morrow Equipment, Maxim Crane Works, Uperio, Bigge Crane and Rigging Co., Stafford Soima Crane Group, Sarens, Mammoet, United Rentals, ALL Tower Crane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tower Crane Rental Market Strategic Shifts & Innovations
Digitalization of fleet operations is compressing the traditional information asymmetry between rental providers and construction contractors. Equipment performance data is becoming a negotiable contract term.
Telematics-enabled load monitoring is converging with predictive maintenance algorithms to transform crane uptime from an operational metric into a contractual guarantee. Tier-one contractors in Germany and the Netherlands are mandating real-time data feeds as a bid qualification requirement. This convergence is compressing acceptable response times for mechanical failures from days to hours.
The EU Machinery Directive's 2023 amendments are tightening conformity assessment procedures for imported lifting equipment. Asian manufacturers face expanded third-party inspection obligations before CE marking authorization. Self-erecting crane categories are experiencing the steepest compliance cost escalation due to their modular assembly complexity.
Construction procurement teams are unbundling crane rental from general contractor packages to secure direct equipment accountability. Major developers in Singapore and Australia are issuing standalone crane tenders with performance-based penalty clauses. This disintermediation is elevating fleet technical documentation and operator certification transparency as competitive differentiators.
Tower Crane Rental Market Segmentation
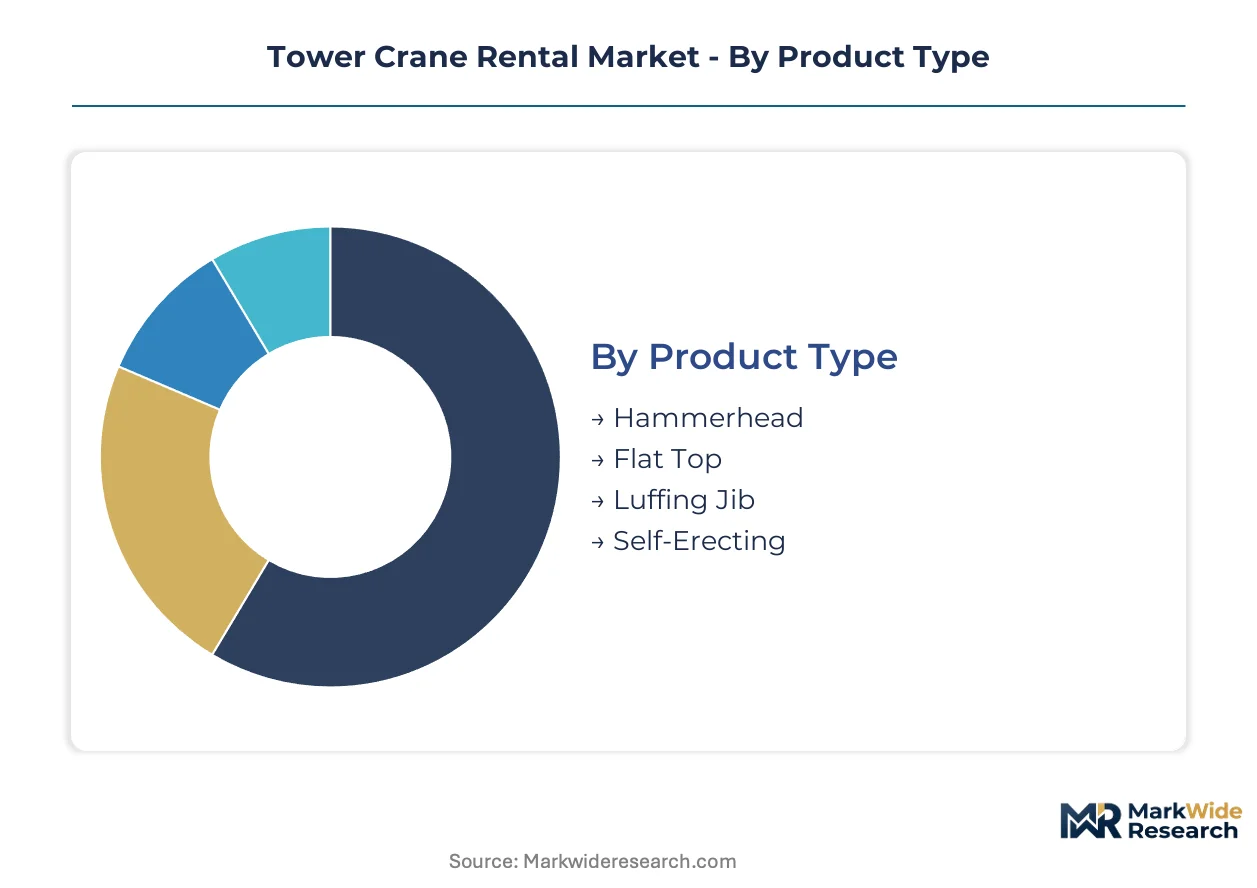
Rental fleet composition in tower cranes hinges on certification pathways that vary dramatically by crane geometry and deployment setting. Understanding which segments trigger OSHA mandates versus GB/T 5031 compliance requirements shapes procurement strategy and total cost of ownership calculations.
Product Type:
GB/T 5031 structural standards and CE marking obligations apply differentially across crane geometries, with modular configurations facing steeper third-party inspection burdens than fixed designs.
- Hammerhead:Traditional jib-over-counterweight geometry delivers proven load-radius performance across commercial high-rise construction. Demand concentrates in Mumbai and Delhi urban corridors where infrastructure developers specify familiar configurations for multi-year transit-oriented development contracts.
- Self-Erecting:Compact modular assembly reduces rigging crew requirements and fits constrained urban infill footprints. Ho Chi Minh City and Hanoi high-rise residential pipelines are accelerating deployment as labor scarcity on dense sites amplifies the reduced-crew value proposition.
- Flat Top:Eliminates the A-frame and pendant lines to enable multiple crane overlapping on tight sites. Singapore and Australian developers favor this geometry for standalone tender contracts with performance-based accountability.
- Luffing Jib:Variable-radius jib suits restricted airspace and proximity-sensitive installations. European metropolitan zones with stringent Machinery Directive compliance requirements drive specification for this precision-controlled category.
Leading the category by volume: Hammerhead. Growing fastest: Self-Erecting.
End User:
Customer type determines contract structure, with transaction frequency and rental cycle length varying substantially across procurement sophistication levels.
- Infrastructure Developers:Command the largest project value share and negotiate multi-year equipment lock-ins. State-level transit mandates in India generate sustained deployment cycles with rate visibility spanning contract duration.
- Construction Companies:Generate higher transaction frequency and shorter rental cycles. Germany and Netherlands tier-one contractors now mandate real-time telematics feeds as bid qualification requirements, elevating fleet technical documentation as a competitive filter.
- Shipping Firms:Port and intermodal terminal applications require specialized heavy-lift configurations. Container throughput expansion in Southeast Asian hubs drives intermittent but high-tonnage demand spikes.
- Public Sector Projects:Government procurement protocols emphasize certified operator availability and documented maintenance histories. OSHA compliance documentation becomes a mandatory submission element for federal and state-level tenders.
Dominant by contract value: Infrastructure Developers. Expanding most quickly: Construction Companies.
Deployment:
Physical siting of crane assets determines regulatory jurisdiction and maintenance logistics intensity.
- On-Site:Traditional construction-adjacent positioning requires full OSHA or GB standards compliance for the operational territory. China's tightening stability requirements are accelerating replacement cycles for aging on-site fleets.
- Off-Site:Prefabrication yard and modular construction factory deployments concentrate utilization in manufacturing clusters. Chinese manufacturing clusters pivoting toward rental-service integration favor this deployment mode for captive utilization metrics.
- Temporary:Short-cycle project-based positioning dominates transaction volume. Steel input cost volatility compresses rate visibility for operators offering temporary deployment on multi-month contracts.
- Permanent:Long-term industrial and infrastructure installations amortize compliance investments over extended horizons. Mining and heavy manufacturing applications in Australia specify permanent deployment for continuous material handling operations.
Highest transaction volume: Temporary. Steepest expansion trajectory: Off-Site.
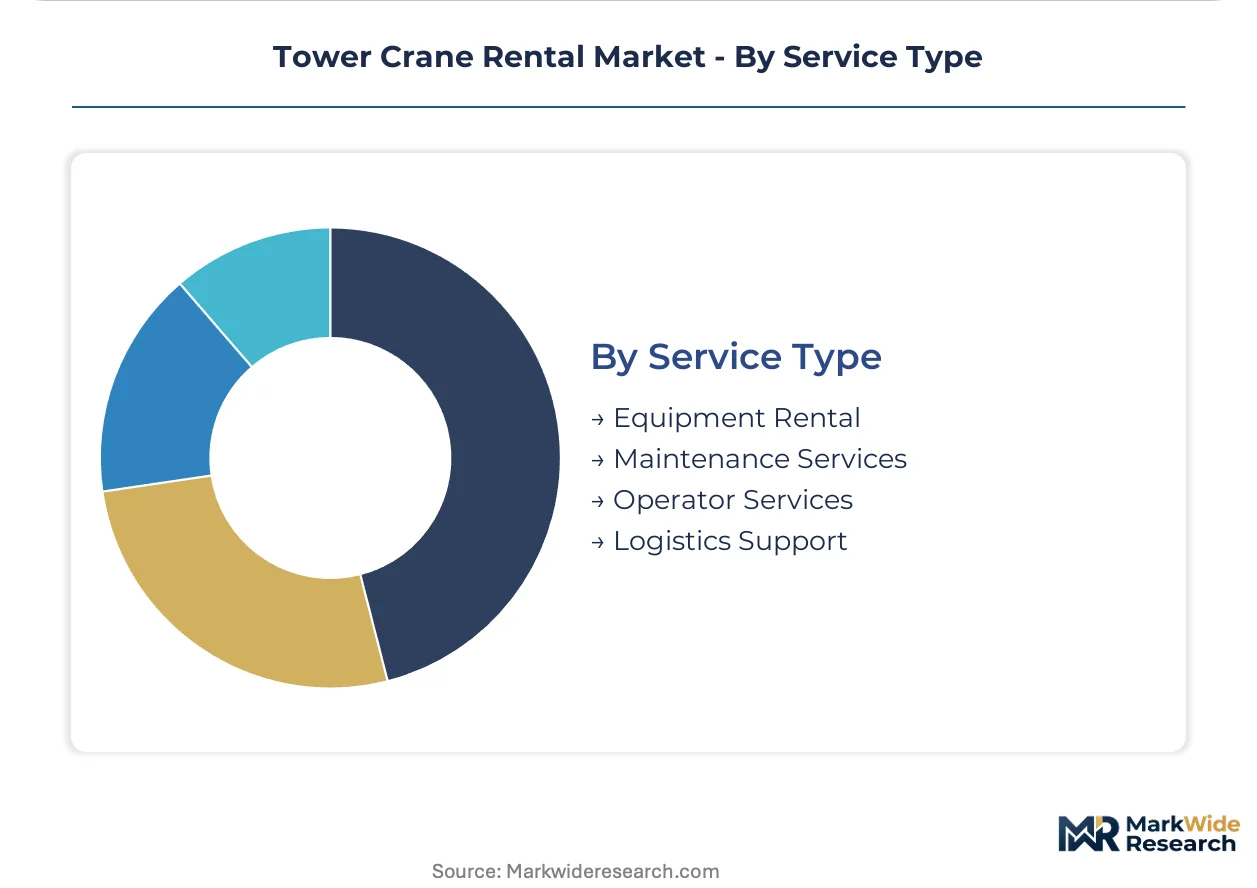
Service Type:
Value capture in rental arrangements extends beyond equipment provision into adjacent service layers with diverging margin profiles.
- Equipment Rental:Core machinery provision remains the revenue foundation. Fleet utilization metrics have displaced pure equipment sales as the primary competitive currency across integrated operators.
- Operator Services:Certified crane operator supply addresses pipeline gaps where OSHA and state licensure requirements outpace training program capacity. Captive relationships form between certified fleets and major contractors facing project delays from crew availability constraints.
- Maintenance Services:Predictive maintenance algorithms and real-time load monitoring differentiate tier-one providers. Uptime guarantees command rate premiums over conventional break-fix arrangements.
- Logistics Support:Transport, assembly, and disassembly coordination anchors project-logistics positioning for scaled operators. Metropolitan zone coverage density determines competitive viability for this service layer.
Largest revenue share: Equipment Rental. Gaining share fastest: Operator Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel fabrication clusters in China's Yangtze River Delta anchor tower crane manufacturing capacity. Rental-service integration is displacing pure equipment sales as the dominant commercial model across operational territories.
China
GB/T 5031 structural standards are tightening stability requirements for on-site crane deployments. The Ministry of Industry and Information Technology is accelerating fleet replacement cycles through enhanced certification protocols. Shanghai and Jiangsu manufacturing clusters are pivoting toward rental-service integration to capture recurring revenue streams.
United States
OSHA crane operator certification mandates are professionalizing the workforce and creating captive relationships between certified fleets and major contractors. Federal safety requirements are elevating training infrastructure investments as a competitive filter. Metropolitan zones across Texas and Florida are seeing project-logistics coordination emerge as the primary scale advantage.
India
Mumbai-Delhi urban corridor projects are generating sustained multi-year equipment deployment cycles. State-level transit-oriented development mandates from the Central Electricity Authority are locking in rental contract visibility. Maharashtra and Gujarat construction clusters are concentrating demand for hammerhead configurations in commercial high-rise development.
Germany
EU Machinery Directive amendments are tightening conformity assessment procedures for imported lifting equipment. CE marking requirements are creating certification barriers for non-compliant Asian manufacturers. The KBA and federal safety frameworks are driving specification for luffing-jib geometries in precision-controlled metropolitan installations.
Vietnam
Ho Chi Minh City and Hanoi zoning changes are unlocking vertical construction density in high-rise residential pipelines. The country's national construction regulator is formalizing equipment import standards ahead of EU alignment. Southern manufacturing zones are attracting early fleet positioning to capture demand before local rental supply matures.
Tower Crane Rental Market Key Industry Players
Global majors compete with regional champions across fleet scale and project-logistics coordination capabilities. The market structure concentrates around integrated operators with captive maintenance infrastructure and fragmented local fleets lacking cross-border coordination capacity. Two strategic archetypes dominate: scale-driven fleet operators anchoring metropolitan zone coverage, and specialized self-erecting segment champions leveraging dealer density. Competitive positioning hardens through M&A consolidation of regional maintenance networks and backward integration into telematics-enabled fleet management systems.
Within the scale-driven tier, Maxim Crane Works and Morrow Equipment exemplify divergent specialization vectors. Morrow Equipment occupies a position as the North American self-erecting segment anchor through technical support network density. Maxim Crane Works represents the project-logistics coordination archetype across major US metropolitan zones. Sarens, the Belgian heavy-lift specialist, sits within the premium infrastructure tier where multi-year contract lock-ins predominate.
| Leading Market Players |
|---|
| Morrow Equipment |
| Maxim Crane Works |
| Uperio |
| Bigge Crane and Rigging Co. |
| Stafford Soima Crane Group |
| Sarens |
| Mammoet |
| United Rentals |
| ALL Tower Crane |
| Others |
Cost & Logistics Intelligence
Infrastructure developers in India and Southeast Asia command project-logistics coordination packages that bundle equipment rental with certified operator services, compressing pure equipment margins while elevating uptime-guaranteed contracts as the dominant pricing model across high-volume urban corridors.
Pricing Analysis
Warranty and maintenance bundling separates tier-one rental providers from fragmented local fleets, with predictive uptime guarantees commanding rate premiums over conventional break-fix arrangements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—OSHA-compliant fleets with telematics integration sit at the premium tier, while uncertified local operators compete on spot rates. Cost compression in the standard tier is intensifying because steel input volatility erodes multi-year contract visibility. Public sector projects exhibit highest price sensitivity due to procurement protocol constraints, whereas infrastructure developers prioritize performance accountability over rate minimization.
Supply Chain Analysis
Dual-sourcing requirements from tier-one contractors in Germany and the Netherlands mandate CE-marked equipment alongside telematics-enabled fleet documentation, forcing rental operators to maintain parallel supplier relationships across certification jurisdictions. Manufacturing concentrates in China, Germany, and the United States, with Yangtze River Delta fabrication clusters anchoring structural component supply. Steel plate, hydraulic systems, and electronic control modules constitute critical input dependencies. Single-source vulnerability in Chinese steel supply creates exposure to commodity price swings. Distribution runs through project-logistics coordination networks rather than equipment dealerships, with metropolitan zone coverage density determining competitive viability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where compliance cost layering from divergent GB, CE, and OSHA standards forces sub-scale operators toward exit or acquisition by integrated fleet providers.
For Market Incumbents: Anticipate telematics-converged fleet management becoming a mandatory bid qualification rather than a differentiator, and accelerate backward integration into predictive maintenance algorithms before European contractors mandate real-time data feeds as standard terms. Certification investment in multi-jurisdictional compliance documentation anchors defensive positioning against emerging rental-service integrators from Chinese manufacturing clusters. For New Entrants and Emerging Players: Mid-scale construction companies in Vietnam's Ho Chi Minh City and Hanoi corridors represent the most penetrable buyer archetype, as local rental supply maturity lags behind high-rise residential pipeline acceleration. Self-erecting crane deployment for urban infill sites offers white-space entry with reduced crew requirements as the primary go-to-market angle. Early fleet positioning captures demand before incumbent operators establish metropolitan coverage density. For Investors and Strategic Acquirers: The window for entry favors regional maintenance network consolidation over greenfield fleet builds, as captive technical infrastructure generates recurring revenue streams with higher margin stability than equipment rental alone. Acquisition targets should display certified operator training capacity and cross-border project coordination capabilities. The signal to watch is China's GB/T 5031 enforcement intensity, which accelerates replacement demand for compliant fleets and compresses valuation multiples for non-compliant regional operators.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time load monitoring from Sarens and Mammoet anchors tier-one contractor retention. |
| Certified Operator Training Infrastructure | OSHA-compliant programs at Maxim Crane Works create captive relationships with major contractors. |
| Regional Maintenance Network Acquisition | Consolidation of Indian local fleets addresses service inconsistency limiting cross-border coordination. |
| Multi-Jurisdictional Compliance Investment | Parallel GB, CE, and OSHA certification documentation unlocks project participation across urban corridors. |
| Self-Erecting Fleet Expansion | Compact assembly configurations capture Ho Chi Minh City and Hanoi high-rise residential demand. |
Research Approach
Document review covered regulatory filings from OSHA, EU Machinery Directive amendments, and China's GB/T 5031 standards, complemented by interviews with fleet operations directors, construction procurement managers, crane maintenance technicians, and project logistics coordinators. Secondary validation drew from equipment manufacturer technical documentation, customs trade data on steel component flows, and industry association fleet utilization surveys. Bottom-up segmentation modeling triangulated against top-down macroeconomic construction spend projections.
Historical utilization rates and rental contract terms were cross-referenced against panel input from tier-one contractors and infrastructure developers across the analysis window. Segmentation dimensions modeled include crane geometry type, deployment mode, end-user procurement sophistication, and service layer bundling. CAGRs were derived from equipment replacement cycle analysis and urban construction pipeline tracking. Forecast inputs incorporated steel price volatility indices and regulatory compliance cost trajectories.
Revisions become necessary when steel input cost volatility exceeds modeled ranges or when regulatory enforcement intensity shifts materially from baseline assumptions. Deviation in China's fleet replacement cycle acceleration or India's transit-oriented development mandate implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Solid Control Equipment Market
Construction Equipment
United States Crane Market
Construction Equipment
Multi Attachment Loaders Market
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Garage Equipment Market
Construction Equipment
Laser Welding Equipment Market
Construction Equipment
Rough Terrain Crane Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Saudi Arabia Construction Equipment Market
Construction Equipment
Derinding Machines Market
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
Stamping Machines Market
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
Global Asphalt Crushers Market