
 Metal Machinery Market | 2026-2036
Metal Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Machinery Market Analytics
Digital twin integration is fragmenting traditional metal machinery value chains into software-hardware bundled offerings. DMG Mori Seiki AG leverages its Celos platform to anchor digital-native machine tool ecosystems. Amada Co., Ltd. sustains dominance in laser-based sheet metal processing through captive fiber laser source development. TRUMPF SE + Co KG competes by extending vertical control from laser generators through automated material handling systems.
Metal machinery comprises powered equipment that shapes, cuts, forms, or finishes metallic workpieces through mechanical, thermal, or electrochemical energy transfer, typically operating at spindle speeds from hundreds to tens of thousands of RPM and positioning accuracies measured in micrometers. Its primary purpose is transforming raw metal stock into precision components for assembled products. Milling machines generate the largest revenue pool among product types due to five-axis complexity premiums in aerospace work. Computer Numerical Control technology leads technology adoption, while Automation segments capture the fastest expansion as lights-out manufacturing requirements intensify. Precision Machining applications command superior margins through tolerance-driven specification premiums.
The EU Machinery Directive and CE marking framework mandate risk assessment protocols and safety interlocks for equipment placed on European markets, while China's SAMR enforces GB standards compliance for domestic sales and import clearance. OSHA lockout-tagout regulations in the United States shape machine guarding design requirements and aftermarket retrofit demand. Stakeholders must weigh regulatory divergence against platform standardization bets as regional certification costs compound.
Market Dynamics
Digital twin integration is fragmenting traditional metal machinery value chains into software-hardware bundled offerings, forcing OEMs to choose between platform standardization and regional certification fragmentation.
Growth Catalysts
- Automotive capital expenditure:OEMs are expanding investment in automated forming equipment for electric vehicle chassis production, particularly in Germany's Stuttgart machine tool cluster.
- EU Machinery Directive:Tightening safety and interoperability requirements for imported equipment are accelerating replacement cycles among European manufacturers seeking CE marking compliance.
- Lights-out manufacturing:Automation segments capture the fastest expansion as China's Yangtze River Delta manufacturing corridor demands unmanned production lines.
Market Restraints
- Fiber laser source concentration:Captive fiber laser development requires substantial R&D investment, creating barriers for smaller equipment builders lacking vertical control over beam generation technology.
- GB standards compliance:China's SAMR enforcement creates import clearance friction and dual certification costs for equipment entering domestic sales channels.
- Five-axis machining complexity:Aerospace work demands positioning accuracies measured in micrometers, limiting supplier pools to builders with proven spindle speed control above ten thousand RPM.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for advanced manufacturing equipment create white space for precision machining applications in automotive and defense sub-supply chains.
- Digital-native ecosystems:Convergence of Celos-type platforms with automated material handling systems enables recurring software revenue streams alongside hardware sales.
- OSHA retrofit demand:Lockout-tagout regulations in the United States drive aftermarket machine guarding upgrades for installed base equipment.
Industry Challenges
- CNC programming talent scarcity:Five-axis complexity premiums require operators capable of simultaneous multi-axis toolpath optimization, creating recruitment bottlenecks in manufacturing clusters.
- CE marking timeline compression:Risk assessment protocols and safety interlock documentation extend product launch cycles, compressing competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Machinery Market |
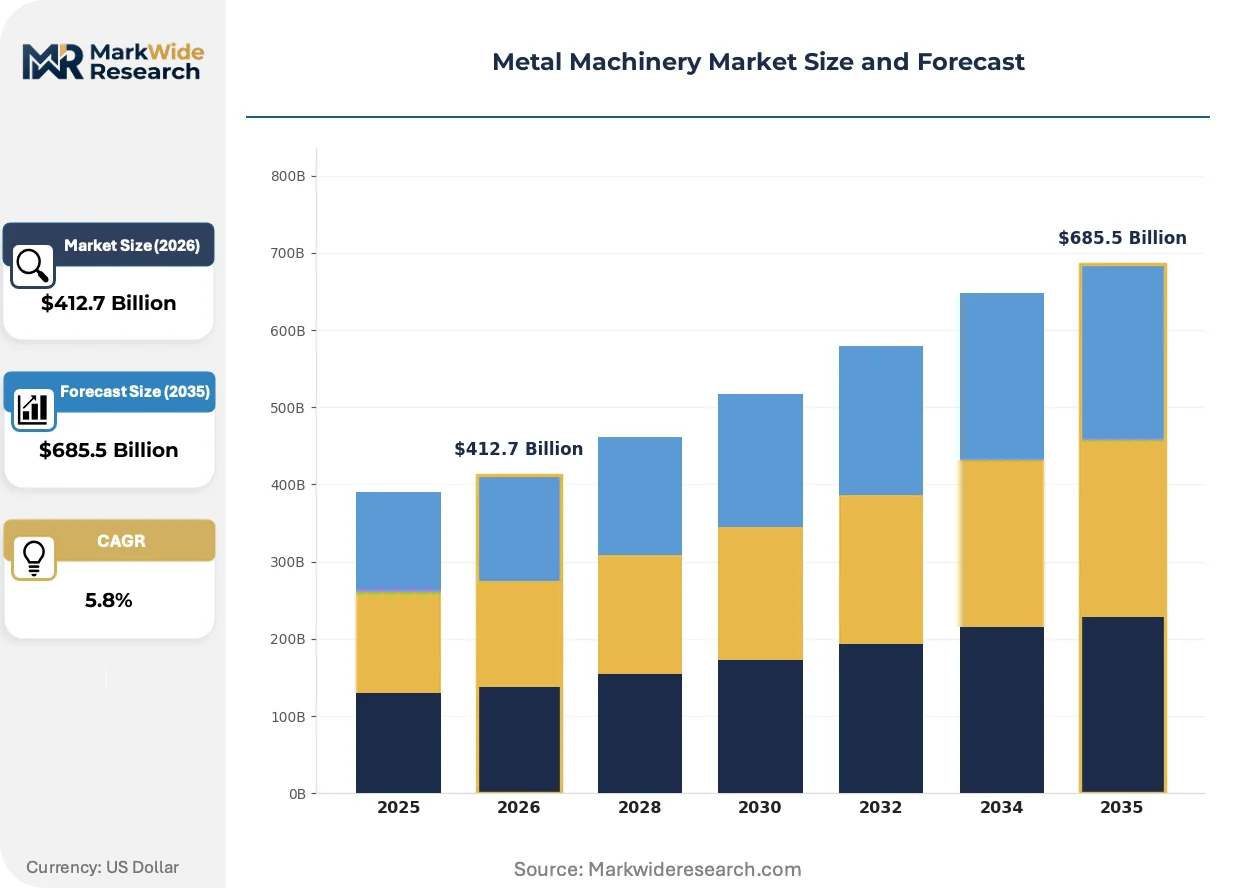
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $685.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lathe Machines, Milling Machines, Drilling Machines, Grinding Machines Technology: Computer Numerical Control, Manual, Hybrid, Automation End User: Aerospace, Automotive OEMs, Construction, Heavy Engineering Application: Fabrication, Precision Machining, Tool Manufacturing, Maintenance |
| Companies Covered | TRUMPF SE + Co KG, Amada Co., Ltd., Bystronic AG, DMG Mori Seiki AG, Mazak Corporation, Haas Automation, Inc., Prima Industrie SpA, Okuma Corporation, LVD Company NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Machinery Market Evolving Landscape
Active reshaping in metal machinery centers on energy transfer modality shifts, regulatory harmonization pressures, and buyer consolidation around integrated solution providers rather than component vendors.
Hybrid manufacturing is migrating from prototype aerospace applications toward production-scale deployment. Tier-one suppliers adopt laser-based sheet metal processing combined with conventional milling for titanium structural components. This convergence compresses lead times for complex geometries previously requiring multiple machine setups and workpiece transfers.
REACH substance restrictions and RoHS compliance deadlines are forcing reformulation of cutting fluids and coolants used in precision machining. Equipment builders must validate alternative chemistries without compromising spindle thermal stability or chip evacuation efficiency. German and Italian OEMs face the tightest compliance windows for existing product lines.
Consolidated procurement by automotive tier suppliers is displacing fragmented purchasing of standalone machine tools. Buyers now specify turnkey cells integrating forming, cutting, and automated material handling from single-source vendors. This pattern is most visible in China's Yangtze River Delta, where battery enclosure manufacturers demand unified warranty coverage across integrated production lines.
Metal Machinery Market Segmentation
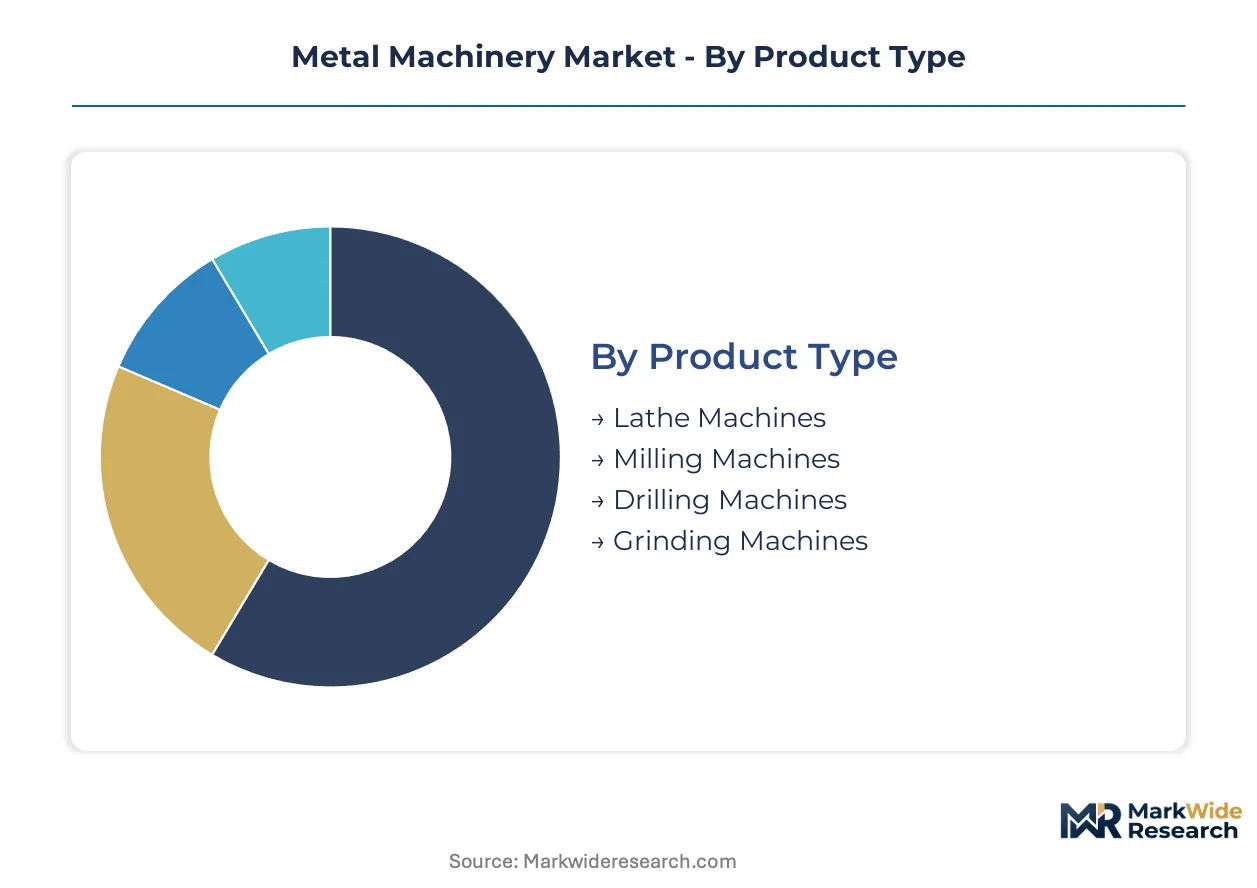
Metal machinery segmentation reveals distinct equipment-performance tiers that align with buyer capital allocation priorities. Aerospace fabricators demand five-axis positioning precision, while automotive OEMs prioritize throughput velocity in automated forming lines. Understanding these segment boundaries enables targeted specification development and channel strategy optimization.
Product Type:
Equipment selection spans the full spectrum from high-volume rotational work to ultra-precision surface finishing, with each machine architecture commanding distinct operator skill requirements and facility infrastructure investments.
- Milling Machines:Five-axis configurations achieve positioning accuracies measured in micrometers through spindle speeds exceeding ten thousand RPM. Demand concentrates in Germany's Stuttgart aerospace cluster, where electric vehicle chassis complexity and turbine blade geometries drive specification premiums.
- Lathe Machines:Rotational workhorse equipment handles cylindrical component production from shafts to threaded fasteners. China's Yangtze River Delta manufacturing corridor absorbs the highest volumes, particularly for automotive powertrain and construction equipment sub-assemblies.
- Drilling Machines:Stationary and radial configurations serve hole-making operations across maintenance and fabrication workflows.
- Grinding Machines:Surface and cylindrical variants deliver final dimensional tolerances for precision machining applications.
The dominant share belongs to Milling Machines, while Lathe Machines is closing the gap fastest through electric vehicle platform standardization.
Technology:
Control modality selection determines workforce composition, with digital-native platforms displacing conventional operator-dependent workflows in high-mix production environments.
- Computer Numerical Control:Programmable motion control enables complex toolpath execution without manual intervention. Automotive OEMs in Germany's machine tool cluster specify CNC for electric vehicle battery enclosure production, where repeatability requirements exceed manual capability thresholds.
- Automation:Lights-out manufacturing systems integrate material handling, tool management, and in-process inspection. China's Yangtze River Delta corridor drives fastest expansion as labor cost arbitrage erodes and unmanned shift coverage becomes mandatory.
- Hybrid:Combines manual setup flexibility with programmable cycle execution for prototype-to-production transitions.
- Manual:Operator-controlled equipment persists in maintenance applications and low-volume custom fabrication.
Computer Numerical Control retains the largest installed base, though Automation is expanding most quickly through tier-one supplier consolidation around turnkey cells.
End User:
Buyer concentration patterns reflect capital intensity gradients, with aerospace and automotive OEMs commanding specification influence that cascades through sub-tier supply chains.
- Automotive OEMs:Electric vehicle platform transitions are accelerating automated forming equipment procurement for chassis and battery enclosure production. Germany's Stuttgart cluster anchors European demand, while China's Yangtze River Delta corridor dominates Asian volume.
- Aerospace:Titanium structural component requirements drive hybrid manufacturing adoption combining laser-based sheet metal processing with conventional milling. Tier-one suppliers in Germany and Italy face REACH substance restriction compliance deadlines for cutting fluid reformulation.
- Heavy Engineering:Mining, energy, and infrastructure equipment manufacturers prioritize durability and load-bearing capacity over dimensional precision.
- Construction:Fabrication shops serving building systems and infrastructure projects favor versatile equipment configurations.
Automotive OEMs command the dominant procurement volume, while Aerospace is gaining share fastest through titanium component complexity premiums.
Application:
Workflow positioning determines margin structure, with precision-driven specifications capturing tolerance premiums versus commoditized fabrication services.
- Precision Machining:Tolerance-driven specifications for aerospace, medical, and defense components command superior margins through micrometer-level positioning requirements. India's PLI scheme for advanced manufacturing equipment is creating white space in automotive and defense sub-supply chains.
- Fabrication:Laser-based sheet metal processing serves structural component production with compressed lead times. China's Yangtze River Delta battery enclosure manufacturers demand unified warranty coverage across integrated production lines.
- Tool Manufacturing:Cutting tool and die production requires specialized grinding and milling configurations.
- Maintenance:Repair and overhaul operations favor flexible manual and hybrid equipment for non-repetitive work.
Precision Machining holds the dominant margin position, while Fabrication is climbing the fastest through consolidated procurement by automotive tier suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and aerospace fabricators concentrate procurement in machine tool clusters where five-axis precision intersects with automated forming capacity. Germany's Stuttgart corridor and China's Yangtze River Delta anchor volume, while regulatory divergence between CE marking and GB standards reshapes supplier qualification requirements.
Germany
Stuttgart's machine tool cluster absorbs premium five-axis milling equipment for electric vehicle chassis and turbine blade production. The EU Machinery Directive and CE marking framework mandate risk assessment protocols that extend product launch cycles. DMG Mori Seiki AG anchors digital-native ecosystems through its Celos platform, bundling software with hardware offerings.
China
SAMR enforces GB standards compliance for domestic sales and import clearance, creating dual certification friction for foreign equipment builders. The Yangtze River Delta manufacturing corridor drives fastest automation expansion as battery enclosure manufacturers demand lights-out production lines. Unmanned shift coverage has become mandatory across tier-one supplier facilities.
United States
OSHA lockout-tagout regulations shape machine guarding design requirements and aftermarket retrofit demand for installed base equipment. Precision machining applications in defense and medical sub-supply chains command tolerance-driven specification premiums. The Southeast automotive corridor expands automated forming procurement for electric vehicle platform transitions.
Japan
METI industrial policy supports hybrid manufacturing adoption combining laser-based sheet metal processing with conventional milling for titanium structural components. Chubu region fabricators face REACH substance restriction compliance deadlines for cutting fluid reformulation. Domestic OEMs prioritize captive fiber laser source development to sustain margin control.
India
The PLI scheme for advanced manufacturing equipment creates white space for precision machining in automotive and defense sub-supply chains. BIS certification requirements add regulatory layering for imported equipment entering domestic channels. Gujarat and Maharashtra industrial corridors attract capital expenditure from tier-one suppliers establishing localized production.
Metal Machinery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base organizes around three archetypes: digital platform bundlers, captive technology integrators, and scale-driven fabricators. Consolidation pressures intensify as turnkey procurement displaces standalone machine tool purchasing. Dominant competitive moves include strategic partnerships for automated material handling integration and backward integration into beam generation technology.
Within the digital platform tier, DMG Mori Seiki AG exemplifies software-hardware bundling through ecosystem anchoring. Among laser-based specialists, TRUMPF SE + Co KG and Amada Co., Ltd. occupy positions defined by vertical control from generators through automated systems. These three represent distinct strategic postures: platform standardization, captive source development, and integrated solution provision.
| Leading Market Players |
|---|
| TRUMPF SE + Co KG |
| Amada Co., Ltd. |
| Bystronic AG |
| DMG Mori Seiki AG |
| Mazak Corporation |
| Haas Automation, Inc. |
| Prima Industrie SpA |
| Okuma Corporation |
| LVD Company NV |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's container rate volatility cascades through Stuttgart's machine tool cluster, amplifying price differentiation between CE-marked European equipment and GB-certified imports bound for China's Yangtze River Delta. This logistics chokepoint tightens margin structures for builders lacking captive control over fiber laser sources or automated material handling systems.
Pricing Analysis
Cost-plus contracts with steel and rare-earth indexation dominate long-term equipment procurement between automotive OEMs and tier-one suppliers. Pricing stratifies across premium five-axis milling configurations, standard three-axis CNC platforms, and economy-grade manual equipment, with CE marking compliance and spindle speed capability as primary differentiation drivers. Cost compression in standard-tier lathe machines is intensifying due to China's Yangtze River Delta capacity expansion. Automotive battery enclosure manufacturers exhibit highest price sensitivity, while aerospace fabricators prioritize micrometer-level tolerance premiums over unit economics.
Supply Chain Analysis
Upstream feedstock concentration in China, Germany, and Japan shapes equipment builder cost structures through dependence on high-grade cast iron, precision ball screws, and rare-earth magnet supplies for spindle motors. The supply chain draws from specialized foundries in Germany's Stuttgart corridor and component machine shops across China's Jiangsu province. Single-source vulnerability in fiber laser resonator technology creates procurement risk for builders without captive beam generation capability. Distribution runs through direct OEM sales teams for turnkey automated cells and regional distributor networks for standalone machine tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal machinery market is entering a cyclical recovery phase as automotive capital expenditure rebounds from electric vehicle platform transition delays. Replacement demand for CE-marked equipment accelerates through tightening EU Machinery Directive enforcement.
For Market Incumbents: Harden digital platform differentiation through Celos-type ecosystem bundling that anchors recurring software revenue alongside hardware sales. Prioritize backward integration into fiber laser source technology to defend margin position against TRUMPF SE + Co KG and Amada Co., Ltd. Expand automated material handling partnerships to capture turnkey procurement consolidation by China's Yangtze River Delta battery enclosure manufacturers. For New Entrants and Emerging Players: Establish a beachhead in India's precision machining segment through PLI scheme qualification for automotive and defense sub-supply chains. Target aftermarket machine guarding retrofit demand driven by OSHA lockout-tagout compliance in the United States. Pursue a channel partnership strategy with established distributors rather than direct sales buildout to minimize capital intensity. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized machine tool divisions lacking digital-native platform integration. Long-term viability centers on software-hardware convergence and recurring revenue attachment rates. Monitor quarterly order intake from Germany's Stuttgart cluster as the lead indicator for aerospace and automotive capital expenditure inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Laser Sources | Captive beam generation technology insulates margin structures from IPG Photonics and nLIGHT supply constraints. |
| Digital Platform Ecosystem Development | Celos-type software-hardware bundling creates recurring revenue streams and switching costs for DMG Mori Seiki AG. |
| Automated Material Handling Partnership | Unified turnkey cells satisfy China's Yangtze River Delta battery enclosure manufacturer procurement consolidation. |
| CE Marking Compliance Acceleration | EU Machinery Directive risk assessment protocols extend competitive moats against uncertified import competition. |
| India PLI Scheme Localization | BIS certification and domestic production qualification unlock precision machining white space in automotive sub-supply chains. |
Research Methodology
The analysis maps milling machines, lathe machines, grinding equipment, and automated forming systems, each validated through plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at tier-one automotive and aerospace suppliers. Primary interview intelligence combined with customs trade data, SEC 10-K filings, EU Machinery Directive certification registries, and SAMR GB standards compliance records enables bottom-up equipment shipment triangulation against top-down capital expenditure estimates.
Assumptions held fixed include regulatory enforcement intensity for CE marking and GB standards, while electric vehicle platform transition timelines and aerospace build rates varied across scenario paths. Segmentation dimensions span product type, control technology, end-user industry, and application workflow, with geographic production cluster as an additional metal machinery-specific layer. CAGRs derive from equipment replacement cycle analysis and capital intensity ratios applied across the projection horizon, incorporating spindle speed specification premiums and automation penetration curves as industry-specific inputs.
Sensitivities concentrate around electric vehicle adoption trajectory, REACH substance restriction enforcement for cutting fluid reformulation, and China-EU regulatory divergence on safety interlock standards. Forecasts reflect documented assumptions regarding labor cost arbitrage erosion and lights-out manufacturing penetration. Quarterly review of Stuttgart cluster order backlogs, Yangtze River Delta automation deployment rates, and India's PLI scheme qualification announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Road Marking Equipment Market
Construction Equipment
Industrial Agitators Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
Core Drill Automatic Feeding Machine Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
India Crane Market
Construction Equipment
Press Brakes Market
Construction Equipment
Compact Loaders Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
Global Scaffolding Market
Construction Equipment
Hexagonal Wire Netting Machine Market
Construction Equipment
Global Industrial Parts Washer Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Winch Market