
 Stud Welding Machine Market | 2026-2036
Stud Welding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Stud Welding Machine Market Analysis
A capital-intensity divergence between automated robotic system builders and manual equipment suppliers is bifurcating competitive dynamics in the stud welding machine landscape. Soyer Stud Welding leverages deep vertical integration in arc welding power sources to sustain margin control across European industrial channels. Nelson Stud Welding anchors its position through extensive distributor networks serving North American automotive and construction end users. KÖCO Stud Welding differentiates via precision engineering in drawn-arc capacitor discharge systems for German automotive OEMs.
Stud welding machines fuse metal fasteners to base materials without through-hole drilling, using controlled electrical arcs or capacitor discharge to create metallurgical bonds in milliseconds, typically handling stud diameters from 3 mm to 25 mm. The equipment serves primary industrial purposes in steel construction, automotive body assembly, and ship deck fabrication where structural integrity and production speed are critical. Automatic and robotic product types command expanding share as labor costs rise and repeatability standards tighten across manufacturing and shipbuilding end users. Drawn arc technology leads installed capacity due to its versatility across carbon steel, stainless steel, and aluminum substrates, while capacitor discharge systems retain dominance in thin-sheet automotive applications where minimal reverse-side marking is essential.
ISO 14555 governs arc stud welding of metallic materials, while AWS D1.1 structural welding codes mandate procedure qualification in North American construction, and CE marking under EU machinery directives controls market access for European equipment imports. These frameworks elevate compliance costs for smaller manufacturers while creating specification-driven replacement cycles among certified end users. Stakeholders must monitor evolving automation integration standards and regional carbon-accounting rules that will reshape equipment procurement criteria and supplier qualification protocols.
Market Dynamics
Automotive OEMs and shipbuilders are consolidating procurement around robotic stud welding cells, compressing demand for manual equipment and rewiring competitive positioning around automation integration capabilities rather than power-source specifications alone.
Growth Catalysts
- ISO 14555 Compliance Mandates:Certification requirements under this arc stud welding standard are forcing equipment replacements across European steel construction, particularly in German bridge and building projects where weld procedure qualification is non-negotiable.
- Aluminum Body Assembly:Automotive manufacturers are expanding drawn-arc capacity to join aluminum studs in electric vehicle platforms, creating metallurgical bonds without through-hole weakening in battery tray and body-in-white applications.
- Japan Shipbuilding Concentration:Japanese shipyards are modernizing deck fabrication lines with automated fastening systems to meet Class NK structural welding rules and reduce labor dependency in high-volume hull assembly.
Market Restraints
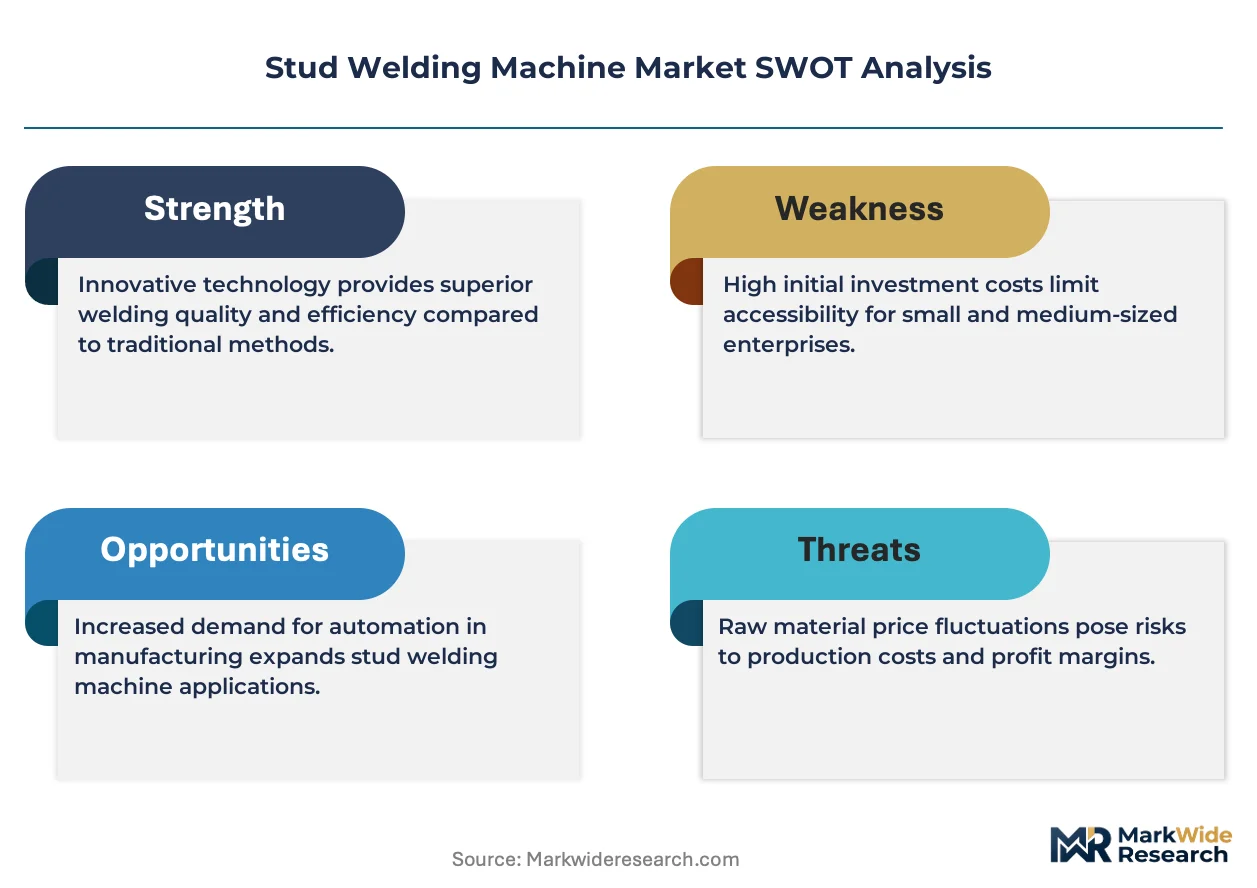
- Copper and Silicon Steel Input Volatility:Transformer core materials and power semiconductor substrates face price swings that compress margins for equipment builders lacking captive supply arrangements or long-term purchase agreements.
- Technical Limitation in Ultra-Thin Sheet:Capacitor discharge systems struggle to achieve consistent penetration below 0.5 mm substrate thickness without burn-through, restricting adoption in advanced automotive closure panels and appliance housings.
- AWS D1.1 Procedure Qualification Burden:North American structural contractors face extended certification timelines and documentation costs that delay equipment deployment and favor incumbent suppliers with established qualification libraries.
Strategic Opportunities
- Indian Infrastructure Build-Out:Metro rail and commercial high-rise projects under the country's PLI scheme for capital goods are opening procurement channels for automated fastening equipment as domestic fabrication capacity expands.
- CE Marking Automation Integration:EU machinery directive updates are creating specification pull for stud welding cells with embedded safety controllers and traceability software, favoring suppliers with in-house control system development.
- Hybrid Laser-Arc Convergence:Shipbuilders are piloting combined heat source systems that merge drawn-arc stability with laser precision for thick-plate deck applications, creating white space for equipment developers with multi-process expertise.
Industry Challenges
- Certified Welding Engineer Scarcity:AWS CWI and IIW EWE qualification holders are concentrated among aging workforces in the United States and Germany, constraining deployment of complex automated systems requiring procedure development and troubleshooting.
- Legacy Control Architecture Integration:Automotive plants running decades-old PLC networks face friction connecting modern robotic stud welding cells without costly line-wide upgrades, slowing replacement cycles despite performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stud Welding Machine Market |
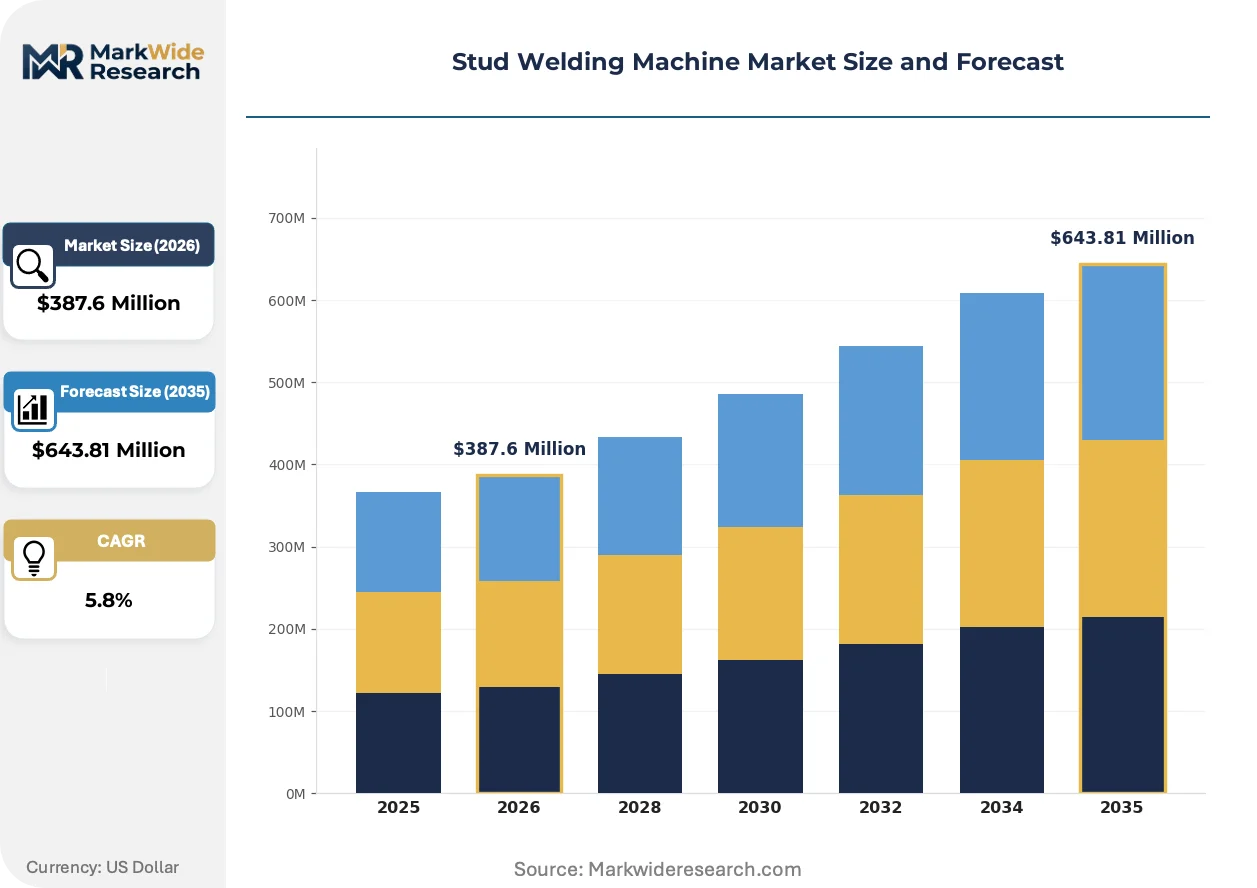
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Automatic, Robotic Technology: Short Cycle, Drawn Arc, Capacitor Discharge, TIG End User: Construction, Automotive, Manufacturing, Shipbuilding Installation: On-Site, Off-Site, Portable, Fixed |
| Companies Covered | Soyer Stud Welding, STUDMASTER, Nelson Stud Welding, Artech Welders, KÖCO Stud Welding, HBS Stud Welding, Midwest Fasteners, Image Industries, Taylor Stud Welding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stud Welding Machine Market Emerging Trajectories
Equipment architecture is fragmentating between all-in-one power source suppliers and modular system integrators, with software-defined welding parameters and cloud-based quality traceability emerging as the primary axes of differentiation.
Digital power source topology is decomposing traditional analog transformer-rectifier designs across European automotive lines. BMW and Volkswagen assembly plants are specifying inverter-based drawn-arc systems with real-time arc voltage feedback. This shift is decomposing the historical advantage of legacy equipment builders whose service revenue depended on proprietary analog component replacement.
EU machinery directive amendments are mandating functional safety integration for collaborative robotic welding cells. Equipment suppliers must now embed safety-rated monitored stops and force-limiting controls to achieve CE marking. German automotive tier-one suppliers are responding by consolidating procurement around vendors with certified safety engineering capabilities, excluding pure power-source specialists.
After-sales service unbundling is disrupting traditional distributor relationships in North American construction channels. Large steel erection contractors are negotiating direct telemetry subscriptions with equipment OEMs for predictive maintenance, bypassing local distributors who previously captured service margins. This pattern is most visible in Texas and California commercial high-rise markets where contractor consolidation has concentrated buying power.
Stud Welding Machine Market Segmentation
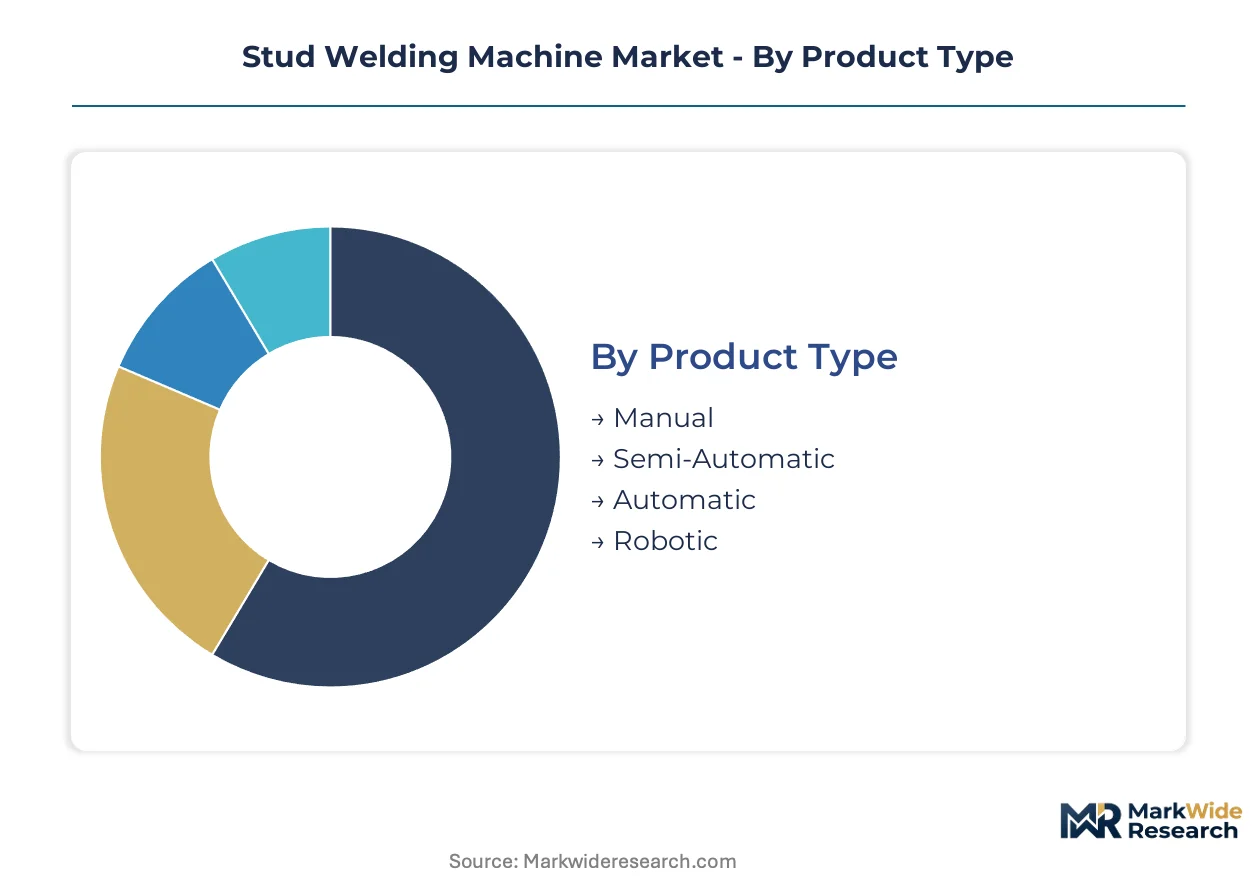
Segmentation in stud welding equipment reveals how procurement patterns split between capital-intensive automation and labor-dependent manual systems. Understanding these divisions exposes where specification power concentrates and which technology platforms command pricing leverage.
Product Type:
Margin pools concentrate in systems with embedded control software and multi-axis coordination capabilities.
- Robotic:Six-axis articulated cells with integrated vision systems and adaptive arc control dominate automotive body-in-white lines. BMW and Volkswagen assembly plants in Germany specify these for aluminum stud joining in electric vehicle platforms. CE marking requirements for collaborative safety systems elevate supplier qualification barriers.
- Automatic:Programmable single-station units with pre-set weld schedules serve high-volume construction steel erectors. Texas and California commercial high-rise contractors deploy these for repetitive deck fastening where labor cost arbitrage justifies capital deployment.
- Semi-Automatic:Operator-triggered systems with automatic stud feed bridge job-site flexibility and throughput.
- Manual:Hand-held guns with basic arc initiation remain prevalent in maintenance operations and small-batch fabrication.
Robotic systems hold installed capacity in automotive. Automatic equipment is rotating up the share rankings in commercial construction procurement.
Technology:
Volume leadership belongs to processes accommodating the broadest substrate range and thickness latitude.
- Drawn Arc:Controlled lift-arc ignition with shielding gas or ceramic ferrule protection handles carbon steel, stainless steel, and aluminum from 1 mm to 25 mm thickness. Japanese shipbuilders specify these for Class NK-compliant hull deck assembly where structural weld procedure qualification is mandatory.
- Capacitor Discharge:Stored-energy discharge through a pilot arc creates metallurgical bonds without reverse-side marking on thin sheet. German automotive tier-one suppliers deploy these for closure panel applications below 0.5 mm where cosmetic requirements are strict.
- Short Cycle:Abbreviated arc duration with reduced heat input serves medium-thickness structural applications.
- TIG:Tungsten inert gas adaptation for specialty alloys and precision repair operations.
Drawn Arc commands the largest installed base. Capacitor Discharge is climbing the fastest in automotive thin-sheet applications.
End User:
Customer concentration tracks capital expenditure cycles and regulatory compliance intensity.
- Automotive:OEMs and tier-one suppliers drive specification for inverter-based systems with real-time arc voltage feedback. Battery tray and body-in-white aluminum joining requirements under ISO 14555 are forcing equipment upgrades across German and United States production networks.
- Shipbuilding:Japanese and South Korean yards modernize deck fabrication with automated fastening to reduce labor dependency. Class NK and Korean Register structural welding rules mandate qualified procedures that favor established equipment suppliers with certification libraries.
- Construction:Steel erectors and bridge contractors face AWS D1.1 qualification burdens that delay deployment and favor incumbents.
- Manufacturing:General fabrication and appliance producers balance flexibility against repeatability requirements.
Automotive holds the densest installed capacity. Shipbuilding is gaining share fastest on fleet renewal and automation mandates.
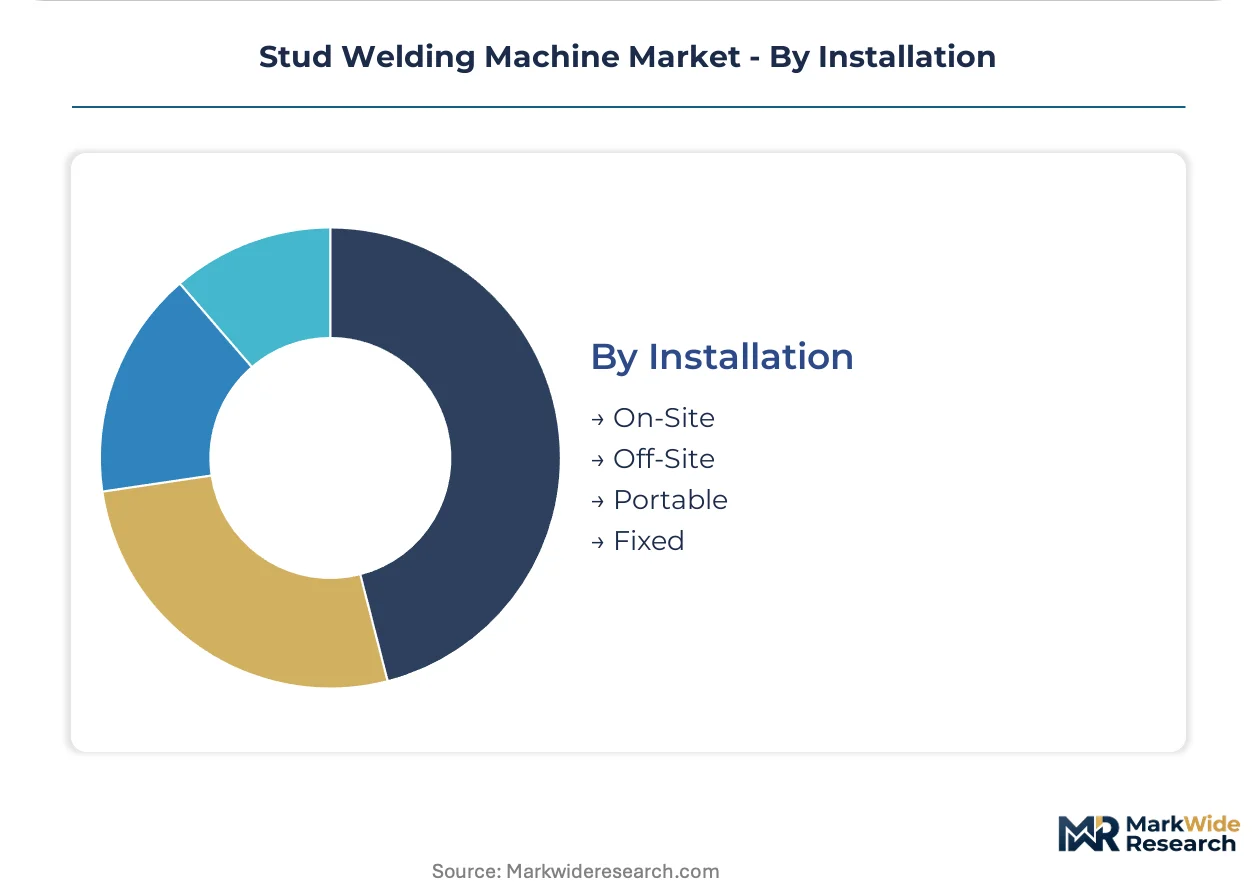
Installation:
Deployment mode selection reflects project scale, mobility requirements, and supply chain configuration.
- Fixed:Permanent line-integrated cells with dedicated power distribution and material handling dominate high-volume automotive and shipyard operations. German automotive OEMs specify these for dedicated body shop lines with decades-long depreciation horizons.
- Portable:Generator-compatible systems with wheeled chassis serve on-site construction and field repair. Indian metro rail and commercial high-rise projects under the PLI scheme for capital goods are opening procurement channels for mobile automated fastening equipment.
- Off-Site:Prefabrication yard installations with overhead crane access support modular construction workflows.
- On-Site:Direct deployment at final assembly location for bespoke structural connections.
Fixed installations retain the largest capacity base. Portable systems are expanding most quickly on infrastructure mobility requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive supply chains while cost-competitive sourcing dominates Indian infrastructure procurement. Equipment specification authority splits between Japanese shipbuilders demanding Class NK-certified systems and North American contractors navigating AWS D1.1 qualification burdens. Regulatory fragmentation across ISO 14555, CE marking, and national structural codes shapes regional deployment timelines.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify inverter-based drawn-arc systems for aluminum body-in-white assembly. CE marking under EU machinery directives mandates functional safety integration for collaborative robotic cells. Stuttgart-based tier-one suppliers consolidate procurement around vendors with certified safety engineering capabilities.
United States
Texas and California commercial high-rise contractors deploy automatic fastening equipment for repetitive deck applications. AWS D1.1 structural welding codes impose extended procedure qualification timelines that favor incumbent suppliers with established certification libraries. OSHA workplace safety standards intersect with contractor liability concerns in steel erection procurement decisions.
Japan
Shipbuilders in Nagoya and Kobe modernize hull assembly lines with automated fastening systems to reduce labor dependency. Class NK structural welding rules mandate qualified weld procedures that compress equipment replacement cycles. METI industrial policy supports automation adoption in maritime manufacturing clusters.
India
Metro rail and commercial high-rise projects under the PLI scheme for capital goods expand procurement channels for mobile automated equipment. BIS certification requirements for welding equipment create specification barriers for unqualified imports. Maharashtra and Gujarat fabrication yards concentrate demand for generator-compatible portable systems.
South Korea
Hyundai Heavy Industries and DSME drive specification for thick-plate deck welding in Ulsan and Geoje shipyards. Korean Register structural rules parallel Class NK requirements in mandating procedure-qualified equipment. Busan-Ulsan industrial corridor anchors automated fastening deployment in fleet renewal programs.
Stud Welding Machine Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the stud welding machine landscape. European specialists command premium positioning through vertical integration in power-source engineering and safety-certified control systems. Asian fabricators compete on scale economics and adaptation to local voltage and regulatory environments. Two strategic archetypes dominate: automation-integrated system builders serving automotive OEMs, and power-source specialists distributing through construction equipment channels. Competitive dynamics center on M&A activity consolidating control system capabilities and geographic expansion through distributor network acquisition.
Among German precision engineering houses, KÖCO Stud Welding GmbH and Soyer Stud Welding occupy positions exemplifying vertical integration into arc welding power sources and European industrial channel control. Nelson Stud Welling anchors North American representation through extensive distributor networks. HBS Stud Welding and Taylor Stud Welding sit within the specialist tier serving regional construction and automotive fabrication markets. STUDMASTER, Artech Welders, and Image Industries represent mid-scale fabricators competing on equipment adaptability and aftermarket service proximity. Midwest Fasteners distributes through construction supply channels rather than manufacturing direct relationships.
| Leading Market Players |
|---|
| Soyer Stud Welding |
| STUDMASTER |
| Nelson Stud Welding |
| Artech Welders |
| KÖCO Stud Welding |
| HBS Stud Welding |
| Midwest Fasteners |
| Image Industries |
| Taylor Stud Welding |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements between German automotive OEMs and inverter power-source suppliers lock in copper and silicon steel access while stabilizing unit economics across volatile commodity cycles. These arrangements concentrate procurement leverage among tier-one suppliers in Bavaria and Baden-Württemberg who can commit to multi-year offtake volumes.
Pricing Analysis
Configured-to-order pricing for robotic stud welding cells commands a 40-60% premium over standard automatic equipment due to embedded safety controllers and vision integration. Three-tier pricing structure across premium certified systems, standard programmable units, and economy manual guns reflects ISO 14555 and CE marking compliance tiers. Cost compression in the manual equipment tier is intensifying because Asian fabricators are flooding construction channels with unbundled power sources. Small-batch fabrication shops exhibit highest price sensitivity, while automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Inbound logistics costs from East Asian semiconductor foundries through Rotterdam and Hamburg ports have elevated lead times for IGBT modules and control boards feeding German power-source manufacturers. Production concentrates in Germany, Japan, and China, with transformer core laminations drawing from Japanese silicon steel mills and Chinese copper refineries. Single-source vulnerability in high-frequency inverter components creates exposure to Taiwan Strait logistics disruption. Distribution runs through authorized distributor networks in North American construction channels and direct OEM relationships in European automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stud welding machine market is experiencing high-growth disruption as ISO 14555 compliance mandates and aluminum body-in-white assembly requirements force equipment replacement cycles across automotive and steel construction end users.
For Market Incumbents: Consolidate control system capabilities through targeted acquisitions of safety engineering specialists to meet EU machinery directive amendments for collaborative robotic cells. Expand captive supply arrangements for copper and silicon steel to defend margin position against commodity volatility. Anchor certification library investments to extend AWS D1.1 qualification advantages in North American structural contracting.
For New Entrants and Emerging Players: CE marking fast-track partnerships with Stuttgart-based tier-one suppliers offer the most penetrable entry point for inverter-based drawn-arc systems. Target Indian metro rail and commercial high-rise projects under the PLI scheme for capital goods with generator-compatible portable automatic equipment. Lead with predictive maintenance telemetry subscriptions to bypass entrenched distributor relationships in Texas and California commercial construction markets.
For Investors and Strategic Acquirers: Capital is best deployed toward automation-integrated system builders with certified safety engineering capabilities and established automotive OEM relationships. Long-term viability over the projection horizon rests on software-defined welding parameters and cloud-based quality traceability differentiation. Monitor Class NK and Korean Register structural welding rule amendments as inflection indicators for fleet renewal-driven equipment demand in Japanese and South Korean shipbuilding clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Semiconductor Sourcing | Captive IGBT module supply secures margin control against Taiwan Strait logistics chokepoints. |
| Safety Controller Certification Investment | CE marking compliance for collaborative robotic cells unlocks BMW and Volkswagen procurement channels. |
| Predictive Maintenance Telemetry Platform | Direct OEM-contractor subscriptions bypass distributor margins in Texas commercial high-rise markets. |
| Aluminum Welding Procedure Qualification Library | ISO 14555-certified processes capture electric vehicle battery tray assembly specifications. |
| Indian PLI Scheme Localization Partnership | Maharashtra and Gujarat fabrication yard access leverages infrastructure build-out procurement channels. |
Methodological Framework
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and distributor channel managers anchors the qualitative findings in operational reality. Secondary validation draws from SEC 10-K filings of listed industrial equipment manufacturers, customs and trade data on welding equipment imports, ISO and AWS certification registries, and automotive production databases. Bottom-up equipment shipment analysis triangulates against top-down capital expenditure modeling across end-use industries.
Sensitivity analysis around copper and silicon steel price trajectories, automation adoption rates, and regulatory amendment timelines shapes the analytical framework. Segmentation dimensions span product type, technology platform, end-user industry, and installation mode, with regional regulatory clusters modeled separately. CAGRs derive from installed base replacement cycles, fleet expansion in shipbuilding, and infrastructure investment patterns. Aluminum body-in-white penetration rates and Class NK procedure qualification velocity serve as industry-specific demand drivers.
Underlying assumptions cover continued ISO 14555 enforcement intensity, CE marking automation integration requirements, and AWS D1.1 qualification burden persistence, with deviation risk concentrated in commodity input volatility and certified welding engineer scarcity constraining automated system deployment. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hand Push Trencher Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Case Erectors Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Casting Equipment Market
Construction Equipment
Construction Pump Market
Construction Equipment
Bulldozer Market
Construction Equipment
Hoist and Winches Market
Construction Equipment
Cold Forming Equipment Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Suction Excavator Market