
 (AWP) Aerial Work Platform Rental Market | 2026-2036
(AWP) Aerial Work Platform Rental Market Size, Share, and Industry Trends Forecast 2026-2036
(AWP) Aerial Work Platform Rental Market Analysis
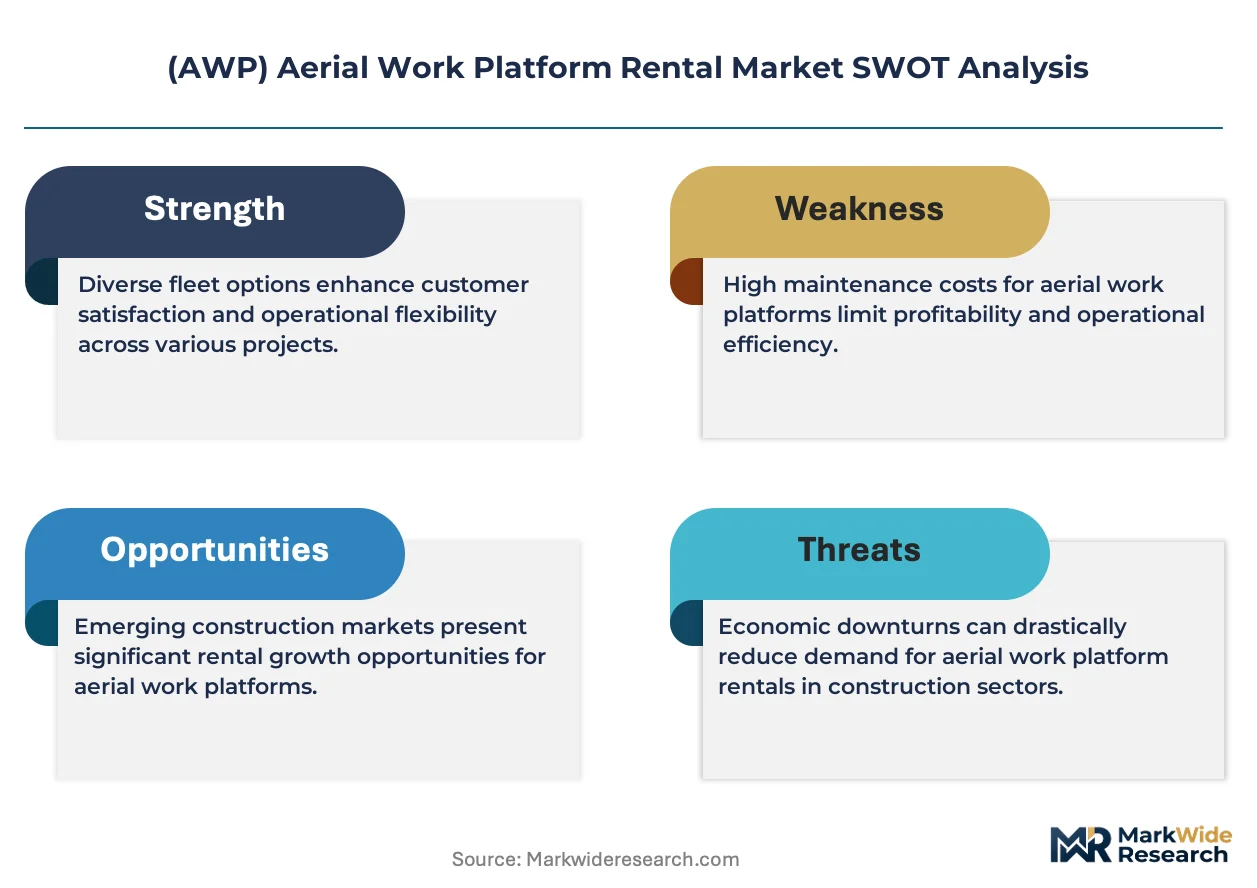
Data center construction is reorganizing demand patterns in the AWP rental sector, pulling fleet operators toward longer-term contracts with technology and logistics clients. United Rentals leverages its North American branch density to capture this shift, while Loxam anchors European infrastructure projects through its specialized high-reach fleet. Sunbelt Rentals differentiates via integrated maintenance services that reduce contractor downtime on complex installations.
An aerial work platform is a mobile elevating device with articulated, telescopic, or scissor mechanisms designed to lift personnel and tools to elevated work zones, typically operating at heights from 20 to 180 feet with load capacities between 500 and 1,000 pounds. Boom lifts dominate capital allocation among rental fleets due to their versatility across uneven terrain and structural reach requirements. Scissor lifts compete aggressively on daily rental rates in maintenance and installation applications where vertical elevation suffices. Short-term rental contracts capture the highest fleet utilization rates in event staging and emergency repair segments.
ANSI A92 standards in the United States mandate load-sensing and tilt-protection systems that filter non-compliant equipment from active rental pools. The EU Machinery Directive and CE marking requirements impose design conformity obligations that shape manufacturer-RFP alignment across European procurement. OSHA inspection protocols and the EPA's phase-in of Tier 4 Final emissions standards for off-road diesel engines compound fleet replacement decisions. Stakeholders must weigh electrification timelines against residual value risk in internal combustion units as regulatory thresholds tighten.
Market Dynamics
ANSI A92 standards and the EU Machinery Directive are filtering non-compliant equipment from active rental pools, forcing fleet operators into accelerated replacement cycles while electrification timelines compress residual value calculations for diesel units.
Growth Catalysts
- Data center construction:Hyperscale facility builds across Germany, the United States, and China are pulling rental fleets toward multi-year contracts with technology and logistics clients, extending asset utilization windows beyond traditional construction cycles.
- Tier 4 Final emissions standards:EPA phase-in requirements for off-road diesel engines are mandating fleet modernization, creating replacement demand even where mechanical life remains.
- Telematics integration:IoT-enabled fleet management systems are optimizing equipment deployment, reducing idle time, and enabling predictive maintenance that extends asset service life.
Market Restraints
- Steel and aluminum input volatility:Boom and scissor lift manufacturing depends on commodity metal pricing that fluctuates with energy costs, compressing manufacturer margins and translating into higher rental rates.
- Battery supply concentration:Lithium-ion cell production for electric AWPs clusters in China, exposing European and North American fleet operators to supply chain disruption risk and tariff exposure.
- Height limitations on scissor platforms:Structural engineering constraints cap scissor lift reach below boom alternatives, limiting addressable work zones in high-rise construction and wind turbine maintenance.
Strategic Opportunities
- India infrastructure buildout:National highway expansion and urban metro projects are creating first-mover advantages for rental operators establishing depot networks in secondary cities.
- CE marking alignment:Harmonized EU conformity assessment procedures are reducing certification duplication costs for manufacturers serving multiple member states, accelerating cross-border fleet mobility.
- Hybrid powertrain convergence:Integration of battery-electric and range-extender technologies is opening indoor-outdoor versatility segments previously split between dedicated equipment classes.
Industry Challenges
- Certified technician scarcity:ANSI A92 and EU Machinery Directive compliance requires specialized maintenance training that outpaces vocational program output, extending equipment downtime during peak demand periods.
- Legacy fleet integration complexity:Telematics retrofits and electrification conversions on pre-Tier 4 diesel units demand engineering resources that divert attention from new product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | (AWP) Aerial Work Platform Rental Market |
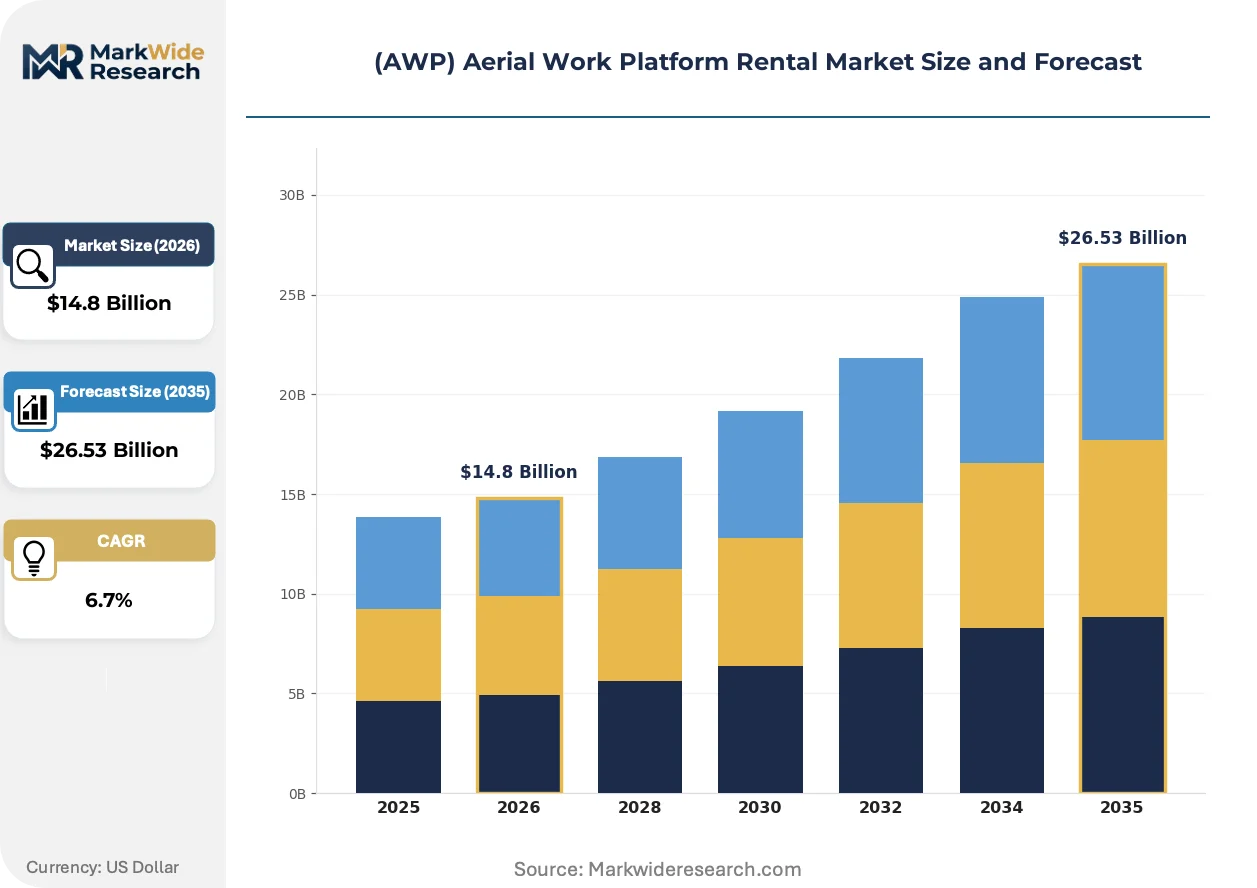
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boom Lifts, Scissor Lifts, Vertical Mast Lifts, Personnel Lifts End User: Construction, Telecommunications, Events, Maintenance Application: Facade Work, Installation, Cleaning, Inspection Service Type: Short-Term Rental, Long-Term Rental, Maintenance Services, Transport Services |
| Companies Covered | Ashtead Group, Boels Rental, United Rentals, Aktio Holdings Corp., Loxam, Sunbelt Rentals, Herc Rentals, Kilotou, Horizon Construction Development, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
(AWP) Aerial Work Platform Rental Market Emerging Trajectories
Electrification and autonomous positioning systems are compressing the operational gap between indoor scissor lifts and outdoor boom platforms, while data center construction is redefining contract structures across the rental sector.
Lithium-ion battery packs with integrated thermal management are supplanting lead-acid and combustion powertrains in mid-reach boom lifts. Data center contractors in Northern Virginia and Frankfurt are specifying all-electric fleets for indoor white-space installation. This shift is compressing the residual value premium previously commanded by diesel versatility.
OSHA inspection protocols and EPA Tier 4 Final emissions standards are tightening equipment eligibility for active rental pools. Fleet operators face accelerated depreciation schedules on non-compliant internal combustion units. The United States market is responding through lease-back arrangements that transfer residual value risk to manufacturers.
Long-term master service agreements are displacing spot rental contracts in data center and logistics verticals. Technology sector procurement teams are consolidating vendor relationships into three-year frameworks with guaranteed availability clauses. This concentration is most visible in Phoenix and Amsterdam, where hyperscale construction clusters have formed.
(AWP) Aerial Work Platform Rental Market Segmentation
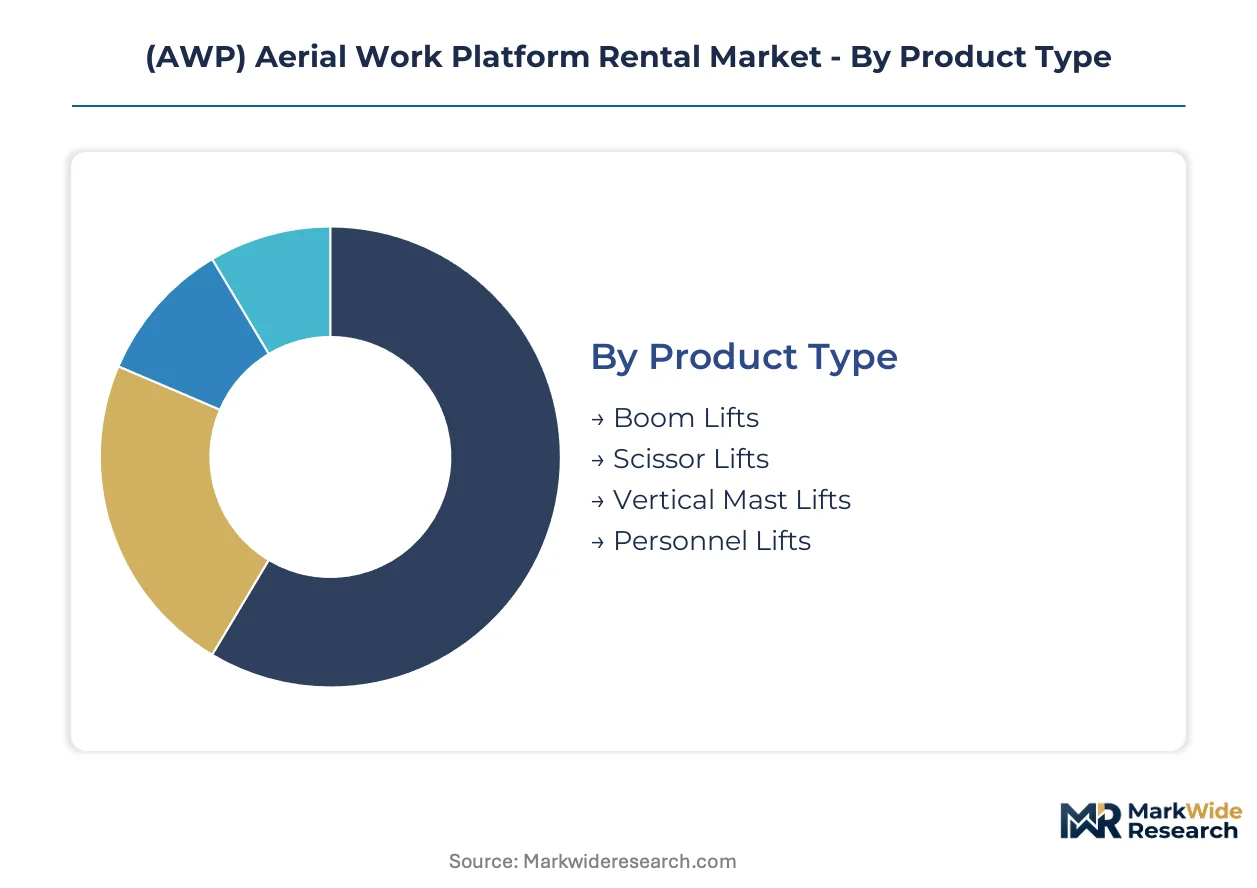
Rental fleet composition and contract duration vary sharply across product categories and end-use verticals. Understanding these splits enables operators to optimize depot placement and capital deployment against utilization patterns.
Product Type:
Domestic fleet concentration in Germany and the United States favors boom and scissor configurations, while vertical mast and personnel lifts flow disproportionately through export channels into emerging infrastructure markets.
- Boom Lifts:Articulated and telescopic booms with 40- to 180-foot reach handle uneven terrain and horizontal outreach requirements. Fleet operators in Northern Virginia and Frankfurt data center corridors are standardizing on all-electric booms for indoor-outdoor versatility.
- Scissor Lifts:Vertical-only elevation platforms with load ratings of 500-1,000 pounds dominate maintenance and installation work. German rental pools favor narrow-slab electric scissors for urban logistics facilities where floor loading limits apply.
- Vertical Mast Lifts:Compact single-mast platforms with sub-30-foot reach serve confined warehouse aisles and retail fit-outs. Demand concentrates in Dutch distribution hubs and Japanese compact construction sites.
- Personnel Lifts:Push-around and self-propelled units for one-operator tasks below 20 feet. These units see highest rotation rates in event staging and facility management contracts across secondary Chinese cities.
Boom lifts hold the largest share; momentum sits with scissor lifts as electrification compresses the performance gap.
End User:
Volume concentration tilts toward construction, but margin expansion tracks telecommunications and events where specialized equipment commands rate premiums.
- Construction:General building, civil infrastructure, and industrial projects drive baseline fleet utilization. Hyperscale data center contractors in Phoenix and Amsterdam are pulling multi-year master service agreements that extend asset depreciation schedules.
- Telecommunications:5G tower installation and fiber optic maintenance require compact rough-terrain booms. Tower companies in rural Texas and Bavaria favor rental over ownership to manage seasonal deployment spikes.
- Events:Concert staging, sports broadcasting, and exhibition rigging demand rapid-response short-term contracts. London and Las Vegas event clusters generate peak utilization rates exceeding 90% during festival seasons.
- Maintenance:Facility management and industrial turnaround work favors electric scissors for indoor HVAC and lighting service. Japanese automotive plants and German chemical complexes drive specification for zero-emission indoor units.
Construction anchors volume; telecommunications and events are climbing the fastest as contract structures lengthen.
Application:
Facade work and installation absorb heavy-reach equipment, while cleaning and inspection segments fragment across lighter, more mobile platforms.
- Facade Work:Exterior cladding, glazing, and restoration on high-rise structures. Frankfurt and Singapore skyscraper maintenance contracts specify boom lifts with dual-fuel capability for emissions-sensitive districts.
- Installation:Mechanical, electrical, and data infrastructure fit-out. Data center white-space contractors in Northern Virginia mandate all-electric fleets to protect sensitive server environments.
- Cleaning:Window washing and building envelope maintenance. UK facilities management providers bundle scissor lift rentals into integrated service contracts with guaranteed response windows.
- Inspection:Bridge, wind turbine, and industrial asset assessment. German wind energy operators favor compact crawler-mounted booms for turbine blade access in remote terrain.
Installation commands the largest equipment allocation; facade work is gaining share fastest as building envelope retrofits accelerate.
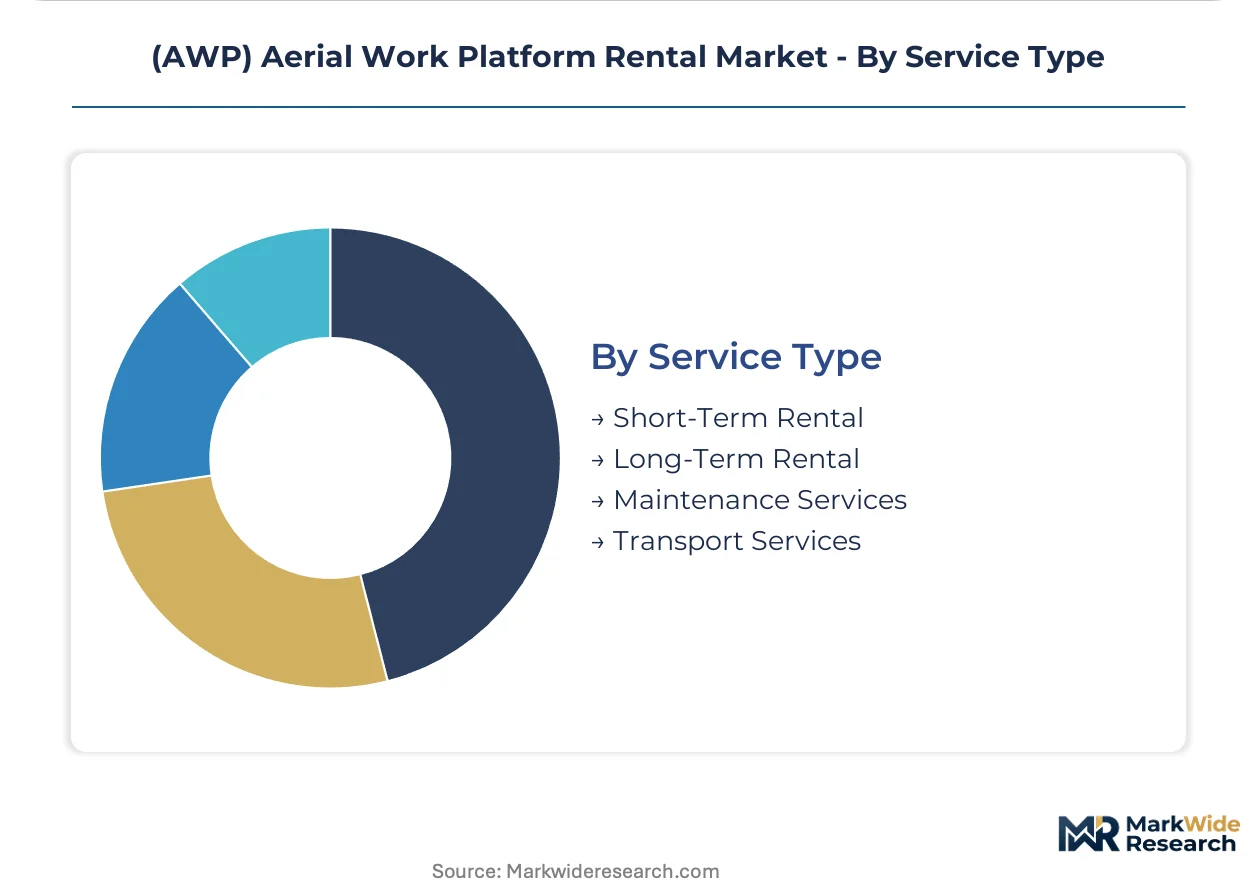
Service Type:
Contract duration and value-added bundling separate premium service tiers from commodity spot rentals.
- Short-Term Rental:Daily and weekly contracts for emergency repair, event staging, and project peaks. Phoenix data center construction corridors see 72-hour average turnaround requirements during buildout phases.
- Long-Term Rental:Multi-year frameworks with guaranteed availability clauses. Technology sector procurement teams in Amsterdam and Northern Virginia are consolidating vendor relationships into 36-month agreements.
- Maintenance Services:Preventive and corrective service bundled with equipment access. German rental operators differentiate through ANSI A92-certified technician networks that reduce contractor downtime.
- Transport Services:Logistics and site delivery coordination. UK infrastructure projects increasingly specify transport-inclusive pricing to manage just-in-time delivery to constrained urban sites.
Short-term rental holds the largest share; long-term rental and bundled maintenance are expanding most quickly as procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northern Virginia data center corridor underwrites the United States' position as the dominant AWP rental geography, with Frankfurt's Mainova grid interconnect anchoring European fleet deployment patterns.
United States
Hyperscale data center construction in Loudoun County and Phoenix pulls rental fleets toward multi-year master service agreements. OSHA inspection protocols and EPA Tier 4 Final emissions standards filter non-compliant diesel units from active pools. Northern Virginia contractors now specify all-electric boom fleets for indoor white-space installation.
Germany
Wind turbine maintenance and chemical complex turnarrows drive demand for compact crawler-mounted booms. The EU Machinery Directive and CE marking requirements impose design conformity obligations that shape manufacturer alignment. Frankfurt's skyline maintenance contracts specify dual-fuel capability for emissions-sensitive districts.
China
National highway expansion and urban metro projects in secondary cities create first-mover advantages for depot network establishment. GB standards and MIIT industrial policy guide domestic equipment certification. Yangtze River Delta manufacturing clusters feed both domestic rental pools and export channels.
India
National infrastructure pipeline projects and smart city initiatives concentrate demand in Maharashtra and Gujarat. The central government's PLI scheme for construction equipment manufacturing attracts component localization. Mumbai-Pune industrial corridor rental operators face certified technician scarcity during peak monsoon repair seasons.
United Arab Emirates
Expo legacy infrastructure and NEOM northwest development sustain premium-rate long-term contracts. The country's national construction regulator mandates third-party inspection protocols for elevated work platforms. Dubai's logistics free zones pull electric scissor lift deployments for warehouse fit-out at scale.
(AWP) Aerial Work Platform Rental Market Vendor Landscape
Concentration sits with North American and European rental networks that combine branch density with integrated maintenance capabilities. Three archetypes dominate: scale-driven fleet aggregators with multi-regional depot networks, specialized high-reach operators serving infrastructure megaprojects, and technology-sector-focused providers bundling telematics with guaranteed availability clauses. Competitive moves center on lease-back arrangements that transfer residual value risk to manufacturers, and strategic partnerships with data center contractors seeking multi-year framework agreements.
Among UK-based rental networks, Ashtead Group and its Sunbelt Rentals subsidiary occupy positions exemplifying scale-driven fleet aggregation across North American branch networks. Loxam anchors the European specialized tier through its high-reach fleet concentration in infrastructure corridors. United Rentals represents the technology-sector procurement vector, with master service agreements consolidating vendor relationships into guaranteed availability frameworks.
| Leading Market Players |
|---|
| Ashtead Group |
| Boels Rental |
| United Rentals |
| Aktio Holdings Corp. |
| Loxam |
| Sunbelt Rentals |
| Herc Rentals |
| Kilotou |
| Horizon Construction Development |
| Others |
Supply Flow & Price Mechanics
Three-month order-to-delivery windows for boom lift chassis concentrate pricing power with Chinese steel fabricators and German hydraulic component suppliers, compressing margins for rental operators unable to lock forward contracts. This lead-time structure rewards fleet aggregators with balance sheet depth while fragmenting procurement leverage across regional independents.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the rental market by equipment age, certification tier, and bundled service intensity. Premium tiers capture ANSI A92-compliant electric booms with telematics integration and guaranteed uptime clauses; economy tiers trade at daily rates 40% below on pre-Tier 4 diesel units with spot availability. Price differentiation hinges on CE marking alignment and after-sales technician density. Cost compression in the economy tier is intensifying because residual value risk on legacy diesel fleets accelerates depreciation schedules. Event staging contractors exhibit highest price sensitivity; data center procurement teams prioritize availability guarantees over rate negotiation.
Supply Chain Analysis
Just-in-time inventory strategies dominate European and North American fleet procurement, though Tier 4 Final compliance deadlines have pushed some operators toward strategic stockpiling of pre-certified diesel units. Manufacturing concentrates in China for lithium-ion battery packs and steel structural components, Germany for precision hydraulics and control systems, and the United States for final assembly and telematics integration. Raw material dependencies span high-strength steel plate, aluminum extrusions, and lithium carbonate cathode material. Supply chain risk centers on single-source vulnerability for battery cell production clustered in the Yangtze River Delta. Distribution runs through manufacturer-direct channels for large fleet orders and regional depot networks for spot rental fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician pipelines are failing to match ANSI A92 and EU Machinery Directive compliance requirements, creating a structural bottleneck that determines competitive viability more than fleet scale alone. This capability gap rewards operators who control training infrastructure and technician deployment networks.
For Market Incumbents: Fortify maintenance service capabilities through captive technician training programs and backward integration into parts distribution. Electrification timelines threaten residual values on diesel-heavy legacy fleets; lease-back arrangements with manufacturers transfer this risk while preserving fleet liquidity. Priority investment belongs to telematics platforms that enable predictive maintenance and guaranteed uptime pricing. For New Entrants and Emerging Players: Anchor in India's secondary city infrastructure corridors where depot network density remains thin and national highway expansion creates sustained equipment demand. White-space opportunity concentrates in hybrid powertrain rental offerings that bridge indoor-outdoor versatility gaps. Go-to-market execution should prioritize transport-inclusive pricing bundles that address just-in-time delivery requirements on constrained urban construction sites. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because branch density and technician networks exhibit strong returns to scale while remaining locally defensible. Target acquisition archetype: regional operators with established depot footprints and ANSI A92-certified maintenance capabilities in data center construction corridors. The signal to watch is technology sector procurement team consolidation into multi-year master service agreements with guaranteed availability clauses.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Fleet Conversion | EPA Tier 4 Final deadlines and data center indoor specifications are mandating battery-electric procurement. |
| Technician Training Certification | ANSI A92 compliance requirements outpace vocational program output, creating captive capability premiums. |
| Telematics Platform Integration | IoT-enabled predictive maintenance extends asset service life and enables guaranteed uptime contracting. |
| Long-Term Master Service Agreements | Technology sector procurement teams are consolidating vendor relationships into 36-month availability frameworks. |
| Depot Network Expansion | India's national infrastructure pipeline rewards first-mover establishment in secondary cities. |
Methodological Framework
A standing panel of fleet operations directors, OEM procurement managers, and data center construction project managers provided ongoing calibration against order book fluctuations and utilization rate shifts. Primary interviews with maintenance service heads and telematics platform engineers were cross-referenced against secondary validation from SEC 10-K filings, customs trade data on aerial platform imports, and OSHA enforcement records. Bottom-up equipment deployment counts triangulated with top-down rental revenue estimates across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs before finalization. The analytical framework modeled segmentation across product type, end-use vertical, contract duration, and regional regulatory cluster throughout the forecast period. CAGRs were derived from equipment replacement cycles, infrastructure investment pipelines, and electrification adoption curves. Industry-specific forecast inputs included data center construction permit flows and wind turbine maintenance scheduling patterns.
Material uncertainties — commodity metal price volatility, battery supply disruption, and regulatory compliance deadline shifts — sit outside the modeled envelope. Forecasts reflect assumptions about technician training pipeline expansion and technology sector capital expenditure continuity. Revision becomes warranted when lithium-ion cell supply concentration or steel input cost spikes cross thresholds that alter fleet procurement economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Global Concrete Curing Equipment Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Industrial Agitators Market
Construction Equipment
Derinding Machines Market
Construction Equipment
BRICS Aerial Work Platforms Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
Overhead Cranes Market