
 GCC Construction Machinery Market | 2026-2036
GCC Construction Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Construction Machinery Market Foresight
UAE's Al Sa'fat green building regulation is hardening emissions thresholds for construction equipment deployed on federal contracts. Caterpillar sustains its dealer network density across the six GCC states, ensuring rapid parts availability in remote project zones. XCMG Construction Machinery Co. Ltd. leverages cost-optimized hydraulic excavator platforms to compete aggressively on Saudi giga-project tenders. J.C. Bamford Excavators Ltd (JCB) anchors its position through compact equipment specialization suited to urban infill work in Dubai and Doha.
Construction machinery encompasses powered equipment designed for earthmoving, material handling, and structural assembly, typically operating at hydraulic pressures exceeding 300 bar and engine outputs ranging from 50 to 500 horsepower for heavy-class units. Its primary purpose is to mechanize site preparation, vertical construction, and material transport across civil engineering and building projects. Excavators dominate fleet composition across GCC rental pools due to versatility in trenching, lifting, and demolition sequences. Diesel technology retains overwhelming installed base share despite pilot electric deployments, though hybrid systems are gaining traction on enclosed urban sites where noise and particulate restrictions apply. Infrastructure Development commands the largest application share, driven by sovereign wealth-funded transport corridors and utility networks spanning Saudi Arabia, the UAE, and Qatar.
Saudi Standards, Metrology and Quality Organization (SASO) and the UAE's Ministry of Industry and Advanced Technology enforce equipment safety certification and emissions conformity for machinery imports, while Qatar's Public Works Authority mandates operator telemetry reporting on public sites. These frameworks elevate total cost of ownership for non-compliant fleets and create regulatory differentiation between established distributors and gray-market suppliers. Stakeholders must monitor how Bahrain and Oman's adoption of Gulf Technical Regulation for construction machinery harmonization affects cross-border equipment mobility and resale values.
Market Dynamics
Sovereign wealth deployment into linear city megaprojects is compressing equipment replacement cycles and forcing fleet standardization across Saudi Arabia's western corridor. Rental pooling and telematics integration are restructuring ownership economics for earthmoving contractors.
Growth Catalysts
- NEOM and Red Sea giga-projects:Linear city construction requires specialized crawler excavator fleets with extended-reach configurations. Procurement volumes concentrate in Saudi Arabia's Tabuk and Medina provinces.
- UAE's Al Sa'fat green building mandate:Federal contracts now enforce emissions thresholds that filter non-compliant machinery from tender eligibility. Equipment distributors are pre-certifying hybrid and Stage V-compliant units.
- Telematics integration:Real-time fuel monitoring and predictive maintenance protocols are reducing idle-time losses on remote desert sites. Adoption spreads fastest among rental fleet operators.
Market Restraints
- Steel and hydraulic component volatility:Input cost swings compress margin predictability for OEMs assembling heavy-class units above 300 bar operating pressure.
- Dealer network concentration:Parts availability depends on distributor density that thins beyond 200 kilometers from Riyadh or Dubai, stranding equipment in Najran or Al Dhahira.
- Diesel technology lock-in:Electric powertrains face range and charging infrastructure gaps on off-grid giga-project sites, delaying zero-emission fleet transitions.
Strategic Opportunities
- Oman's infrastructure corridor:Port and logistics hub investments around Duqm are generating first-mover positioning for compact equipment specialists.
- Retrofit telematics packages:Aftermarket sensor installation on legacy diesel fleets opens recurring revenue streams independent of new unit sales.
- Bahrain's regulatory harmonization:Adoption of Gulf Technical Regulation for construction machinery is simplifying cross-border resale and reducing compliance fragmentation.
Industry Challenges
- Operator telemetry certification:Qatar's Public Works Authority mandates real-time reporting that requires retraining programs for site supervisors unfamiliar with data-dashboard interpretation.
- Fleet reconfiguration timelines:Giga-project scale-up demands compress procurement-to-deployment windows, straining logistics capacity for oversized transport permits.
Report Scope
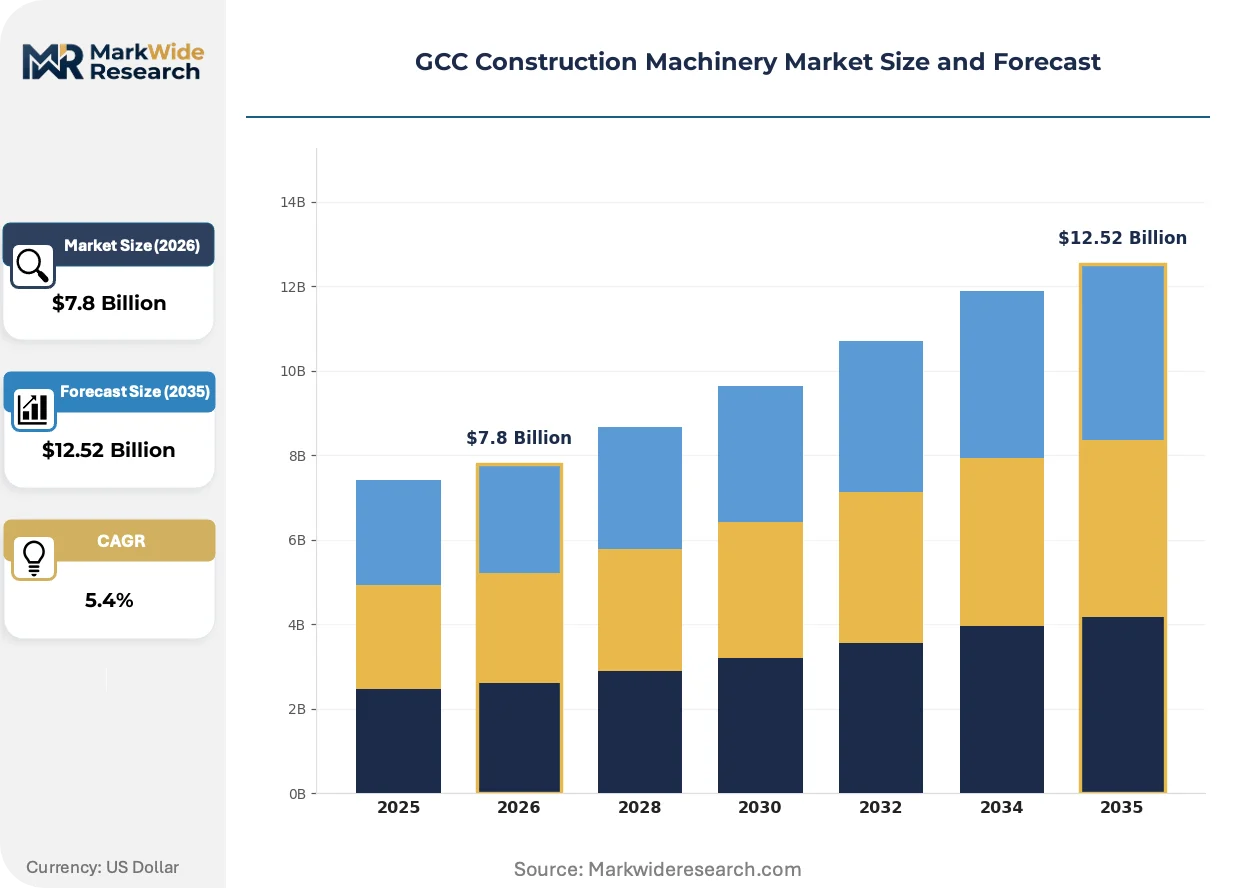
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Construction Machinery Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Cranes, Bulldozers, Loaders, Compactors Technology: Hydraulic, Pneumatic, Electric, Diesel, Hybrid Application: Infrastructure Development, Residential Construction, Commercial Projects, Oil & Gas Facilities, Mining Operations End User: Contractors, Equipment Rental Companies, Government Agencies, Developers, Construction Firms |
| Companies Covered | XCMG Construction Machinery Co. Ltd., Hitachi Construction Machinery Co. Ltd., Caterpillar Inc., J.C. Bamford Excavators Ltd (JCB), SANY Heavy Industry Co. Ltd., Komatsu Ltd., AB Volvo (Volvo Construction Equipment), Hyundai Construction Equipment Co. Ltd., Liebherr International AG, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Construction Machinery Market Shifts & Advancements
Electrification pathways and digital fleet management are converging to reshape equipment specification standards across GCC procurement offices. Technology choices made in 2024-2025 will lock in operational architectures for decade-long depreciation cycles.
Hybrid powertrain architectures are unifying diesel reliability with electric torque response for enclosed urban demolition sites. Dubai-based contractors facing noise ordinances in downtown districts are specifying these configurations for after-hours work windows. The technology is compressing the performance gap between conventional and zero-emission alternatives, extending equipment utility across regulatory boundaries.
Saudi Standards, Metrology and Quality Organization certification requirements for imported machinery are hardening safety and emissions testing protocols. Non-compliant units face port detention and resale value collapse, elevating due diligence costs for gray-market suppliers. Western Region project developers are prioritizing pre-certified inventory to avoid SASO inspection delays that stall site mobilization.
Rental pooling with integrated maintenance guarantees is displacing direct ownership among mid-tier contractors facing balance sheet constraints. Equipment-as-a-service contracts now bundle telematics, fuel management, and operator training into single monthly rates. This model concentrates fastest in Doha's urban infill sector where project duration uncertainty makes depreciation risk unacceptable.
GCC Construction Machinery Market Segmentation
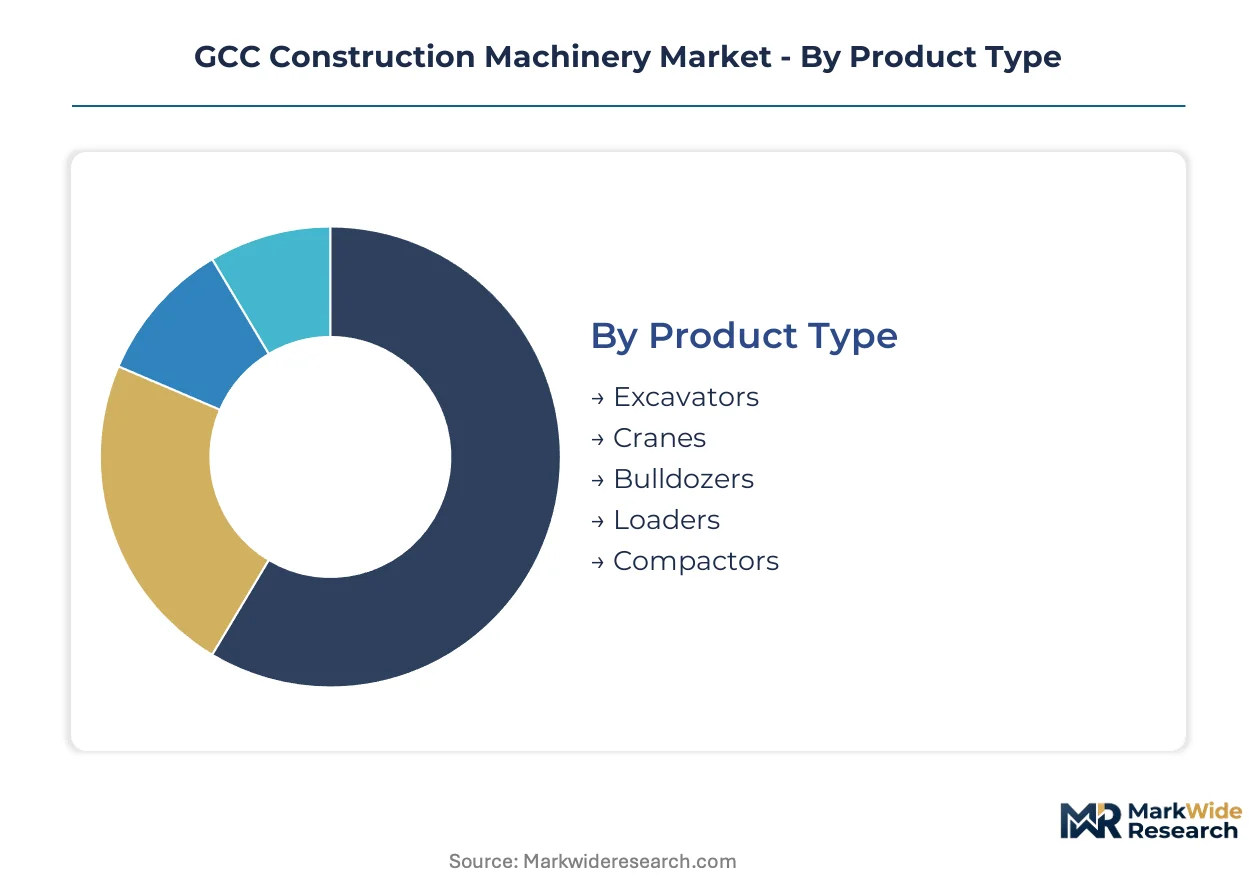
Equipment specification standards in the GCC diverge sharply between remote giga-project sites and dense urban cores. Procurement officers segment fleets by powertrain compatibility with local emissions enforcement and by mobility requirements across desert versus infill conditions.
Product Type:
Standalone earthmoving units dominate fleet investment, while lifting and compaction equipment increasingly embed into integrated site systems.
- Excavators:Crawler-mounted units with operating weights above 20 tonnes handle bulk earthworks across NEOM's linear city trenches. Saudi Arabia's western corridor concentrates procurement of extended-reach configurations for deep foundation work.
- Cranes:Tower and mobile variants above 100-tonne capacity serve vertical construction phases on Dubai's high-rise clusters. UAE contractors facing Al Sa'fat green building mandates now specify hybrid-powered units for enclosed downtown sites.
- Bulldozers:Track-type tractors with blade capacities exceeding 15 cubic meters clear overburden on Saudi giga-project plateaus.
- Loaders:Wheel loaders below 10-tonne payload dominate Qatar's urban infill material handling.
- Compactors:Vibratory drum units achieve specified soil density on Red Sea coastal reclamation zones.
Excavators lead volumes today; hybrid powertrain variants across all product types are gaining share fastest.
Technology:
Cost tiers separate mature hydraulic and diesel platforms from emerging electric and hybrid architectures with higher upfront capital requirements.
- Hydraulic:Systems operating above 300 bar pressure remain the default for heavy-class earthmoving across GCC rental pools. Reliability in abrasive desert conditions sustains dominance despite efficiency penalties.
- Diesel:Compression-ignition engines retain overwhelming installed base share on off-grid giga-project sites lacking charging infrastructure. SASO emissions certification requirements now filter non-compliant imports at Saudi ports.
- Hybrid:Diesel-electric architectures deliver torque response for urban demolition while meeting Dubai noise ordinances. Adoption concentrates among contractors with federal UAE contract eligibility.
- Electric:Battery-powered units face range constraints on remote Saudi sites but deploy in Doha's compact urban cores.
- Pneumatic:Compressed-air systems serve specialized tunneling applications on Qatar's utility networks.
Diesel technology anchors current fleet composition; hybrid systems are expanding most quickly in municipal contract segments.
Application:
Volume concentration varies by sovereign wealth deployment intensity, with linear infrastructure commanding multi-year equipment commitments.
- Infrastructure Development:Transport corridors and utility networks across Saudi Arabia, the UAE, and Qatar absorb the largest equipment volumes. NEOM and Red Sea giga-projects compress replacement cycles for specialized earthmoving fleets.
- Residential Construction:Mid-rise clusters in Riyadh's northern expansion and Dubai's suburban corridors drive compact equipment demand. Project duration uncertainty accelerates rental pooling adoption.
- Commercial Projects:High-rise developments in Doha and Abu Dhabi specify crane-intensive lifting configurations.
- Oil & Gas Facilities:Maintenance turnarounds on Saudi Aramco sites require explosion-proof machinery certifications.
- Mining Operations:Quarry extraction in the UAE's northern emirates deploys heavy-class loaders and haul trucks.
Infrastructure Development represents the dominant application today; Residential Construction is climbing the fastest as Saudi mortgage subsidy programs expand.
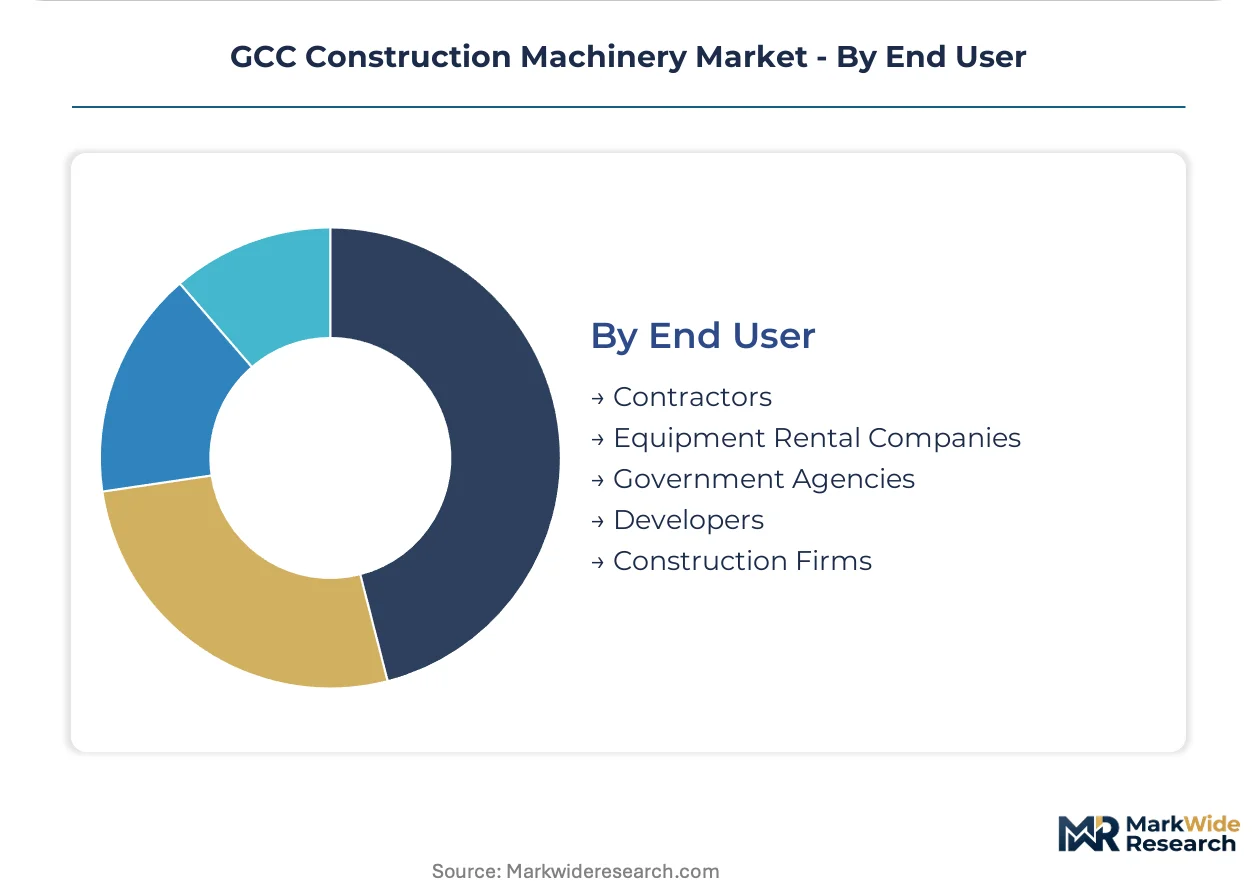
End User:
Customer type determines ownership economics, with balance sheet capacity separating rental-dependent mid-tier contractors from fleet-owning majors.
- Equipment Rental Companies:Fleet operators bundle telematics, maintenance, and operator training into monthly service contracts. Telematics integration spreads fastest among Doha-based rental pools serving urban infill uncertainty.
- Contractors:Mid-tier earthmoving specialists face capital constraints that displace direct ownership toward equipment-as-a-service models. Qatar's Public Works Authority telemetry mandates require dashboard retraining investments.
- Government Agencies:Saudi sovereign wealth vehicles standardize crawler excavator specifications across Tabuk and Medina provinces.
- Developers:Master-planned community builders in Dubai specify compact equipment for phased infrastructure rollout.
- Construction Firms:Full-service builders maintain mixed fleets for vertical and horizontal construction sequences.
Equipment Rental Companies lead transaction volumes today; Government Agencies are expanding procurement fastest on giga-project scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled equipment operators and maintenance technicians concentrate along Saudi Arabia's western corridor, anchoring deployment capacity for giga-project earthmoving fleets. Technical labor pools in the UAE and Qatar support precision crane operations on high-rise vertical construction. Bahrain and Oman develop specialized niches in port logistics and compact urban equipment segments.
Saudi Arabia
NEOM and Red Sea giga-projects drive crawler excavator procurement volumes exceeding regional benchmarks. SASO enforces emissions certification and safety testing protocols that filter non-compliant machinery at Jeddah and Dammam ports. The Western Region corridor from Tabuk to Medina concentrates extended-reach earthmoving fleets for linear city foundation work.
United Arab Emirates
Federal construction contracts under Al Sa'fat green building mandates specify hybrid-powered equipment for downtown Dubai demolition sequences. MOHAP and federal environmental frameworks harden emissions thresholds for machinery eligibility on government tenders. Abu Dhabi's high-rise clusters and Dubai's urban infill zones anchor crane-intensive lifting operations.
Qatar
Public Works Authority telemetry mandates reshape contractor fleet management through real-time operator reporting requirements. The national infrastructure regulator enforces dashboard certification protocols that strain site supervisor technical capacity. Doha's compact urban cores deploy battery-powered compact equipment for restricted-access material handling.
Oman
Duqm port and logistics corridor investments generate first-mover positioning opportunities for specialized material handling fleets. The national standards body adopts Gulf Technical Regulation harmonization that simplifies cross-border equipment resale from UAE rental pools. Northern Batinah and Dhofar regions concentrate quarry extraction equipment for aggregate supply to coastal developments.
Bahrain
Regulatory harmonization with Gulf Technical Regulation standards reduces compliance fragmentation for equipment imported via Saudi Arabia. The national industrial development strategy prioritizes construction logistics efficiency across the King Fahd Causeway economic zone. Manama's urban densification projects sustain compact equipment rental demand for constrained site access.
GCC Construction Machinery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment categories and powertrain technologies. The vendor base organizes into three tiers: full-line manufacturers with integrated component operations, regional assemblers leveraging cost-optimized platforms, and niche specialists in compact or electrified segments. Strategic differentiation centers on dealer network density for parts availability, telematics integration depth, and emissions pre-certification for SASO and UAE federal compliance. Competitive moves concentrate on fleet standardization partnerships with giga-project developers and retrofit telematics packages for legacy diesel installations.
Among full-line heavy equipment manufacturers, Caterpillar Inc., Komatsu Ltd., and XCMG Construction Machinery Co. Ltd. represent distinct strategic archetypes. Caterpillar exemplifies the established distributor-network model with rapid parts availability infrastructure spanning remote Saudi project zones. Komatsu occupies a position emphasizing integrated telematics and predictive maintenance protocols for rental fleet operators. XCMG sits within the cost-optimized platform tier, leveraging Chinese manufacturing scale to compete on Saudi giga-project tender pricing. J.C. Bamford Excavators Ltd anchors the compact equipment specialization segment suited to urban infill constraints in Dubai and Doha. Hitachi Construction Machinery Co. Ltd. and SANY Heavy Industry Co. Ltd. exemplify regional market penetration strategies through localized assembly partnerships and emissions certification alignment with GCC import frameworks.
| Leading Market Players |
|---|
| XCMG Construction Machinery Co. Ltd. |
| Hitachi Construction Machinery Co. Ltd. |
| Caterpillar Inc. |
| J.C. Bamford Excavators Ltd (JCB) |
| SANY Heavy Industry Co. Ltd. |
| Komatsu Ltd. |
| AB Volvo (Volvo Construction Equipment) |
| Hyundai Construction Equipment Co. Ltd. |
| Liebherr International AG |
| Others |
Supply & Pricing Matrix
UAE's Al Sa'fat green building mandate and Saudi Arabia's SASO emissions certification are compressing procurement timelines and forcing distributors to pre-certify hybrid and Stage V-compliant inventory. Equipment suppliers must absorb upfront compliance costs or forfeit eligibility on federal and sovereign wealth contracts, tightening margin structures across the GCC.
Pricing Analysis
Bundled equipment-as-a-service contracts now command premium positioning against unbundled unit sales. Three-tier pricing structure across premium certified, standard compliant, and economy gray-market tiers separates fleet operators by contract eligibility. Price differentiation rests on telematics integration depth and SASO pre-certification status. Cost compression in economy tiers is intensifying because gray-market suppliers face port detention risks that strand capital. Mid-tier contractors with balance sheet constraints exhibit highest price sensitivity; giga-project developers with sovereign backing show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German hydraulic component suppliers for systems operating above 300 bar. Manufacturing concentration in China, South Korea, and Germany feeds GCC import channels with finished machines and critical subassemblies. Steel castings, high-pressure hydraulic pumps, and emissions after-treatment modules anchor raw material dependencies. Tariff exposure on Chinese-origin equipment creates compliance cost layering at Saudi and UAE ports. Distribution runs through authorized dealer networks with parts depots concentrated within 200 kilometers of Riyadh and Dubai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC construction machinery market functions as a stable compounder anchored by decade-long sovereign wealth deployment into linear infrastructure. Giga-project pipelines across Saudi Arabia's western corridor generate predictable equipment replacement cycles.
For Market Incumbents:Anchored fleet standardization partnerships with NEOM and Red Sea developers lock out substitute technologies. Incumbents should deepen backward integration into telematics platforms to capture recurring revenue independent of unit sales. Gray-market encroachment on economy tiers threatens margin compression; SASO certification investment creates regulatory moats.
For New Entrants and Emerging Players:Bahrain's Gulf Technical Regulation harmonization opens a window for cross-border resale arbitrage from UAE rental pools. Duqm port investments in Oman present first-mover positioning for compact equipment specialists. Retrofit telematics packages for legacy diesel fleets offer the most penetrable aftermarket entry point. Go-to-market execution should target rental fleet operators with integrated maintenance guarantees.
For Investors and Strategic Acquirers:Asymmetric upside sits with telematics-integrated rental platforms serving urban infill uncertainty in Doha and Dubai. Long-term viability favors asset-light service models over capital-intensive fleet ownership. Acquisition targets should demonstrate operator training infrastructure and dashboard certification capabilities aligned with Qatar's Public Works Authority mandates. Watch for SASO enforcement intensity at Jeddah and Dammam ports as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Standardization Partnership | Locks multi-year procurement commitments from NEOM and Red Sea giga-project developers. |
| Telematics Platform Integration | Enables predictive maintenance revenue streams for rental fleet operators across Doha. |
| SASO Pre-Certification Investment | Eliminates port detention risk and accelerates site mobilization for Saudi western corridor projects. |
| Retrofit Sensor Installation | Captures recurring aftermarket revenue from legacy diesel fleets without new unit sales. |
| Compact Equipment Specialization | Addresses constrained site access in Manama and Dubai urban densification zones. |
Research Methodology
Coverage spans Saudi Arabia, UAE, Qatar, Oman, and Bahrain, with primary inputs from each market. The analysis combines structured interviews with fleet operations directors, rental company procurement heads, OEM regional managers, and aftermarket service specialists with secondary validation. Trade customs data, SASO certification registries, MOHAP federal contract disclosures, and equipment import manifests anchor quantitative baselines. Bottom-up equipment unit economics and top-down sovereign wealth deployment tracking triangulate market sizing.
Segmentation granularity extends to product type, powertrain technology, application vertical, and end-user archetype across the projection horizon. The analytical framework models Infrastructure Development, Residential Construction, Commercial Projects, Oil and Gas Facilities, and Mining Operations as distinct demand pools. CAGRs derive from equipment replacement cycle compression on giga-project sites and rental pooling adoption curves. Forecast inputs include steel price volatility indices and hydraulic component lead time fluctuations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory enforcement intensity shifts or sovereign wealth reallocation. Forecasts reflect documented assumptions about SASO certification throughput and Al Sa'fat mandate expansion timelines. Commodity price spikes, port congestion events, or operator telemetry mandate delays in additional GCC states could revise equipment procurement trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Earthmover Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Fully Automatic Metal Band Saw Machine Market
Construction Equipment
Drilling Machine Market
Construction Equipment
Hand Push Trencher Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Global Welding Market
Construction Equipment
Snow Removal Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Welding and Cutting Equipment Market
Construction Equipment
Backhoes Market
Construction Equipment
Thermal Spray Equipment Market