
 Xenon Gas Market | 2026-2036
Xenon Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Xenon Gas Market Intelligence
Russia is reconfiguring its role in xenon supply chains amid export redirection dynamics. Air Liquide leverages cryogenic separation expertise to sustain high-purity output for semiconductor clients. Linde Gas & Equipment Inc. anchors North American distribution through integrated bulk supply networks. Chengdu Taiyu Industrial Gases Co., Ltd competes on regional cost structures within Asia-Pacific markets.
Xenon gas is a noble gas with atomic number 54, occurring in trace amounts in Earth's atmosphere at roughly 0.087 parts per million, and is extracted through cryogenic distillation of liquid air followed by purification via adsorption and catalytic processes. Its primary industrial purpose centers on high-performance applications requiring extreme chemical inertness, including excimer laser mixtures for semiconductor photolithography and ion propulsion systems for spacecraft propulsion. Medical Grade product commands premium positioning due to stringent purity requirements for anesthesia and neuroprotective applications in healthcare settings. Electronic Grade supply is experiencing the fastest structural expansion as advanced node semiconductor manufacturing intensifies demand for excimer laser gas mixtures. Lighting applications represent a mature consumption segment with stable but decelerating volume trajectories.
The EPA regulates xenon discharge and reporting under Clean Air Act frameworks, while the EU F-Gas Regulation imposes phasedown quotas on fluorinated and noble gas imports that reshape procurement geography. China's SAMR enforces GB standards for industrial gas purity classifications that determine market access for foreign suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate supply allocation shifts and certification compliance burdens.
Market Dynamics
The xenon gas market is restructuring around supply chain fragmentation triggered by the EU F-Gas Regulation's phasedown quotas, which have forced semiconductor manufacturers to diversify sourcing away from traditional European suppliers toward non-EU cryogenic separation facilities.
Growth Catalysts
- Semiconductor node advancement:Excimer laser gas mixtures for sub-7nm lithography require ultra-high-purity xenon, pulling volume into Electronic Grade specifications as Taiwan Semiconductor Manufacturing Company and Samsung Foundry expand advanced fabrication capacity.
- EU F-Gas Regulation:Phasedown mandates on fluorinated and noble gas imports are redirecting procurement spend toward Russian and Chinese cryogenic separation plants, creating new supply corridor economics.
- Space propulsion commercialization:Ion thruster adoption by satellite constellation operators such as SpaceX's Starlink and Amazon's Kuiper is establishing xenon as a strategic propellant for orbital station-keeping and de-orbit maneuvers.
Market Restraints
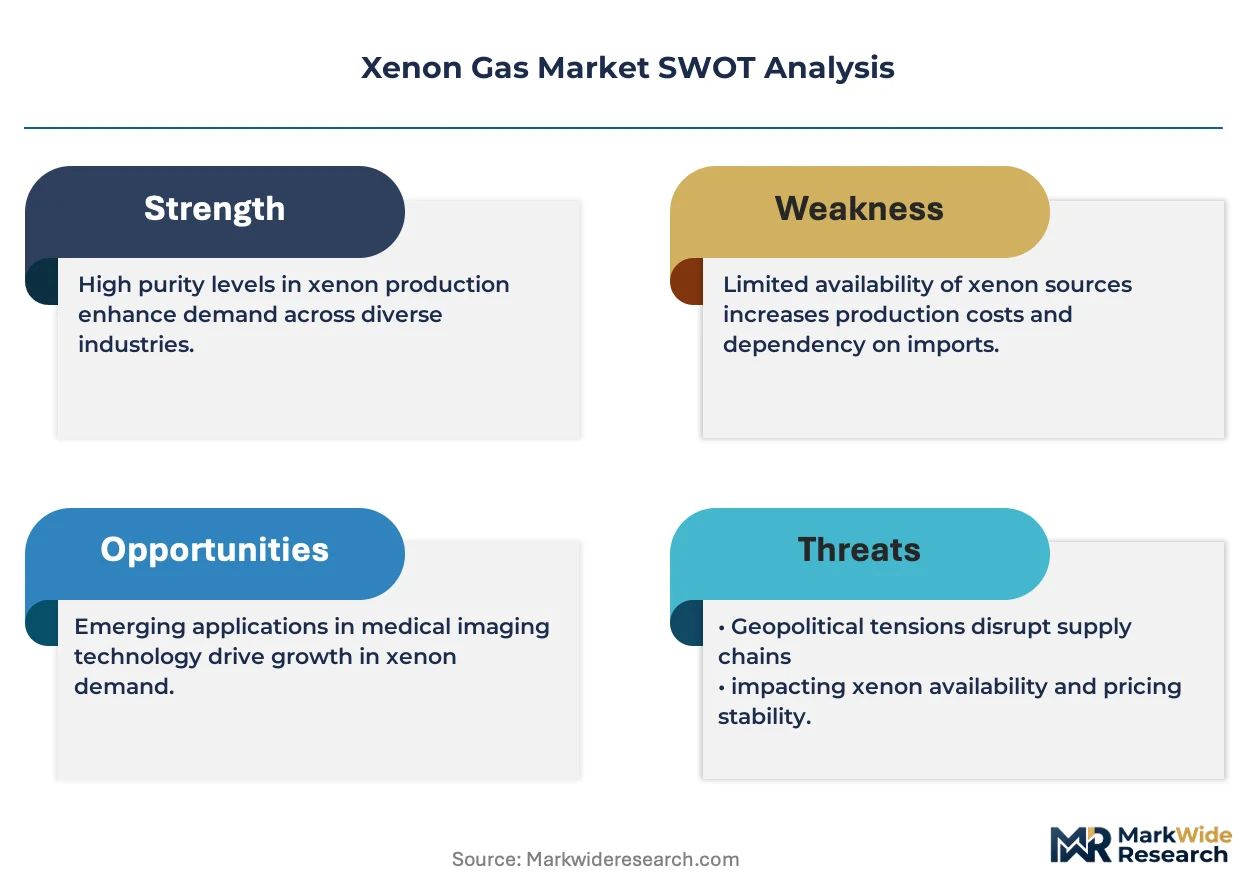
- Atmospheric concentration limits:Xenon occurs at 0.087 parts per million in ambient air, constraining raw material availability regardless of cryogenic distillation capacity expansion.
- Energy input cost volatility:Liquid air separation requires substantial electricity throughput, exposing production economics to regional power price fluctuations in Germany and Japan.
- Russian supply concentration:Cryogenic facilities in Siberia and the Urals account for disproportionate global output, creating geopolitical risk exposure for buyers dependent on uninterrupted pipeline flows.
Strategic Opportunities
- India semiconductor manufacturing:The country's PLI scheme for electronics fabrication is attracting foundry investment that will require localized noble gas supply chains, creating first-mover positioning for cryogenic operators.
- Neuroprotective anesthesia protocols:Medical Grade xenon for cardiopulmonary bypass and traumatic brain injury management is gaining clinical traction in Japanese and German hospital systems as an alternative to volatile anesthetics.
- Closed-loop recycling systems:Semiconductor fabs in Hsinchu and Pyeongtaek are piloting on-site xenon recovery from excimer laser exhaust streams, reducing virgin gas dependency and creating service-contract revenue pools.
Industry Challenges
- Cryogenic engineering talent scarcity:Qualified technicians for air separation unit operation and high-purity gas handling are concentrated at legacy Linde and Air Liquide training centers, limiting new entrant scale-up velocity.
- Multi-jurisdiction certification timelines:Medical Grade xenon requires simultaneous FDA 510(k) clearance, EMA marketing authorization, and NMPA registration in China, stretching product launch cycles across divergent purity documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xenon Gas Market |
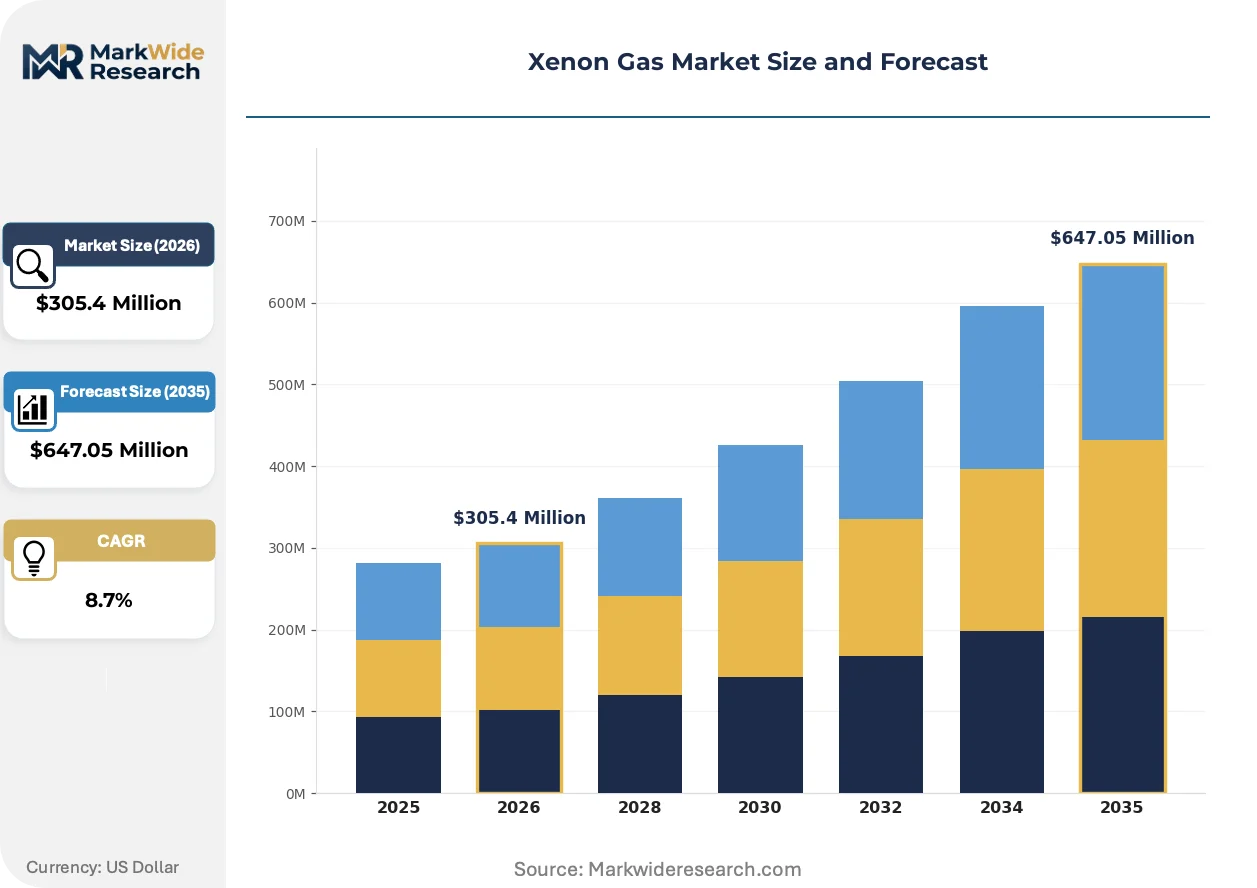
| Market Size in 2026 | $305.4 Million |
| Market Size in 2035 | $647.05 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Medical Grade, Scientific Grade, Electronic Grade Application: Lighting, Nuclear Energy, Space Exploration, Medical Imaging End User: Aerospace, Healthcare, Research Institutions, Electronics Delivery Mode: Cylinders, Bulk Supply, On-Site Generation, Liquid Delivery |
| Companies Covered | American Gas Products, Chengdu Taiyu Industrial Gases Co., Ltd, AEROGAS, Air Liquide, SUMITOMO SEIKA CHEMICALS CO.,LTD., American Welding & Gas, INGAS, Messer Group, Linde Gas & Equipment Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xenon Gas Market Strategic Shifts & Innovations
Technical and regulatory forces are compressing product lifecycles while expanding purity thresholds. Three distinct vectors are reconfiguring how xenon is produced, certified, and consumed across end-use verticals.
Excimer laser gas mixtures are migrating from xenon-argon-halogen blends toward optimized xenon-fluoride formulations as semiconductor lithography pushes toward high-numerical-aperture EUV transition nodes. ASML and Nikon Precision Equipment are qualifying these mixtures for 3nm and 2nm production ramps. The shift is compressing specification tolerance windows from parts-per-million to parts-per-billion impurity thresholds, forcing cryogenic separation plants to retool adsorption and catalytic purification trains.
China's SAMR enforcement of revised GB/T 4842 purity standards for electronic gases is tightening market access for foreign suppliers while accelerating domestic cryogenic capacity investment. The standards mandate stricter control of krypton and nitrogen contaminants that degrade excimer laser performance. Korean and Japanese semiconductor material distributors are responding by establishing localized blending and certification facilities in Suzhou and Wuxi to maintain qualification status.
Long-term purchase agreements with take-or-pay clauses are displacing spot market transactions as the dominant procurement mechanism for semiconductor-grade xenon. Foundry operators in Taichung and Gyeonggi-do are consolidating supplier panels to three qualified sources per geography, extracting volume commitments in exchange for technical collaboration on next-generation purity specifications. The concentration is most visible in Taiwan, where TSMC's supplier scorecard system now weights supply security metrics above unit pricing in annual contract negotiations.
Xenon Gas Market Segmentation
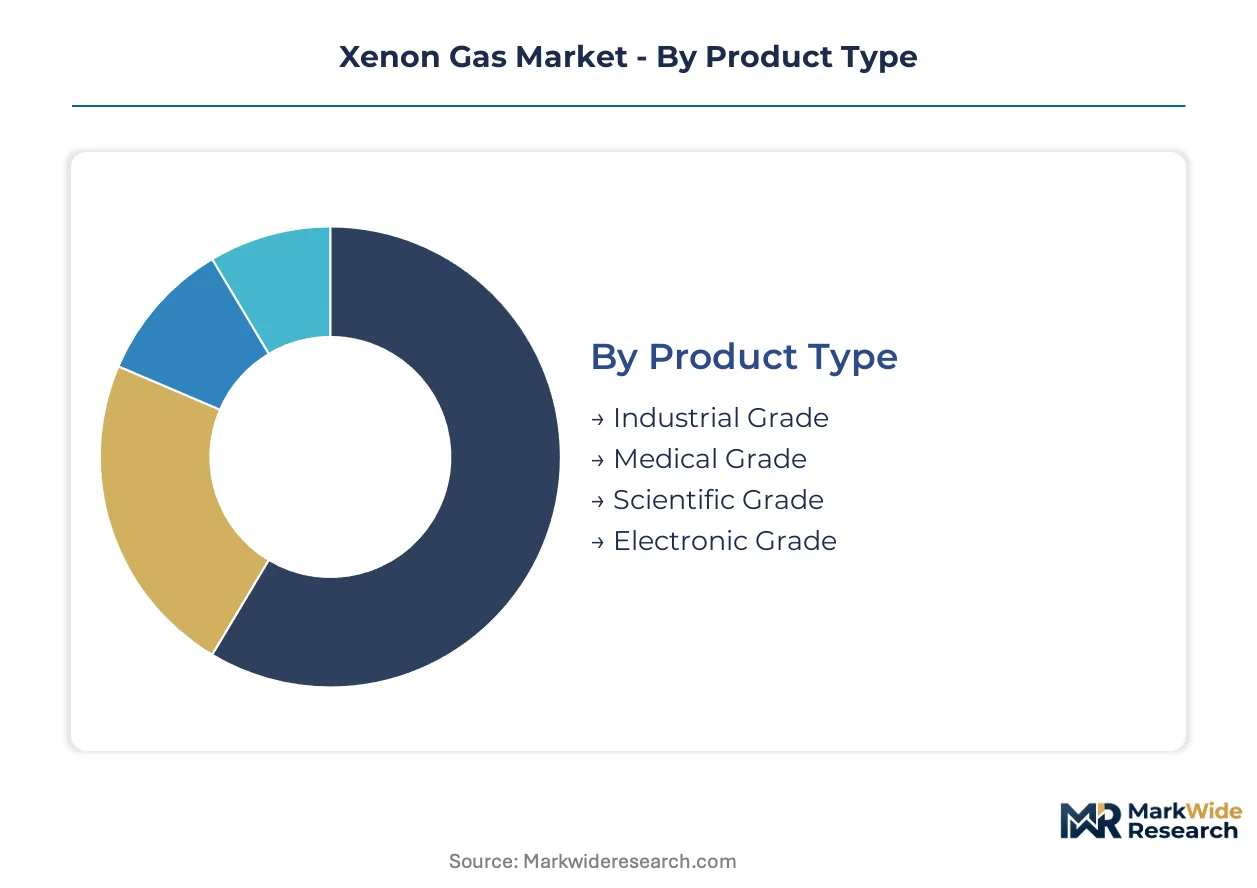
Xenon gas specifications diverge sharply across end-use verticals, with purity thresholds ranging from parts-per-million for industrial applications to parts-per-billion for semiconductor lithography. Segmentation by product grade and delivery mechanism determines pricing architecture, regulatory compliance burden, and supplier qualification pathways for procurement teams.
Product Type:
Application-specific purity requirements stratify the market into four distinct certification tiers, each commanding different margin structures and technical documentation standards.
- Electronic Grade:Ultra-high-purity xenon meeting sub-parts-per-billion contamination limits for excimer laser gas mixtures in semiconductor photolithography. Demand concentrates in Hsinchu and Gyeonggi-do as TSMC and Samsung Foundry expand advanced node capacity, pulled by EUV transition requirements for 3nm and 2nm production ramps.
- Medical Grade:Pharmacopeia-compliant xenon for anesthesia and neuroprotective applications requiring FDA 510(k) clearance and EMA marketing authorization. German and Japanese hospital systems are adopting protocols for cardiopulmonary bypass and traumatic brain injury management, creating premium positioning against volatile anesthetics.
- Industrial Grade:Standard purity xenon for general industrial processes and lighting applications with established GB/T 4842 certification pathways through China's SAMR.
- Scientific Grade:Research-calibrated xenon for laboratory instrumentation and experimental physics with documented traceability chains.
Electronic Grade commands the established base. The steepest expansion runs through Medical Grade as neuroprotective protocols gain clinical traction.
Application:
End-use demand patterns reflect maturity gradients across technology sectors, with emerging applications reshaping volume allocation.
- Space Exploration:Ion propulsion systems utilizing xenon as propellant for orbital station-keeping and de-orbit maneuvers. SpaceX's Starlink and Amazon's Kuiper satellite constellations are establishing long-term offtake agreements, with procurement concentrating at facilities qualified for aerospace-grade handling.
- Medical Imaging:Xenon-enhanced CT and MRI contrast protocols requiring sterile handling infrastructure. Japanese diagnostic equipment manufacturers are qualifying domestic suppliers under PMDA pharmaceutical gas standards.
- Lighting:High-intensity discharge lamps and specialized illumination systems with decelerating volume trajectories as LED substitution advances.
- Nuclear Energy:Detector calibration and research reactor applications with stable but limited procurement volumes.
Lighting retains the volume base. Space Exploration is climbing the fastest as commercial constellation deployment accelerates.
End User:
Customer archetypes determine contract structures, with foundry operators consolidating supplier panels while research institutions maintain fragmented procurement.
- Electronics:Semiconductor fabs in Taichung and Pyeongtaek piloting closed-loop recycling systems to reduce virgin gas dependency, extracting technical collaboration commitments through take-or-pay agreements.
- Aerospace:Satellite manufacturers and launch service providers requiring propellant-grade certification with extended supply security clauses.
- Healthcare:Hospital systems and anesthesia equipment suppliers navigating multi-jurisdiction registration timelines.
- Research Institutions:Universities and national laboratories with spot-market purchasing patterns and lower volume thresholds.
Electronics anchors procurement volume. Aerospace is gaining share fastest as ion thruster adoption commercializes.
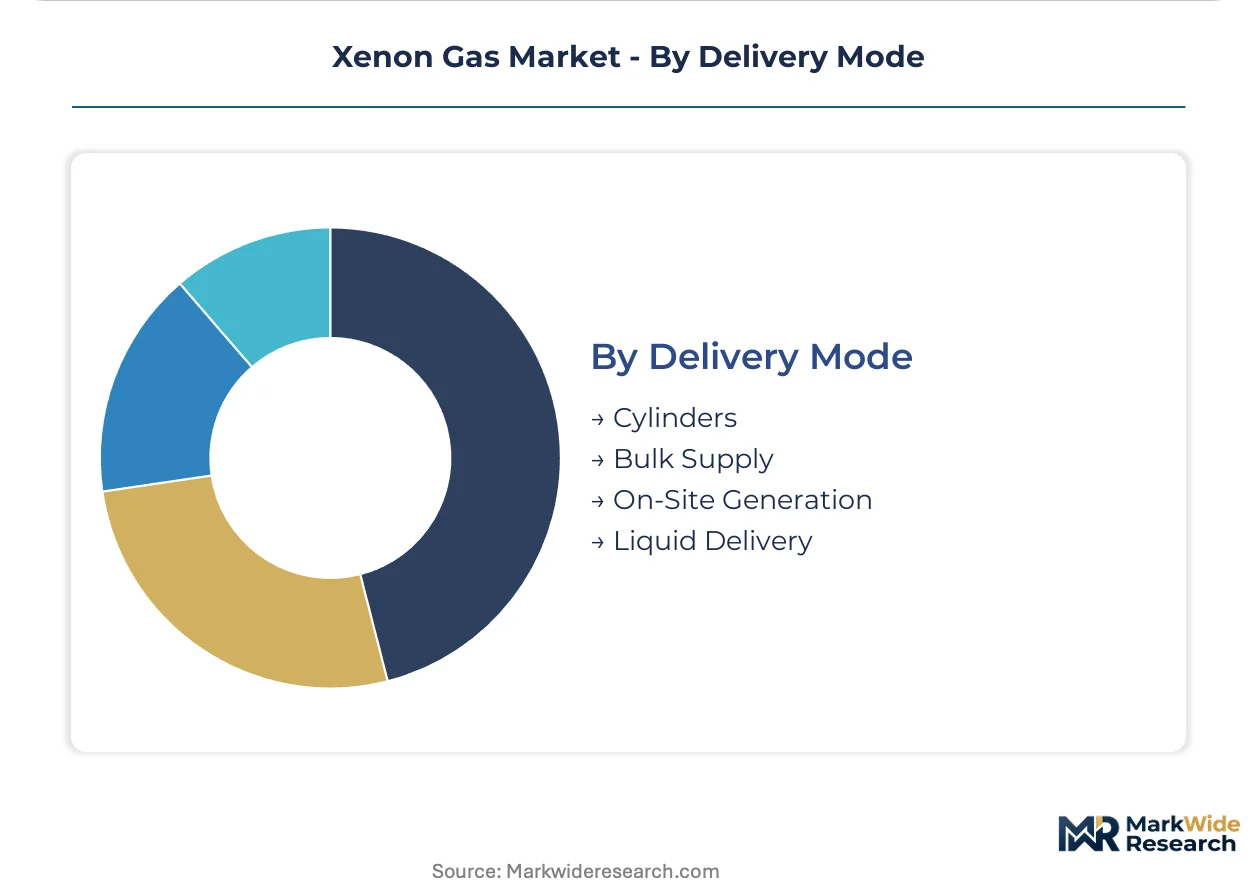
Delivery Mode:
Logistics configuration directly shapes working capital requirements and supply security profiles for buyers across end-use segments.
- Bulk Supply:Cryogenic tanker deliveries integrated with on-site storage infrastructure for high-volume semiconductor fabs. Air Liquide and Linde Gas & Equipment Inc. anchor North American and European distribution through pipeline-connected separation plants.
- On-Site Generation:Dedicated air separation units co-located with foundry complexes in Taiwan and South Korea, eliminating transportation contamination risks for Electronic Grade specifications.
- Cylinders:Standard compressed gas packaging for Medical and Scientific Grade applications with established pharmacopeia documentation.
- Liquid Delivery:Dewar-based distribution for intermediate volume requirements in aerospace manufacturing and research settings.
Bulk Supply commands the established base. On-Site Generation is expanding most quickly as foundry operators prioritize supply security metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cryogenic separation facilities in Siberia and the Urals generate disproportionate global xenon output, forcing procurement teams to navigate geopolitical risk exposure while diversifying toward Chinese and North American air separation plants.
China
Domestic semiconductor fabrication capacity expansion in Hsinchu and Shanghai is pulling Electronic Grade xenon volumes toward advanced node production. SAMR enforcement of revised GB/T 4842 purity standards tightens market access for foreign suppliers while accelerating domestic cryogenic investment. Foundry complexes in Suzhou and Wuxi are localizing blending and certification facilities to maintain qualification status.
United States
TSMC's Arizona fab and Intel's Ohio expansion are establishing new demand anchors for high-purity noble gas supply chains. EPA regulation of xenon discharge under Clean Air Act frameworks shapes environmental compliance burdens for air separation operators. Bulk supply networks in the Gulf Coast corridor integrate with semiconductor manufacturing clusters emerging in Texas and Arizona.
Germany
Medical Grade xenon adoption for neuroprotective anesthesia protocols is gaining clinical traction in hospital systems across Bavaria and North Rhine-Westphalia. The EU F-Gas Regulation's phasedown quotas on noble gas imports are redirecting procurement spend toward non-EU cryogenic facilities. Industrial gas infrastructure in the Ruhr Valley maintains legacy separation capacity serving diversified end-use segments.
South Korea
Samsung Foundry and SK Hynix are expanding advanced node capacity in Pyeongtaek and Yongin, intensifying demand for sub-parts-per-billion purity specifications. Korean semiconductor material distributors are establishing localized blending operations to satisfy SAMR-equivalent certification requirements for China-bound exports. Closed-loop recycling pilots in Gyeonggi-do are reducing virgin gas dependency.
Japan
Xenon-enhanced CT and MRI contrast protocols are driving Medical Grade qualification under PMDA pharmaceutical gas standards. METI industrial policy supports domestic cryogenic capacity retention for strategic material security. Diagnostic equipment manufacturers in Tokyo and Osaka are qualifying localized suppliers against stringent contamination thresholds.
Xenon Gas Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in cryogenic separation and purification. The vendor base clusters around three strategic archetypes: diversified industrial gas conglomerates with integrated air separation networks, regional specialists competing on cost structures within defined geographies, and aerospace-focused operators securing propellant-grade certification. Dominant competitive moves include backward integration into captive cryogenic capacity and geographic expansion through localized blending facilities.
Among diversified industrial gas conglomerates, Air Liquide and Linde Gas & Equipment Inc. exemplify platform-scale positioning through pipeline-connected separation plants and bulk distribution infrastructure. Chengdu Taiyu Industrial Gases Co., Ltd. occupies a position within the regional specialist tier, leveraging proximity to Asia-Pacific semiconductor manufacturing clusters. These three entities represent distinct competitive archetypes: the integrated multinational, the Americas-anchored distributor, and the China-based cost competitor.
| Leading Market Players |
|---|
| American Gas Products |
| Chengdu Taiyu Industrial Gases Co., Ltd |
| AEROGAS |
| Air Liquide |
| SUMITOMO SEIKA CHEMICALS CO.,LTD. |
| American Welding & Gas |
| INGAS |
| Messer Group |
| Linde Gas & Equipment Inc. |
| Others |
Cost & Logistics Intelligence
Siberian cryogenic separation clusters in the Urals and Krasnoyarsk Krai anchor global xenon extraction capacity, concentrating pricing power among operators with pipeline-connected liquefaction trains. Downward price pressure on Electronic Grade specifications intensifies as semiconductor fabs in Taichung and Pyeongtaek consolidate supplier panels and extract volume commitments through take-or-pay structures.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure through phasedown quotas that compress margins on European-sourced volumes while elevating premiums for non-EU certification. Three-tier pricing stratifies across Electronic Grade, Medical Grade, and Industrial Grade levels, with purity thresholds and regulatory documentation burden as primary differentiation drivers. Cost compression in Electronic Grade specifications runs through energy input volatility at air separation plants, while Medical Grade buyers exhibit lowest price sensitivity due to pharmacopeia compliance requirements and limited qualified supplier pools.
Supply Chain Analysis
Export control regimes on cryogenic separation technology limit capacity expansion outside legacy industrial gas conglomerates, tethering supply growth to Russian, Chinese, and North American production footprints. Raw material extraction draws from atmospheric air distillation, with energy throughput and adsorption medium availability as critical input dependencies. Single-source vulnerability concentrates in Siberian pipeline flows, while distribution runs through bulk cryogenic tanker networks integrated with on-site storage infrastructure at semiconductor manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified technicians for air separation unit operation represent the binding constraint on capacity expansion, with training pipelines concentrated at legacy industrial gas facilities creating a multi-year skill gap for new entrants.
For Market Incumbents: Entrench supply security relationships with foundry operators through dedicated on-site generation investments in Taiwan and South Korea, while accelerating backward integration into captive cryogenic capacity to offset Russian supply concentration risk. Prioritize certification investment for SAMR GB/T 4842 compliance to defend qualification status as China's domestic semiconductor ecosystem matures. For New Entrants and Emerging Players: Establish a beachhead in Medical Grade xenon for neuroprotective anesthesia protocols, where pharmacopeia documentation requirements create defensible moats against commodity competition. Target German and Japanese hospital systems with sterile handling infrastructure partnerships, leveraging localized blending facilities as the go-to-market angle to bypass bulk supply network disadvantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aerospace-grade xenon operators with propellant certification and long-term offtake visibility from satellite constellation deployment. The five-to-ten year viability window rewards acquisition of cryogenic specialists with established EPA environmental compliance and FAA aerospace handling credentials. Watch ion thruster adoption rates across commercial constellation operators as the inflection signal for demand acceleration beyond semiconductor cyclicality.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cryogenic Capacity | Captive air separation units in Taiwan and South Korea secure supply security metrics for TSMC and Samsung Foundry procurement scorecards. |
| Long-term Supply Agreement | Take-or-pay structures with take-or-pay clauses displace spot transactions as dominant procurement mechanism for Electronic Grade specifications. |
| Joint Venture | Localized blending facilities in Suzhou and Wuxi enable Korean and Japanese distributors to maintain SAMR qualification status for China-bound exports. |
| Capacity Expansion | On-site generation investments at Arizona and Ohio semiconductor fabs establish North American supply anchors independent of Siberian pipeline flows. |
| Green Manufacturing Transition | Closed-loop recycling pilots in Hsinchu and Pyeongtaek reduce virgin gas dependency while creating service-contract revenue pools for cryogenic operators. |
Research Approach
Desk research of customs trade databases, EPA environmental filings, and SAMR regulatory bulletins preceded structured interviews with air separation plant managers, semiconductor procurement leads at foundry operators, and cryogenic engineering specialists. Primary fieldwork with industrial gas distribution channel partners and secondary validation against SEC 10-K disclosures from diversified gas conglomerates enabled bottom-up and top-down triangulation of production capacity and demand allocation.
Assumptions around EU F-Gas Regulation phasedown trajectories, semiconductor node migration timelines, and ion propulsion commercialization curves were held fixed across modeling scenarios while regional energy price volatility and geopolitical risk exposure were varied. Segmentation dimensions included product grade tier, end-use application, delivery mode configuration, and regional regulatory cluster. CAGRs were derived from production capacity buildout schedules and foundry capital expenditure pipelines across the projection horizon, with excimer laser gas mixture specifications and satellite constellation deployment rates as industry-specific demand inputs.
Stress conditions across Siberian supply disruption scenarios, EU quota acceleration timelines, and Chinese domestic capacity substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on cryogenic separation technology diffusion and regulatory enforcement intensity. Material shifts in export control regimes on air separation equipment or breakthroughs in alternative propellant ion thruster chemistry would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
South-East Asia (SEA) Syngas Market
Industrial Gases
Helium Market
Industrial Gases
Europe Syngas Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
Transcritical CO2 Market
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
Gas Sampling Line Market
Industrial Gases
Syngas Market
Industrial Gases
Global Rare Gases Market
Industrial Gases
Food-Grade Gases Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Oxygen Market